
 Native Whey Protein Ingredients Market | 2026-2036
Native Whey Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Native Whey Protein Ingredients Market Foresight
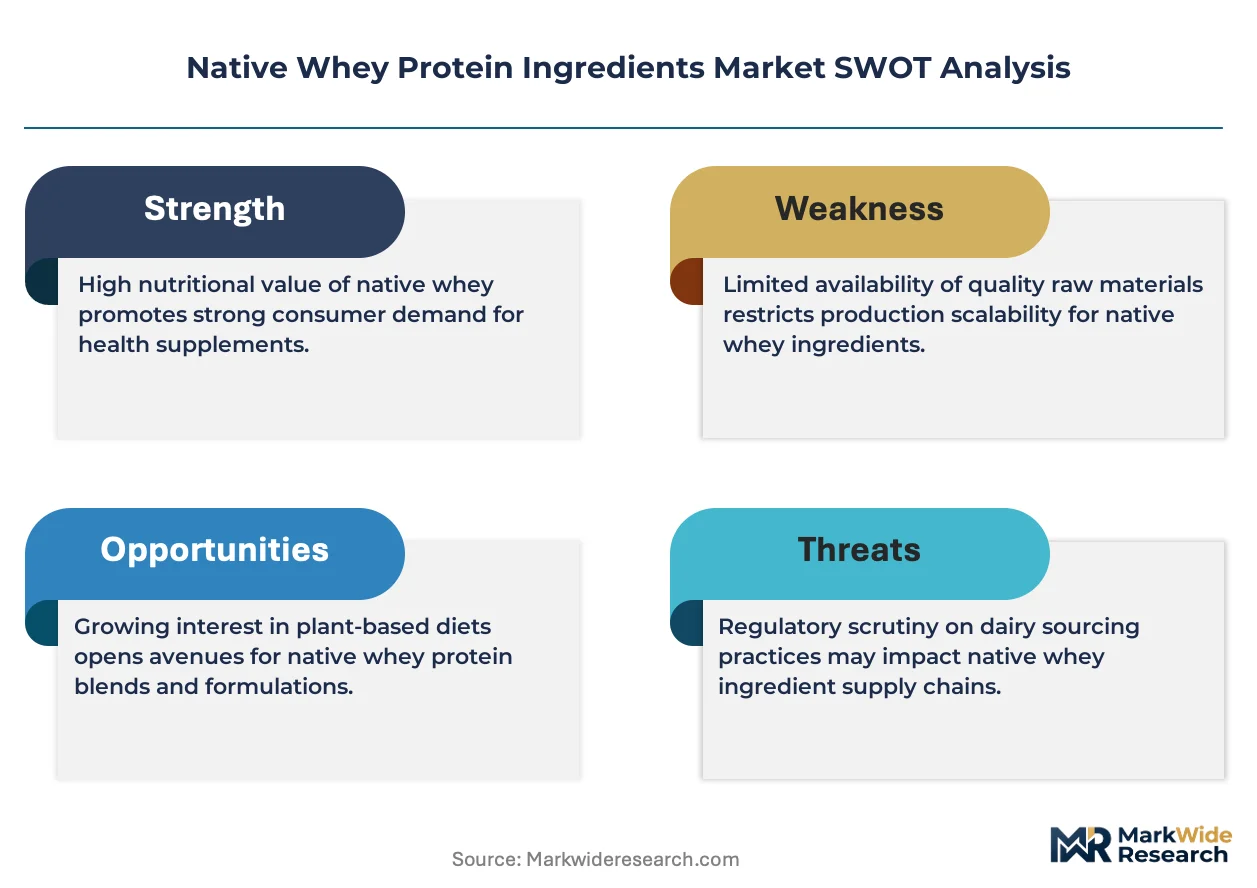
Grass-fed and cold-processed specification tiers is unwinding commoditization pressures across the native whey protein landscape. Glanbia Nutritionals leverages its Irish dairy supply base to secure premium raw milk streams for isolate production. Arla Foods Ingredients anchors its competitive position through backward integration into Scandinavian cooperative farming networks. Ingredia SA differentiates via specialized ceramic microfiltration capabilities that preserve native protein structures.
Native whey protein ingredients comprise undernatured protein fractions extracted directly from milk through low-temperature membrane filtration, retaining higher levels of cysteine, leucine, and immunoglobulins than cheese-derived alternatives. The isolate segment commands the deepest margin pools due to its protein concentration exceeding 90% and superior solubility profiles for sports nutrition applications. Hydrolysate variants represent the fastest-growing structural category as pre-digested proteins gain traction among medical nutrition and senior health formulations. Bakery applications remain comparatively mature, with concentrate grades dominating cost-sensitive industrial procurement.
The FDA enforces allergen labeling and GRAS notification requirements that shape formulation decisions for US-bound native whey products. EFSA's health claims framework in Europe constrains marketing language around muscle protein synthesis, forcing evidence-based positioning. Health Canada's PMRA and CFIA jointly oversee dairy ingredient safety standards that govern cross-border trade flows. Stakeholders must monitor evolving precision fermentation regulations that could redefine competitive boundaries between animal-derived and biosimilar protein sources.
Market Dynamics
The native whey protein ingredients market is restructuring around cold-processing capabilities that preserve bioactive fractions, with membrane filtration investments determining competitive tier positioning among ingredient suppliers.
Growth Catalysts
- EFSA health claims framework:Evidence-based muscle protein synthesis positioning creates premium pricing power for isolate grades in European sports nutrition formulations.
- Medical nutrition expansion:Pre-digested hydrolysate variants penetrate senior health and clinical recovery applications, opening higher-margin therapeutic channels.
- Germany production clustering:MILEI GmbH and FrieslandCampina Ingredients anchor supply concentration serving pan-European functional food formulators.
Market Restraints
- Raw milk cost volatility:Irish and Scandinavian dairy cooperative pricing directly compresses margin pools for isolate producers dependent on grass-fed supply streams.
- Single-source membrane technology:Ceramic microfiltration equipment concentrates among limited European vendors, creating equipment procurement bottlenecks.
- Precision fermentation substitution:Biosimilar whey proteins from microbial sources threaten to displace animal-derived native fractions in cost-sensitive bakery applications.
Strategic Opportunities
- Underpenetrated US clinical nutrition:FDA GRAS notification pathways enable hydrolysate expansion into post-surgical recovery and malabsorption formulations.
- Clean label bakery reformulation:Concentrate grades replace modified dairy proteins in European industrial procurement as EFSA transparency requirements tighten.
- Direct-to-consumer powder channels:Subscription models for minimally processed protein sources bypass traditional sports nutrition brand intermediation.
Industry Challenges
- Membrane operator skill scarcity:Low-temperature filtration expertise concentrates among veteran technicians at Ingredia SA and Arla Foods Ingredients, constraining capacity expansion.
- Dual certification timelines:simultaneous FDA GRAS and Health Canada PMRA approvals delay cross-border product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Native Whey Protein Ingredients Market |
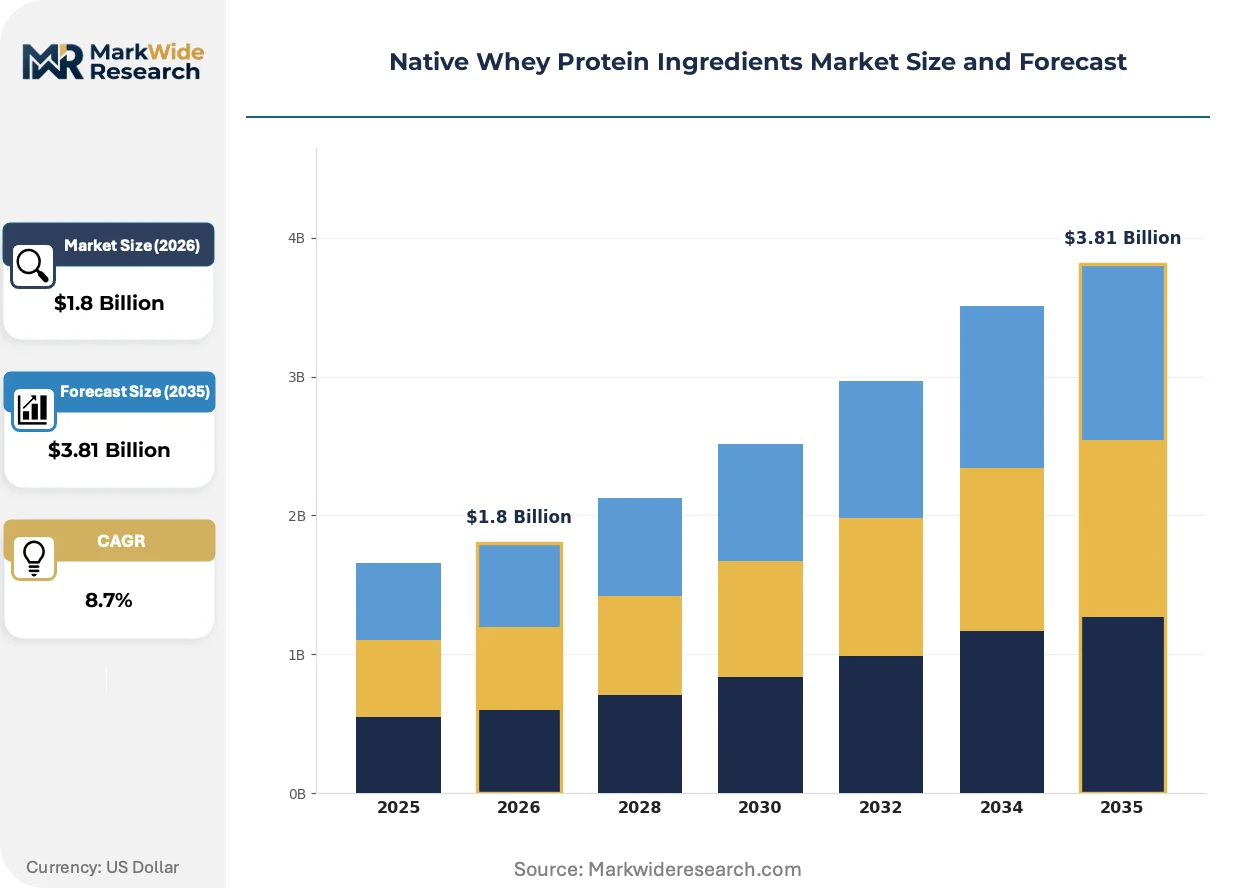
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Hydrolysate, Blends Application: Sports Nutrition, Dietary Supplements, Bakery Products, Dairy End User: Athletes, Fitness Enthusiasts, Health-Conscious Consumers, Medical Patients Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | Lactalis Ingredients, Ingredia SA, Glanbia Nutritionals, Arla Foods Ingredients, Fonterra Co-operative Group, MILEI GmbH, Hilmar Cheese Company, Agropur Dairy Cooperative, FrieslandCampina Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Native Whey Protein Ingredients Market Shifts & Advancements
Cold-processing technology is fragmenting competitive tiers while regulatory transparency mandates and direct procurement behaviors reshape channel economics across the native whey value chain.
Ceramic microfiltration is bifurcating the supplier base between premium isolate producers and commodity concentrate processors. Sports nutrition brands with technical procurement teams now specify membrane pore size and temperature curves in supplier contracts. This capability stratification is compressing margin pools for heat-processed cheese-derived alternatives while rewarding backward-integrated dairy cooperatives with captive cold-chain infrastructure.
EFSA's updated transparency requirements on health claim substantiation are forcing reformulation documentation at the ingredient level. Manufacturers must now disclose protein denaturation thresholds and bioactive fraction retention rates in regulatory submissions. Medical nutrition formulators in Germany and the Netherlands are responding by consolidating supplier relationships around certified low-temperature processors with established dossier libraries.
Ingredient buyers are consolidating procurement decisions away from distributors toward direct technical partnerships with membrane filtration operators. Large sports nutrition brands now embed quality auditors at supplier facilities in Ireland and Denmark. This disintermediation is most visible in North American markets where FDA supply chain verification requirements have compressed traditional three-tier distribution into bilateral manufacturer-formulator relationships.
Native Whey Protein Ingredients Market Segmentation
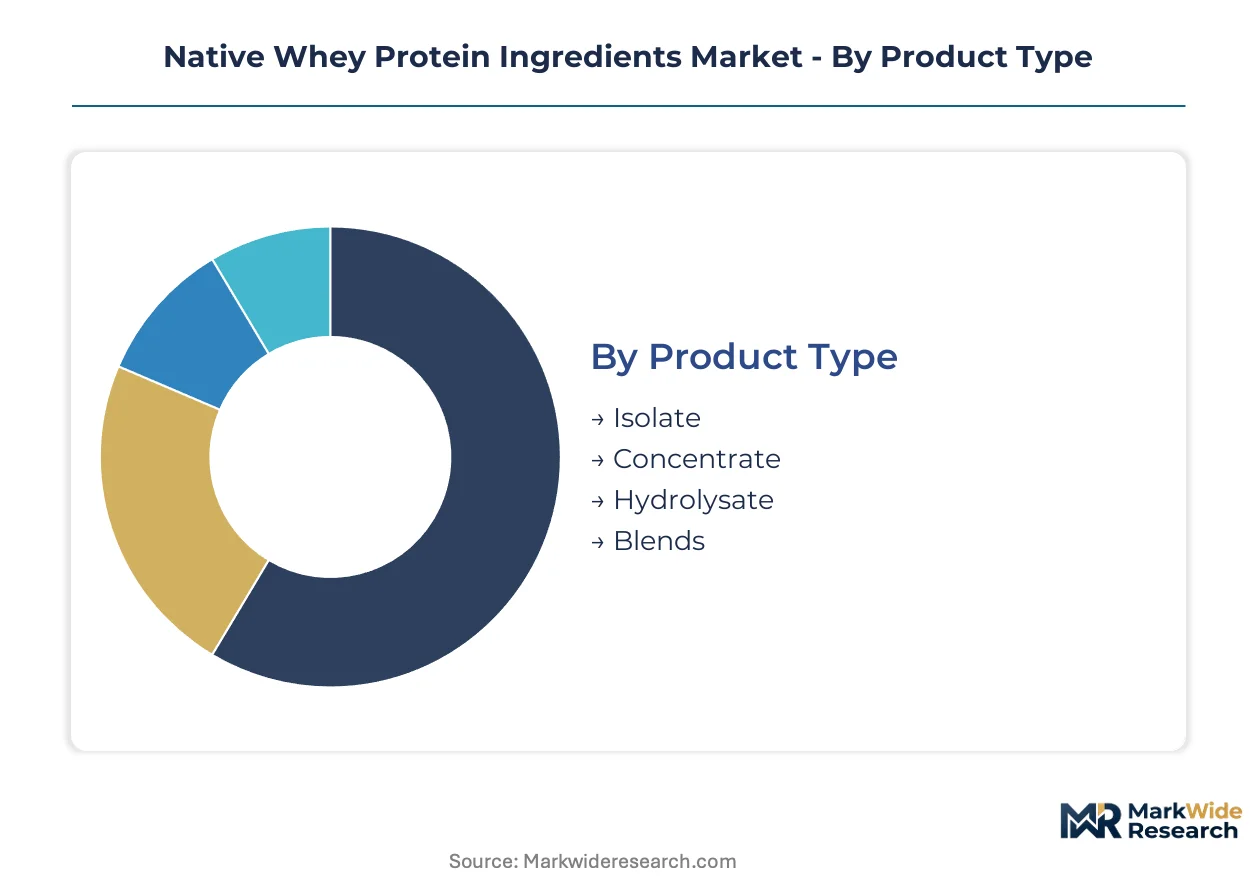
Native whey protein ingredients fragment across four structural dimensions that determine substitution vulnerability and margin architecture. Product type stratification separates premium cold-processed isolates from commodity heat-treated concentrates, while application mix shifts toward medical and sports nutrition channels resistant to precision fermentation displacement.
Product Type:
Substitution pressure from biosimilar proteins concentrates most intensely on lower-specification grades where functional differentiation collapses.
- Isolate:Protein concentration exceeds 90% with superior solubility profiles achieved through ceramic microfiltration at sub-10°C temperatures. Demand concentrates in German and Irish sports nutrition formulators seeking EFSA-substantiated muscle protein synthesis claims for premium powder lines.
- Hydrolysate:Pre-digested peptide fractions manufactured through controlled enzymatic hydrolysis reduce allergenic potential and accelerate gastric emptying. Medical nutrition manufacturers in the Netherlands and senior health formulators drive procurement expansion for post-surgical recovery applications.
- Concentrate:70-80% protein content retains more lactose and lipid fractions; cost-sensitive European industrial bakery procurement dominates volume.
- Blends:Custom ratio formulations combining isolate, concentrate, and hydrolysate fractions; private-label sports nutrition brands specify these for differentiated positioning.
Concentrate retains volume leadership; hydrolysate holds the steepest expansion curve.
Application:
Cost tier stratification determines which applications absorb premium native whey specifications versus commodity alternatives.
- Sports Nutrition:Powder, bar, and ready-to-drink formulations command the deepest margin pools as brands specify membrane pore size and temperature curves in supplier contracts. German formulators consolidate procurement around certified low-temperature processors with established EFSA dossier libraries.
- Dietary Supplements:Capsule and tablet applications prioritize bioactive fraction retention for immune positioning; Irish supply chains dominate premium capsule-grade isolate.
- Bakery Products:Industrial bread and pastry applications favor concentrate grades where modified dairy proteins face displacement; transparency requirements tighten procurement documentation.
- Dairy:Functional milk and yogurt fortification uses native whey for clean-label protein enhancement; Scandinavian cooperative networks supply cost-competitive concentrate streams.
Sports nutrition commands premium pricing; dietary supplements gain share fastest.
End User:
Customer type fragmentation separates performance-driven procurement from wellness-oriented purchasing behaviors.
- Athletes:Competitive and professional sports participants drive isolate specification for leucine threshold optimization; direct-to-consumer subscription models bypass traditional brand intermediation.
- Fitness Enthusiasts:Recreational gym users expand the addressable base for concentrate-grade powders; online retail channels capture this price-sensitive segment.
- Health-Conscious Consumers:Clean-label prioritization favors grass-fed and cold-processed certifications; MILEI GmbH and FrieslandCampina Ingredients anchor European supply.
- Medical Patients:Malabsorption, post-surgical recovery, and senior nutrition applications specify hydrolysate for pre-digested protein delivery; FDA GRAS pathways enable US clinical expansion.
Fitness enthusiasts represent the largest addressable base; medical patients drive the steepest value-per-kilogram expansion.
Distribution Channel:
Supply concentration shapes channel economics as quality verification requirements compress traditional distribution tiers.
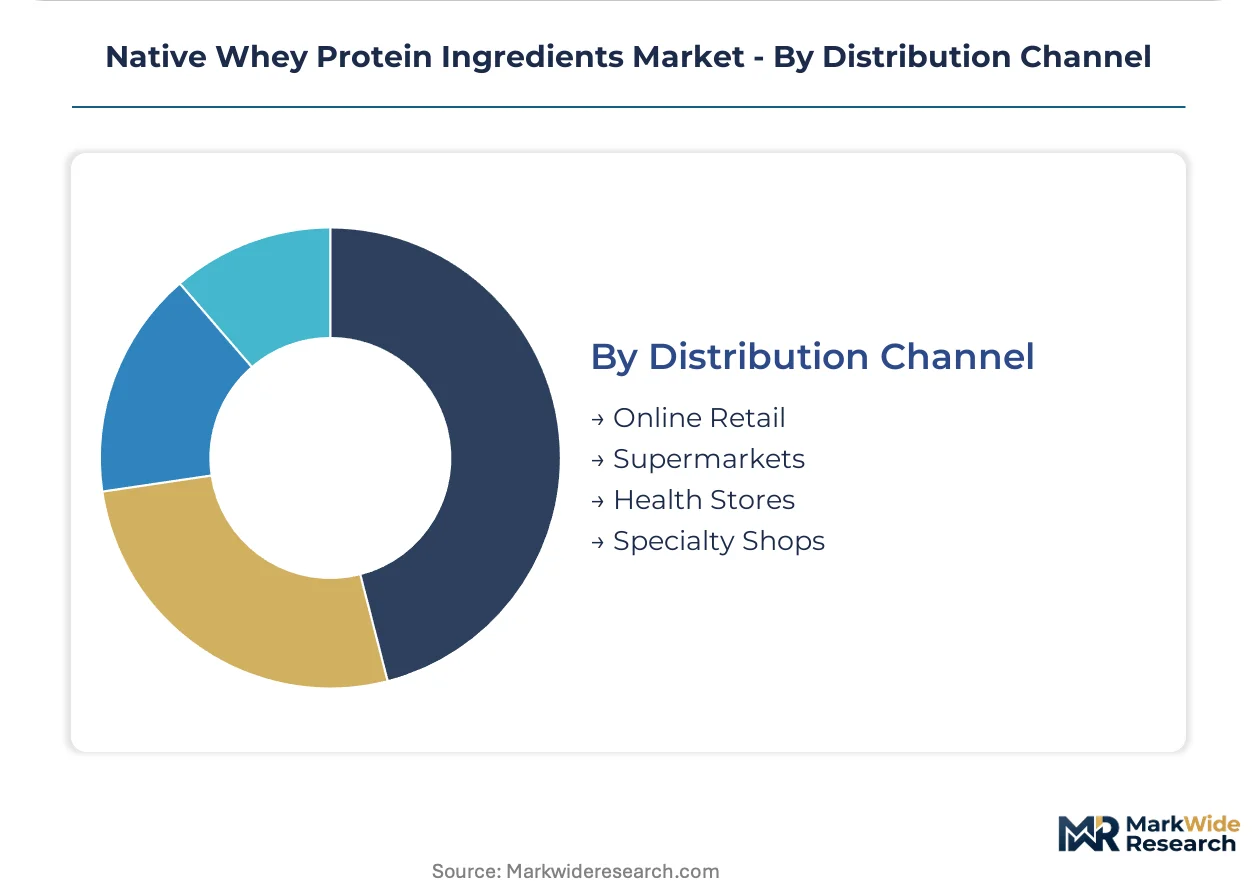
- Online Retail:Direct-to-consumer platforms and subscription services capture growing share of minimally processed protein sourcing; large brands embed quality auditors at Irish and Danish supplier facilities.
- Supermarkets:Mass-market powder and bar placement favors concentrate grades with established retail slotting; German retail consolidation favors pan-European suppliers.
- Health Stores:Specialty retail channels prioritize isolate and hydrolysate positioning with clinical substantiation; EFSA health claim compliance determines shelf access.
- Specialty Shops:Independent sports nutrition retailers serve dedicated athlete segments with technical specification support; regional clustering in Scandinavia and Benelux.
Online retail captures volume leadership; health stores deliver the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in native whey protein ingredients tilt toward export surplus in dairy-abundant northern European nations, while import dependency shapes procurement strategies in protein-deficient Asian markets. Germany and Ireland anchor outbound shipment volumes through integrated cooperative processing infrastructure. Regulatory divergence between EFSA-substantiated health claims and FDA GRAS pathways fragments cross-Atlantic product development timelines.
Germany
EFSA health claim substantiation requirements concentrate premium isolate procurement decisions among Munich and Frankfurt sports nutrition formulators seeking muscle protein synthesis positioning. The country's national dairy regulator enforces strict cold-chain documentation for bioactive fraction retention claims. MILEI GmbH anchors production clustering in Bavaria, supplying pan-European functional food manufacturers with certified low-temperature processed isolates.
United States
FDA GRAS notification pathways enable hydrolysate penetration into post-surgical recovery and clinical malabsorption formulations across major metropolitan hospital networks. The agency's updated nutrition labeling requirements push manufacturers toward cleaner ingredient decks with transparent protein sourcing. California and Wisconsin dairy processing corridors concentrate import demand for Irish and Scandinavian isolate grades serving premium sports nutrition brands.
Ireland
Glanbia Nutritionals leverages captive grass-fed dairy supply streams to secure premium raw milk access for isolate production serving UK and continental European export markets. The country's national food safety authority enforces rigorous cold-processing certification for bioactive retention claims. County Kilkenny and Cork processing facilities anchor backward-integrated production infrastructure with direct quality auditor relationships from North American brand procurement teams.
Netherlands
Medical nutrition formulators in Utrecht and Rotterdam drive hydrolysate procurement expansion for senior health and post-surgical recovery applications requiring pre-digested protein delivery. EFSA transparency mandates on health claim substantiation force documentation of protein denaturation thresholds at the ingredient level. FrieslandCampina Ingredients anchors supply concentration serving German and Benelux clinical nutrition manufacturers with established regulatory dossier libraries.
Denmark
Arla Foods Ingredients secures competitive positioning through cooperative farming network integration across Jutland and Zealand dairy regions. The country's veterinary and food administration oversees stringent dairy ingredient safety standards governing cross-border trade flows with Swedish and German markets. Copenhagen-area technical centers concentrate membrane filtration expertise with limited operator availability constraining rapid capacity expansion.
Native Whey Protein Ingredients Market Competitive Landscape
Listed leaders compete with private specialists across membrane filtration capability tiers, with cooperative ownership structures dominating premium isolate supply. The supplier base stratifies between backward-integrated dairy networks with captive cold-chain infrastructure and independent processors dependent on spot milk markets. Three archetypes define positioning: cooperative-owned filtration operators with grass-fed supply control, publicly traded nutrition platforms with multi-source procurement, and specialized ceramic microfiltration houses with technical certification depth. Competitive moves center on membrane equipment procurement partnerships and direct quality auditor embedding at formulator facilities.
Among European cooperative-based operators, FrieslandCampina Ingredients and MILEI GmbH exemplify the premium-tier archetype through integrated farming-to-ingredient control. Glanbia Nutritionals occupies a position representing publicly listed platforms with multi-territory supply base diversification. These three anchors demonstrate how ownership structure and geographic supply concentration determine competitive tier access in EFSA-regulated European markets.
| Leading Market Players |
|---|
| Lactalis Ingredients |
| Ingredia SA |
| Glanbia Nutritionals |
| Arla Foods Ingredients |
| Fonterra Co-operative Group |
| MILEI GmbH |
| Hilmar Cheese Company |
| Agropur Dairy Cooperative |
| FrieslandCampina Ingredients |
| Others |
Supply & Pricing Matrix
EFSA health claim substantiation requirements gate both supplier qualification and price differentiation simultaneously, forcing formulators to pay premiums for certified low-temperature processors with established dossier libraries while excluding heat-treated alternatives from premium positioning.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on membrane pore size certification and grass-fed supply chain documentation. Cost compression in concentrate grades is intensifying because precision fermentation alternatives threaten displacement in bakery applications. Fitness enthusiasts purchasing through online retail channels exhibit the highest price sensitivity, while medical nutrition formulators purchasing hydrolysate for clinical applications show the lowest.
Supply Chain Analysis
Inventory lead times stretch longest for ceramic microfiltration equipment sourced from limited European vendors, constraining rapid capacity expansion. Geographic supply concentration centers on Germany, Ireland, and Denmark, where cooperative dairy networks feed cold-processing facilities. Raw material dependencies include grass-fed raw milk streams, ceramic membrane modules, and enzymatic hydrolysis catalysts. Single-source equipment vulnerability creates procurement bottlenecks. Distribution runs through bilateral manufacturer-formulator relationships that have replaced traditional three-tier structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among large sports nutrition brands has shifted buyer power decisively, as technical teams now embed quality auditors directly at supplier facilities rather than relying on distributor intermediation.
For Market Incumbents: Secure backward integration into captive grass-fed dairy supply streams to defend margin pools against precision fermentation substitution. Invest in ceramic microfiltration capacity expansion in Bavaria and County Kilkenny before equipment procurement queues lengthen. Prioritize FDA GRAS notification completion for hydrolysate grades to lock in US clinical nutrition channel access. For New Entrants and Emerging Players: Lead with specialized hydrolysate production for post-surgical recovery applications, where regulatory barriers deter commodity competitors. Target the underpenetrated US clinical nutrition segment through direct technical partnerships with hospital network formulators. Differentiate via transparent bioactive fraction retention documentation that exceeds EFSA transparency minimums. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydrolysate manufacturing as enzymatic hydrolysis expertise concentrates among limited operator pools. Five-to-ten year viability favors acquisition targets with established EFSA dossier libraries and embedded quality auditor relationships from North American brands. Monitor FDA precision fermentation guidance timelines as the critical inflection signal for animal-derived protein valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Microfiltration Capacity Expansion | MILEI GmbH and FrieslandCampina Ingredients anchor Bavarian production clustering serving pan-European formulators. |
| FDA GRAS Notification Completion | Hydrolysate manufacturers unlock US hospital network procurement for post-surgical recovery applications. |
| Backward Integration into Grass-Fed Supply | Glanbia Nutritionals leverages Irish cooperative networks to secure premium raw milk stream access. |
| Direct Quality Auditor Embedding | Large sports nutrition brands compress distribution tiers by stationing technical teams at Irish supplier facilities. |
| EFSA Dossier Library Investment | Medical nutrition formulators in Utrecht and Rotterdam consolidate procurement around certified low-temperature processors. |
Research Methodology
A standing panel of membrane filtration operators, sports nutrition procurement directors, clinical nutrition formulators, and dairy cooperative supply managers provided ongoing calibration throughout the study. Primary interview findings triangulated against secondary sources including EFSA health claim submission databases, FDA GRAS notification filings, and customs trade flow records. Bottom-up volume modeling across product type and application segments reconciled with top-down dairy protein market sizing.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled product type, application channel, end-user archetype, and regional production hub dimensions simultaneously. CAGRs derived from segment-level growth rate distributions weighted by protein concentration tier and bioactive fraction retention specifications. Forecast inputs incorporated membrane equipment procurement queues, grass-fed milk supply seasonality, and regulatory pathway timelines.
The analysis sits within stated boundaries; outcomes outside EFSA health claim framework stability or precision fermentation regulatory acceleration would require recalibration. Forecasts reflect documented assumptions regarding cold-processing technology adoption curves and dairy cooperative pricing structures. Precision fermentation cost parity achievement represents the primary risk factor that could revise animal-derived protein demand trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Plant Protein Ingredients Market
Ingredients
Siraitia Grosvenorii Extract Market
Ingredients
Coconut Derivatives Market
Ingredients
Quark Powder Market
Ingredients
Alginate Market
Ingredients
Phytogenic Market
Ingredients
United States Gelatin Market
Ingredients
Sprouted Brown Rice Protein Market
Ingredients
Orange Powder Market
Ingredients
Pine Needle Oil Market
Ingredients
Wheat Germ Oil Market
Ingredients
Synephrine Market
Ingredients
Pea Starch Market
Ingredients
Egg Yolk Powder Market
Ingredients
Commercial Amino Acids Market
Ingredients
Jasmine Extract Market