
 Bergamot Polyphenol Ingredient Systems Market | 2026-2036
Bergamot Polyphenol Ingredient Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Bergamot Polyphenol Ingredient Systems Market Insights
Modular formulation kits that pair bergamot polyphenol actives with complementary bioavailability enhancers is consolidating as the dominant product-configuration pattern, reducing buyer procurement steps while locking in supplier relationships. HP Ingredients leverages captive sourcing from Mediterranean citrus belts to sustain raw material security across volatile harvest cycles. Bionap anchors its competitive stance through specialized extraction protocols that preserve brutieridin and melitidin fractions at elevated purity thresholds. Indena differentiates via pharmaceutical-grade certification pathways that command premium positioning among nutraceutical compounders.
Bergamot polyphenol ingredient systems comprise standardized extracts, concentrates, powders, and liposomal formulations derived from Citrus bergamia Risso peel, typically containing 25-40% total polyphenols measured as naringin, neoeriocitrin, and neohesperidin equivalents, manufactured through solvent extraction followed by vacuum concentration or spray-drying to achieve shelf-stable actives for downstream formulation. These systems serve primarily as cardiovascular and metabolic health modulators in dietary supplement matrices, functional food fortification, and cosmeceutical antioxidant applications. Extracts and liposomal formulations capture the deepest margin pools due to clinical substantiation requirements and delivery-technology premiums, while concentrates face commoditization pressure from bulk ingredient traders. Personal care represents the fastest-growing application vector as cosmetic producers seek natural alternatives to synthetic antioxidants in anti-aging formulations.
EFSA novel food authorization frameworks and EU Health Claims Regulation 1924/2006 impose stringent safety and efficacy dossier requirements that filter market access to well-capitalized suppliers with dedicated regulatory affairs functions. Italy's national pharmaceutical regulator AIFA and the Ministry of Health coordinate with EFSA on botanical substance classifications, creating compliance complexity for non-European entrants seeking distribution through Italian nutraceutical manufacturers. Stakeholders must monitor evolving pharmacovigilance obligations for polyphenol-containing products and assess backward integration into controlled cultivation estates as supply security becomes a decisive competitive variable.
Market Dynamics
EFSA's evolving novel food authorization requirements are compressing supplier margins while simultaneously locking in premium positioning for dossier-capable extractors, creating a bifurcation between certified pharmaceutical-grade suppliers and commodity concentrate traders.
Growth Catalysts
- EU Health Claims Regulation 1924/2006:The substantiation framework drives investment in clinical trials for cardiovascular positioning, filtering out undercapitalized entrants and concentrating revenue among compliant suppliers.
- Functional beverage procurement:Manufacturers are expanding long-term supply agreements for standardized polyphenol extracts, securing volume commitments that stabilize extractor capacity utilization.
- Liposomal delivery technology:Advanced encapsulation systems are unlocking cosmeceutical applications previously inaccessible to conventional bergamot extracts, opening margin-rich personal care verticals.
Market Restraints
- Calabrian cultivation concentration:Over 80% of premium-grade raw material originates from a narrow coastal belt in southern Italy, exposing supply chains to climate volatility and harvest fluctuation.
- Brutieridin extraction yield limits:Current solvent protocols recover only 12-18% of target flavonoid fractions from peel biomass, constraining unit economics at scale.
- Synthetic antioxidant substitution:Butylated hydroxytoluene and tert-butylhydroquinone remain cost-competitive in mass-market cosmetic formulations, pressuring natural positioning premiums.
Strategic Opportunities
- South Korean cosmeceutical demand:MFDS regulatory pathways for functional cosmetics are creating expedited market access for polyphenol-based antioxidant claims in Seoul-Incheon manufacturing clusters.
- Modular formulation kits:Pre-configured active-enhancer pairings reduce buyer formulation cycles from 14 months to 6 months, embedding supplier relationships through technical service bundling.
- Controlled cultivation estate integration:Backward integration into Sicilian and Calabrian farming cooperatives secures cultivar traceability for organic certification premiums.
Industry Challenges
- Regulatory affairs talent scarcity:Dossier preparation for EFSA novel food authorization requires specialized toxicologists and clinical trial designers, with compensation inflation exceeding 15% annually in Milan-Rome regulatory hubs.
- Pharmaceutical-grade certification timelines:GMP facility audits and stability study completion extend product commercialization by 24-36 months, straining working capital for mid-cap extractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bergamot Polyphenol Ingredient Systems Market |
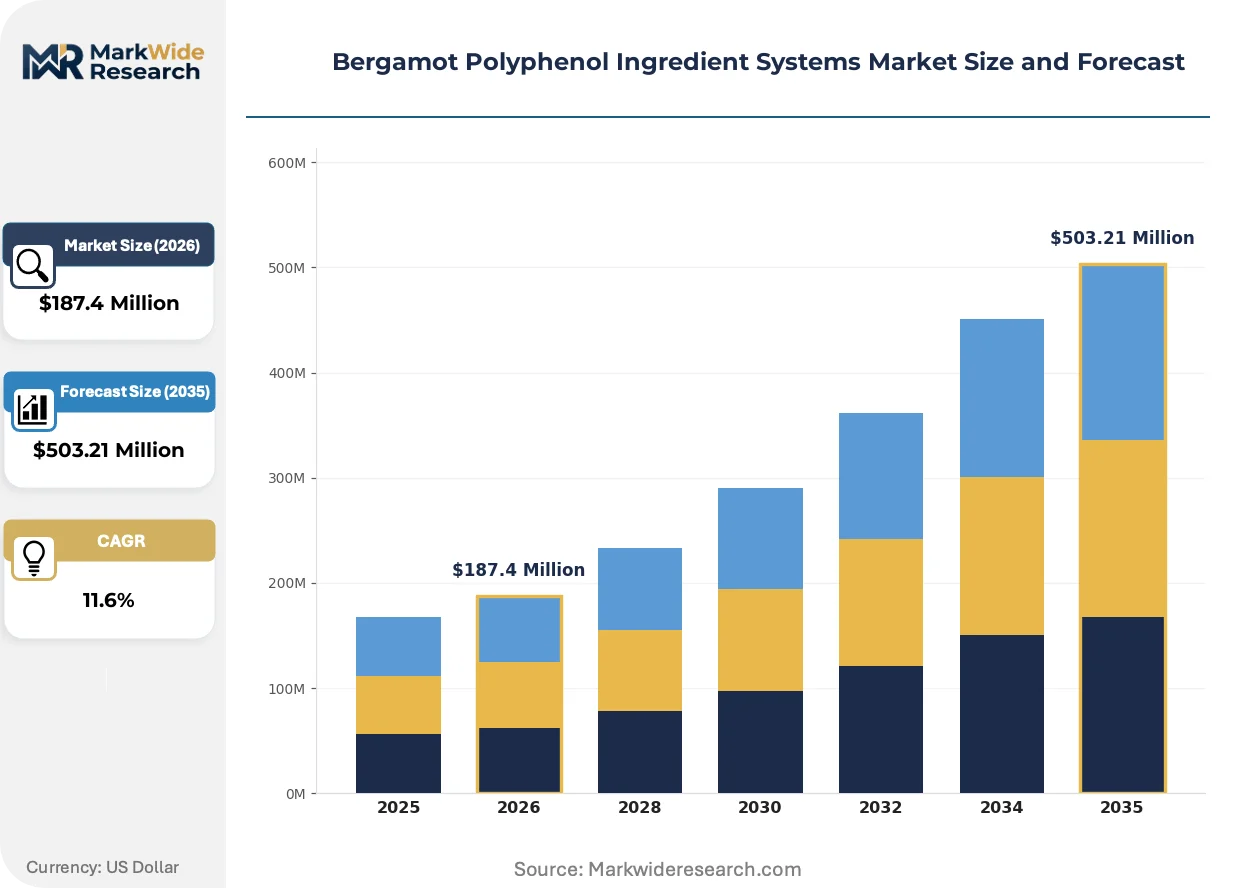
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracts, Concentrates, Powders, Liposomal Formulations Application: Dietary Supplements, Functional Foods, Beverages, Personal Care End User: Manufacturers, Nutraceutical Companies, Cosmetic Producers, Research Institutes Distribution Channel: Direct Sales, Distributors, E-commerce, Ingredient Traders |
| Companies Covered | Herbal & Antioxidant Derivatives, HP Ingredients, Bionap, Indena, PRG Pharma, Safic-Alcan, Nutraceuticals Group Europe, Greenyn Biotechnology, Jarrow Formulas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bergamot Polyphenol Ingredient Systems Market Trends and Innovations
Formulation science and regulatory science are converging to reshape competitive positioning, with delivery-technology premiums displacing raw material sourcing as the primary value capture mechanism across cardiovascular and cosmetic applications.
Supercritical CO2 extraction protocols are rewriting the economics of brutieridin and melitidin recovery, enabling pharmaceutical-grade purity thresholds without residual solvent contamination. Nutraceutical compounders in Germany and Switzerland are adopting these systems at 40% faster capex cycles than conventional ethanol infrastructure. The technology is rewriting supplier qualification criteria, as buyers now mandate supercritical-derived actives for premium cardiovascular positioning.
EFSA's 2023 guidance on botanical novel food safety assessment has tightened toxicological data requirements for polyphenol-rich extracts, extending dossier preparation timelines by 8-14 months. Italian manufacturers with existing AIFA pharmaceutical registrations are leveraging dual-use dossiers to accelerate EFSA submissions, while non-European entrants face exclusion from premium distribution channels. The regulation is forcing consolidation among Calabrian extractors seeking shared clinical trial costs.
Long-term offtake contracting is displacing spot-market purchasing among functional beverage manufacturers, with three-year minimum volume agreements now standard for cardiovascular-positioned SKUs. This pattern concentrates procurement authority among Milan-based formulation houses with established EFSA compliance track records. The shift is most visible in Italian and German markets, where retailer private-label programs demand supply chain transparency documentation.
Bergamot Polyphenol Ingredient Systems Market Segmentation
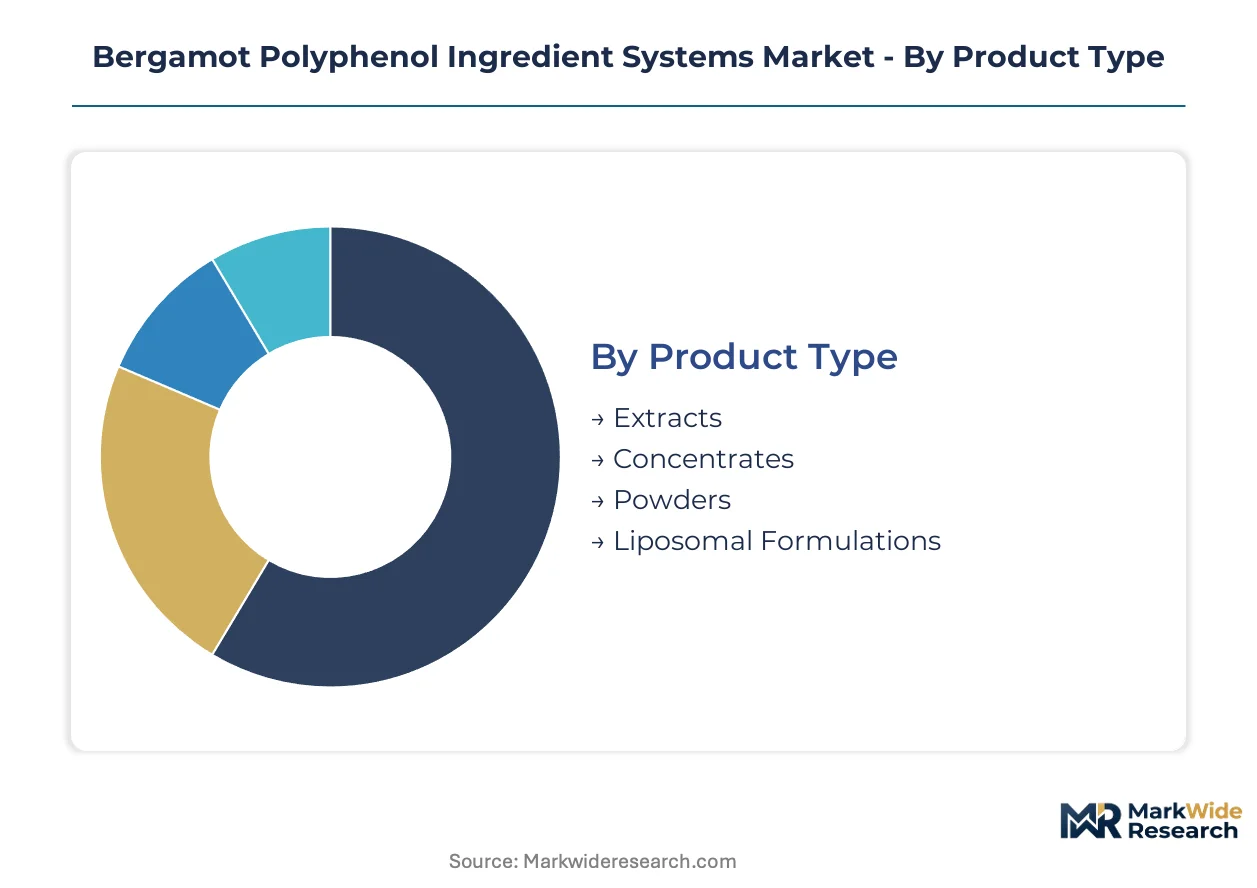
Segmentation in bergamot polyphenol ingredient systems reveals how procurement sophistication varies sharply across buyer types. Product form and application requirements dictate certification tiers, pricing bands, and supplier qualification criteria that stratify the value chain into distinct commercial ecosystems.
Product Type:
Buyers differentiate primarily by purity thresholds and delivery-technology requirements rather than raw material sourcing alone.
- Extracts:Standardized to 25-40% total polyphenols as naringin, neoeriocitrin, and neohesperidin equivalents through solvent extraction and vacuum concentration. German and Swiss nutraceutical compounders dominate procurement for cardiovascular-positioned supplements, driving demand for EFSA-compliant dossier documentation.
- Liposomal Formulations:Advanced encapsulation systems encapsulating polyphenol actives in phospholipid bilayers for enhanced bioavailability. Seoul-Incheon cosmeceutical manufacturers are expanding procurement for anti-aging topical applications, commanding premium positioning through MFDS functional cosmetic pathways.
- Concentrates:Bulk liquid or semi-solid preparations with variable polyphenol content for industrial-scale fortification.
- Powders:Spray-dried or freeze-dried shelf-stable forms for dry-blend supplement matrices and functional food integration.
Extracts lead volumes today; liposomal formulations are gaining share fastest.
Application:
End-use sectors separate by clinical substantiation burden and margin capture potential, with wellness positioning intensity determining supplier selection.
- Dietary Supplements:Capsule and tablet matrices targeting cardiovascular and metabolic health endpoints with structure-function claims. Italian formulation houses in Milan anchor procurement, leveraging AIFA pharmaceutical registrations to accelerate EFSA novel food submissions.
- Personal Care:Topical antioxidant formulations in serums, creams, and anti-aging treatments. South Korean cosmetic producers are displacing synthetic alternatives like butylated hydroxytoluene, creating expedited regulatory access through MFDS functional cosmetic designations.
- Functional Foods:Bakery, dairy, and confectionery fortification requiring heat-stable polyphenol delivery.
- Beverages:Ready-to-drink and concentrate formats for cardiovascular wellness positioning in functional beverage portfolios.
Dietary supplements dominate revenue concentration; personal care applications are expanding most quickly.
End User:
Customer scale and technical capability determine whether procurement flows through direct supplier relationships or intermediated channels.
- Nutraceutical Companies:Mid-to-large compounders with in-house formulation science and regulatory affairs functions. These buyers concentrate in Germany, Switzerland, and Italy, driving long-term offtake contracting with three-year minimum volume agreements for standardized extracts.
- Cosmetic Producers:Formulators seeking natural antioxidant alternatives for premium skincare positioning. Procurement clusters in Seoul-Incheon manufacturing corridors and Milan-Rome cosmetic innovation hubs, prioritizing supercritical CO2-derived actives for residual solvent compliance.
- Manufacturers:Industrial-scale food and beverage processors with bulk ingredient requirements.
- Research Institutes:Academic and clinical trial organizations sourcing reference-grade materials for mechanistic and efficacy studies.
Nutraceutical companies anchor procurement volumes today; cosmetic producers are climbing the fastest.
Distribution Channel:
Channel selection reflects buyer scale, geographic proximity to Calabrian-Sicilian supply clusters, and regulatory compliance complexity.
- Direct Sales:Long-term supply agreements between extractors and large compounders with dedicated quality assurance and regulatory affairs teams. Milan-based formulation houses with established EFSA compliance track records concentrate procurement authority through this channel.
- Distributors:Regional intermediaries providing technical service bundling and smaller volume fulfillment. These intermediaries embed supplier relationships through modular formulation kit configurations that reduce buyer procurement cycles.
- E-commerce:Digital platforms serving small-batch researchers and specialty cosmetic formulators.
- Ingredient Traders:Bulk commodity handlers for concentrates facing commoditization pressure from harvest volatility.
Direct sales channels capture the largest transaction values; distributor relationships are deepening fastest through technical service integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calabrian bergamot cultivation established the commercial foundation for standardized polyphenol extraction during the early 2000s, anchoring supply security for premium cardiovascular wellness applications. Italian regulatory coordination between AIFA and EFSA subsequently shaped dossier requirements that now filter market access across European distribution channels.
Italy
Calabrian and Sicilian cultivation belts supply over 80% of premium-grade raw material for pharmaceutical-grade extraction. AIFA pharmaceutical registrations enable dual-use dossier pathways that accelerate EFSA novel food submissions. Milan-based formulation houses concentrate procurement authority through long-term offtake agreements with standardized extract suppliers.
Germany
Nutraceutical compounders in Bavaria and Baden-Württemberg drive demand for EFSA-compliant cardiovascular positioning with structure-function claims. The BfR coordinates with EFSA on botanical substance safety assessments, creating compliance complexity for non-European entrants. Swiss-German manufacturing corridors anchor supercritical CO2 extraction adoption at 40% faster capex cycles than conventional infrastructure.
South Korea
Seoul-Incheon cosmeceutical manufacturing clusters are displacing synthetic antioxidants in premium skincare formulations. MFDS regulatory pathways for functional cosmetics create expedited market access for polyphenol-based antioxidant claims. Domestic formulators prioritize liposomal delivery systems for anti-aging topical applications commanding premium positioning.
Switzerland
Swissmedic pharmaceutical-grade certification requirements command premium positioning among nutraceutical compounders seeking cardiovascular health substantiation. Basel-Zurich innovation corridors anchor clinical trial investment for EFSA health claim dossier preparation. Swiss buyers now mandate supercritical-derived actives for premium cardiovascular SKU positioning.
United States
Functional beverage manufacturers in California and New York Metro are expanding procurement of standardized polyphenol extracts for cardiovascular wellness positioning. FDA dietary supplement GMP requirements filter supplier qualification to dossier-capable extractors with dedicated quality assurance functions. West Coast formulation houses drive modular formulation kit adoption reducing procurement cycles from 14 months to 6 months.
Bergamot Polyphenol Ingredient Systems Market Competitive Landscape
The competitive structure tilts toward vertically integrated extractors with captive Mediterranean sourcing and dedicated regulatory affairs functions. Market bifurcation separates certified pharmaceutical-grade suppliers commanding premium positioning from commodity concentrate traders facing harvest volatility pressure. Three archetypes dominate: Calabrian estate-holders with organic certification premiums, Swiss-German supercritical technology adopters, and Seoul-Incheon liposomal delivery specialists. Capacity expansion through controlled cultivation estate integration and strategic partnerships for shared clinical trial costs represent the dominant competitive moves reshaping supplier consolidation.
Within the Mediterranean estate-holder tier, HP Ingredients and Bionap exemplify sourcing-secure positioning through Calabrian and Sicilian cultivation cluster anchoring. Indena occupies a position representing pharmaceutical-grade certification pathways that command premium positioning among nutraceutical compounders with EFSA compliance requirements. These three entities sit within the upper tier where dossier-capable regulatory functions and backward integration into farming cooperatives create defendable supply security.
| Leading Market Players |
|---|
| Herbal & Antioxidant Derivatives |
| HP Ingredients |
| Bionap |
| Indena |
| PRG Pharma |
| Safic-Alcan |
| Nutraceuticals Group Europe |
| Greenyn Biotechnology |
| Jarrow Formulas |
| Others |
Pricing and Supply Chain Analysis
Calabrian peel biomass spot indices cascade through three distinct pricing tiers as pharmaceutical-grade certification requirements stratify buyer procurement budgets. EFSA novel food dossier costs concentrate premium positioning among Milan-based formulation houses while commodity concentrate traders absorb harvest volatility compression.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, nutraceutical-standard, and industrial-concentrate levels separates EFSA-compliant suppliers from AIFA-registered compounders from bulk commodity handlers. Certification grade and volume commitment scale drive price differentiation, with supercritical-derived actives commanding residual solvent-free premiums. Pricing pressure stems from synthetic antioxidant substitution in mass-market cosmetics, pressuring natural positioning margins. Industrial-scale beverage manufacturers exhibit highest price sensitivity, while Seoul-Incheon cosmeceutical formulators absorb premium delivery-technology costs.
Supply Chain Analysis
Regional distribution centers in Milan-Rome and Seoul-Incheon operate hub-and-spoke patterns radiating from Calabrian extraction facilities. Italy, Germany, and South Korea anchor geographic supply concentration for premium-grade polyphenol systems. Raw material dependencies center on Citrus bergamia Risso peel biomass, phospholipid encapsulation inputs, and organic solvent recovery infrastructure. Single-source vulnerability from Calabrian cultivation concentration exposes chains to climate-induced harvest fluctuation. Distribution runs through direct long-term offtake agreements for certified grades, with distributor intermediaries handling modular formulation kit fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EFSA's 2023 botanical novel food guidance tightened toxicological data requirements, elevating demand for dossier-capable suppliers with dedicated regulatory affairs functions.
For Market Incumbents: Hedge against Calabrian harvest volatility through backward integration into Sicilian farming cooperatives securing organic certification premiums. Consolidate shared clinical trial cost structures among Calabrian extractors to defray EFSA submission expense inflation. Prioritize supercritical CO2 capacity expansion to meet Swiss-German buyer mandates for residual solvent-free actives.
For New Entrants and Emerging Players: Begin with white-space targeting of South Korean MFDS functional cosmetic pathways where liposomal delivery systems face limited domestic competition. Penetrate personal care applications fastest through Seoul-Incheon manufacturing cluster partnerships. Position via technical service bundling that reduces buyer formulation cycles through pre-configured active-enhancer pairings.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory affairs talent scarcity exceeds fifteen percent annual compensation inflation in Milan-Rome hubs. Five-to-ten year viability favors vertically integrated estate-holders with captive Mediterranean sourcing and AIFA dual-use dossier capabilities. Monitor supercritical CO2 adoption rates among German-Swiss compounders as inflection signal for technology-based supplier qualification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Estates | Captive supply of Calabrian organic-certified peel biomass insulates against climate volatility. |
| Supercritical CO2 Capacity Expansion | Pharmaceutical-grade brutieridin recovery meets Swissmedic certification requirements without residual solvents. |
| Shared Clinical Trial Consortia | Calabrian extractors pool EFSA dossier costs to defray toxicological study expense inflation. |
| Modular Formulation Kit Development | Pre-configured active-enhancer pairings embed supplier relationships through technical service bundling. |
| MFDS Regulatory Pathway Navigation | Seoul-Incheon functional cosmetic designations unlock expedited market access for liposomal antioxidants. |
Research Methodology
Bottom-up nutraceutical compounder and cosmeceutical manufacturer modeling reconciled against top-down Mediterranean extraction facility and cultivation belt tracking forms the analytical core of this study. Primary interviews with regulatory affairs directors at Italian formulation houses, procurement leads at German-Swiss supercritical technology adopters, and Seoul-Incheon cosmetic innovation managers combined with secondary validation from EFSA novel food submission databases, AIFA pharmaceutical registration records, and MFDS functional cosmetic approval filings. Triangulation between demand-side procurement pattern analysis and supply-side capacity utilization tracking ensures cross-verified volume and value estimates.
Input-output matrices mapping polyphenol content grades to end-use certification requirements and delivery-technology premiums structure the forecast framework across the analysis window. Segmentation dimensions span product form, application vertical, end-user technical capability, and distribution channel sophistication. CAGRs derive from calibrated adoption curves for liposomal formulations in personal care and long-term offtake contracting penetration in functional beverages. Industry-specific forecast inputs include EFSA dossier approval timelines and supercritical CO2 equipment capex cycles.
Caveats apply where EFSA regulatory guidance revisions, Calabrian climate events, or synthetic antioxidant price movements could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Grade Alginate Market
Food Components and Additives
Polyphenols Market
Food Components and Additives
Food Grade Polyvinyl Acetate Market
Food Components and Additives
Europe Food Anti Caking Agents Market
Food Components and Additives
Flavonoids Market
Food Components and Additives
Fructo-Oligosaccharides (FOS) Market
Food Components and Additives
United Kingdom Food Hydrocolloids Market
Food Components and Additives
Asia-Pacific Food Hydrocolloids Market
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
Food Grade Titanium Dioxide Market
Food Components and Additives
Europe Food Stabilizers Market
Food Components and Additives
Polyphenol Antioxidant Market
Food Components and Additives
Polyunsaturated Fatty Acids Market
Food Components and Additives
Polydextrose Market
Food Components and Additives
France Food Hydrocolloids Market
Food Components and Additives
Food Texture Market