
 Australia Sodium Reduction Ingredients Market | 2026-2036
Australia Sodium Reduction Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Sodium Reduction Ingredients Market Outlook
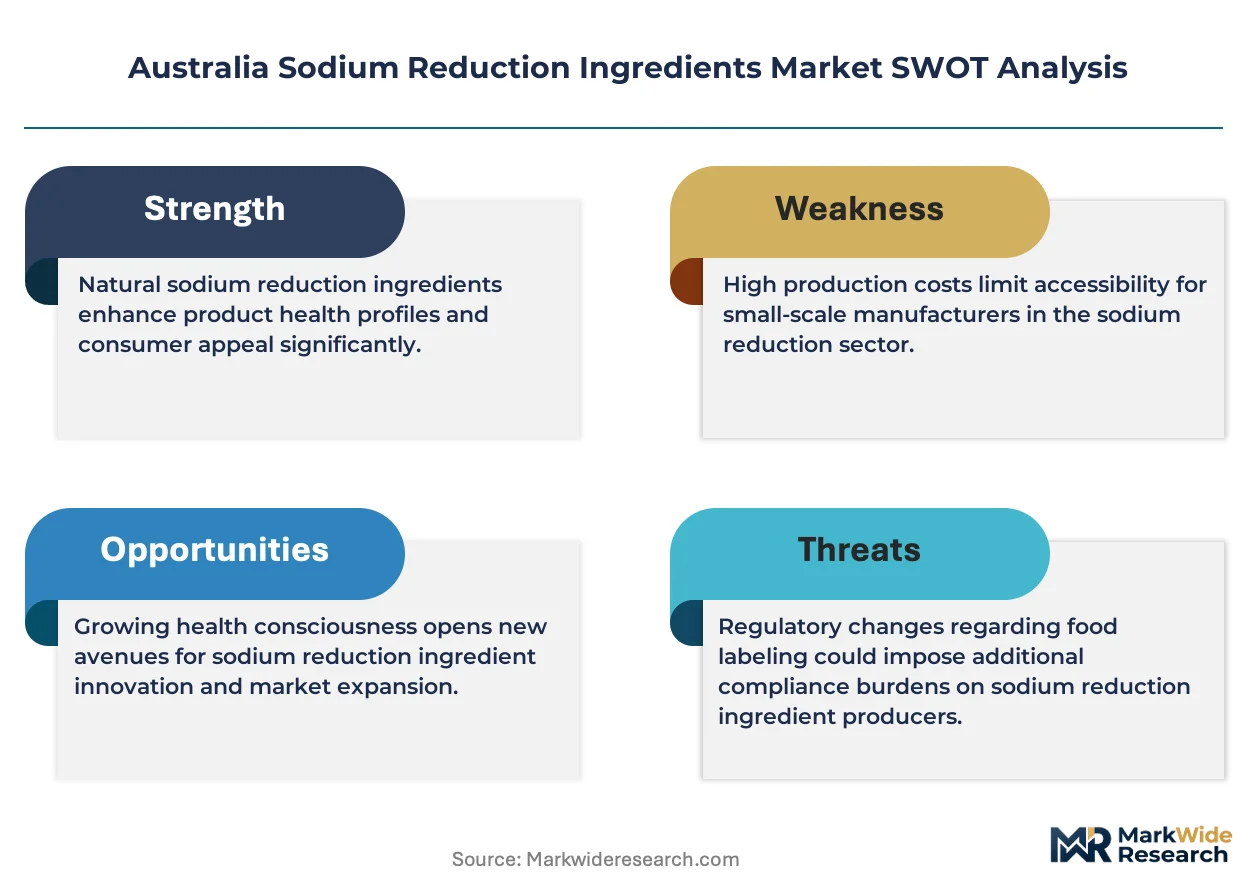
FSANZ sodium reduction targets is recalibrating the cost-of-entry calculus for ingredient suppliers seeking shelf placement in Australian retail. Cargill leverages its global salt-alternative portfolio to anchor supply relationships with domestic processed meat manufacturers. Kerry Group competes through flavor modulation systems that mask potassium chloride bitterness in reduced-sodium applications. Ingredion Incorporated specializes in texture-building starches that compensate for salt's functional loss in clean-label formulations.
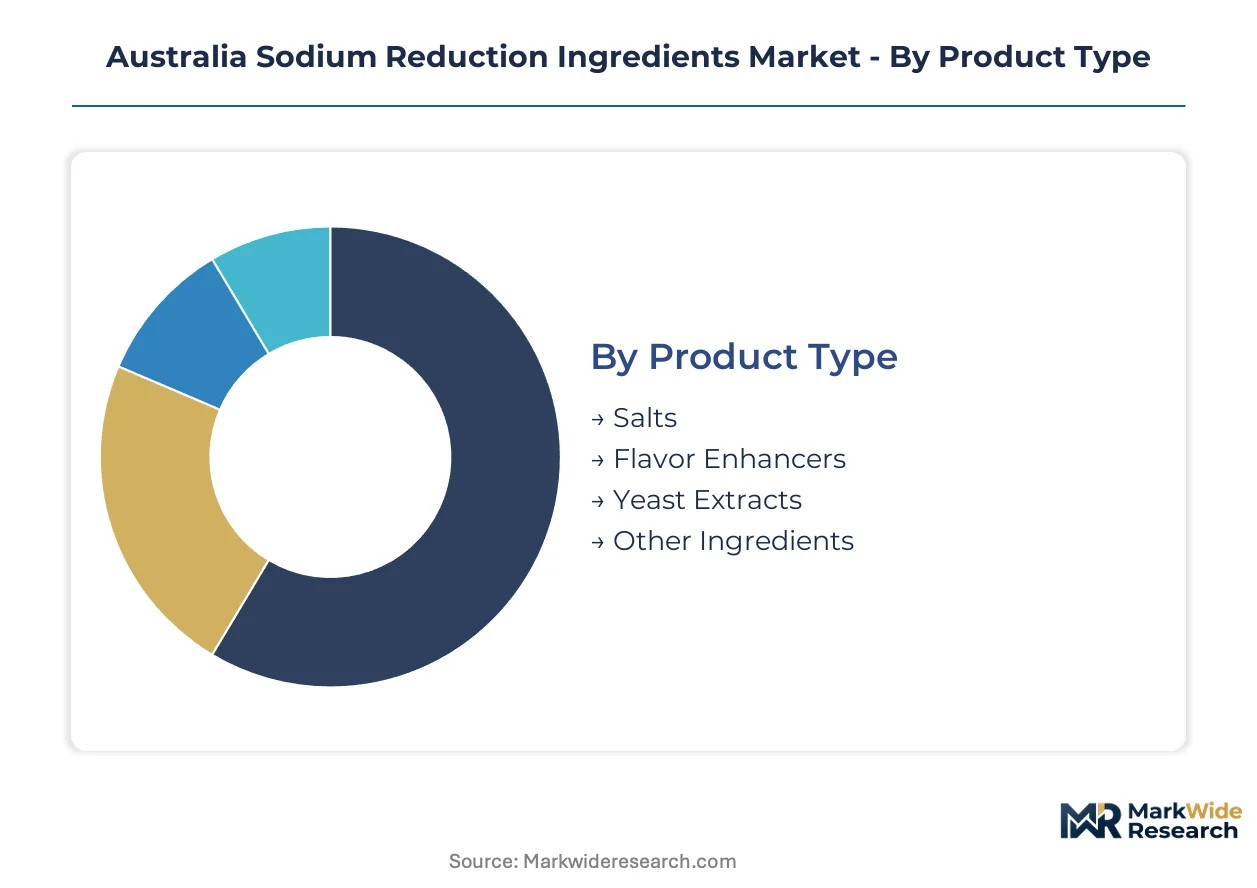
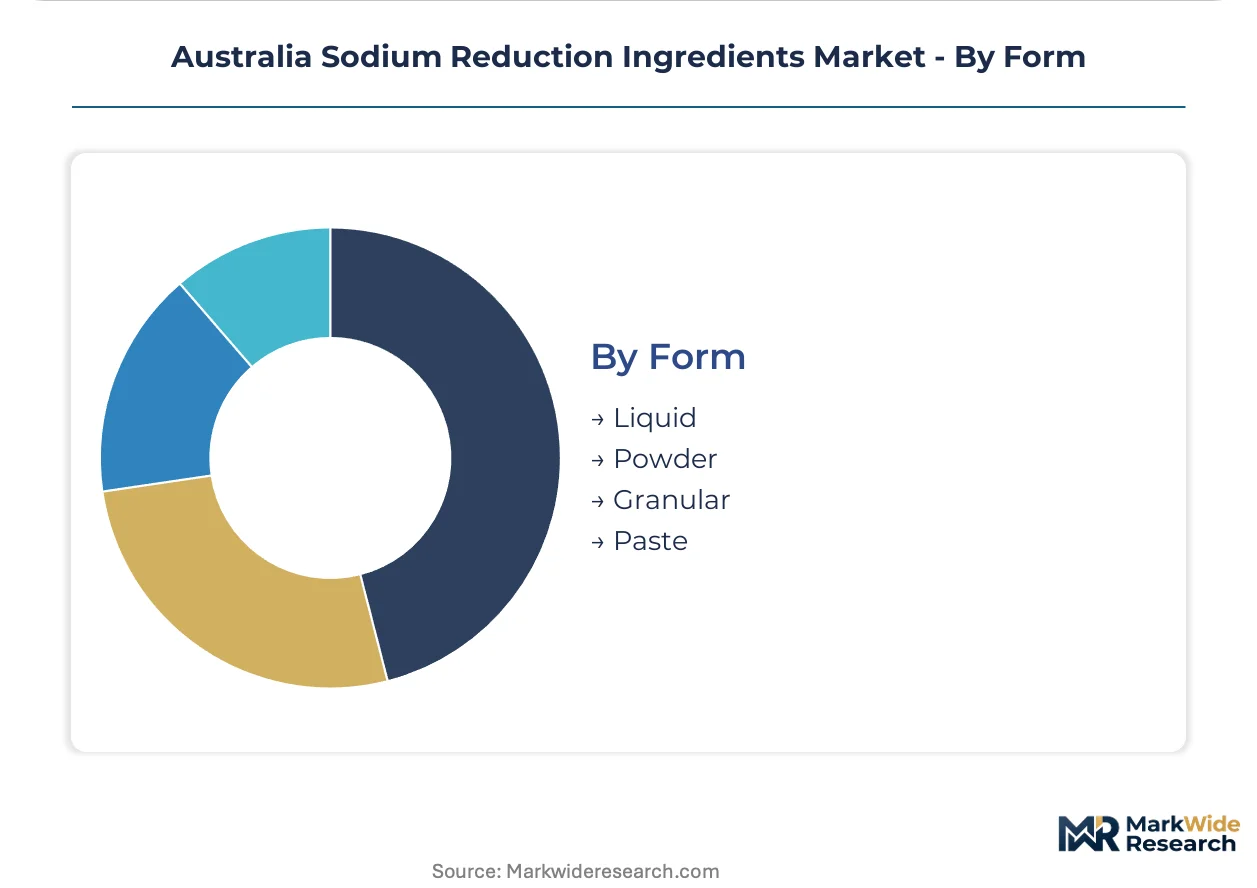
Sodium reduction ingredients comprise mineral salts, yeast-derived flavor potentiators, and botanical extracts engineered to replicate sodium chloride's sensory and preservative functions while delivering substantially lower sodium content per serving. Potassium chloride blends typically substitute 25-50% of sodium chloride in processed applications, though bitter off-notes require companion flavor technologies for consumer acceptance. Salts dominate current volume flows, yet yeast extracts capture expanding share as umami-forward formulations gain traction in sauces and condiments. Powder forms lead manufacturing throughput due to dosing precision and extended stability, while liquid formats grow fastest in ready-meal and sauce applications where homogeneous dispersion matters.
FSANZ maintains mandatory sodium reporting through the Health Star Rating system, while Food Standards Code Standard 2.10.2 governs salt substitute compositional limits. The Australian Competition and Consumer Commission scrutinizes sodium-related health claims under Australian Consumer Law, compressing marketing latitude for ingredient marketers. Stakeholders must monitor FSANZ's pending review of voluntary sodium targets for processed meat and bread categories, as tightened benchmarks would force accelerated reformulation cycles across Australia's concentrated retail grocery sector.
Market Dynamics
FSANZ's pending review of voluntary sodium targets for processed meat and bread categories is compressing reformulation timelines across Australia's concentrated retail grocery sector, forcing ingredient suppliers to accelerate R&D investment cycles.
Growth Catalysts
- Health Star Rating system:Mandatory sodium reporting through this FSANZ framework is compelling processed food manufacturers to reformulate existing product lines to maintain shelf placement and consumer visibility.
- Potassium chloride blends:These mineral salt substitutes now anchor 25-50% sodium replacement in processed meat applications across New South Wales and Victoria manufacturing hubs.
- Melbourne and Sydney food technology clusters:Concentrated R&D investment in these cities is accelerating commercialization of yeast-derived flavor potentiators for umami-forward sauce formulations.
Market Restraints
- Potassium chloride off-notes:Bitter taste profiles require companion flavor modulation technologies, adding formulation complexity and cost layers for clean-label developers.
- FSANZ Standard 2.10.2:Compositional limits on salt substitutes restrict maximum substitution rates in certain processed categories, capping reformulation flexibility.
- Input concentration:Yeast extract supply chains concentrate among limited fermentation capacity operators, creating vulnerability for umami-forward formulation scaling.
Strategic Opportunities
- Queensland and Western Australia expansion:These states show underpenetrated processed food manufacturing bases relative to sodium reduction ingredient adoption rates in eastern seaboard states.
- Liquid format acceleration:Ready-meal and sauce applications in Sydney and Melbourne are shifting toward homogeneous dispersion requirements that favor liquid yeast extract delivery systems.
- Clean-label texture compensation:Texture-building starches that replicate salt's functional properties represent white space for ingredient suppliers targeting premium positioning.
Industry Challenges
- Flavor modulation expertise gap:Formulation chemists capable of masking potassium chloride bitterness while maintaining clean-label status remain scarce in Australian talent pools.
- Reformulation capex cycles:Compressed timelines between FSANZ target announcements and compliance deadlines strain capital allocation for production line adjustments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Sodium Reduction Ingredients Market |
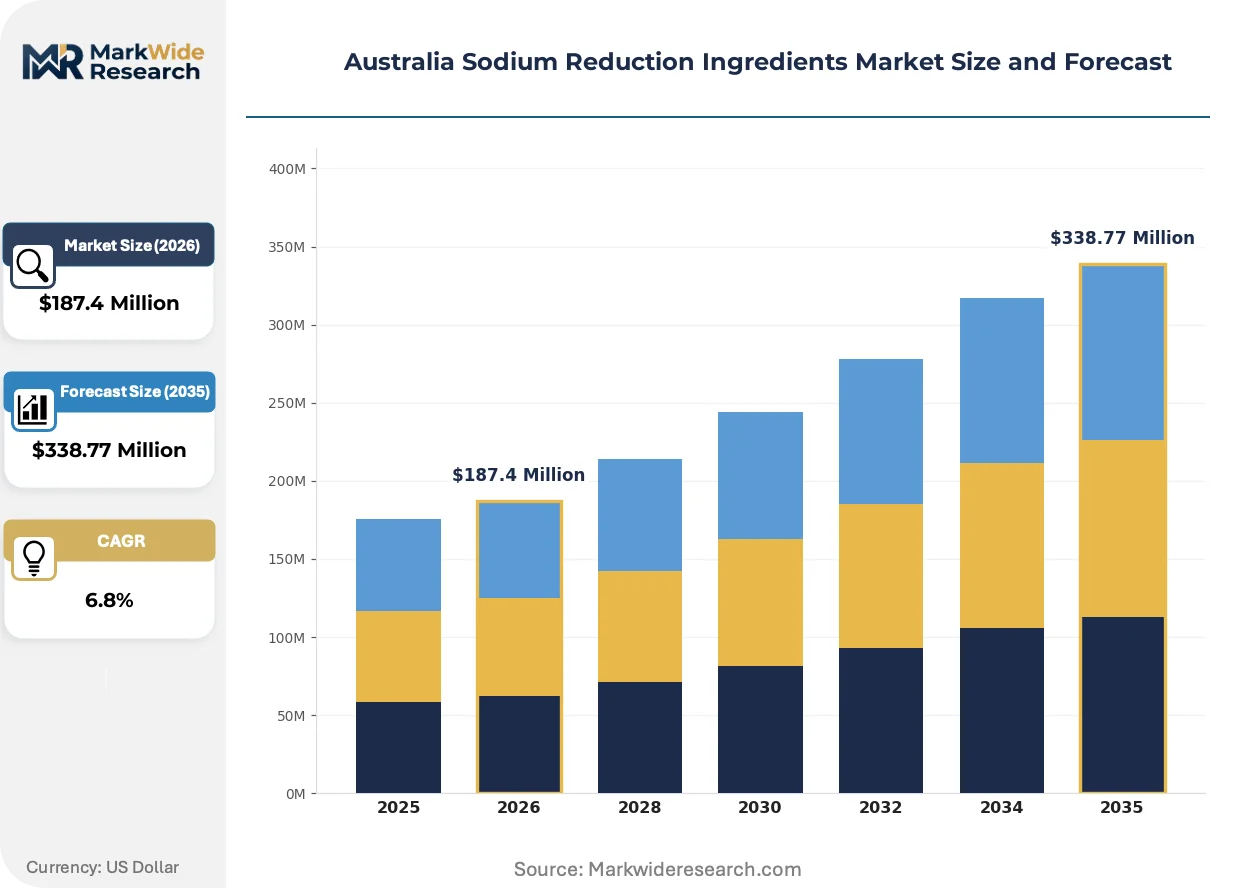
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salts, Flavor Enhancers, Yeast Extracts, Other Ingredients End User: Food Manufacturers, Restaurants, Retail Chains, Others Application: Snacks, Processed Foods, Sauces, Condiments Form: Liquid, Powder, Granular, Paste |
| Companies Covered | Ingredion Incorporated, Cargill, Tate & Lyle PLC, Kerry Group, DSM Nutritional Products, Salt of the Earth Ltd, Givaudan, Corbion, Kraft Heinz Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Sodium Reduction Ingredients Market Strategic Shifts
Yeast extract technology is displacing mineral salts as the preferred sodium reduction pathway in premium sauce and condiment formulations. Three interconnected developments are reshaping competitive positioning in ingredient supply.
Yeast-derived umami potentiators are consolidating market share in Australian sauce manufacturing. These fermentation-based ingredients deliver sodium reduction without the bitter off-notes associated with potassium chloride. Major condiment producers in Sydney and Melbourne are accelerating adoption. The technology is consolidating supplier relationships around specialized fermentation capacity operators with proven clean-label credentials.
FSANZ's Health Star Rating recalibration is tightening sodium thresholds for packaged bread and processed meat categories. This regulatory pressure is forcing accelerated reformulation cycles among manufacturers seeking to maintain four-star and above ratings. Victorian and New South Wales meat processors are responding with dual-track R&D investments in both mineral salt blends and yeast extract systems.
Ingredient procurement is rotating toward direct technical partnership models with suppliers. Large processed food manufacturers are bypassing traditional distributor channels to secure dedicated formulation support from yeast extract and mineral salt specialists. This shift is most pronounced in Melbourne's concentrated food technology hub, where co-development agreements now precede volume contracts.
Australia Sodium Reduction Ingredients Market Segmentation
Ingredient suppliers must calibrate portfolio depth against the standardization pressures of Australia's concentrated retail grocery sector. Segmentation strategy determines whether suppliers compete on formulation partnership depth or commodity volume throughput.
Product Type:
Customization intensity varies sharply across this category, from off-the-shelf mineral salts to co-developed yeast extract systems requiring dedicated technical collaboration.
- Salts:Potassium chloride and potassium-based blends constitute the volume foundation, with 25-50% sodium replacement capability in processed meat applications across New South Wales and Victoria. FSANZ Standard 2.10.2 compositional limits cap maximum substitution rates, constraining reformulation flexibility for clean-label developers seeking higher replacement thresholds.
- Yeast Extracts:Fermentation-derived umami potentiators deliver sodium reduction without potassium chloride's bitter off-notes. Melbourne and Sydney food technology hubs concentrate R&D investment here as premium sauce manufacturers accelerate adoption. Supply chains concentrate among limited fermentation capacity operators, creating scaling vulnerability.
- Flavor Enhancers:Companion masking technologies and modulation systems that enable higher potassium chloride inclusion rates.
- Other Ingredients:Botanical extracts and mineral complexes engineered for niche preservative-replacement functions.
Leading the category by volume: Salts. Growing fastest: Yeast Extracts.
End User:
Procurement sophistication separates this category, with multinational food manufacturers demanding integrated formulation support versus price-sensitive independent operators.
- Food Manufacturers:Processed meat and bread producers across Victoria and New South Wales drive bulk demand. FSANZ Health Star Rating recalibration compels reformulation investment to maintain four-star shelf positioning.
- Restaurants:Commercial kitchen operators in Sydney and Melbourne seek sodium reduction for menu labeling compliance and health-positioned offerings.
- Retail Chains:Private-label developers at Coles and Woolworths specify ingredient standards that cascade through supplier tiers.
- Others:Institutional foodservice and healthcare catering operations with specialized dietary requirements.
Food Manufacturers command procurement volume. Restaurants show steepest expansion trajectory as menu transparency regulations tighten.
Application:
Functional requirements fragment this category, from salt's structural role in processed meats to its flavor-delivery function in condiments.
- Processed Foods:Meat and bread categories face the most immediate FSANZ sodium target pressure. Victorian processors deploy dual-track R&D in mineral salts and yeast extracts to maintain compliance timelines.
- Sauces:Umami-forward formulations favor yeast extract adoption. Sydney and Melbourne condiment producers lead conversion away from potassium chloride due to bitterness sensitivity in liquid applications.
- Snacks:Seasoning applications balance cost constraints against clean-label positioning for premium positioning.
- Condiments:Table sauces and spreads where homogeneous dispersion requirements favor liquid format ingredients.
Processed Foods anchor current volume. Sauces gain share fastest as flavor modulation technology matures.
Form:
Manufacturing integration requirements divide this category between precision-dosing powder systems and homogeneous-dispersion liquid formats.
- Powder:Dominates current throughput due to dosing precision and extended stability in dry-mix applications. New South Wales and Victoria manufacturing hubs optimize production lines around powder handling infrastructure.
- Liquid:Ready-meal and sauce applications in Sydney and Melbourne shift toward this format where homogeneous dispersion matters. Technical partnership models with suppliers intensify for liquid system co-development.
- Granular:Intermediate flow properties for seasoning and topical applications.
- Paste:Concentrated delivery for high-viscosity sauce manufacturing.
Powder leads manufacturing throughput. Liquid climbs the fastest as ready-meal production expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New South Wales and Victoria concentrate sodium reduction ingredient demand through food technology clusters in Sydney and Melbourne. Queensland and Western Australia present expansion vectors with underpenetrated processed food manufacturing bases relative to eastern seaboard adoption rates.
New South Wales
Processed meat manufacturers in Sydney's western industrial corridor drive potassium chloride blend procurement for 25-50% sodium replacement formulations. FSANZ Health Star Rating mandatory reporting compels reformulation investment to maintain four-star retail shelf positioning. The Sydney food technology hub concentrates R&D partnerships between ingredient suppliers and condiment producers accelerating yeast extract adoption.
Victoria
Melbourne's concentrated food manufacturing sector anchors dual-track R&D investments in mineral salt and yeast extract systems for bread and processed meat compliance. Victorian meat processors face immediate FSANZ sodium target pressure with compressed reformulation timelines. The city's food technology cluster intensifies direct technical partnership models between manufacturers and fermentation-based ingredient specialists.
Queensland
Brisbane-Gold Coast processed food manufacturing shows lower sodium reduction ingredient penetration relative to New South Wales and Victoria adoption curves. Queensland's state-level food innovation programs support clean-label reformulation capability building among mid-tier manufacturers. Regional meat processors are initiating pilot programs with potassium chloride blends following eastern seaboard compliance precedents.
Western Australia
Perth's isolated food manufacturing base relies on distributed supply chains for sodium reduction ingredient procurement with higher logistics cost structures. The state's resource-driven economy limits dedicated food technology R&D investment relative to eastern states. Western Australian processed meat and sauce manufacturers are evaluating yeast extract systems as potassium chloride bitterness solutions gain market validation.
South Australia
Adelaide's smaller-scale food processing sector concentrates on premium positioning where clean-label sodium reduction commands price premiums. South Australian manufacturers prioritize yeast-derived flavor potentiators over mineral salts for umami-forward sauce applications. The state's wine industry adjacency supports fermentation expertise transfer into food ingredient innovation pipelines.
Australia Sodium Reduction Ingredients Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Australia's sodium reduction ingredient supply base. The market structure tilts toward consolidated global ingredient suppliers with established FSANZ regulatory navigation capabilities. Three strategic archetypes dominate: multinational salt-alternative portfolio holders, fermentation-derived flavor potentiator specialists, and texture-functional starch developers. Competitive moves concentrate on direct technical partnership models and co-development agreements that bypass traditional distribution channels.
Within the multinational diversified tier, Cargill and Kerry Group occupy anchor positions. Cargill represents the global salt-alternative portfolio archetype with supply relationships across domestic processed meat manufacturers. Kerry Group exemplifies the flavor modulation systems specialist archetype targeting potassium chloride bitterness masking applications. Ingredion Incorporated sits within the texture-functional ingredients tier, supplying starch systems that compensate for salt's functional loss in clean-label formulations.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Cargill |
| Tate & Lyle PLC |
| Kerry Group |
| DSM Nutritional Products |
| Salt of the Earth Ltd |
| Givaudan |
| Corbion |
| Kraft Heinz Company |
| Others |
Value Chain & Pricing Dynamics
Premium yeast extract formulations command 40-60% price premiums over standard potassium chloride blends, with that divergence mapping directly onto fermentation capacity scarcity versus mineral salt commodity availability. FSANZ compliance deadlines compress procurement timelines, forcing manufacturers to absorb premium pricing for guaranteed supply or risk reformulation delays.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as FSANZ target announcements trigger demand spikes. Three-tier pricing structure across premium yeast extracts, standard potassium blends, and economy mineral salts reflects formulation complexity and clean-label certification tiers. Pricing pressure stems from concentrated fermentation capacity among limited Australian operators, squeezing margins for sauce manufacturers seeking umami-forward alternatives. Independent processed food manufacturers show highest price sensitivity, while multinational anchors absorb premiums for supply security.
Supply Chain Analysis
Potassium chloride feedstock rests on Australian domestic salt processing and Canadian potash mining operations, with fermentation-derived yeast extracts drawing from specialized bioreactor capacity concentrated in Melbourne and Sydney. Raw material dependencies span agricultural potash, molasses substrates, and pharmaceutical-grade fermentation nutrients. Single-source vulnerability concentrates in yeast extract bioreactor networks, where capacity expansion lags demand acceleration by 18-24 months. Distribution runs through direct technical partnership models that bypass traditional ingredient distributors for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity scarcity props pricing power for yeast extract specialists, creating supply-constrained conditions that favor incumbent margin defense and selective new entrant positioning.
For Market Incumbents: Deepen backward integration into molasses substrate supply and bioreactor capacity expansion in Victoria to offset emerging mineral salt blend competitors. Anchor relationships with Coles and Woolworths private-label developers through dedicated formulation support teams that replicate Kerry Group's flavor modulation service model. Lock in multi-year offtake agreements with Queensland meat processors before FSANZ bread category targets accelerate. For New Entrants and Emerging Players: Launch via liquid format specialization targeting Sydney ready-meal manufacturers seeking homogeneous dispersion solutions. Queensland and Western Australia processed meat operations offer the most penetrable geography given eastern seaboard incumbent saturation. Position around clean-label texture compensation using Ingredion-style starch systems to bypass potassium chloride bitterness challenges entirely. For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-based flavor potentiator specialists given FSANZ's pending sodium target expansion and yeast extract's displacement trajectory in premium sauces. Long-term viability favors operators with captive bioreactor capacity and established FSANZ regulatory navigation capabilities. Watch yeast extract spot pricing volatility as the inflection signal for capacity shortage severity.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Melbourne bioreactor additions address yeast extract supply bottlenecks constraining sauce manufacturer reformulation timelines. |
| Direct Technical Partnership | Co-development agreements with Victorian meat processors bypass distributor markups and accelerate potassium chloride blend adoption. |
| Clean-Label Certification Investment | FSANZ-compliant natural flavor potentiator status commands shelf placement priority at Woolworths and Coles. |
| Queensland Geographic Expansion | Brisbane-Gold Coast meat processing penetration captures lagging adoption curves relative to eastern seaboard saturation. |
| Flavor Modulation R&D Partnership | Melbourne food technology cluster collaboration masks potassium chloride bitterness without clean-label compromise. |
Study Parameters
Document review covered FSANZ regulatory filings, Food Standards Code amendments, and Australian Bureau of Agricultural and Resource Economics trade data, complemented by interviews with ingredient procurement directors at processed meat manufacturers, fermentation facility operations managers, and retail chain private-label developers. Secondary validation drew from Australian Competition and Consumer Commission enforcement records, Health Star Rating system documentation, and customs import statistics for potassium chloride and yeast extract categories. Bottom-up volume estimates from individual manufacturing facility outputs were cross-referenced against top-down sector spending analyses.
Historical volume trajectories were cross-referenced against expert panel assessments of FSANZ compliance timeline feasibility across the projection horizon. Segmentation modeling covered product type, end user sophistication tier, application functional requirements, and form factor manufacturing integration needs. CAGRs were derived from slope-consistency checks against regulatory deadline pacing and adoption curve inflection points. Forecast inputs incorporated Health Star Rating recalibration scenarios and yeast extract bioreactor capacity commissioning schedules.
The model assumes a particular technology adoption path favoring yeast extract displacement of mineral salts in premium applications; alternative pathways emphasizing potassium chloride bitterness masking breakthroughs would alter the outlook toward mineral salt retention. Forecasts reflect assumptions about FSANZ target enforcement intensity and fermentation capacity expansion timing. A small set of triggers—bioreactor construction delays, unexpected FSANZ target acceleration, and potassium chloride flavor modulation patent expirations—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Middle East and Africa Dairy Ingredients Market
Ingredients
Cultured Non-Fat Dairy Ingredients Market
Ingredients
Starch-Derived Fiber Market
Ingredients
Commercial Flour Market
Ingredients
Marine Protein Market
Ingredients
Feed Premix Market
Ingredients
Fish Feed Ingredients Market
Ingredients
Pea Peptones Market
Ingredients
Global Distillers Grains Market
Ingredients
North America Gums Market
Ingredients
Dried Distillers' Grains with Soluble Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
South America Agar Market
Ingredients
Proteose Peptone Market
Ingredients
Soy Lecithin Market
Ingredients
Sunflower Protein Market