
 Egg Membrane Powder Market | 2026-2036
Egg Membrane Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Egg Membrane Powder Market Analysis
Specialized protein extraction technicians is rotating toward biotech hubs as egg membrane processing demands enzymatic hydrolysis expertise that conventional food science programs rarely cover. Biova LLC leverages captive supply chains for membrane sourcing from Midwestern egg-breaking facilities. Kewpie Corporation anchors production scale through integrated poultry operations in Japan. Eggnovo SL specializes in pharmaceutical-grade isolates for European cosmetic laboratories.
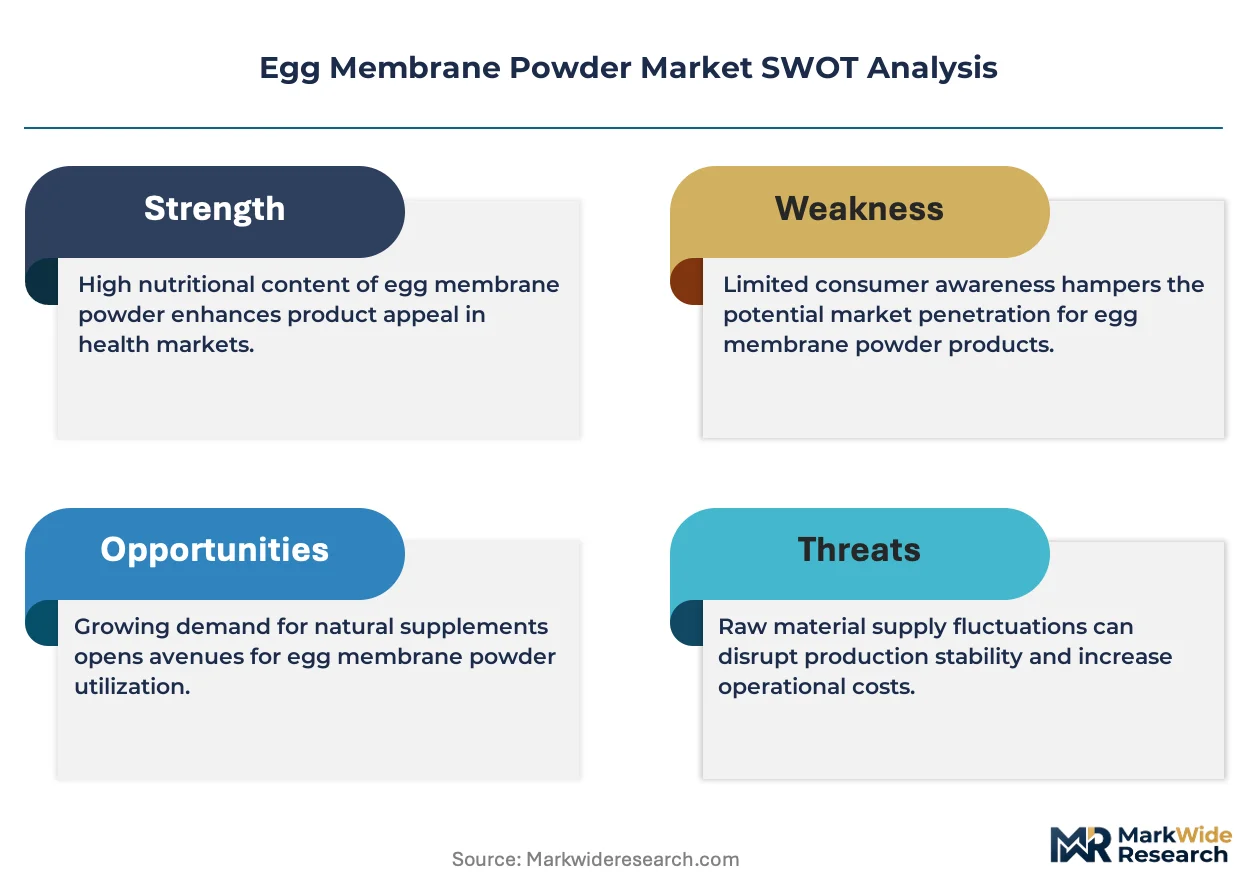
Egg membrane powder consists of dried, processed inner and outer eggshell membranes containing collagen types I, V, X, elastin, and glycosaminoglycans such as hyaluronic acid and chondroitin sulfate, typically recovered through mechanical separation followed by spray-drying or enzymatic hydrolysis to preserve bioactive peptide integrity. Manufacturers employ it primarily as a functional ingredient in nutricosmetic and orthopedic supplement formulations where endogenous collagen synthesis stimulation drives efficacy claims. Hydrolyzed product types command premium positioning due to superior bioavailability and faster dissolution profiles in beverage applications. Nutraceutical applications absorb the largest volume share as aging demographics in developed economies sustain demand for joint mobility and skin elasticity solutions.
US FDA GRAS self-affirmation pathways and EU EFSA Novel Food authorizations create divergent market entry timelines that favor established players with dedicated regulatory affairs teams. The USDA organic certification and ISO 22000 food safety management standards further segment supplier credibility tiers across export markets. Stakeholders must monitor evolving peptide characterization requirements from pharmacopeial bodies as clinical substantiation thresholds tighten for structure-function claims.
Market Dynamics
Enzymatic hydrolysis capability scarcity concentrates competitive advantage among processors with dedicated biotech R&D infrastructure, forcing mid-tier suppliers into toll-manufacturing arrangements or exit.
Growth Catalysts
- EU Novel Food authorization pathway:EFSA's structured safety assessment framework creates regulatory clarity that accelerates ingredient approval timelines for hydrolyzed membrane isolates entering European nutricosmetic formulations.
- Aging demographic joint health expenditure:Medicare-eligible populations in the United States sustain prescription-to-supplement substitution patterns that expand addressable market for collagen-alternative orthopedic products.
- Clean-label collagen displacement:Marine collagen supply volatility and bovine source religious dietary restrictions position avian-derived membrane proteins as the preferred alternative for halal and kosher-certified functional foods.
Market Restraints
- Input cost volatility:Shell egg price spikes at Midwestern breaking facilities transmit directly to membrane recovery economics, compressing processor margins during avian influenza outbreaks.
- Supply concentration risk:Captive membrane sourcing from integrated poultry operations in Japan and the United States limits spot market availability for independent nutraceutical formulators.
- Substitution threat:Fermentation-derived collagen peptides from precision biotech platforms achieve cost parity in beverage applications, threatening egg membrane's positioning in premium hydrolyzed segments.
Strategic Opportunities
- Underpenetrated South Korean nutricosmetic channel:MFDS functional food approval pathways for joint health claims remain underutilized by Western membrane suppliers relative to domestic chondroitin sulfate dominance.
- Regulatory tailwind from USDA organic certification:Certified organic egg production expansion creates membrane supply pools that command 40-60% premia in European and North American premium supplement channels.
- Technology convergence of membrane fractionation and microencapsulation:Combined processing protects hyaluronic acid integrity through gastric transit, enabling pharmaceutical-grade applications previously restricted to synthetic sources.
Industry Challenges
- Peptide characterization skill scarcity:Analytical chemists with LC-MS/MS experience in collagenous protein sequencing command compensation premiums that inflate quality control department budgets.
- Capex intensity of GMP-grade isolation suites:ISO 14644 cleanroom infrastructure for pharmaceutical-grade membrane production requires seven-figure capital commitments that exclude smaller regional processors.
- Pharmacopeial standardization delays:United States Pharmacopeia monograph absence for egg membrane-derived chondroitin sulfate forces batch-specific analytical method validation, extending release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg Membrane Powder Market |
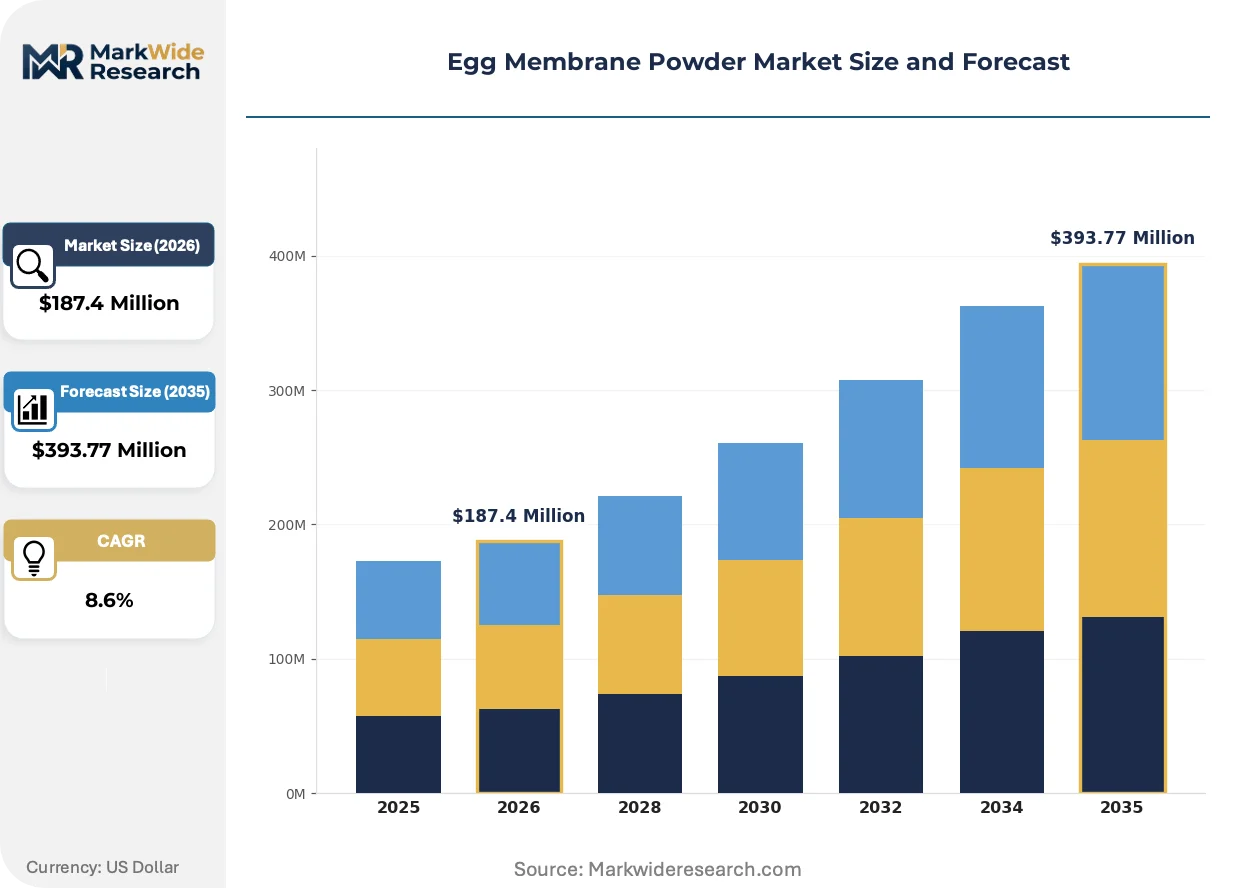
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Dehydrated, Spray-Dried, Hydrolyzed Application: Cosmetics, Nutraceuticals, Pharmaceuticals, Food & Beverages End User: Healthcare Providers, Manufacturers, Retailers, Distributors Packaging Type: Bulk, Sachets, Bottles, Bags |
| Companies Covered | Biova LLC, Kewpie Corporation, Eggnovo SL, Ecovatec Solutions Inc., Stratum Nutrition, Microcore Research Laboratories, Mitushi Biopharma, Certified Nutraceuticals Inc., Bolise Co., Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg Membrane Powder Market Emerging Trajectories
Processing technology divergence and regulatory pathway specialization are fragmenting the supplier base into distinct capability tiers that serve non-overlapping end-use segments.
Enzymatic hydrolysis with substrate-specific proteases is bifurcating the product landscape into bioactive peptide concentrates for clinical nutrition versus intact collagen fiber grades for cosmetic topical applications. Nutraceutical formulators in Germany and the United States are adopting peptide-characterized hydrolysates at accelerated procurement cycles. This technological split is compressing undifferentiated spray-dried whole-membrane suppliers into commodity pricing tiers while premium hydrolysate producers capture value from structure-function claim substantiation.
EFSA's 2023 updated guidance on novel food allergenicity assessment imposes additional in vitro protein digestibility study requirements for egg-derived ingredients. The industrial consequence extends development timelines by 12-18 months for new market entrants lacking existing safety dossiers. European cosmetic laboratories sourcing pharmaceutical-grade isolates are responding by consolidating supplier relationships with established authorization holders rather than qualifying novel sources.
Direct-to-practitioner distribution is displacing traditional ingredient broker networks for clinical-grade membrane peptides. Functional medicine clinics in the United States and integrative health practitioners in Australia are establishing preferred supplier agreements that bypass wholesale distributors. This channel compression is most visible in California and New South Wales, where practitioner-branded supplement lines specify single-source membrane traceability for patient compliance programs.
Egg Membrane Powder Market Segmentation
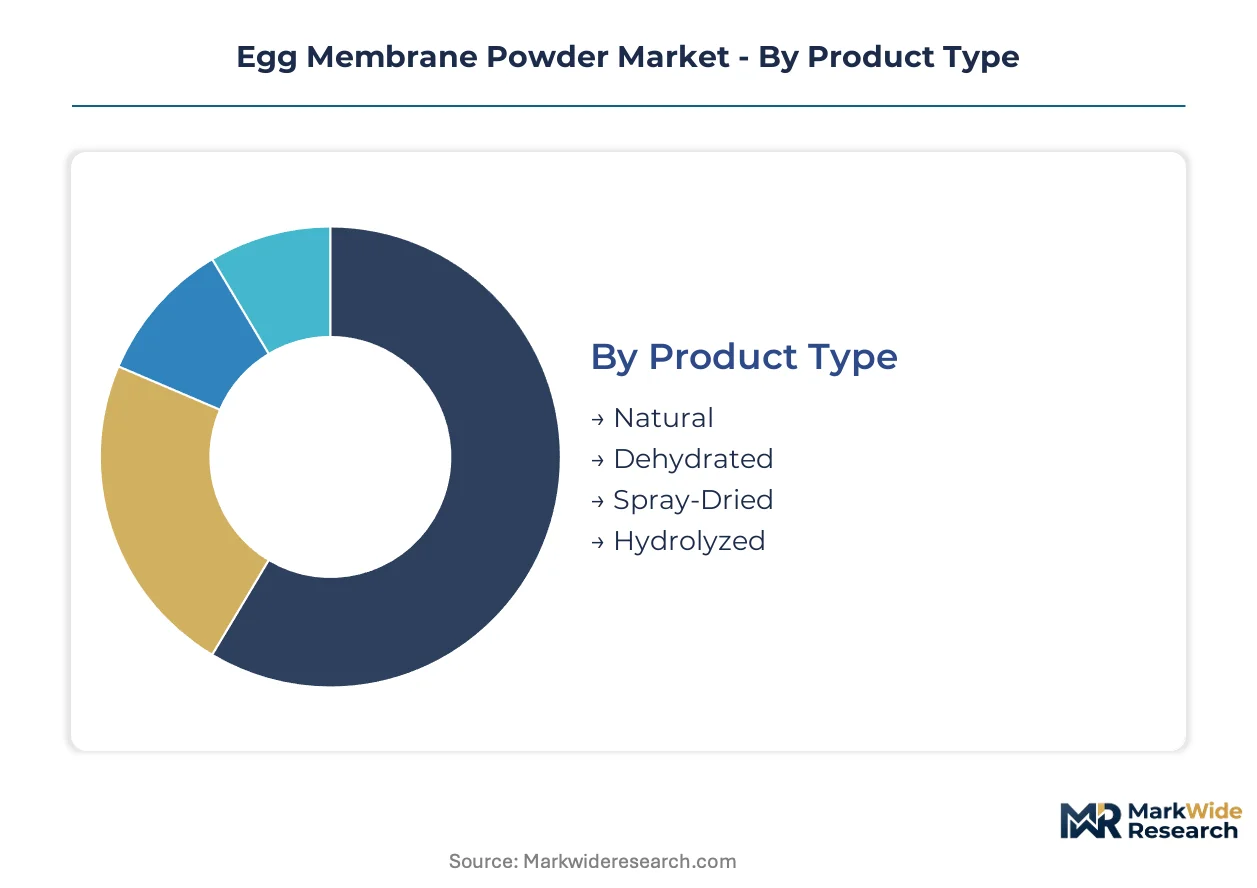
Segmentation in egg membrane powder reveals how processing intensity and regulatory classification determine commercial pathways. Manufacturers navigate divergent margin structures across natural extracts versus hydrolyzed bioactives, while application-specific purity requirements fragment supplier capabilities.
Product Type:
Natural and dehydrated grades serve domestic food manufacturers seeking cost-efficient collagen alternatives, while hydrolyzed variants target export-led nutraceutical formulators demanding peptide-characterized dossiers for EFSA Novel Food submissions.
- Hydrolyzed:Enzymatic cleavage with substrate-specific proteases yields bioactive peptides with enhanced bioavailability. German and US nutricosmetic laboratories prioritize these grades for joint health beverages requiring rapid dissolution and documented structure-function claims.
- Spray-Dried:Thermal processing preserves intact collagen fiber architecture for cosmetic topical formulations. Japanese and South Korean skincare manufacturers dominate procurement, driven by consumer preference for minimally processed natural ingredients in premium sheet masks and serums.
- Natural:Mechanical separation without thermal or enzymatic intervention retains native glycosaminoglycan ratios. Domestic supplement brands in North America favor this grade for whole-food positioning.
- Dehydrated:Low-temperature moisture reduction extends shelf stability for bulk ingredient trading. Regional distributors in Southeast Asia stock this grade for downstream toll-processing arrangements.
Spray-dried grades command the established base. The steepest expansion runs through hydrolyzed isolates.
Application:
Cost tier stratification separates pharmaceutical-grade isolates commanding seven-figure validation investments from food-grade powders accessible to mid-tier processors.
- Nutraceuticals:Dietary supplement formulations targeting joint mobility and skin elasticity absorb the largest volume share. Medicare-eligible populations in the United States sustain prescription-to-supplement substitution patterns that expand addressable market for collagen-alternative orthopedic products.
- Cosmetics:Topical nutricosmetic applications leverage hyaluronic acid and elastin content for dermal hydration claims. European cosmetic laboratories sourcing pharmaceutical-grade isolates are consolidating supplier relationships with established EFSA authorization holders.
- Pharmaceuticals:Clinical-grade peptides require ISO 14644 cleanroom production and pharmacopeial monograph compliance. Batch-specific analytical method validation extends release timelines where United States Pharmacopeia standards remain absent.
- Food & Beverages:Clean-label functional ingredients position avian-derived proteins as halal and kosher-certified alternatives to marine and bovine collagen. Beverage manufacturers prioritize hydrolyzed grades for solubility in ambient-stable formulations.
Nutraceutical applications anchor current revenue. Cosmetics and pharmaceuticals are climbing the fastest as peptide characterization capabilities mature.
End User:
Customer type determines procurement sophistication, with healthcare providers demanding single-source traceability while distributors aggregate spot-market volumes.
- Healthcare Providers:Functional medicine clinics and integrative health practitioners establish preferred supplier agreements bypassing wholesale channels. Direct-to-practitioner distribution concentrates in California and New South Wales.
- Manufacturers:Nutraceutical formulators and cosmetic laboratories drive specification-grade procurement with peptide characterization requirements.
- Distributors:Regional ingredient brokers aggregate undifferentiated spray-dried grades for mid-tier supplement brands.
- Retailers:Practitioner-branded supplement lines and premium wellness channels specify organic-certified membrane traceability.
Manufacturers represent the volume anchor. Healthcare providers are gaining share fastest through channel compression.
Packaging Type:
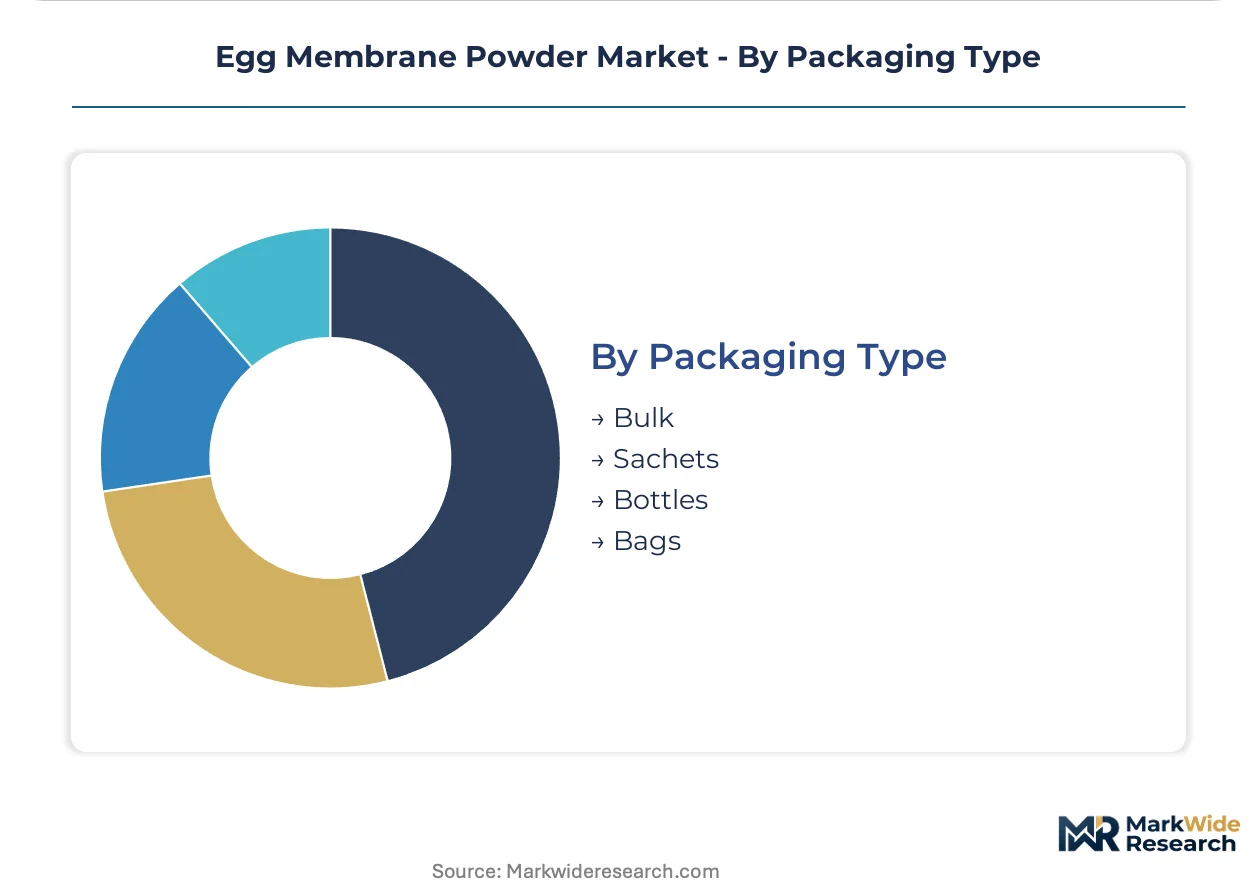
Supply concentration in integrated poultry operations favors bulk arrangements for captive processors, while independent formulators rely on sachet and bottle formats for flexibility.
- Bulk:Tanker and drum shipments serve integrated nutraceutical manufacturers with in-house blending capabilities. Biova LLC and Kewpie Corporation leverage captive supply chains for membrane sourcing.
- Sachets:Unit-dose formats support clinical trial materials and practitioner sample programs requiring precise dosing documentation.
- Bottles:Retail-ready packaging for direct-to-consumer supplement brands emphasizes shelf stability and tamper evidence.
- Bags:Intermediate bulk containers balance handling efficiency with moisture protection for regional distributors.
Bulk packaging dominates procurement economics. Sachet formats are expanding most quickly through clinical and practitioner channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA GRAS self-affirmation pathways in the United States establish the regulatory benchmark that shapes approval timelines for egg membrane powder entrants across developed markets. National regulators in Germany, Japan, South Korea, and Australia track FDA precedent while maintaining distinct submission requirements for novel food proteins.
United States
Medicare-eligible populations drive prescription-to-supplement substitution for joint health products. FDA GRAS notifications for hydrolyzed membrane isolates proceed through self-affirmation channels without mandatory pre-market approval. California functional medicine clinics consolidate preferred supplier agreements that bypass wholesale distribution channels.
Germany
Nutricosmetic laboratories prioritize peptide-characterized hydrolysates for beverage applications. EFSA Novel Food authorizations impose additional in vitro protein digestibility study requirements that extend development timelines. Bavarian ingredient distributors aggregate undifferentiated spray-dried grades for mid-tier European supplement brands.
Japan
Premium skincare manufacturers dominate procurement of intact collagen fiber grades for sheet mask formulations. METI standards for functional food labeling create distinct claim substantiation pathways separate from pharmaceutical regulations. Kewpie Corporation leverages integrated poultry operations in Chubu and Kanto regions for captive membrane supply.
South Korea
Domestic chondroitin sulfate producers currently dominate the nutricosmetic channel for joint health claims. MFDS functional food approval pathways remain underutilized by Western membrane suppliers relative to local ingredient dominance. Seoul-based cosmetic laboratories source pharmaceutical-grade isolates through consolidated supplier relationships with established EFSA authorization holders.
Australia
Integrative health practitioners in New South Wales establish direct-to-practitioner distribution channels that bypass traditional ingredient brokers. TGA therapeutic goods regulations distinguish between food-grade powders and clinical-grade peptides for practitioner compounding. Sydney and Melbourne wellness clusters specify organic-certified membrane traceability for patient compliance programs.
Egg Membrane Powder Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that relies on toll-manufacturing arrangements or regional distribution. Three archetypes define the competitive structure: captive processors with backward integration into egg-breaking facilities, enzymatic hydrolysis specialists with dedicated biotech R&D infrastructure, and undifferentiated commodity suppliers competing on spot-market pricing. Dominant competitive moves include capacity expansion in GMP-grade isolation suites and strategic partnerships with functional medicine clinics for direct-to-practitioner channel access.
Among integrated processors with captive supply chains, Biova LLC and Kewpie Corporation exemplify the scale-driven archetype through control over membrane sourcing from Midwestern and Japanese egg-breaking operations respectively. Eggnovo SL occupies a position within the pharmaceutical-grade specialist tier, serving European cosmetic laboratories with isolates requiring EFSA Novel Food authorization. These three entities anchor the competitive spectrum from commodity spray-dried grades through peptide-characterized hydrolysates.
| Leading Market Players |
|---|
| Biova LLC |
| Kewpie Corporation |
| Eggnovo SL |
| Ecovatec Solutions Inc. |
| Stratum Nutrition |
| Microcore Research Laboratories |
| Mitushi Biopharma |
| Certified Nutraceuticals Inc. |
| Bolise Co., Limited |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Midwestern egg-breaking facilities and membrane processors lock in both supply access and price visibility, insulating integrated players from shell egg volatility that compresses margins for spot-market buyers during avian influenza disruptions.
Pricing Analysis
Price spreads between pharmaceutical-grade hydrolysates and commodity spray-dried grades widen during supply shocks, with EFSA-authorized isolates commanding substantial premia over undifferentiated powders. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified isolates from food-grade hydrolysates and bulk dehydrated grades. Cost compression in the standard tier is intensifying because fermentation-derived collagen alternatives achieve cost parity in beverage applications. Independent nutraceutical formulators exhibit highest price sensitivity, while functional medicine clinics prioritize single-source traceability over unit economics.
Supply Chain Analysis
Inventory cycles extending six to nine months from membrane recovery to hydrolysate release create working capital intensity that favors processors with captive supply arrangements. Production concentrates in the United States, Japan, and Spain, where integrated poultry operations or specialized extraction facilities anchor supply. The chain draws from shell egg byproduct streams, substrate-specific proteases, and ISO 14644 cleanroom infrastructure. Single-source vulnerability runs through Midwestern egg-breaking concentration during avian influenza outbreaks. Distribution runs through direct-to-practitioner channels displacing traditional ingredient brokers for clinical-grade peptides.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egg membrane powder functions as a platform ingredient where interoperability between peptide characterization capabilities and regulatory authorization databases determines competitive position, with EFSA Novel Food dossiers serving as the critical ecosystem gateway for European market access.
For Market Incumbents: Compound regulatory moats by deepening EFSA authorization portfolios ahead of 2023 allergenicity guidance implementation, while expanding GMP-grade isolation capacity to defend against fermentation-derived collagen substitution threats. Backward integration into organic-certified egg production secures supply pools commanding premium channel access. For New Entrants and Emerging Players: Differentiate on enzymatic hydrolysis specialization targeting the underpenetrated South Korean nutricosmetic channel, where MFDS functional food approvals for joint health claims remain underutilized relative to domestic chondroitin dominance. Direct-to-practitioner distribution partnerships in California and New South Wales offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enzymatic hydrolysis specialists with established EFSA authorization holders, given the 12-18 month timeline extension for new entrants lacking safety dossiers. Acquisition targets should demonstrate captive membrane supply or toll-manufacturing relationships with integrated poultry operations. Watch for pharmacopeial monograph establishment for egg membrane-derived chondroitin sulfate as the inflection signal for pharmaceutical-grade market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Authorization Expansion | Accelerates European nutricosmetic market entry for hydrolyzed membrane isolates ahead of competitors. |
| GMP-Grade Isolation Suite Investment | Enables pharmaceutical-grade production serving cosmetic laboratories with ISO 14644 cleanroom requirements. |
| Organic Certification Supply Integration | Captures 40-60% price premia in European and North American premium supplement channels. |
| Direct-to-Practitioner Channel Development | Bypasses wholesale distributors through preferred supplier agreements with California functional medicine clinics. |
| Microencapsulation Technology Convergence | Protects hyaluronic acid integrity through gastric transit for pharmaceutical applications previously restricted to synthetic sources. |
Methodological Framework
The analysis maps hydrolyzed isolates, spray-dried grades, natural extracts, and dehydrated powders, each validated through protein extraction technicians, regulatory affairs specialists at nutraceutical formulators, cosmetic laboratory procurement managers, and functional medicine clinic operators. Primary interviews with these stakeholders combined with secondary validation against FDA GRAS notifications, EFSA Novel Food submissions, USDA organic certification databases, and ISO 22000 audit records. Bottom-up membrane recovery volume estimates triangulated against top-down nutraceutical ingredient demand projections.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled processing intensity tiers, application-specific purity requirements, end-user procurement sophistication, and regional regulatory pathway divergence. CAGRs derived from segment-level demand elasticity analysis incorporating aging demographic joint health expenditure patterns and clean-label collagen displacement trends.
Material uncertainties — avian influenza recurrence, fermentation-derived collagen cost parity acceleration, pharmacopeial standardization delays — sit outside the modeled envelope. Forecasts reflect assumptions about EFSA authorization timeline stability and Medicare-eligible population supplement substitution persistence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Feed Ingredients Market
Ingredients
United States Corn Glucose Market
Ingredients
Potato Fiber Market
Ingredients
Vegetable Concentrates Market
Ingredients
Plant Based Premix Market
Ingredients
Injection Grade Soybean Oil Market
Ingredients
Specialty Fats and Oils Market
Ingredients
Mussel Oil and Powder Market
Ingredients
Black Cumin Seed Oil Market
Ingredients
Asia-Pacific Bakery Ingredients Market
Ingredients
Protein Extracts from Single Cell Protein and Other Conventional Sources Market
Ingredients
Sodium Caseinate Market
Ingredients
Citrus Fiber Market
Ingredients
Brazil Starch Derivatives Market
Ingredients
Horehound Extract Market
Ingredients
India Soy Protein Market