
 Polyphenols Market | 2026-2036
Polyphenols Market Size, Share, and Industry Trends Forecast 2026-2036
Polyphenols Market Intelligence
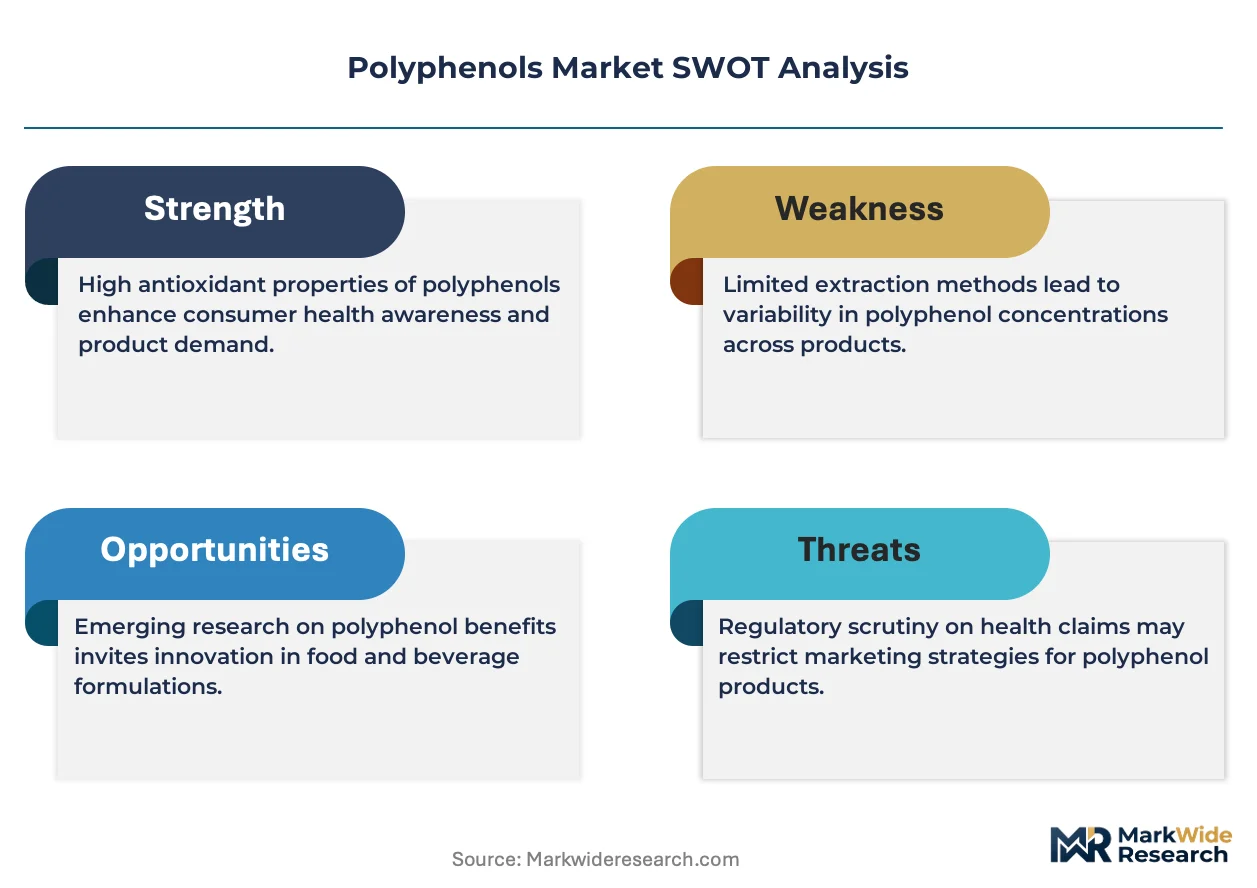
Asset-light contract extraction models is reconfiguring competitive entry barriers for mid-sized botanical processors. Cargill Incorporated leverages its integrated agricultural supply chains to secure raw material throughput for phenolic acid production. Indena S.p.A. anchors its position through pharmaceutical-grade purification capabilities that command premium offtake agreements. Kemin Industries Inc. differentiates via specialized grape seed extract formulations targeting dietary supplement brands.
Polyphenols comprise a structurally diverse class of plant secondary metabolites characterized by multiple hydroxylated aromatic rings, typically extracted through solvent-based or supercritical CO2 methods to preserve antioxidant capacity for food preservation and therapeutic applications. Flavonoids dominate commercial volume due to established supply chains from tea and citrus processing, while stilbenes command concentrated margin pools in pharmaceutical applications despite narrower raw material availability. Dietary supplements represent the fastest-growing end user channel as direct-to-consumer brands build demand for standardized extracts with verified polyphenol content.
The FDA oversees New Dietary Ingredient notifications for novel polyphenol isolates entering U.S. supplement channels, while EFSA's health claims regulation in Europe demands randomized controlled trial evidence before permitting cardiovascular or cognitive benefit statements. China's NMPA and SAMR coordinate traditional medicine ingredient standards that influence export specifications for tea-derived polyphenols. Stakeholders must monitor evolving substantiation thresholds across jurisdictions to determine where clinical investment will unlock commercial access versus where formulation constraints will limit positioning.
Market Dynamics
Functional beverage brands in the United States are accelerating polyphenol fortification programs, tightening raw material throughput requirements and forcing extraction processors to expand dedicated catechin production lines ahead of demand curves.
Growth Catalysts
- EFSA health claims substantiation:The European Food Safety Authority's tightened verification protocols for bioactive compounds are driving clinical investment that unlocks premium positioning for cardiovascular benefit statements.
- Tea-derived catechin extraction capacity:German ingredient processors are building dedicated facilities, concentrating supply-side expertise and reducing lead times for dietary supplement formulators.
- Supercritical CO2 purification:This solvent-free extraction technology preserves antioxidant capacity during processing, enabling pharmaceutical-grade applications that command higher offtake premiums.
Market Restraints
- Stilbene raw material scarcity:Narrow grape and berry cultivation bases concentrate supply risk in Mediterranean and Californian growing regions, creating price volatility for resveratrol isolates.
- FDA New Dietary Ingredient notification burden:Novel polyphenol isolates face extended review timelines before entering U.S. supplement channels, compressing product development windows.
- Flavonoid supply chain maturity:Established tea and citrus processing infrastructure limits margin expansion opportunities as commodity-grade extracts flood commodity pricing tiers.
Strategic Opportunities
- Direct-to-consumer supplement channels:Digital-native brands are building demand for standardized extracts with verified polyphenol content, bypassing traditional wholesale distribution markups.
- Pharmaceutical-grade stilbene applications:Therapeutic formulations targeting metabolic syndrome indications offer concentrated margin pools despite narrower addressable markets.
- China NMPA-SAMR traditional medicine standards:Export specification alignment for tea-derived polyphenols opens institutional procurement channels in domestic Chinese healthcare systems.
Industry Challenges
- Cross-jurisdiction substantiation thresholds:Clinical investment decisions require simultaneous tracking of FDA notification requirements, EFSA randomized controlled trial demands, and China's evolving traditional medicine ingredient standards.
- Extraction technician specialization:Solvent-based and supercritical CO2 methods demand distinct operational expertise, fragmenting workforce development pipelines across contract manufacturing networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyphenols Market |
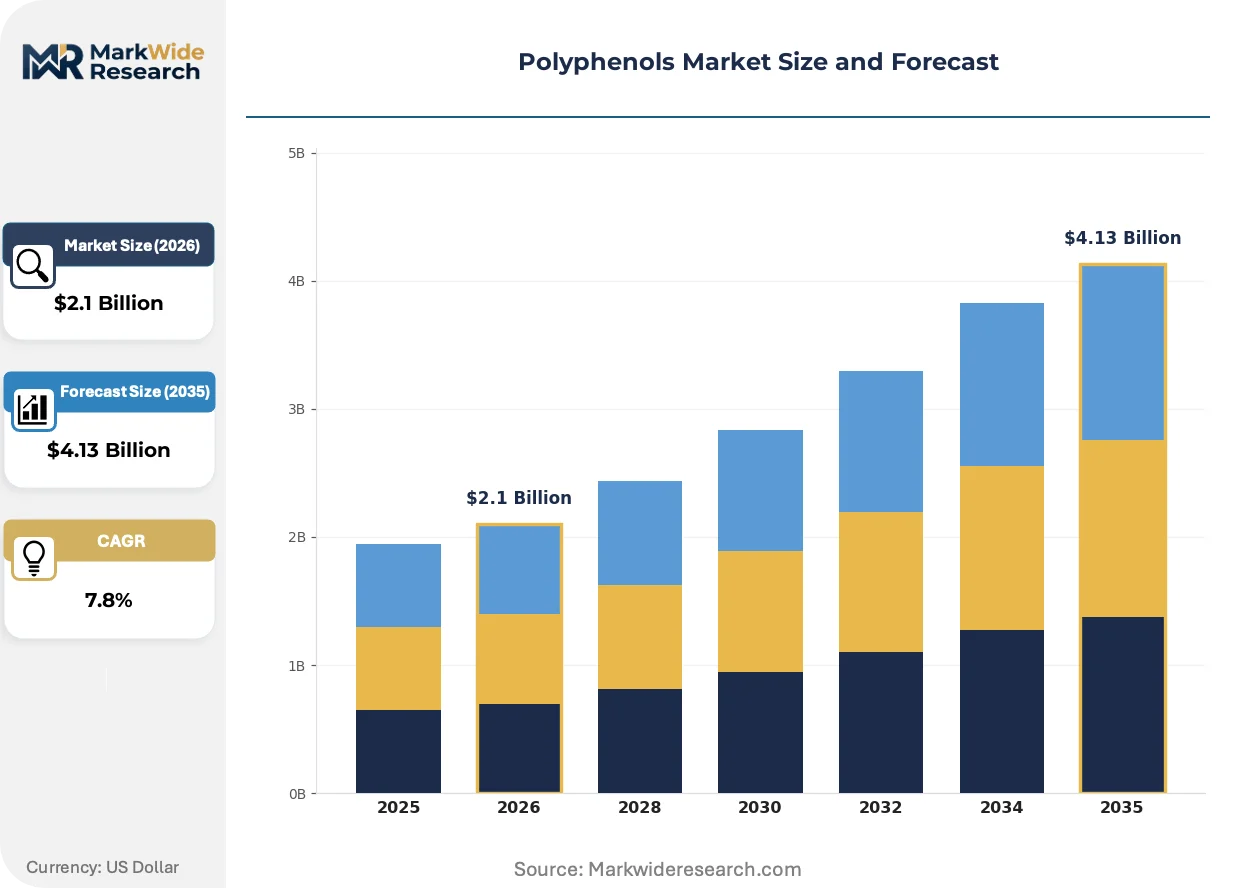
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavonoids, Phenolic Acids, Stilbenes, Lignans End User: Food & Beverage, Pharmaceuticals, Cosmetics, Dietary Supplements Source: Fruits, Vegetables, Tea, Red Wine Form: Powder, Liquid, Extract, Concentrate |
| Companies Covered | Archer Daniels Midland, Ajinomoto Co. Inc., Cargill Incorporated, Indena S.p.A., International Flavors and Fragrances, DSM-Firmenich, Barry Callebaut, Kemin Industries Inc., Givaudan SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyphenols Market Strategic Shifts & Innovations
Extraction technology evolution and regulatory substantiation requirements are compressing competitive differentiation timelines, forcing processors to demonstrate clinical validation earlier in product development cycles.
Supercritical CO2 extraction systems are migrating from niche pharmaceutical applications toward mainstream food-grade polyphenol production. Mid-sized botanical processors in Germany and Italy are adopting these systems to meet EFSA substantiation requirements for preservative-free antioxidant claims. The technology shift is enabling solvent residue elimination that unlocks clean-label positioning for functional beverage brands.
REACH registration requirements for novel extraction solvents are tightening purity documentation obligations across European processing facilities. ECHA's expanded substance evaluation program is extending compliance timelines for phenolic acid derivatives entering cosmetic and nutraceutical channels. German contract manufacturers are responding by pre-registering alternative solvent systems ahead of authorization deadlines.
Certification-driven procurement patterns are displacing commodity spot purchasing among dietary supplement brands. Third-party polyphenol content verification from ISO-accredited laboratories is becoming a mandatory supplier qualification step. This behavioral shift is most visible in United States direct-to-consumer channels, where brands use standardized extract documentation as primary marketing differentiation.
Polyphenols Market Segmentation
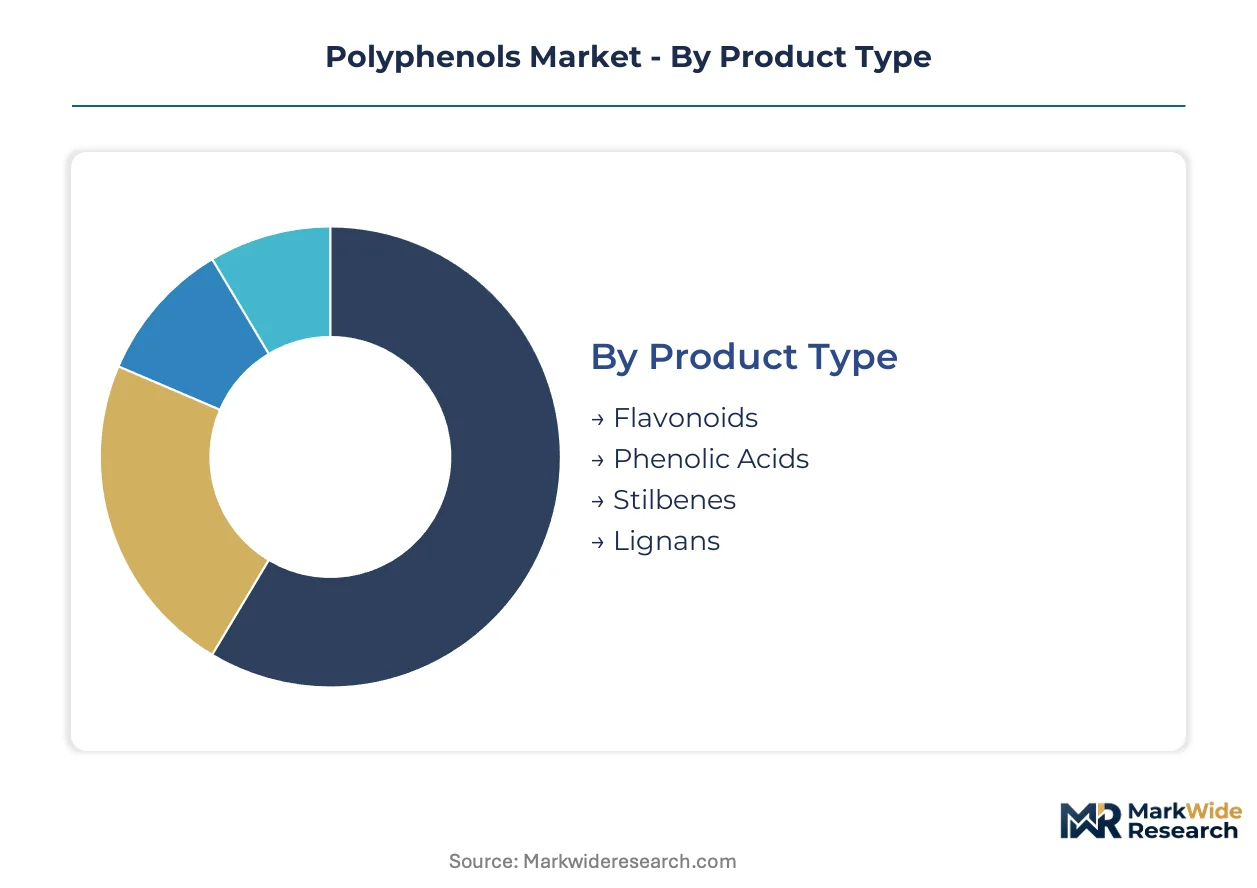
Polyphenol commercialization pathways diverge sharply across molecular classes and end-use specifications, with extraction technology choices and regulatory substantiation requirements fragmenting addressable margin pools. Formulators must match product type to application channel, as EFSA cardiovascular claims demand pharmaceutical-grade purity while functional beverage fortification tolerates broader compositional variance.
Product Type:
Mature flavonoid supply chains from tea and citrus processing anchor commercial volume, while emerging stilbene applications command concentrated margin premiums despite constrained raw material bases.
- Flavonoids:This structurally diverse subclass encompasses catechins from Camellia sinensis, anthocyanins from berries, and flavanones from citrus peel. Tea-derived catechin demand concentrates in Germany, where dedicated extraction facilities are expanding capacity to serve dietary supplement formulators seeking EFSA-compliant cardiovascular benefit substantiation.
- Phenolic Acids:Hydroxycinnamic and hydroxybenzoic acid derivatives from coffee, cereal grains, and olive processing exhibit broad antimicrobial and antioxidant functionality. Cargill's integrated agricultural supply chains secure raw material throughput for phenolic acid production targeting food preservation applications in North American processed meat channels.
- Stilbenes:Resveratrol and pterostilbene isolates from grape skin and Polygonum cuspidatum root face supply risk from narrow Mediterranean and Californian cultivation bases.
- Lignans:Secoisolariciresinol and matairesinol from flaxseed and sesame hulls serve niche nutraceutical applications with limited commercial scale.
Flavonoids retain volume leadership; stilbenes hold the steepest expansion curve.
End User:
Cost tier stratification separates pharmaceutical-grade specifications from commodity food additive positioning, with certification requirements escalating across the value chain.
- Dietary Supplements:Direct-to-consumer brands are building demand for standardized extracts with verified polyphenol content from ISO-accredited laboratories, bypassing traditional wholesale distribution markups. FDA New Dietary Ingredient notification requirements compress product development timelines for novel isolates entering U.S. channels.
- Food & Beverage:Functional beverage brands accelerate polyphenol fortification programs, tightening raw material throughput requirements and forcing extraction processors to expand dedicated catechin production lines ahead of demand curves.
- Pharmaceuticals:Therapeutic formulations targeting metabolic syndrome indications require supercritical CO2 purification to eliminate solvent residues.
- Cosmetics:Topical antioxidant claims drive demand for low-molecular-weight polyphenol fractions with enhanced dermal penetration.
Dietary Supplements command the highest margin tier; Food & Beverage generates the largest absolute volume throughput.
Source:
Geographic concentration of cultivation infrastructure determines supply security and price volatility profiles across botanical raw materials.
- Tea:Camellia sinensis leaf processing yields concentrated catechin fractions, with German ingredient processors building dedicated extraction capacity to reduce lead times for European formulators. China's NMPA and SAMR traditional medicine ingredient standards influence export specifications for institutional procurement channels.
- Fruits:Berry anthocyanin extraction faces seasonal supply constraints from temperate cultivation zones.
- Vegetables:Onion quercetin and artichoke cynarin represent secondary extraction streams from food processing waste streams.
- Red Wine:Grape skin resveratrol recovery from vinification byproducts concentrates supply risk in Mediterranean growing regions.
Tea dominates commercial extraction scale; fruits exhibit the most volatile supply profile.
Form:
Application-driven formulation requirements dictate physical state selection, with dissolution kinetics and shelf stability governing specification choices.
- Extract:Standardized polyphenol content from solvent-based or supercritical CO2 methods enables precise dosing in pharmaceutical and supplement applications. Third-party verification from ISO-accredited laboratories has become mandatory for supplier qualification in United States direct-to-consumer channels.
- Powder:Spray-dried or freeze-dried formats suit dry blend beverage premixes and capsule formulations.
- Liquid:Aqueous or glyceritic solutions serve ready-to-drink functional beverage fortification.
- Concentrate:High-potency fractions command premium positioning in therapeutic applications.
Extract forms retain specification leadership; concentrates capture the most rapid value expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's EFSA-aligned substantiation protocols are reshaping procurement standards across European formulators. China's NMPA-SAMR traditional medicine standards are creating dual certification requirements for tea-derived exports. The United States FDA notification burden is compressing product development timelines for novel isolates.
United States
Functional beverage brands are accelerating polyphenol fortification programs, tightening raw material throughput requirements. FDA New Dietary Ingredient notifications impose extended review timelines for novel isolates entering supplement channels. Extraction processors in California and the Pacific Northwest are expanding dedicated catechin production lines ahead of demand curves.
Germany
Ingredient processors are building dedicated extraction capacity for tea-derived catechins to serve European formulators. EFSA health claims verification demands randomized controlled trial evidence before permitting cardiovascular benefit statements. Industrial clusters in Bavaria and North Rhine-Westphalia are concentrating supply-side expertise and reducing lead times for dietary supplement manufacturers.
China
Domestic healthcare systems are driving institutional procurement for tea-derived polyphenols under traditional medicine frameworks. NMPA and SAMR coordinate export specifications that influence global supply standards. Processing facilities in the Yangtze River Delta are aligning production to meet dual certification requirements for both domestic and international markets.
Italy
Grape skin resveratrol recovery from vinification byproducts is concentrating supply risk in Mediterranean growing regions. REACH registration requirements for novel extraction solvents are tightening purity documentation obligations. Supercritical CO2 extraction systems in Piedmont and Lombardy are migrating from niche pharmaceutical applications toward mainstream food-grade production.
Switzerland
Pharmaceutical-grade purification capabilities are commanding premium offtake agreements from therapeutic formulators. Swissmedic standards for metabolic syndrome indications require solvent residue elimination through advanced extraction technologies. Basel-area processors are pre-registering alternative solvent systems ahead of ECHA authorization deadlines.
Polyphenols Market Key Industry Players
On the supply side, the industry is consolidating around three distinct capability tiers. Integrated agricultural conglomerates leverage captive raw material throughput for phenolic acid production. Specialized botanical extractors anchor positions through pharmaceutical-grade purification certifications. Mid-sized contract manufacturers are adopting asset-light extraction models to reduce competitive entry barriers. Dominant competitive moves include backward integration into agricultural supply chains and technology licensing for supercritical CO2 systems.
Within the integrated supply chain tier, Cargill Incorporated exemplifies scale-driven raw material security. Among European pharmaceutical-grade specialists, Indena S.p.A. occupies a position defined by premium-tier purification capabilities. At the specialized formulation end, Kemin Industries Inc. represents the dietary supplement channel archetype targeting standardized extract demand.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Ajinomoto Co. Inc. |
| Cargill Incorporated |
| Indena S.p.A. |
| International Flavors and Fragrances |
| DSM-Firmenich |
| Barry Callebaut |
| Kemin Industries Inc. |
| Givaudan SA |
| Others |
Cost & Logistics Intelligence
German catechin extraction capacity concentration anchors margin capture for pharmaceutical-grade flavonoid tiers, while commodity phenolic acid streams from North American agricultural processors face compression from spot-market oversupply. Certification requirements from EFSA and FDA notification protocols create pricing stratification that rewards verified supply chains with premium offtake agreements.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and commodity polyphenol streams. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA cardiovascular claim substantiation, ISO-accredited laboratory verification, and solvent residue thresholds. Cost compression in commodity flavonoid tiers is intensifying because tea and citrus processing infrastructure has matured, flooding spot markets. Dietary supplement brands in direct-to-consumer channels exhibit the least price sensitivity due to marketing premiumization, while food preservation buyers negotiate aggressively on volume contracts.
Supply Chain Analysis
Mid-sized contract manufacturers in Germany, Italy, and Switzerland hold the majority of supercritical CO2 extraction capacity for pharmaceutical-grade applications. Raw material throughput draws from Camellia sinensis cultivation in China, grape skin vinification byproducts in Mediterranean zones, and cereal grain processing streams in North America. Single-source vulnerability concentrates in tea-derived catechin supply from Yangtze River Delta processing clusters. Distribution runs through ingredient distributor networks serving dietary supplement formulators and direct procurement relationships with functional beverage brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyphenol commercialization is approaching a platform-economics inflection where EFSA-FDA dual certification interoperability unlocks premium positioning across Atlantic markets. Standardized extract verification protocols from ISO-accredited laboratories are becoming the interoperability layer that determines supplier inclusion.
For Market Incumbents: Insulate pharmaceutical-grade margin tiers by accelerating supercritical CO2 capacity additions in Bavaria and North Rhine-Westphalia before contract manufacturers replicate certification capabilities. Threat of backward integration by Cargill and DSM-Firmenich into captive catechin extraction compresses third-party processor viability. Priority lever rests on pre-registering alternative solvent systems ahead of ECHA REACH authorization deadlines to lock in clean-label positioning. For New Entrants and Emerging Players: China's domestic healthcare procurement under NMPA-SAMR traditional medicine frameworks represents the most penetrable white-space target, as export specification alignment remains incomplete for mid-sized processors. Direct-to-consumer supplement channels in the United States offer secondary entry through digital-native brand partnerships that bypass wholesale distribution markups. Go-to-market angle centers on third-party polyphenol content verification as mandatory supplier qualification leverage. For Investors and Strategic Acquirers: Capital is best deployed toward specialized botanical extractors with pharmaceutical-grade purification certifications and existing EFSA cardiovascular claim dossiers. Long-term viability over the coming decade hinges on clinical investment amortization across multiple jurisdiction approvals rather than single-market positioning. Signal to watch is FDA New Dietary Ingredient notification backlog clearance rates as inflection indicator for novel isolate commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | German processors meeting EFSA preservative-free antioxidant claims command premium offtake from functional beverage brands. |
| Backward Integration into Tea Cultivation | Cargill's integrated agricultural supply chains secure raw material throughput against catechin spot price volatility. |
| Dual Certification Alignment | NMPA-SAMR export specification compliance unlocks institutional procurement channels in China's domestic healthcare systems. |
| Direct-to-Consumer Channel Development | Digital-native supplement brands bypass wholesale markups through standardized extract verification from ISO-accredited laboratories. |
| Alternative Solvent Pre-Registration | REACH compliance ahead of ECHA authorization deadlines preserves clean-label positioning for European cosmetic and nutraceutical channels. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured interviews with extraction technicians, dietary supplement formulators, functional beverage R&D directors, and procurement leads at ingredient distributors. Secondary validation incorporated EFSA health claims register entries, FDA New Dietary Ingredient notification filings, NMPA traditional medicine ingredient standards, customs trade data for tea-derived polyphenol flows, and SEC disclosures from integrated agricultural conglomerates. Bottom-up capacity assessments across German and Italian processing facilities were triangulated against top-down demand modeling from end-use consumption patterns.
Calibration against historical capacity utilization rates and regulatory approval timelines informed the analytical framework across the projection horizon. Segmentation dimensions modeled encompass molecular class, end-use application channel, extraction technology type, certification grade tier, and geographic regulatory cluster. CAGRs were derived from weighted average growth contributions across these segments, with specific inputs including EFSA substantiation investment cycles, supercritical CO2 system adoption curves, and direct-to-consumer channel penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated agricultural conglomerates into captive extraction capacity would shift outcomes toward supply consolidation. Quarterly review of FDA notification backlog clearance, EFSA opinion publication velocity, and NMPA export specification amendments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Global Zeaxanthin Market
Food Components and Additives
Food Antioxidant Market
Food Components and Additives
Polyphenol Antioxidant Market
Food Components and Additives
Astaxanthin Market
Food Components and Additives
Food Texture Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Asia-Pacific Food Hydrocolloids Market
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
Edible Oil Co-Products and by-Products Market
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
South America Food Hydrocolloids Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Natural Fatty Acids Market