
 United Kingdom Protein Market | 2026-2036
United Kingdom Protein Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Protein Market Analytics
Supermarket private-label ranges is tilting toward functional protein products as British retailers expand dedicated health aisles. Arla Foods AmbA leverages its cooperative dairy network to dominate whey protein sourcing across the UK. Glanbia Plc competes through specialized sports nutrition ingredients, while Myprotein anchors direct-to-consumer subscription models that bypass traditional retail markup structures.
United Kingdom protein encompasses amino acid chains derived from animal, plant, and microbial sources, typically processed through enzymatic hydrolysis, membrane filtration, or extrusion to achieve specific nitrogen content and digestibility scores. These inputs serve primarily as nutritional fortifiers in consumer packaged goods, clinical formulations, and athletic performance products. Whey protein occupies the premium tier of the product type landscape due to superior leucine bioavailability and established consumer trust. Pea protein represents the fastest-expanding plant-based category as British food manufacturers reformulate away from soy allergens. The ready-to-drink form commands higher margin pools than powder equivalents, reflecting convenience premiums in urban commuting patterns.
The Food Standards Agency enforces novel food authorizations that delay new alternative protein launches, while retained EU REACH frameworks govern chemical safety in processing aids. British Retail Consortium standards further constrain supplier qualification, tightening market access for unaccredited overseas manufacturers. Stakeholders must monitor divergence between UK and EU regulatory frameworks as post-Brexit alignment decisions reshape ingredient approval timelines and cross-border formulation strategies.
Market Dynamics
Post-Brexit regulatory divergence between the UK and EU is fragmenting supply chains and forcing dual-track compliance investments. The Food Standards Agency's retained novel food frameworks now operate independently from EFSA, creating parallel approval bottlenecks for alternative protein entrants.
Growth Catalysts
- Clean-label reformulation mandates:Major British retailers are removing artificial additives from private-label ranges, driving demand for minimally processed whey and pea protein isolates that deliver functional performance without E-number declarations.
- England's urban fitness density:London and Manchester host concentrated CrossFit and boutique studio networks that normalize protein supplementation as daily nutrition rather than elite athletic equipment.
- NHS clinical nutrition procurement:Hospital trusts are expanding medical food contracts to address malnutrition in aging populations, opening institutional volume channels for high-digestibility protein hydrolysates.
Market Restraints
- Dairy input cost volatility:Whey protein concentrate pricing tracks volatile global skim milk powder markets, compressing margin predictability for British sports nutrition brands dependent on Arla's cooperative supply base.
- Novel food authorization timelines:The Food Standards Agency's retained EU procedures impose 18-month minimum review periods for precision-fermented and cultivated protein submissions, delaying commercialization.
- Soy allergen substitution ceiling:Pea protein's amino acid incompleteness limits its standalone use in complete nutrition products, constraining full displacement of soy isolates in infant formula applications.
Strategic Opportunities
- Scottish and Welsh retail expansion:Dedicated health aisles remain underdeveloped outside England's M25 corridor, offering first-mover positioning in Edinburgh, Glasgow, and Cardiff supermarket networks.
- Subscription direct-to-consumer models:Myprotein's recurring revenue infrastructure demonstrates bypass potential for traditional retail slotting fees and margin stacking.
- British Retail Consortium accreditation leverage:Overseas manufacturers lacking BRC certification face automatic exclusion from Tesco, Sainsbury's, and Asda supplier pools, creating defensive moats for accredited domestic processors.
Industry Challenges
- Dual-track regulatory compliance staffing:Exporters maintaining EU and UK market access must employ separate regulatory affairs teams to manage diverging novel food dossier requirements.
- Extrusion equipment retrofit cycles:Textured protein manufacturing for meat analogues demands capital-intensive twin-screw extruder upgrades that strain mid-tier processor balance sheets.
- Leachate testing protocol standardization:Inconsistent heavy metals and mycotoxin thresholds between British Retail Consortium specifications and retained EU methods create batch release friction for plant protein importers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Protein Market |
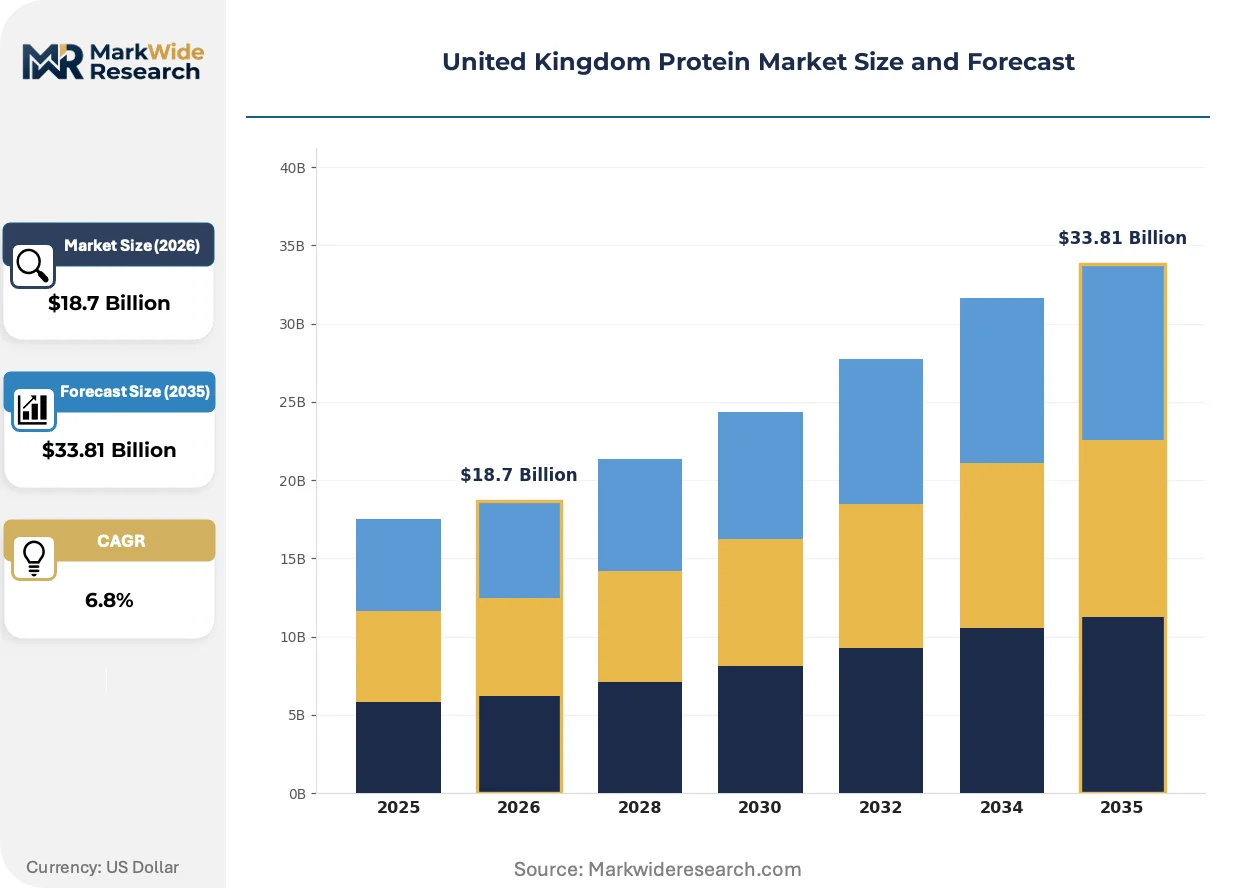
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Soy Protein, Pea Protein End User: Sports Nutrition, Dietary Supplements, Food & Beverage, Bakery Products Form: Powder, Bar, Ready-to-Drink, Liquid Application: Meal Replacement, Weight Management, Muscle Building, General Health |
| Companies Covered | Archer Daniels Midland Company, Ingredion Incorporated, Arla Foods AmbA, Myprotein, Roquette Frères, Glanbia Plc, Cargill Incorporated, Quorn Foods, Kerry Group Plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Protein Market Evolving Landscape
Precision fermentation is collapsing cost curves for recombinant protein production. Enzymatic hydrolysis advances are unlocking novel bioactive peptides. Regulatory divergence is fragmenting formulation strategies across the Channel.
Precision fermentation platforms utilizing modified yeast and fungal chassis are collapsing the capital intensity of recombinant protein manufacturing. British biotech startups are deploying this technology to produce lactoferrin and osteopontin previously extracted from bulk dairy streams. Food and beverage manufacturers in England are accelerating adoption timelines, with several pilot facilities operational in the Oxford-Cambridge arc.
The Food Standards Agency's divergence from EFSA novel food timelines is compressing approval strategy horizons for alternative protein developers. Retained EU procedures now operate with UK-specific risk assessment protocols that demand additional toxicology endpoints. Precision-fermented ingredient suppliers are responding by filing parallel dossiers, accepting duplicated expenditure to secure dual-market access.
British supermarket buyers are consolidating supplier relationships around vertically integrated processors capable of delivering finished ready-to-drink formulations rather than commodity isolates. This procurement concentration is marginalizing pure-play ingredient traders and rewarding Arla Foods AmbA and Glanbia Plc for their beverage co-manufacturing capabilities. The shift is most visible in Tesco's dedicated sports nutrition bays, where private-label RTD shelf space expanded substantially.
United Kingdom Protein Market Segmentation
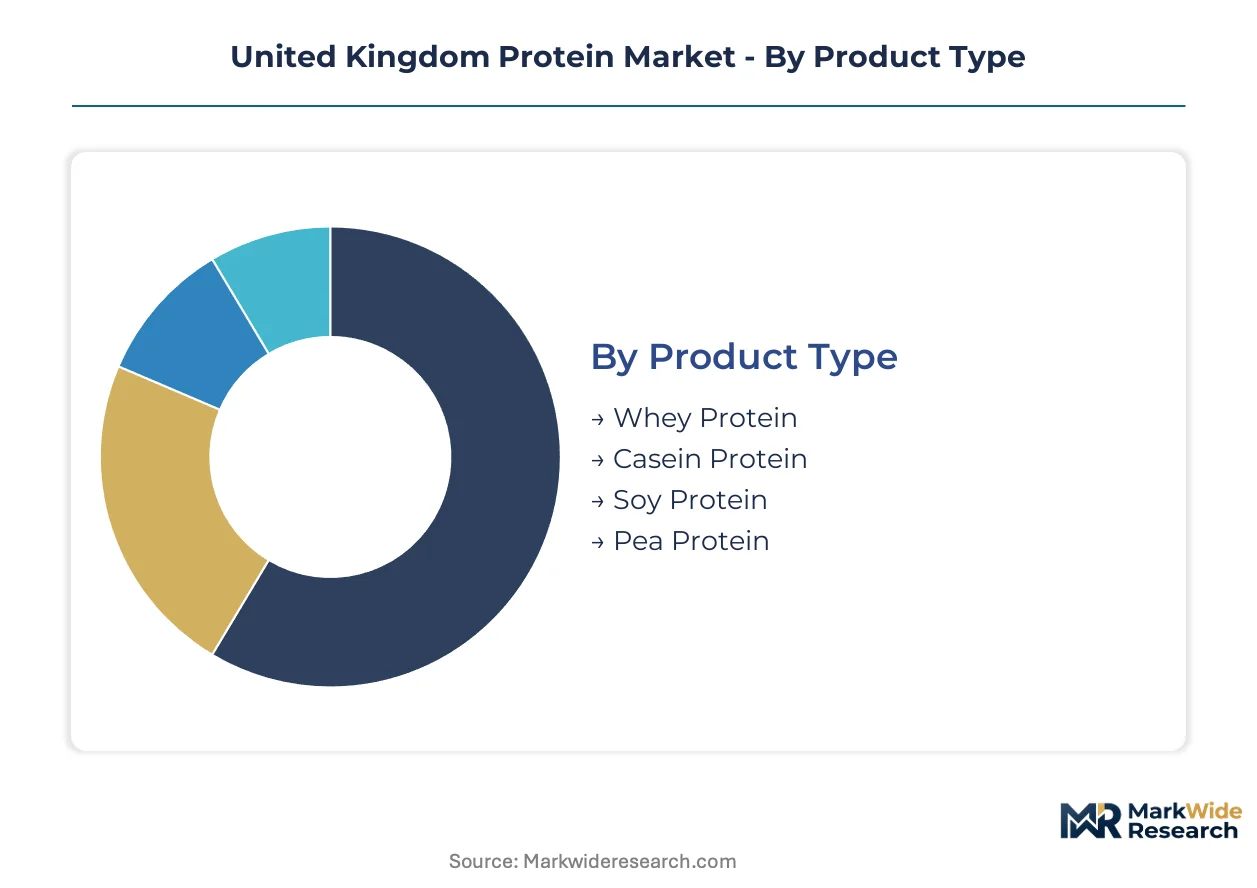
Segmentation in the United Kingdom protein market reveals how distinct user needs and channel economics fragment purchasing behavior. Manufacturers must align formulation investments with the technical specifications demanded by each category's dominant buyers.
Product Type:
Cost tiers within protein sourcing determine margin structures and supply chain partnerships across British manufacturing.
- Whey Protein:Derived from cheese production through membrane filtration, whey delivers superior leucine bioavailability and rapid absorption kinetics. Sports nutrition brands in London and Manchester command premium positioning based on these performance credentials. Arla Foods AmbA's cooperative network dominates domestic whey concentrate supply.
- Pea Protein:Yellow split pea isolates processed through wet fractionation offer hypoallergenic positioning for soy-avoidant consumers. British bakery and meat analogue manufacturers in England's urban corridors are accelerating reformulation around this segment as clean-label mandates intensify.
- Casein Protein:Micellar casein extracted through microfiltration provides sustained amino acid release for overnight recovery applications.
- Soy Protein:Defatted soy flour processed into isolates retains cost advantages in institutional nutrition, though allergen labeling constraints limit retail growth.
Whey protein commands the established base. The steepest expansion runs through pea protein.
End User:
Application intensity varies dramatically across customer types, with performance-oriented users tolerating higher per-gram pricing than mainstream consumers.
- Sports Nutrition:Dedicated athletes and fitness enthusiasts consume protein as training infrastructure rather than discretionary nutrition. CrossFit affiliates and boutique studios in Manchester normalize supplementation as daily ritual, driving powder and ready-to-drink volume through direct-to-consumer subscriptions.
- Food & Beverage:British manufacturers fortify plant-based milks, yogurts, and meat analogues with functional protein to achieve nutritional parity with animal-derived equivalents. Tesco and Sainsbury's private-label ranges are expanding dedicated health aisles that absorb these inputs.
- Dietary Supplements:Capsule and tablet formats target aging populations addressing sarcopenia through convenient dosing.
- Bakery Products:High-protein bread and snack formulations appeal to health-conscious commuters seeking satiety in grab-and-go formats.
Sports nutrition anchors volume concentration. Food and beverage applications are climbing the fastest as mainstream retail absorption accelerates.
Form:
Convenience premiums stratify pricing power across delivery formats, with portability determining urban channel suitability.
- Ready-to-Drink:Aseptically processed beverages in shelf-stable packaging command the highest margins per serving. British supermarket buyers are consolidating procurement around vertically integrated processors capable of delivering finished formulations rather than commodity isolates.
- Powder:Bulk canisters and pouches dominate value-oriented purchasing through subscription models that bypass traditional retail markup structures. Myprotein's recurring revenue infrastructure demonstrates the bypass potential for slotting fee avoidance.
- Bar:Extruded and cold-pressed formats compete for gym bag and desk drawer placement against confectionery alternatives.
- Liquid:Concentrated shots and mixers serve niche functional positioning in clinical and athletic recovery contexts.
Powder retains the volume base. Ready-to-drink formats are gaining share fastest through convenience premiums in urban commuting patterns.
Application:
Outcome specificity determines formulation complexity and regulatory scrutiny intensity across intended use cases.
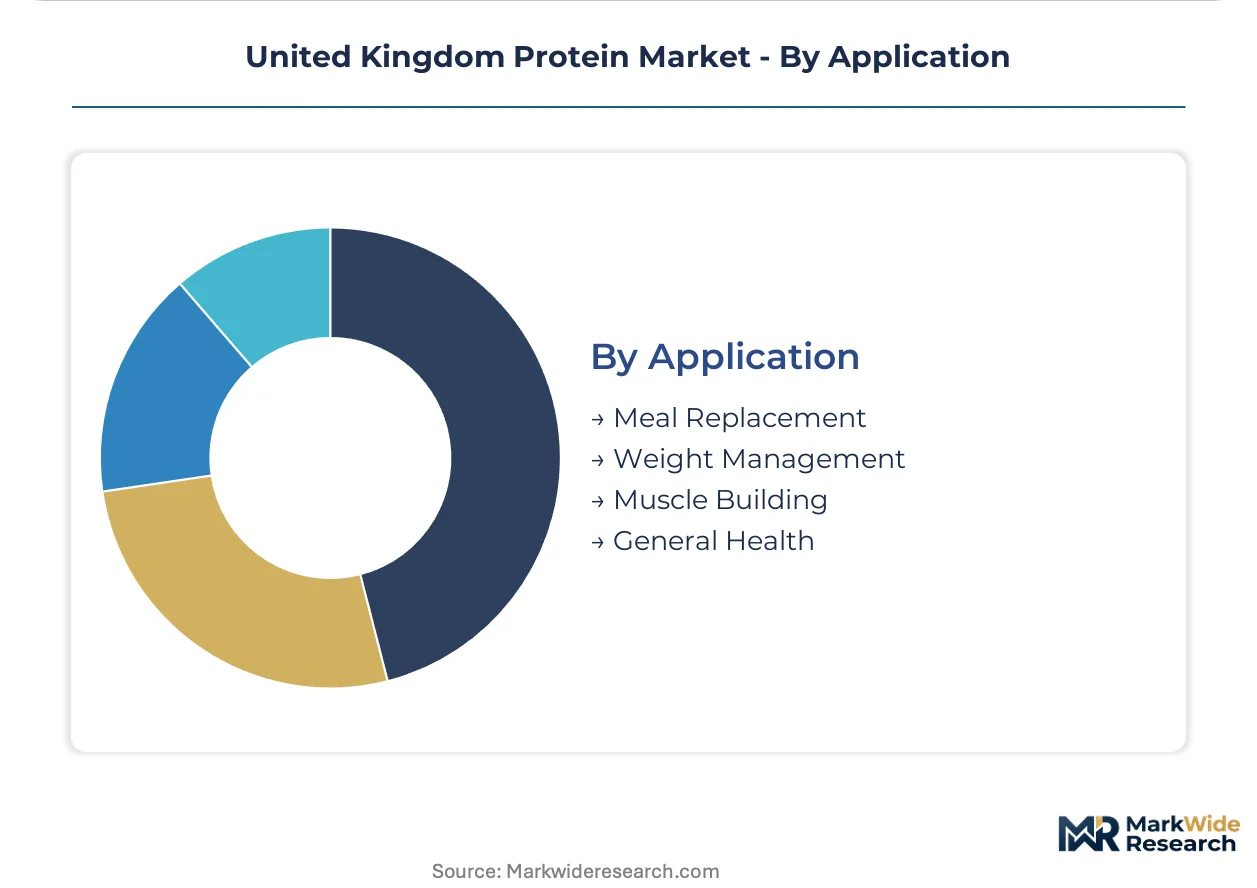
- Muscle Building:Leucine-enriched formulations targeting mTOR pathway activation support resistance training adaptations. NHS clinical nutrition procurement is expanding medical food contracts to address malnutrition in aging populations, opening institutional volume channels for high-digestibility protein hydrolysates.
- Meal Replacement:Complete amino acid profiles combined with micronutrient fortification satisfy regulatory requirements for sole-source nutrition claims. The Food Standards Agency enforces novel food authorizations that delay new alternative protein launches in this category.
- Weight Management:Satiety-promoting protein loads replace caloric density in reduced-energy formulations.
- General Health:Maintenance dosing for wellness-positioned consumers tolerates lower protein concentrations per serving.
Muscle building commands the performance premium tier. Meal replacement applications are expanding most quickly through clinical and convenience convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Tilbury's deep-water container terminals and direct rail links to the Midlands anchor protein ingredient distribution across England's manufacturing belt. This multimodal infrastructure underwrites the United Kingdom's position as a regional hub for sports nutrition and functional food processing.
London and the Southeast
CrossFit affiliates and boutique fitness studios in Shoreditch and Clapham normalize protein supplementation as daily nutrition. The Food Standards Agency's novel food authorization procedures delay precision-fermented protein launches in this corridor. Oxford-Cambridge biotech clusters host pilot facilities for recombinant lactoferrin production.
Midlands
Birmingham and Leicester food manufacturers accelerate pea protein reformulation for clean-label bakery applications. British Retail Consortium accreditation requirements constrain supplier pools for Tesco and Sainsbury's procurement teams. Derbyshire processing plants expand extrusion capacity for meat analogue textured proteins.
North England
Manchester's urban fitness density drives ready-to-drink protein volume through direct-to-consumer subscription models. Arla Foods AmbA's cooperative dairy network dominates whey concentrate supply to local sports nutrition brands. Liverpool port facilities handle bulk plant protein imports for regional formulation facilities.
Scotland
Edinburgh and Glasgow supermarkets underdevelop dedicated health aisles relative to England's M25 corridor. NHS Scotland clinical nutrition procurement expands medical food contracts for aging populations. Aberdeen's food technology incubators explore precision fermentation for dairy-identical proteins.
Wales
Cardiff retail networks offer first-mover positioning for functional protein product launches outside England's saturated corridors. Welsh Government food innovation grants support alternative protein startup formation. Newport distribution hubs leverage Bristol Channel port access for European ingredient sourcing.
United Kingdom Protein Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated processors capable of delivering finished formulations rather than commodity isolates. The vendor base stratifies into three tiers: multinational ingredient conglomerates with global sourcing networks, cooperative dairy processors with captive milk supply, and direct-to-consumer brands bypassing traditional retail markup structures. Dominant competitive moves include backward integration into dairy processing and subscription infrastructure buildout to secure recurring revenue streams.
Among multinational ingredient suppliers, Archer Daniels Midland Company and Cargill Incorporated occupy positions anchored by global oilseed and grain processing networks. Within the specialized nutrition tier, Glanbia Plc exemplifies the vertically integrated model combining whey processing with finished product co-manufacturing capabilities. Arla Foods AmbA represents cooperative structures leveraging member-farmer milk supply for protein isolate production. Myprotein sits within the direct-to-consumer archetype, demonstrating subscription-based bypass potential for traditional retail slotting fees.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Arla Foods AmbA |
| Myprotein |
| Roquette Frères |
| Glanbia Plc |
| Cargill Incorporated |
| Quorn Foods |
| Kerry Group Plc |
| Others |
Value Network & Pricing Analysis
Undercapacity in precision-fermented protein facilities across the Oxford-Cambridge arc is compressing supplier margins while amplifying pricing power for established dairy processors. This utilization squeeze forces alternative protein developers toward premium positioning strategies that absorb elevated unit costs, while Arla Foods AmbA's cooperative network maintains stable whey concentrate pricing through captive milk supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates British protein procurement. Premium tiers command positioning through British Retail Consortium certification and leucine bioavailability scores, while economy segments compete on bulk powder volume. Cost compression in the standard tier is intensifying because pea protein manufacturers battle whey incumbents for bakery reformulation contracts. NHS clinical nutrition buyers exhibit highest price sensitivity due to fixed-budget procurement frameworks, whereas CrossFit-affiliated direct-to-consumer channels tolerate elevated per-serving premiums.
Supply Chain Analysis
Tariff exposure between the European Union and United Kingdom dominates supply chain risk calculations for precision-fermented ingredient developers. Raw material sourcing draws from Irish dairy streams, Dutch pea protein fractionation facilities, and German extrusion equipment manufacturers. Single-source vulnerability concentrates in membrane filtration skids supplied by Danish engineering firms. Distribution runs through Port of Tilbury container terminals with direct rail links to Midlands formulation plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom protein market is recovering from post-Brexit regulatory adjustment costs as Food Standards Agency novel food backlogs clear and precision-fermented capacity comes online.
For Market Incumbents: Build certification moats through British Retail Consortium accreditation investments that automatically exclude unqualified overseas competitors from Tesco and Sainsbury's supplier pools. Secure backward integration into dairy processing to insulate margin structures from Arla's cooperative pricing power. Precision-fermented startups represent the emerging threat archetype requiring monitoring. For New Entrants and Emerging Players: Scottish and Welsh supermarket networks outside England's saturated M25 corridor represent the most penetrable entry point for functional protein product launches. NHS Scotland clinical nutrition procurement offers institutional volume anchoring for high-digestibility hydrolysate developers. Direct-to-consumer subscription infrastructure bypasses traditional retail slotting fee structures entirely. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision-fermented protein production as yeast chassis optimization reduces bioreactor scale requirements. Five-to-ten year viability favors vertically integrated processors with finished formulation capabilities over pure-play ingredient traders. Watch Food Standards Agency novel food authorization velocity as the key inflection signal for alternative protein commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| BRC Accreditation Investment | British Retail Consortium certification unlocks Tesco and Sainsbury's supplier pools automatically. |
| Precision Fermentation Scale-Up | Yeast chassis optimization in Oxford-Cambridge facilities collapses recombinant protein production costs. |
| Direct-to-Consumer Subscription Launch | Myprotein's recurring revenue model demonstrates bypass potential for retail markup avoidance. |
| Scottish Retail Network Expansion | Edinburgh and Glasgow health aisles remain underdeveloped relative to England's urban corridors. |
| NHS Clinical Nutrition Partnership | Hospital trust procurement opens institutional volume channels for high-digestibility hydrolysates. |
Research Methodology
Initial hypotheses were tested against primary input from sports nutrition brand managers, Food Standards Agency regulatory affairs leads, Tesco category buyers, and Arla Foods procurement directors and refined through secondary validation. Primary fieldwork combined structured interviews with supply chain planners at Midlands formulation plants and commercial directors at Oxford-Cambridge biotech incubators. Secondary sources encompassed British Retail Consortium technical standards, Food Standards Agency novel food registers, and HMRC trade data for whey and plant protein imports. Bottom-up volume modeling triangulated against top-down market sizing from retail audit databases.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled included product type tier, end-use application intensity, form factor convenience premium, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical volume movements adjusted for identified inflection drivers. Industry-specific forecast inputs incorporated NHS clinical nutrition procurement cycle timing and precision-fermentation facility commissioning schedules.
Practitioners should monitor Food Standards Agency novel food authorization velocity and dairy input commodity price movements for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Rice Starch Market
Ingredients
Asia-Pacific Lipids Market
Ingredients
Pea Flour Market
Ingredients
Industrial Sugar Market
Ingredients
Coconut Flour Market
Ingredients
Sesame Oil Market
Ingredients
Global Cocoa Ingredients Market
Ingredients
Drum to Hopper Blends Market
Ingredients
Black Seed Oil Market
Ingredients
Cold-Pressed Citrus Seed Oil Ingredients Market
Ingredients
Europe Plant Protein Ingredients Market
Ingredients
Textured Soy Protein Market
Ingredients
Vital Wheat Gluten Market
Ingredients
Brazil Corn Syrup Market
Ingredients
Global Distillers Grains Market
Ingredients
Wheat Starch Market