
 Commercial Flour Market | 2026-2036
Commercial Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Flour Market Outlook
Bakery channel procurement is rebalancing toward higher-protein and specialty blends as artisan bread consumption rises in urban centers. Ardent Mills leverages its North American milling network to sustain bulk supply contracts with industrial bakers. General Mills anchors its position through R&D intensity in whole-grain formulations. Cargill competes on global grain origination, securing cost-advantaged wheat streams for its flour operations.
Commercial flour denotes wheat and alternative grain powders milled to specific protein content, ash levels, and granulation for food manufacturing and foodservice use, with protein specifications typically ranging from 8% to 14% depending on end application. Its primary commercial purpose centers on providing consistent rheological properties for baked goods, noodles, and processed foods. All-purpose flour occupies the largest volume pool across retail and foodservice channels, while organic grade captures expanding margin pools as clean-label requirements harden across European and North American buyer specifications. Bread flour sustains the fastest growth trajectory in food manufacturing segments where high-gluten performance is non-negotiable.
USDA grading standards, FDA food safety modernization protocols, and EU REACH-adjacent food contact material rules collectively determine import eligibility and domestic product labeling across major supply corridors. China's SAMR enforces GB standards on flour fortification and additive limits, shaping reformulation requirements for exporters. Stakeholders must monitor diverging fortification mandates between jurisdictions and calibrate sourcing strategies accordingly.
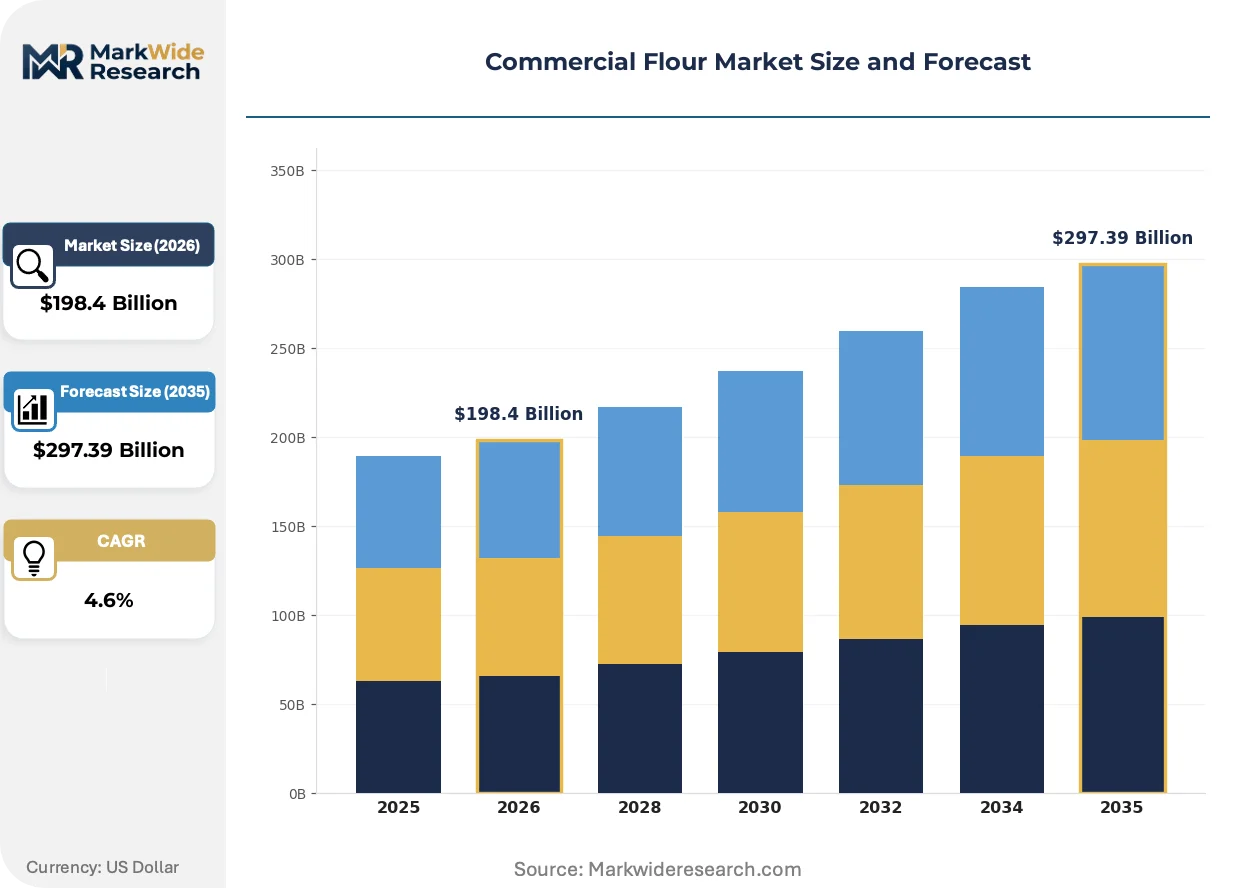
Market Dynamics
Protein specification divergence between artisan bakeries and industrial food manufacturers is fragmenting procurement contracts and forcing millers to maintain parallel production lines with distinct ash and gluten profiles.
Growth Catalysts
- India's PLI scheme:Food processing infrastructure subsidies under the Production Linked Incentive scheme are expanding domestic milling capacity and pulling imported wheat into specialty grade conversion.
- EFSA clean-label mandates:European additive disclosure requirements are accelerating reformulation toward enzyme-treated flours that reduce chemical additive dependence in bakery applications.
- Urban artisan bakery clusters:High-protein bread flour procurement from independent bakeries in São Paulo, Mexico City, and Lagos is creating premium volume pools outside industrial channels.
Market Restraints
- Black Sea supply concentration:Wheat origination dependence on Ukrainian and Russian export corridors exposes millers to port closure risk and freight rate volatility.
- FDA FSMA compliance costs:Food Safety Modernization Act preventive control requirements impose capital-intensive facility upgrades on mid-scale regional millers.
- Alternative grain substitution:Cassava and rice flour adoption in gluten-free manufacturing segments is compressing addressable volume for conventional wheat processors.
Strategic Opportunities
- Indonesia's underpenetrated specialty segment:Noodle manufacturers in Java and Sumatra are transitioning from commodity flour to customized protein blends for texture differentiation.
- Carbon accounting integration:EU Green Deal farm-to-fork traceability requirements are creating first-mover advantage for millers with verified Scope 3 emissions data.
- Direct-to-bakery distribution:Bypassing traditional distributor networks through proprietary delivery fleets is capturing margin from fragmented urban bakery clusters in tier-2 Indian cities.
Industry Challenges
- Milling automation skill gaps:PLC programming and near-infrared calibration expertise shortages are delaying smart mill deployment timelines.
- Organic certification backlogs:USDA National Organic Program inspector availability constraints are extending certification timelines by eight to fourteen months.
- Legacy ERP integration:Batch tracking systems from the 1990s require costly middleware development to connect with modern supply chain visibility platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Flour Market |
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $297.39 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Purpose Flour, Whole Wheat Flour, Bread Flour, Cake Flour End User: Bakeries, Restaurants, Home Cooks, Food Manufacturers Grade: Standard Grade, Premium Grade, Organic Grade, Specialty Grade Packaging Type: Bags, Bulk Containers, Boxes, Sachets |
| Companies Covered | Ardent Mills, Archer Daniels Midland, General Mills, Cargill, Grain Craft, GoodMills Group, Ingredion, Bunge Global, Associated British Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Flour Market Strategic Shifts
Digital quality control systems and enzyme engineering are compressing the gap between artisan performance characteristics and industrial production economics. These shifts are redrawing competitive boundaries between commodity and specialty flour tiers.
Near-infrared spectroscopy coupled with machine learning algorithms is expanding into real-time protein and moisture adjustment during the milling process. Industrial bakeries in Germany and the United States are adopting these systems at replacement cycle points. The technology is expanding into mid-scale regional millers who previously lacked capital for laboratory-grade quality control infrastructure.
China's SAMR enforcement of GB standards on flour fortification mandates is restructuring import eligibility for non-domestic millers. The regulations require iron, zinc, and folic acid addition thresholds that exceed many origin-country baseline formulations. Australian and Canadian exporters are reformulating export-grade products specifically for Chinese market access.
Bakery procurement teams are consolidating supplier relationships from twelve to four annual contracts to secure volume commitments and technical service access. This concentration is displacing spot-market purchasing in the food manufacturing segment. The pattern is most visible in Mexico and Turkey where industrial bakers are vertically integrating into milling through equity partnerships rather than arm's-length supply agreements.
Commercial Flour Market Segmentation
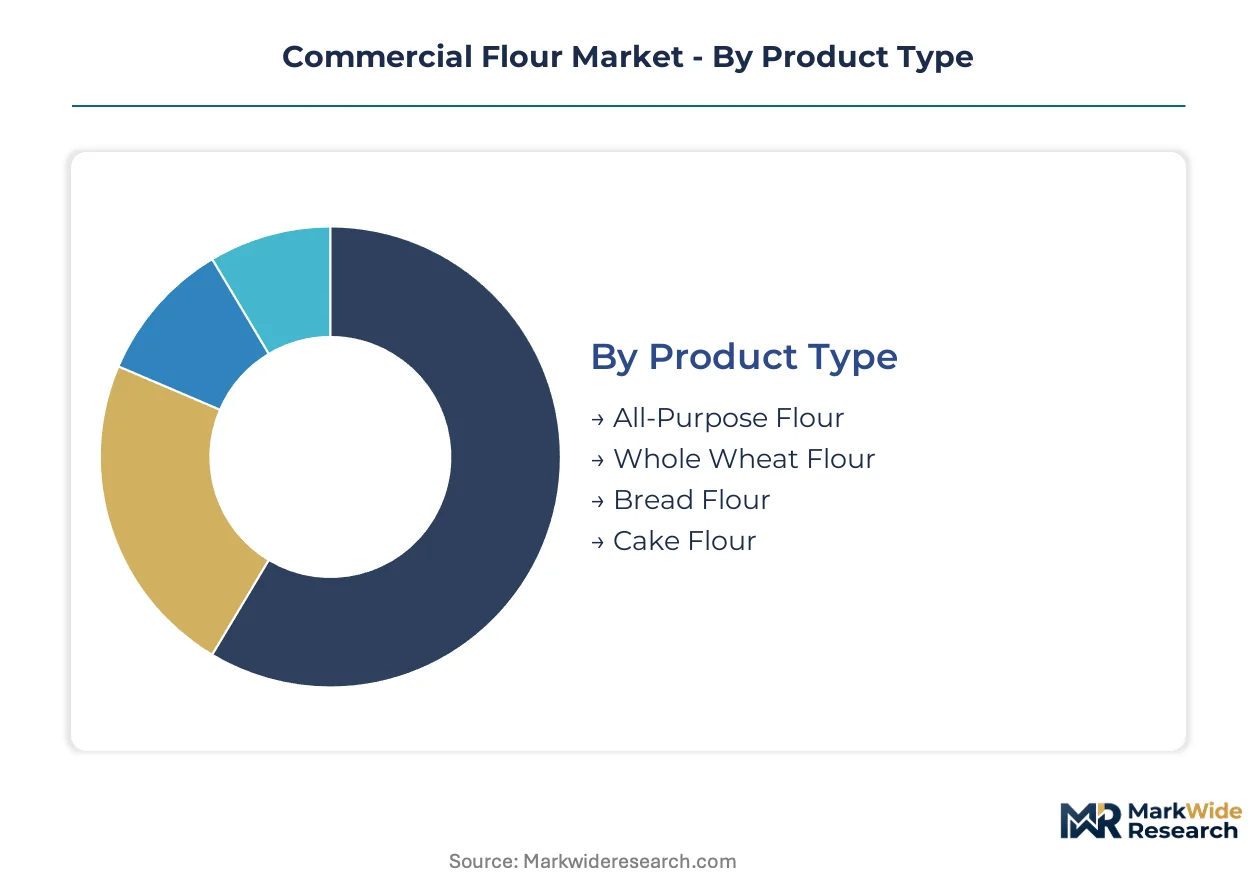
Protein specification and ash content requirements fragment procurement decisions across end-use channels. Millers must align production lines with distinct rheological profiles demanded by artisan bakers versus industrial food manufacturers.
Product Type:
Application-specific gluten performance drives product selection, with protein content ranging from 8% to 14% depending on end-use requirements.
- All-Purpose Flour:Versatile mid-protein blend (10-12%) suited for general baking and food manufacturing. Volume concentrates in North American retail and foodservice channels where formulation flexibility reduces inventory complexity.
- Bread Flour:High-gluten formulation (12-14%) engineered for yeast-raised products requiring strong protein networks. Demand accelerates in urban artisan bakery clusters across São Paulo, Mexico City, and Lagos where crust structure and crumb elasticity command premium positioning.
- Whole Wheat Flour:Milled with bran and germ intact, delivering higher fiber content and denser texture profiles for health-positioned products.
- Cake Flour:Low-protein, chlorinated or heat-treated soft wheat with fine granulation for tender crumb structure in high-ratio cakes.
All-purpose flour leads on scale; bread flour leads on momentum.
End User:
Procurement scale and technical service requirements separate volume buyers from fragmented specialty purchasers.
- Bakeries:Artisan and industrial baking operations requiring consistent protein specifications and technical milling support. Procurement in tier-2 Indian cities is shifting toward direct mill relationships to bypass distributor markups.
- Food Manufacturers:Large-scale industrial processors with annual contract structures and integrated supply chain visibility requirements. EFSA clean-label mandates are accelerating enzyme-treated flour adoption in German and French manufacturing facilities.
- Restaurants:Foodservice operators purchasing through broadline distributors with limited specification control.
- Home Cooks:Retail-packaged consumers driving organic grade expansion through supermarket channels.
Food manufacturers dominate procurement volume; bakeries command the steepest expansion trajectory.
Grade:
Certification tiers align with buyer willingness to pay for traceability and additive-free positioning.
- Organic Grade:USDA National Organic Program or equivalent certified production with prohibited synthetic inputs. Certification backlogs extending eight to fourteen months are constraining supply expansion in North American markets.
- Specialty Grade:Custom protein blends, heritage wheat varieties, or region-specific origin designations. Indonesia's noodle manufacturers in Java and Sumatra are transitioning to customized protein blends for texture differentiation.
- Premium Grade:Elevated quality specifications above standard commercial thresholds without full organic certification.
- Standard Grade:Commodity-tier production meeting baseline regulatory requirements for cost-sensitive applications.
Standard grade anchors volume; organic grade captures margin expansion.
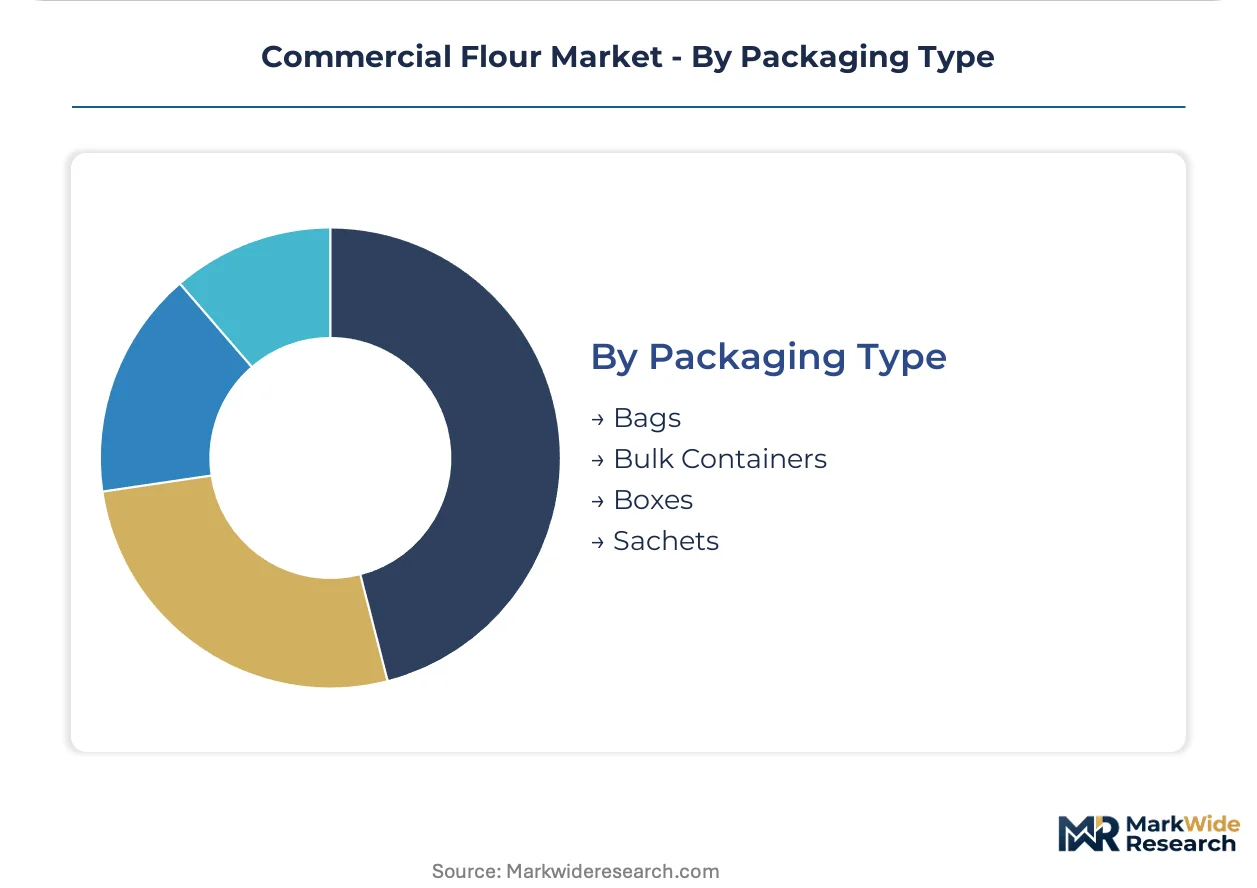
Packaging Type:
Distribution economics and shelf-life requirements determine format selection across channel tiers.
- Bulk Containers:Tanker or tote-based delivery for high-volume industrial users with dedicated handling infrastructure. EU Green Deal farm-to-fork traceability requirements are creating first-mover advantage for bulk suppliers with verified Scope 3 emissions data.
- Bags:Multi-wall paper or woven polypropylene for mid-scale bakery and foodservice procurement.
- Boxes:Corrugated containment for retail and foodservice distribution requiring stacking strength.
- Sachets:Single-serve portion control for hospitality and institutional channels.
Bulk containers dominate industrial procurement; bags sustain the broadest channel coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme-linked milling clusters anchor the fastest-expanding procurement corridors for specialty flour grades. Regulatory divergence between China's SAMR fortification mandates and EU EFSA clean-label rules fragments export formulation requirements across major supply corridors.
United States
Industrial bakeries in Chicago and Dallas-Fort Worth drive bulk procurement of high-protein bread flour for scaled production. FDA FSMA preventive control protocols impose facility upgrade costs on mid-scale regional millers. The Midwest grain belt sustains cost-advantaged wheat origination for domestic milling operations.
China
Noodle manufacturers in the Yangtze River Delta and Pearl River Delta intensify demand for customized protein blends with specific texture profiles. SAMR enforcement of GB fortification standards mandates iron, zinc, and folic acid thresholds exceeding many origin-country baselines. Australian and Canadian exporters reformulate export-grade products specifically for Chinese market access compliance.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia accelerate enzyme-treated flour adoption under EFSA clean-label mandates. EU Green Deal farm-to-fork traceability requirements create first-mover advantage for millers with verified Scope 3 emissions data. Near-infrared spectroscopy systems expand into mid-scale regional milling operations at replacement cycle points.
Brazil
Artisan bakery clusters in São Paulo command premium positioning for high-gluten bread flour with specific crust structure requirements. ANVISA food safety protocols shape import eligibility for specialty grade products. Urban procurement in Rio de Janeiro and Belo Horizonte shifts toward direct mill relationships to bypass distributor markups.
Indonesia
Noodle manufacturers in Java and Sumatra transition from commodity flour to customized protein blends for texture differentiation. The country's national food regulator enforces fortification and additive limits that reshape reformulation requirements for importers. Surabaya and Bandung industrial zones concentrate mid-scale milling capacity expansion.
Commercial Flour Market Competitive Environment
Capacity expansion dominates the current landscape as millers deploy parallel production lines for distinct protein specifications. The vendor base separates into integrated grain-trading conglomerates, regional milling specialists, and artisan-grade niche operators. Three archetypes define competitive positioning: North American network-scale millers with bulk supply contracts, European clean-label specialists with enzyme engineering capabilities, and Asian market-focused players with fortification compliance expertise. M&A activity and geographic expansion represent the dominant competitive moves as participants seek origination security and regulatory-aligned production assets.
Within the network-scale archetype, Ardent Mills leverages its North American milling infrastructure to anchor bulk supply relationships with industrial bakers. General Mills occupies a position exemplifying R&D intensity in whole-grain formulation development. Cargill represents the grain-origination-integrated model, securing cost-advantaged wheat streams for flour operations. These three entities collectively illustrate the competitive tension between commodity scale and specialty grade premium capture.
| Leading Market Players |
|---|
| Ardent Mills |
| Archer Daniels Midland |
| General Mills |
| Cargill |
| Grain Craft |
| GoodMills Group |
| Ingredion |
| Bunge Global |
| Associated British Foods |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal farm-to-fork traceability requirements gate qualified supply access and premium-tier pricing eligibility for commercial flour millers seeking carbon-verified positioning in European procurement channels. Buyers with Scope 3 emissions data command contract premiums while uncertified suppliers face exclusion from ESG-mandated sourcing programs.
Pricing Analysis
Distributor margin compression defines the channel economics for standard-grade flour, while direct-to-bakery relationships in tier-2 Indian cities bypass traditional markups entirely. Three-tier pricing structure across organic, specialty, and standard certification levels reflects protein specification and fortification compliance costs. Pricing pressure stems from Black Sea wheat origination volatility and freight rate uncertainty. Industrial food manufacturers exhibit highest price sensitivity due to annual contract volume commitments, while artisan bakeries in São Paulo and Lagos absorb premiums for customized gluten profiles.
Supply Chain Analysis
Freight cost volatility from Ukrainian and Russian export corridors disrupts wheat origination economics for millers dependent on Black Sea grain streams. Supply concentration centers on Australia, Canada, and the Black Sea region for high-protein wheat varieties. Raw material dependencies include specific protein-grade wheat cultivars, enzyme treatment inputs, and fortification premixes for iron and folic acid compliance. Single-source vulnerability from port closure risk in Odessa and Novorossiysk threatens contract fulfillment. Distribution runs through bulk tanker networks for industrial users, regional bag distributors for mid-scale bakeries, and direct fleet delivery for urban artisan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial flour functions as a regulatory compounder where China's SAMR fortification mandates and EU EFSA clean-label rules simultaneously expand compliance-driven demand and fragment formulation requirements across export corridors.
For Market Incumbents: Deploy parallel production line architecture to service divergent protein specifications without cross-contamination between artisan and industrial grades. Cargill and Ardent Mills should deepen backward integration into Australian and Canadian grain origination to secure cost-advantaged wheat streams insulated from Black Sea disruption. Certification investment in USDA National Organic Program standards captures margin expansion as inspector backlogs constrain competitor supply expansion. For New Entrants and Emerging Players: Begin with Indonesia's underpenetrated specialty segment where Java and Sumatra noodle manufacturers seek customized protein blends for texture differentiation. Direct-to-bakery distribution models in tier-2 Indian cities offer white-space access outside established distributor networks. Technical service partnerships with enzyme engineering specialists provide differentiation without capital-intensive milling infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for regional milling specialists with fortification compliance expertise because regulatory divergence between China's GB standards and EU additive rules fragments efficient scale. Target mid-scale millers with legacy ERP systems ripe for middleware integration and supply chain visibility upgrades. Watch for carbon accounting platform adoption rates as the inflection signal for premium-tier contract access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Secures cost-advantaged wheat streams from Australia and Canada for ESG-compliant supply. |
| Enzyme Engineering Partnership | Enables EFSA clean-label reformulation without chemical additive dependence in bakery applications. |
| Direct-to-Bakery Distribution Buildout | Captures margin from fragmented urban clusters in tier-2 Indian cities bypassing distributors. |
| Carbon Accounting Platform Deployment | Creates first-mover advantage for EU Green Deal farm-to-fork traceability contract eligibility. |
| Parallel Production Line Investment | Services divergent protein specifications between artisan bakeries and industrial manufacturers. |
Study Parameters
Multiple input streams — milling operations executives, bakery procurement managers, grain trading specialists, and food safety compliance officers — were reconciled with secondary validation from USDA trade data, EU EFSA additive disclosure filings, and Chinese SAMR GB standard documentation. Bottom-up volume estimates from regional milling capacity and top-down demand calibration from end-use consumption patterns were triangulated to establish market sizing.
Data-stream reconciliation across product type, protein specification tier, end-use channel, and regional regulatory cluster informed the analytical framework over the projection horizon. CAGRs were derived from trend extrapolation of urbanization-linked bakery expansion and PLI scheme-linked food processing investment intensity. Forecast inputs incorporated enzyme adoption rates in European manufacturing and fortification mandate enforcement trajectories in import markets.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting Black Sea wheat corridors and unforeseen regulatory harmonization between divergent fortification regimes. Forecasts reflect documented assumptions about protein specification fragmentation and clean-label transition pacing. Stakeholders should weight assumptions against their own operating context and origination security requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Mediterranean Women’s Cycle Support Ingredient Systems Market
Ingredients
Tryptose Market
Ingredients
North America Cheese Powder Market
Ingredients
Cacao Bean Market
Ingredients
North America Cocoa Products Market
Ingredients
Soy Derivatives Market
Ingredients
Mustard Oil Market
Ingredients
Asia Pacific Feed Yeast Market
Ingredients
Hemp Seed Peptide Market
Ingredients
Asia-Pacific Gelatin Market
Ingredients
Non-GMO Soya Market
Ingredients
Apple Extract Market
Ingredients
Roll-Dried Starch Market
Ingredients
Notoginseng Root Extract Market
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Bakery Ingredients Market