
 Fermented Plant Extracts Market | 2026-2036
Fermented Plant Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Plant Extracts Market Foresight
Pharmaceutical-grade fermentation specifications are redrawing competitive boundaries in the Fermented Plant Extracts Market. Chr. Hansen leverages its microbial strain library to dominate high-purity enzyme production for nutraceutical clients. Kerry Group anchors European supply through backward integration into fermentation capacity and botanical sourcing networks. Xian Sost Biological Science & Technology specializes in powder-form extracts, competing on cost-adjusted yields for amino acid concentrates.
Fermented plant extracts are biologically active substances produced through controlled microbial fermentation of botanical raw materials, typically yielding standardized metabolite profiles with enhanced bioavailability compared to conventional solvent extraction. The process employs specific bacterial or fungal strains at defined temperature, pH, and oxygen parameters to convert plant polyphenols, saponins, or alkaloids into more absorbable derivatives for nutritional, cosmetic, or therapeutic applications. Probiotics and enzymes represent the most established product categories, with margin pools shifting toward enzymes as manufacturers demand catalytic specificity for clean-label formulations. Nutritional supplements lead application volume, though cosmetics is the fastest-growing segment as fermented actives displace synthetic preservatives in Korean and French skincare formulations.
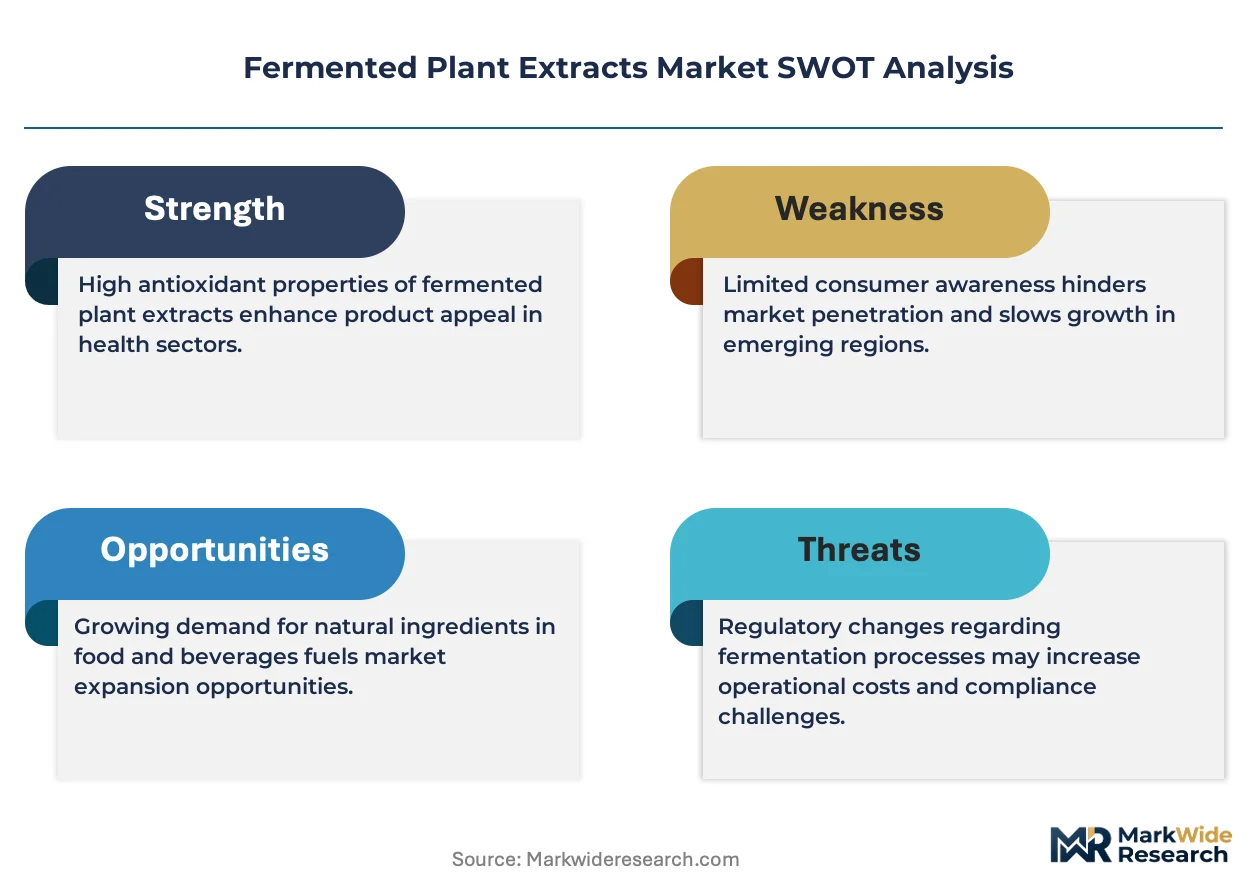
EFSA Novel Food guidance and EU REACH compliance for fermentation-derived substances are elevating entry barriers, forcing smaller suppliers to invest in toxicology dossiers or exit the European market. The US FDA GRAS self-affirmation pathway and China's NMPA health food registration requirements create divergent compliance architectures that multinational suppliers must navigate simultaneously. Stakeholders should monitor regulatory harmonization efforts between EFSA and FDA on postbiotic definitions, as classification decisions will determine whether fermented extracts face drug-like scrutiny or retain food-supplement status.
Market Dynamics
Pharmaceutical-grade fermentation specifications are redrawing competitive boundaries as nutraceutical manufacturers demand catalytic specificity for clean-label formulations. This structural force concentrates margin pools around enzyme production while compressing commodity probiotic margins.
Growth Catalysts
- EFSA Novel Food pathways:Tightening substantiation requirements for bioactive compounds are filtering out low-substantiation suppliers, concentrating demand among dossier-ready producers in Germany.
- Cosmetic actives displacement:Fermented botanicals are displacing synthetic preservatives in Korean and French skincare formulations as clean-label mandates intensify.
- Immune-support formulation expansion:Nutraceutical companies are expanding fermented botanical use in immune-support products, pulling volume from solvent-extracted alternatives.
Market Restraints
- EFSA toxicology dossier costs:REACH compliance and Novel Food guidance elevate entry barriers, forcing smaller suppliers to exit the European market entirely.
- Strain library concentration:High-purity enzyme production depends on proprietary microbial strain collections held by a narrow supplier base in Denmark and Germany.
- Dual compliance architecture:Simultaneous navigation of US FDA GRAS self-affirmation and China's NMPA health food registration creates redundant regulatory expenditure.
Strategic Opportunities
- Postbiotic classification harmonization:EFSA-FDA alignment on postbiotic definitions would clarify whether fermented extracts face drug-like scrutiny or retain food-supplement status.
- Powder-form amino acid concentrates:Cost-adjusted yield competition in powder extracts creates white space for mid-scale fermenters serving sports nutrition contract manufacturers.
- Frankfurt-Rhine-Main biotech corridor:Ingredient innovators and contract fermenters cluster here, enabling co-location synergies for just-in-time botanical processing.
Industry Challenges
- Fermentation parameter control:Maintaining defined temperature, pH, and oxygen parameters across batch scales requires specialized bioprocess engineers in short supply.
- Metabolite standardization:Achieving consistent bioactive profiles between fermentation runs demands analytical chemistry capabilities that strain mid-tier quality budgets.
- Legacy extraction integration:Manufacturers with captive solvent-extraction infrastructure face capital reconfiguration friction when shifting to microbial fermentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Plant Extracts Market |
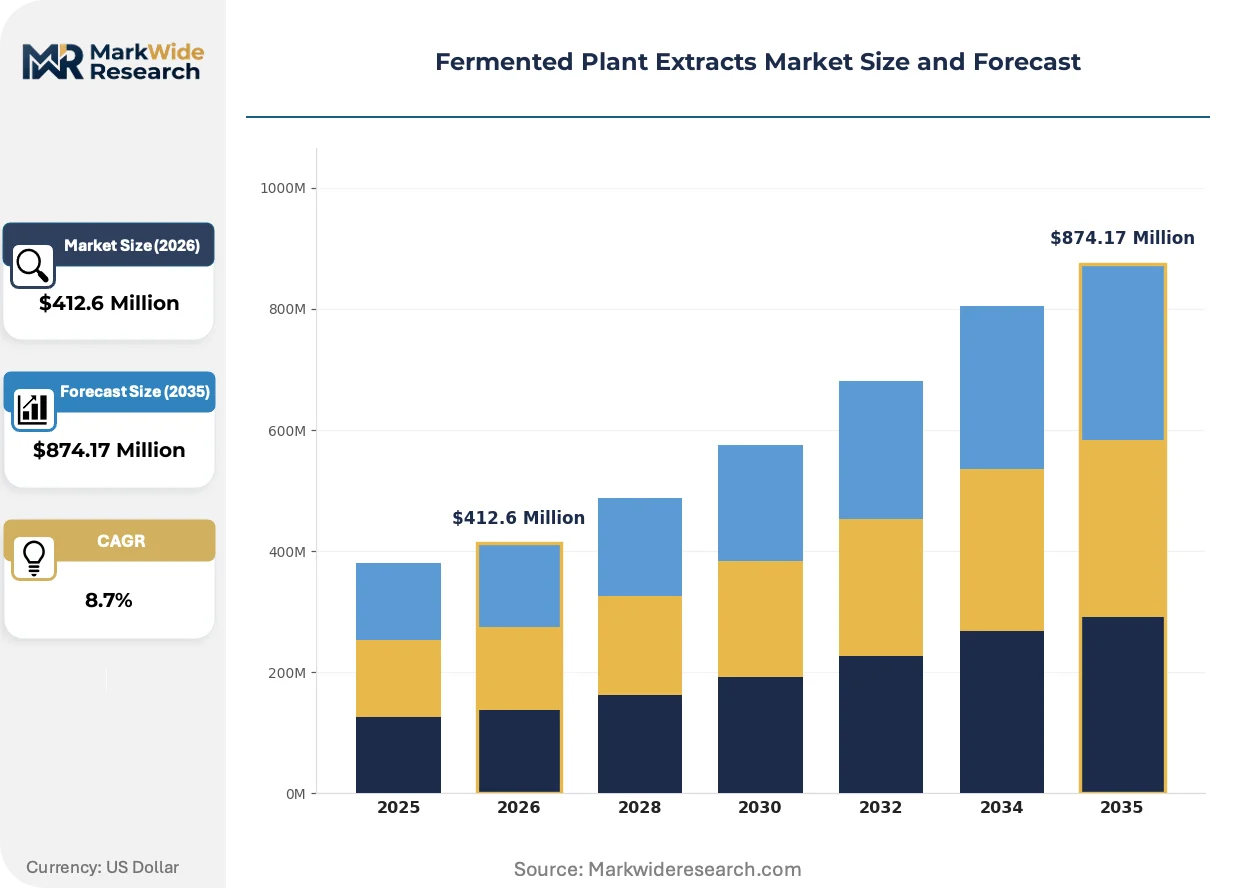
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Enzymes, Amino Acids, Antioxidants Application: Nutritional Supplements, Cosmetics, Food & Beverages, Animal Feed Form: Liquid, Powder, Capsule, Granule End User: Retail Consumers, Beverage Manufacturers, Nutraceutical Companies, Herbal Product Firms |
| Companies Covered | Xian Sost Biological Science & Technology, Chr. Hansen, ID Bio, Kerry Group, Novozymes, Phytoneering Extract Solutions GmbH, Ecuadorian Rainforest, Honson Pharmatech Group, Xi'an Hao-Xuan Bio-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Plant Extracts Market Shifts & Advancements
Precision fermentation is fragmenting traditional extraction economics as biotech-enabled production displaces agricultural commodity dependence. This shift compresses batch-to-batch variability while enabling novel metabolite profiles unreachable through conventional processing.
Continuous bioprocessing is fragmenting the batch-fermentation paradigm that has dominated botanical extraction for decades. Contract manufacturers in Germany and Denmark are adopting perfusion systems that maintain cells in exponential growth phase indefinitely. This technology is compressing capital intensity per unit output while enabling real-time metabolite monitoring.
EU REACH compliance for fermentation-derived substances is tightening substance identity requirements for bioactive compounds entering the European market. The regulation now demands full metabolite characterization that solvent-extracted equivalents rarely provide. Small and mid-scale suppliers are responding by partnering with Frankfurt-based toxicology consultancies to share dossier development costs.
Buyer concentration among multinational nutraceutical formulators is compressing supplier negotiation leverage and elongating payment cycles. Direct sourcing contracts between finished goods manufacturers and fermentation specialists are displacing traditional ingredient distributor networks. This pattern is most visible in Germany, where Kerry Group and Chr. Hansen have established captive supply relationships with immune-support brands.
Fermented Plant Extracts Market Segmentation
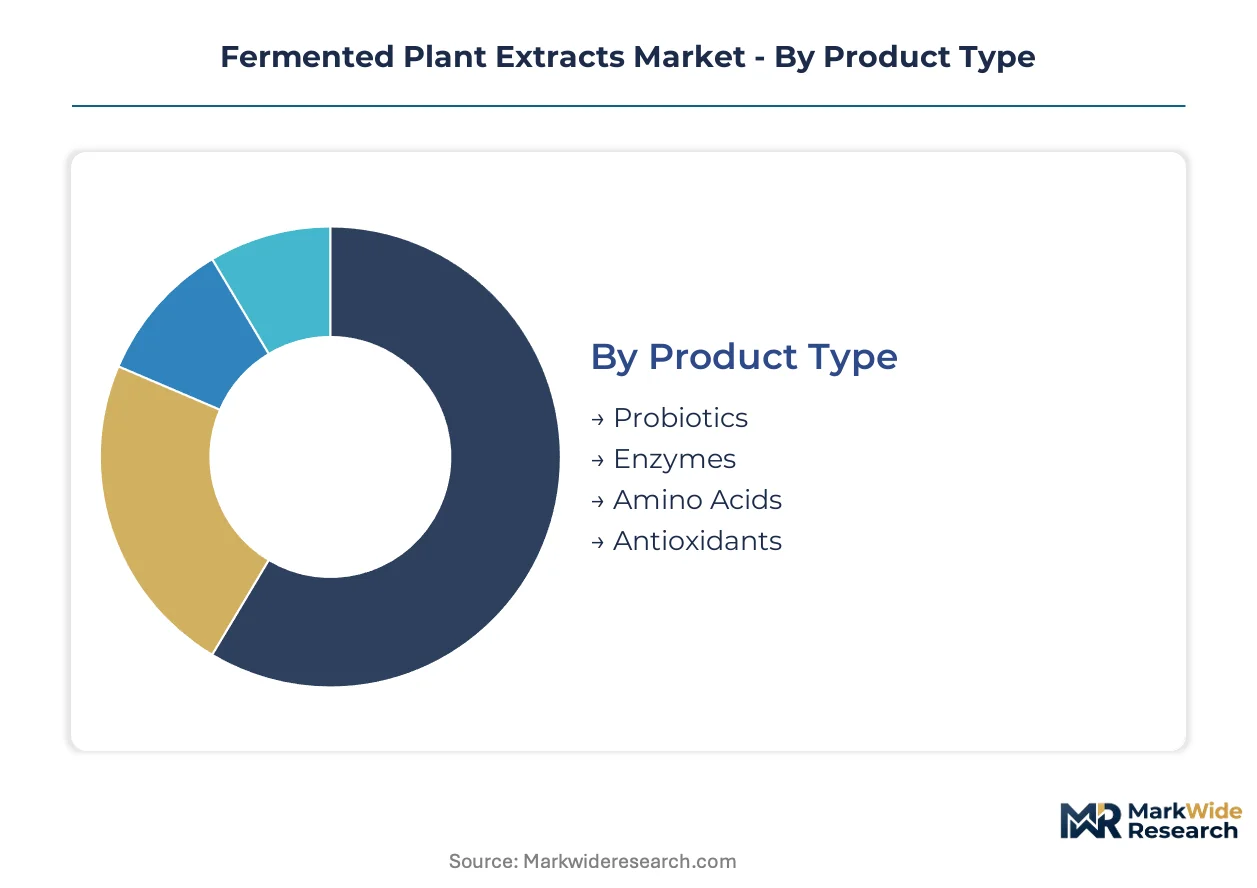
Fermented plant extracts fragment across four functional dimensions that determine margin capture and regulatory pathway. Product type dictates fermentation infrastructure requirements, while application governs substantiation burden and customer procurement behavior.
Product Type:
Probiotics and enzymes dominate domestic European production, while amino acid concentrates flow primarily to export markets serving Asian sports nutrition contract manufacturers.
- Probiotics:Live microbial cultures delivered in standardized CFU counts require cold-chain logistics and short shelf-life management. Demand concentrates in German and Danish nutraceutical facilities supplying EFSA-compliant immune-support formulations, with margin pressure from commoditization in bulk powder grades.
- Enzymes:Catalytic proteins with defined activity units enable clean-label processing claims for finished goods manufacturers. Production gravity sits with Danish strain library holders serving pharmaceutical-grade specifications, where catalytic specificity commands premium positioning over commodity alternatives.
- Amino Acids:Fermented botanical-derived protein building blocks compete with synthetic and extraction-based sources on cost-adjusted yields.
- Antioxidants:Polyphenol metabolites with enhanced bioavailability target cosmetic and anti-aging supplement applications.
Enzymes hold the largest share; momentum sits with amino acids.
Application:
Cosmetics applications command the steepest expansion trajectory as Korean and French formulators displace synthetic actives, while nutritional supplements anchor volume through established procurement channels.
- Nutritional Supplements:Capsule and tablet formats containing standardized fermented actives for immune, digestive, and metabolic support claims. Procurement concentrates among German contract manufacturers with integrated EFSA dossier capabilities, pulling volume from solvent-extracted alternatives as bioavailability substantiation tightens.
- Cosmetics:Fermented botanicals replacing parabens and synthetic preservatives in skincare formulations, with Korean beauty brands driving specification innovation and French luxury houses adopting the technology for clean-label positioning.
- Food & Beverages:Functional ingredients enabling fermentation-derived health claims in fortified products and fermented beverages.
- Animal Feed:Gut health promoters and digestibility enhancers for livestock and companion animal nutrition.
Nutritional supplements generate the highest absolute volume; cosmetics is climbing the fastest.
Form:
Powder formats concentrate production in Chinese cost-competitive facilities, while liquid extracts require proximity to European botanical processing clusters.
- Liquid:Aqueous or hydro-alcoholic solutions with immediate bioavailability for beverage and cosmetic serum applications. Production clusters around Frankfurt-Rhine-Main contract fermenters enabling just-in-time botanical processing for German nutraceutical clients.
- Powder:Spray-dried or freeze-dried concentrates with extended stability for supplement and feed applications. Chinese manufacturers compete on cost-adjusted yields, serving sports nutrition contract manufacturers with bulk amino acid and enzyme concentrates.
- Capsule:Pre-measured unit doses for direct-to-consumer supplement channels.
- Granule:Free-flowing agglomerated powders for sachet and stick-pack formats.
Powder holds the largest share; liquid is gaining share fastest.
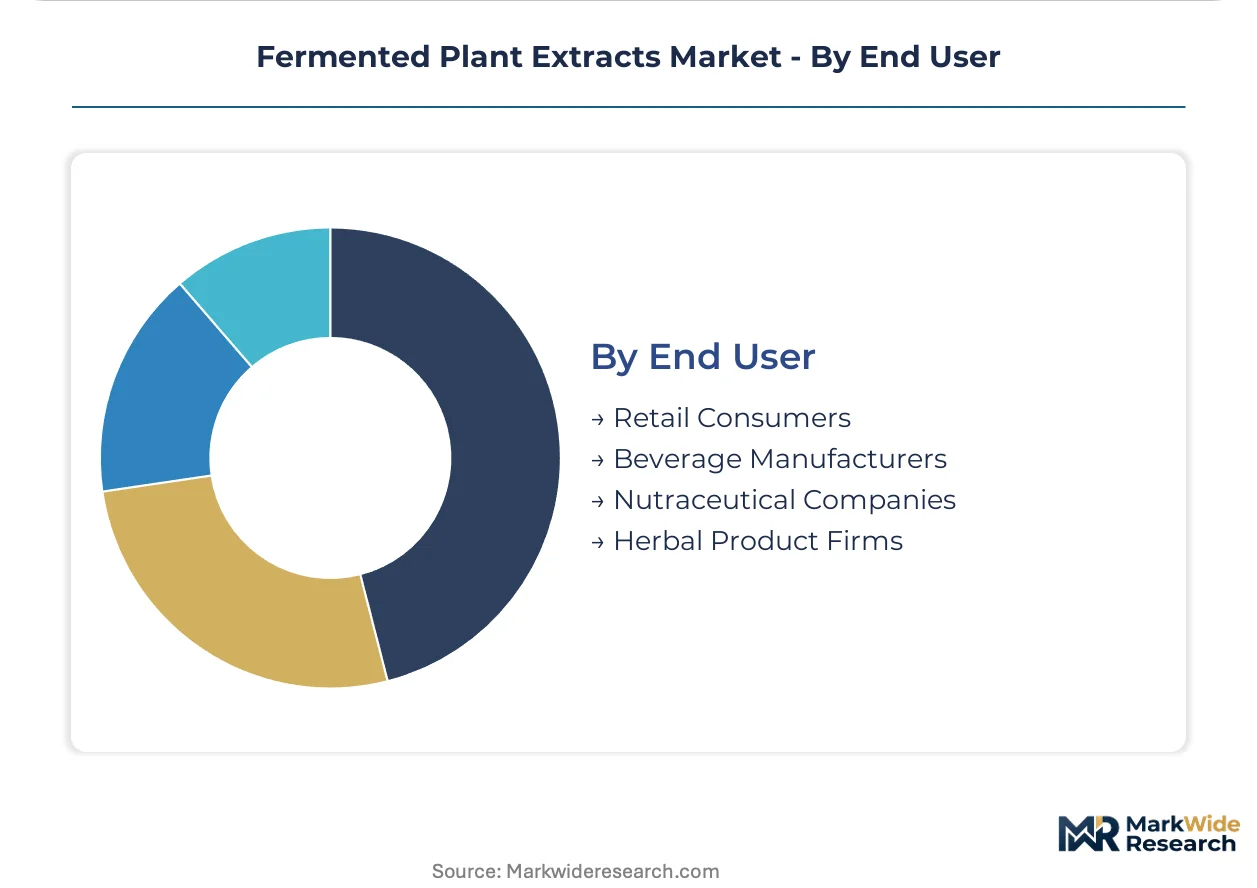
End User:
Nutraceutical companies and beverage manufacturers drive specification complexity, while retail consumers and herbal product firms purchase through distributor intermediaries.
- Nutraceutical Companies:Finished goods manufacturers with captive formulation capabilities demanding EFSA-compliant bioactive standardization. Direct sourcing contracts with Chr. Hansen and Kerry Group displace traditional ingredient distributors, compressing payment cycles and elevating quality audit requirements.
- Beverage Manufacturers:Functional drink producers incorporating fermented extracts for immune and digestive positioning. Procurement concentrates among multinational formulators with dual compliance architectures spanning FDA GRAS and NMPA registration requirements.
- Retail Consumers:Individual purchasers through e-commerce and specialty health channels.
- Herbal Product Firms:Traditional medicine and botanical supplement producers integrating fermentation-derived actives.
Nutraceutical companies hold the largest share; beverage manufacturers show the steepest procurement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in fermented plant extracts tilt toward European value-added processing and Asian bulk manufacturing, with regulatory divergence shaping trade corridors. Germany and Denmark dominate high-purity enzyme exports, while Chinese powder-form suppliers capture volume contracts for sports nutrition markets.
Germany
EFSA Novel Food dossier capabilities concentrate demand among Frankfurt-Rhine-Main contract fermenters serving immune-support brands. REACH compliance requirements for fermentation-derived substances filter out low-substantiation competitors. The Hesse biotech corridor anchors just-in-time botanical processing for nutraceutical clients demanding pharmaceutical-grade specifications.
China
NMPA health food registration requirements pull volume toward amino acid concentrates for domestic and export sports nutrition markets. GB standards for fermented food ingredients create compliance benchmarks that mid-scale suppliers struggle to meet. Zhengzhou and Xi'an manufacturing clusters compete on cost-adjusted yields for powder-form extracts.
United States
FDA GRAS self-affirmation pathways attract enzyme producers seeking faster market entry than European Novel Food routes. Clean-label formulation mandates from finished goods manufacturers drive catalytic specificity requirements. California and New Jersey biotech hubs house formulation partners for immune-support product development.
Denmark
Proprietary microbial strain libraries underpin high-purity enzyme production for pharmaceutical-grade applications. EFSA health claim substantiation requirements align with Danish regulatory affairs capabilities. Copenhagen-area facilities serve as supply anchors for multinational nutraceutical formulators with captive sourcing contracts.
France
ANSM cosmetic ingredient oversight accelerates fermented botanical adoption in luxury skincare replacing synthetic preservatives. Korean beauty brand specifications drive innovation in bioactive metabolite profiles. The Île-de-France region clusters formulation laboratories bridging pharmaceutical and cosmetic application expertise.
Fermented Plant Extracts Market Competitive Landscape
Concentration sits with strain library holders and backward-integrated fermentation specialists. The supplier base compresses around three tiers: premium-grade enzyme producers with proprietary microbial collections, mid-scale contract fermenters serving regional nutraceutical clients, and cost-competitive powder manufacturers. M&A activity targets toxicology dossier capabilities for EFSA compliance, while capacity expansion concentrates in the Frankfurt-Rhine-Main corridor to exploit co-location synergies.
Within the premium enzyme tier, Chr. Hansen and Novozymes occupy positions defined by microbial strain proprietary advantages. Kerry Group represents the backward-integrated archetype combining fermentation capacity with botanical sourcing networks. Xian Sost Biological Science & Technology exemplifies cost-competitive powder-form specialists competing on yield-adjusted pricing for amino acid concentrates.
| Leading Market Players |
|---|
| Xian Sost Biological Science & Technology |
| Chr. Hansen |
| ID Bio |
| Kerry Group |
| Novozymes |
| Phytoneering Extract Solutions GmbH |
| Ecuadorian Rainforest |
| Honson Pharmatech Group |
| Xi'an Hao-Xuan Bio-Tech |
| Others |
Supply & Pricing Matrix
Synthetic preservative displacement by fermented botanicals simultaneously redraws supply geography toward Frankfurt-Rhine-Main contract fermenters and compresses pricing economics for commodity probiotic grades. This substitution dynamic concentrates margin capture among enzyme specialists with catalytic specificity while elongating payment cycles for bulk powder suppliers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures spanning premium pharmaceutical-grade, standard nutraceutical-grade, and economy feed-grade tiers. Price differentiation rests on EFSA Novel Food certification status and strain library provenance, with Danish and German holders commanding substantial premia over unvalidated alternatives. Cost compression in economy probiotic grades is intensifying because Chinese powder manufacturers compete on yield-adjusted amino acid pricing. Nutraceutical formulators with captive sourcing contracts exhibit lowest price sensitivity; sports nutrition contract manufacturers purchasing bulk concentrates show highest sensitivity.
Supply Chain Analysis
Germany, Denmark, and China anchor distinct supply tiers—pharmaceutical-grade enzymes, strain library-dependent specialty fermentation, and cost-competitive powder extraction respectively. Raw material flows draw from botanical sourcing networks in Eastern Europe, proprietary microbial collections in Copenhagen, and standardized plant substrates in Shaanxi province. Single-source vulnerability concentrates in proprietary strain libraries held by narrow supplier bases. Distribution runs through direct sourcing contracts between finished goods manufacturers and fermentation specialists, displacing traditional ingredient distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EFSA, FDA, and NMPA pathways fragments supplier viability standards, creating acquisition opportunities for dossier-ready producers and exit pressure on unsubstantiated competitors.
For Market Incumbents: Compound defensive positioning through backward integration into Frankfurt-Rhine-Main fermentation capacity and captive strain library expansion. EFSA toxicology dossier requirements threaten smaller competitors with exit costs; incumbents should accelerate certification investment to consolidate immune-support formulation relationships before regulatory harmonization clarifies postbiotic classification. For New Entrants and Emerging Players: FDA GRAS self-affirmation fast-tracks offer lower barrier entry than European Novel Food routes for enzyme producers seeking catalytic specificity positioning. White space concentrates in powder-form amino acid concentrates for sports nutrition contract manufacturers underserved by mid-scale fermenters. Target co-location partnerships with Hesse biotech corridor facilities to exploit just-in-time botanical processing synergies. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract fermenters lacking EFSA dossier capabilities but holding pharmaceutical-grade infrastructure. Five-to-ten year viability favors acquisition of toxicology consultancy-integrated producers capable of navigating divergent FDA-EFSA-NMPA compliance architectures. Signal to monitor: EFSA-FDA alignment on postbiotic definitions determining whether fermented extracts face drug-like scrutiny or retain food-supplement status.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Investment | Filters low-substantiation competitors while securing immune-support formulation relationships with German nutraceutical brands. |
| Strain Library Expansion | Proprietary microbial collections in Denmark underpin catalytic specificity premia unavailable to commodity probiotic producers. |
| Frankfurt-Rhine-Main Co-location | Contract fermenter clustering enables just-in-time botanical processing for pharmaceutical-grade specifications. |
| Continuous Bioprocessing Adoption | Perfusion systems in Germany and Denmark compress capital intensity while enabling real-time metabolite monitoring. |
| Direct Sourcing Contract Negotiation | Finished goods manufacturers bypass traditional distributors, compressing payment cycles and elevating quality audit requirements. |
Research Methodology
Desk research of EFSA Novel Food guidance documents, REACH compliance databases, and NMPA health food registration precedents preceded structured interviews with contract fermentation facility managers, nutraceutical procurement directors, regulatory affairs specialists, and cosmetic formulation scientists. Secondary validation drew from customs trade data, SEC filings of publicly traded ingredient suppliers, and EU biotech corridor development reports. Bottom-up volume estimates triangulated against top-down market sizing across product type and application segments.
Variance decomposition across the projection horizon isolates volume, price, and mix contributions to value expansion. Segmentation dimensions modeled include product type tier, application substantiation burden, form factor logistics requirements, and end-user procurement sophistication. CAGRs were derived from trend extrapolation of historical fermentation capacity expansion and regulatory filing velocity. Industry-specific forecast inputs incorporate EFSA dossier approval timelines and strain library patent expiration patterns.
Underlying assumptions cover sustained EFSA enforcement of Novel Food requirements, stable NMPA registration processing rates, and continued Korean-French cosmetic clean-label adoption, with deviation risk concentrated in regulatory harmonization timing and postbiotic classification decisions. Recalibration cycles align with material shifts in EFSA-FDA alignment negotiations and fermentation technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Europe Pea Protein Market
Plant Based Food
Vegan Steak Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Global Tofu Market
Plant Based Food
Organic Pea Protein Market
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
Europe Plant-Based Meal Kit Market
Plant Based Food
Tempeh Market
Plant Based Food
North America Tofu Market
Plant Based Food
Fava Bean Protein Market
Plant Based Food
Plant-Based Yogurt Market
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Vegan Protein Blend Market
Plant Based Food
Europe Meat Substitutes Market
Plant Based Food
United Kingdom Plant Protein Market