
 Cooking Coconut Milk Market | 2026-2036
Cooking Coconut Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Cooking Coconut Milk Market Analysis
Food service procurement is restructuring as Southeast Asian and Caribbean restaurant chains expand coconut milk-based menu offerings across North American and European cities. Theppadungporn Coconut leverages its integrated crushing and canning facilities in Thailand to sustain supply continuity for export markets. Goya Foods anchors its competitive stance through specialized Hispanic and Latin American channel control in US grocery retail. McCormick & Company differentiates via R&D intensity in flavor-stable emulsion technologies for industrial sauce applications.
Cooking coconut milk denotes the heat-stable, higher-fat extract derived from grated mature coconut kernel, typically containing 17-24% fat and processed through mechanical pressing or centrifugal separation for culinary applications requiring thermal tolerance. Canned formats dominate institutional procurement due to extended shelf stability and standardized brix levels, while organic variants command premium positioning in specialty retail channels. Tetra pack packaging is gaining traction among food service distributors seeking reduced logistics weight and ambient storage flexibility compared to conventional tinplate containers.
FDA food labeling standards and EFSA novel food regulations shape ingredient disclosure requirements and import clearance protocols for coconut milk entering US and European markets. Thailand's Ministry of Industry enforces Good Manufacturing Practice certification for export-oriented copra processing facilities, directly affecting market access for regional suppliers. Stakeholders must monitor evolving plant-based dairy alternative classifications in major import jurisdictions, as reclassification risks could alter tariff structures and retail placement protocols.
Market Dynamics
Clean-label formulation mandates from EFSA and FDA are tightening additive disclosure requirements for coconut milk processors. Plant-based sauce and curry base applications are restructuring procurement patterns among food service operators across North American and European cities.
Growth Catalysts
- EFSA Novel Food Regulations:Standardized safety assessments for coconut-derived ingredients accelerate import clearance into European markets. Processors investing in dossier preparation gain first-mover shelf placement advantages.
- Thai Copra Supply Clusters:Integrated crushing and canning facilities in Samut Sakhon and Surat Thani provinces sustain export-grade supply continuity. Proximity to raw material sources compresses lead times for institutional buyers.
- Tetra Pack Ambient Storage:Food service distributors adopt aseptic carton formats to reduce logistics weight and eliminate cold-chain dependencies. This packaging shift expands addressable market reach to remote kitchen operations.
Market Restraints
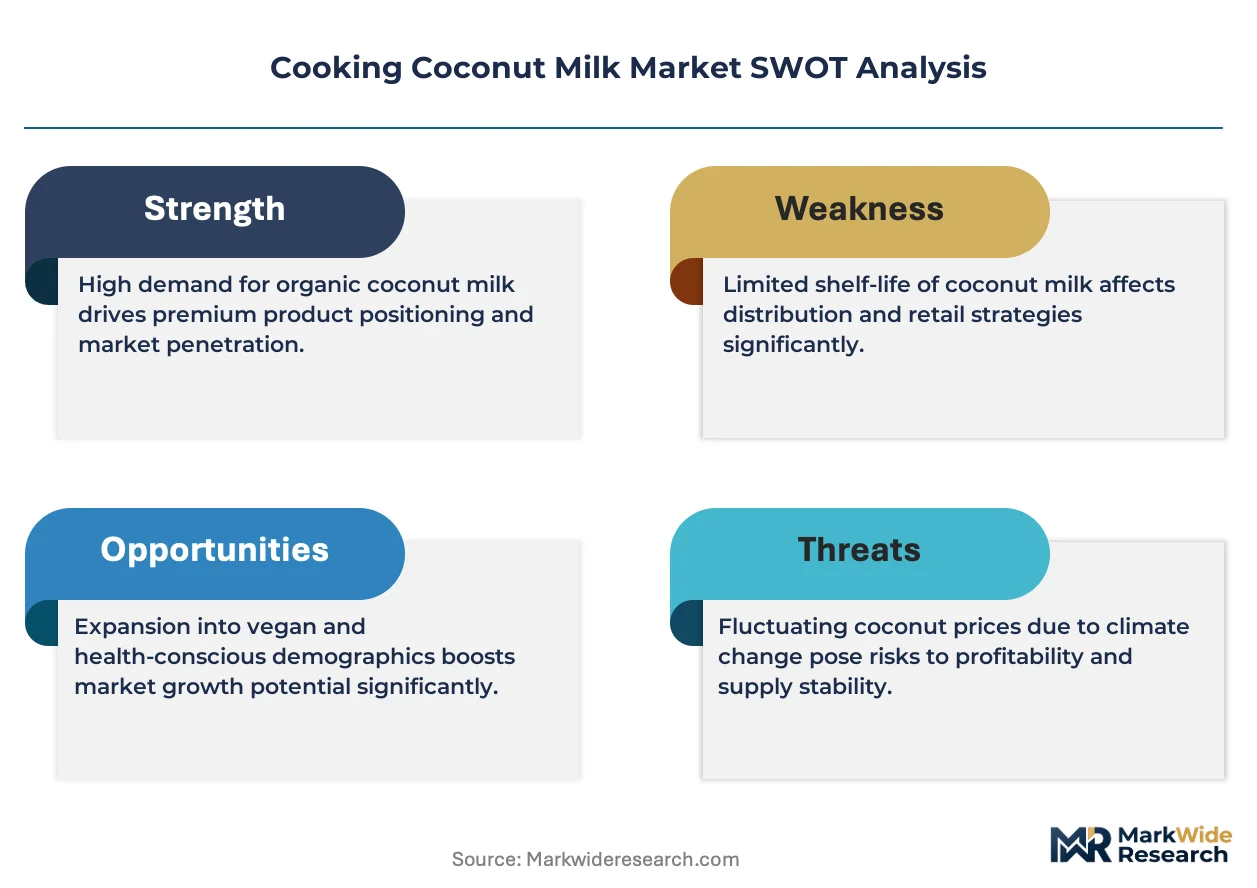
- Copra Price Volatility:Drought cycles in Mindanao and Sulawesi disrupt Philippine coconut harvests. Input cost swings compress margin predictability for processors lacking backward integration into plantation assets.
- Thai Facility Concentration:Export-oriented Good Manufacturing Practice certification concentrates in Thailand's Ministry of Industry oversight zones. Single-country supply dependency creates geopolitical exposure for North American importers.
- Oat and Soy Milk Substitution:Barista-formulated oat milks displace coconut milk in specialty coffee applications. Creaming stability advantages in plant-based dairy alternatives erode coconut's position in beverage-forward channels.
Strategic Opportunities
- US FDA Plant-Based Dairy Reclassification:Pending standards of identity revisions may recategorize coconut milk alongside nut milks. Early compliance investments position suppliers for revised retail placement protocols.
- Caribbean Restaurant Chain Expansion:Hispanic and Latin American culinary concepts in Miami and Houston are expanding coconut milk-based menu offerings. Regional food service distributors can capture this demand through specialized ethnic channel partnerships.
- Centrifugal Separation and Microfiltration Convergence:Combined mechanical pressing and membrane technologies enable fat-standardized extracts without chemical stabilizers. Clean-label positioning commands premium placement in specialty retail channels.
Industry Challenges
- Flavor-Stable Emulsion R&D Talent Scarcity:Industrial sauce applications require food scientists skilled in heat-stable lipid dispersion. Competition from broader plant-based sectors stretches technical recruitment pipelines.
- Thai GMP Certification Timelines:Export facility audits by the Ministry of Industry extend 14-18 months for new market entrants. Capital deployment delays compress revenue realization windows for capacity expansion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooking Coconut Milk Market |
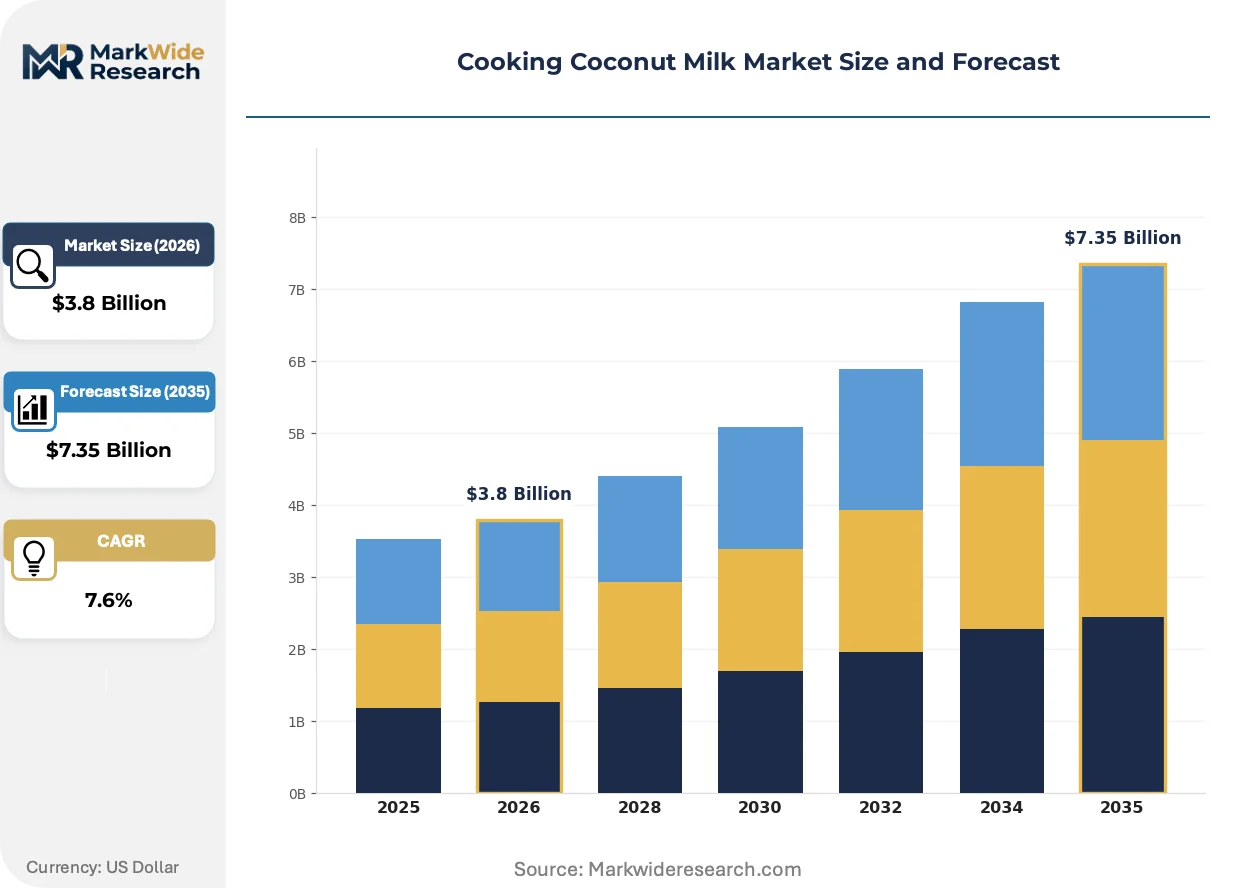
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned, Powdered, Fresh, Organic Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Stores End User: Households, Restaurants, Food Service, Cafés Packaging Type: Bottles, Tetra Packs, Pouches, Jars |
| Companies Covered | McCormick & Company, Theppadungporn Coconut, Axelum Resources Corp., Campbell Soup Company, Goya Foods, Thai Coconut Public Company Limited, Danone S.A., So Delicious, Sambu Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooking Coconut Milk Market Emerging Trajectories
Aseptic processing advances and packaging format diversification are compressing traditional supply chain configurations. Regulatory clarity on plant-based labeling is simultaneously reshaping competitive positioning in retail and food service channels.
High-pressure processing (HPP) technology is rewriting shelf-life extension protocols for refrigerated coconut milk formats. Cold-brew coffee chains and fast-casual Asian concepts in Los Angeles and New York are adopting HPP-treated extracts at accelerating rates. This non-thermal approach is compressing the historical dominance of retort-canned products in premium food service segments.
EU Green Deal farm-to-fork sustainability metrics are tightening traceability requirements for tropical commodity imports. Coconut processors must now document deforestation-free sourcing and carbon intensity per liter. Thai and Indonesian suppliers investing in blockchain-verified supply chain mapping secure preferential placement with European retail consolidators.
Direct-to-food-service distribution models are displacing traditional broker-mediated procurement in North American urban markets. Specialty distributors in Chicago and Toronto now source coconut milk directly from Thai canning facilities, bypassing layered import intermediaries. This channel compression is most visible in independent Southeast Asian restaurant clusters seeking cost transparency and volume flexibility.
Cooking Coconut Milk Market Segmentation
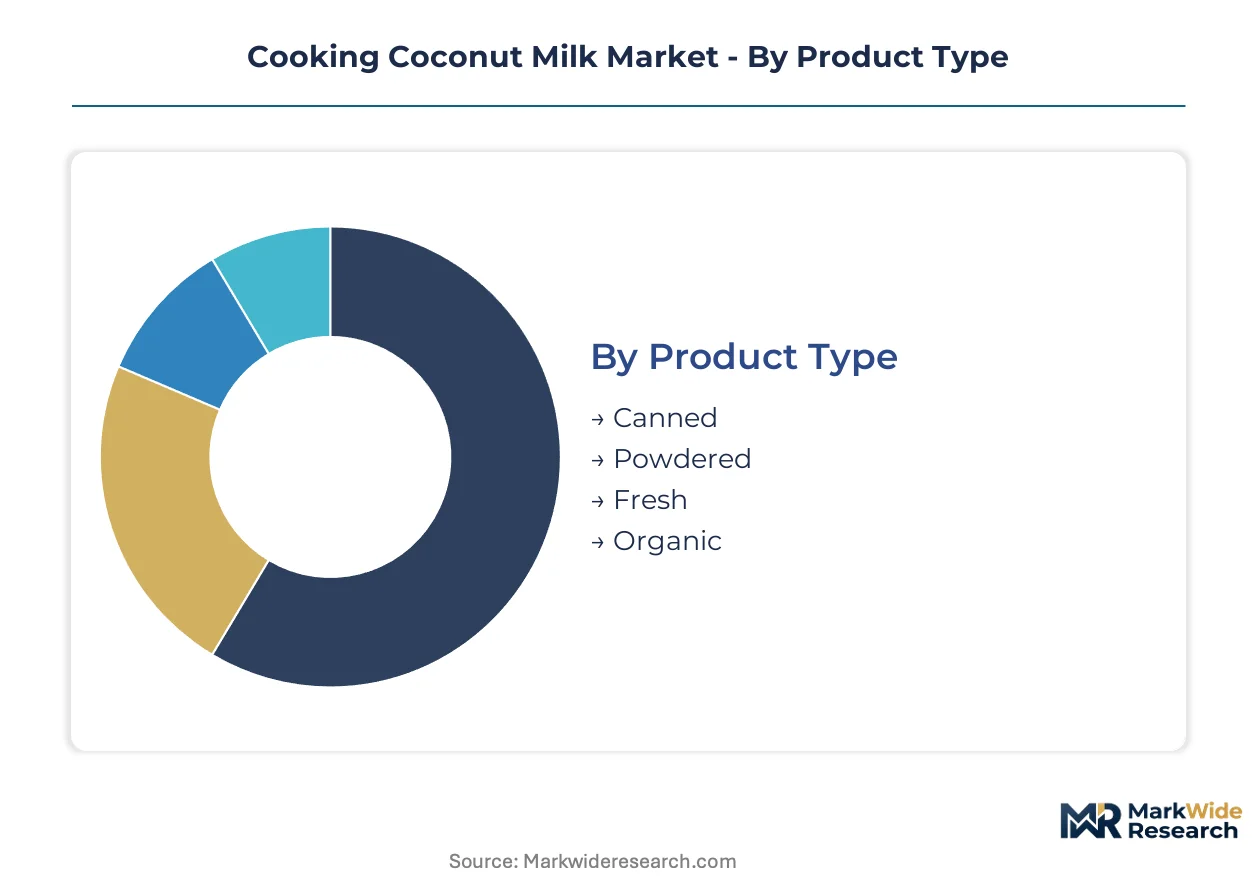
Cooking coconut milk segmentation reveals how procurement patterns diverge across shelf-stable versus fresh formats, and how channel control determines margin capture. Understanding these fault lines exposes where suppliers can command premium positioning versus competing on volume throughput.
Product Type:
Standardization dominates at the industrial end while customization concentrates in specialty retail, with fat content and thermal tolerance serving as the primary technical differentiators.
- Canned:Heat-stable extracts with 17-24% fat content processed through retort sterilization. Institutional buyers in Thai and Philippine food manufacturing clusters specify this format for curry base production due to batch consistency and extended shelf stability.
- Organic:Certified copra sourcing with additive-free processing protocols. European retail consolidators under EU Green Deal traceability mandates are driving procurement toward blockchain-verified supply chains from Samut Sakhon province.
- Powdered:Spray-dried coconut cream with reconstitution ratios tailored for industrial sauce applications. Southeast Asian export processors dominate capacity.
- Fresh:Refrigerated extracts with shorter shelf life requiring cold-chain logistics. Limited to urban food service clusters with same-day delivery infrastructure.
Most installed capacity flows through Canned. Expansion is steepest in Organic.
Distribution Channel:
Channel economics split between direct procurement compression in food service and layered retail intermediaries that erode supplier margins.
- Supermarkets:Grocery retail chains in US Hispanic markets and European urban centers stock standardized SKUs with EFSA-compliant labeling. Placement fees and slotting costs compress net margins for exporters.
- Online:Direct-to-restaurant platforms and specialty food e-commerce. Thai canning facilities now bypass import brokers through Chicago and Toronto-based distributor partnerships, accelerating volume growth.
- Specialty Stores:Ethnic grocery formats serving Caribbean and Southeast Asian diaspora communities in Miami and Houston. Curated SKU mixes support premium positioning for clean-label variants.
- Convenience Stores:Limited assortment of long-shelf-life formats. Urban grab-and-go demand in Asian metropolitan areas drives placement.
Volume concentrates in Supermarkets. Margin expansion is fastest in Online.
End User:
Application requirements fragment between thermal tolerance needs in commercial kitchens and convenience priorities in residential settings.
- Restaurants:Southeast Asian and Caribbean chain concepts across North American cities require fat-standardized extracts for sauce consistency. Direct procurement from Thai GMP-certified facilities is displacing broker-mediated supply.
- Food Service:Industrial sauce manufacturers and institutional caterers specify brix-calibrated bulk formats. McCormick-style R&D partnerships demand flavor-stable emulsion technologies.
- Households:Retail-packaged formats with recipe-friendly portion sizing. Organic and clean-label positioning commands shelf space in specialty channels.
- Cafés:Specialty coffee applications facing displacement by barista-formulated oat milks. Remaining demand concentrates in cold-brew chains adopting HPP-treated extracts.
Procurement volume centers on Restaurants. Technical specification intensity is highest in Food Service.
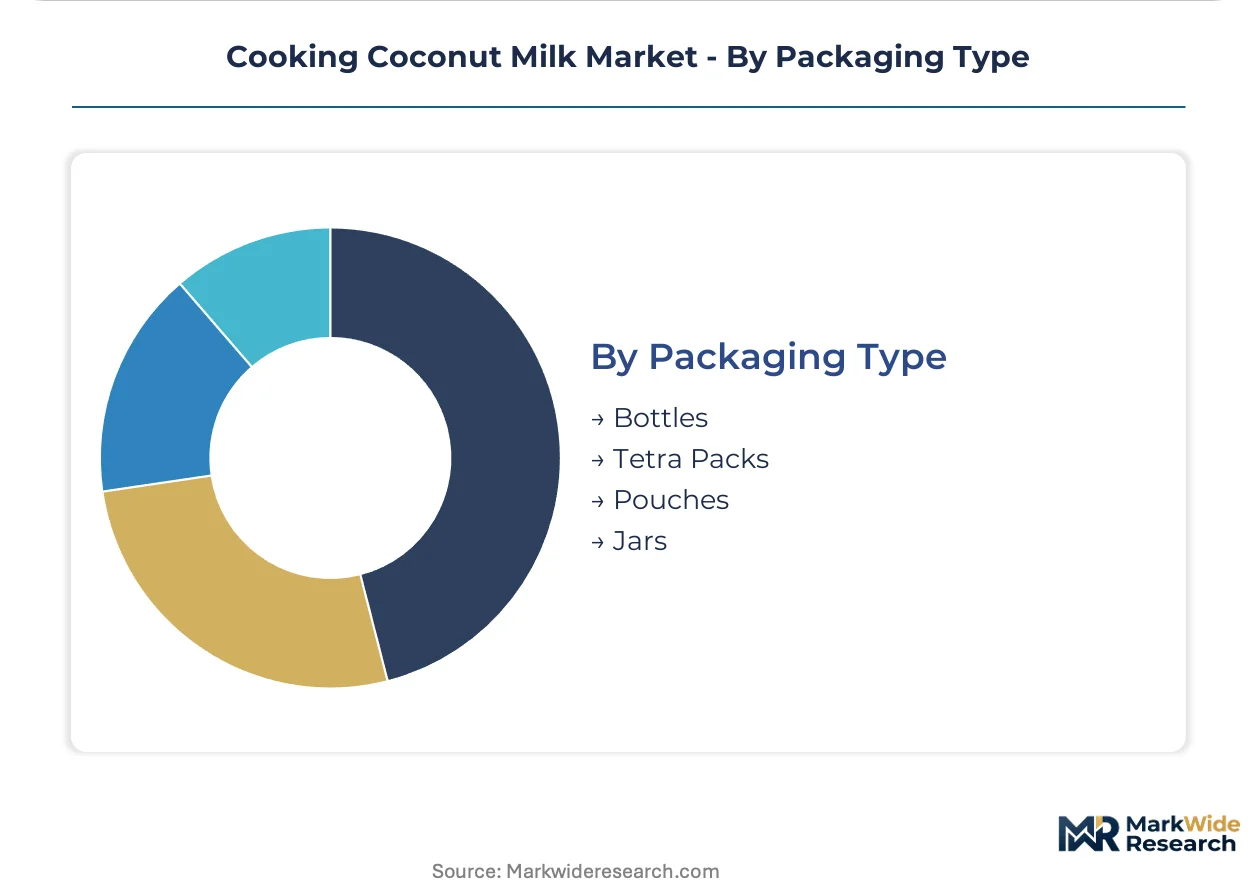
Packaging Type:
Logistics cost structures and storage flexibility determine format adoption across ambient versus cold-chain dependent supply chains.
- Tetra Packs:Aseptic carton formats reducing logistics weight by 60% versus tinplate. North American food service distributors favor ambient storage flexibility for remote kitchen operations.
- Pouches:Flexible packaging for single-serve and food service portion control. Southeast Asian manufacturing clusters are expanding retort pouch capacity for export markets.
- Bottles:Refrigerated formats for fresh and HPP-treated extracts. Cold-brew coffee chains in Los Angeles and New York specify this packaging for premium positioning.
- Jars:Glass packaging for organic and specialty retail positioning. European sustainability metrics favor recyclable formats despite higher freight costs.
Capacity investment concentrates in Tetra Packs. Adoption velocity is highest in Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as Thai and Indonesian processors exploit compliance cost gaps versus European and North American manufacturing. EFSA novel food dossier requirements and FDA facility registration protocols create asymmetric barriers that concentrate export-oriented capacity in Southeast Asian GMP-certified zones.
Thailand
Samut Sakhon and Surat Thani provinces host integrated crushing and canning facilities serving North American food service distributors. Thai Ministry of Industry GMP certification mandates compress new entrant timelines to 14-18 months. Surat Thani copra supply clusters sustain backward integration advantages for export-grade cooking coconut milk production.
United States
Hispanic and Caribbean restaurant chains in Miami and Houston are expanding coconut milk-based menu procurement. FDA food labeling standards enforce additive disclosure requirements for imported extracts. Chicago and Toronto distributors now bypass import brokers through direct Thai facility partnerships.
Philippines
Mindanao and Sulawesi copra harvests face drought-cycle disruption that propagates input cost volatility. Philippine coconut authority export protocols align with EU Green Deal deforestation-free sourcing mandates. Davao processing clusters concentrate organic certification capacity for European retail consolidators.
Germany
EU Green Deal farm-to-fork sustainability metrics tighten traceability requirements for tropical commodity imports. EFSA clean-label formulation mandates drive procurement toward blockchain-verified Thai supply chains. Hamburg and Rotterdam port logistics handle bulk tetra pack distribution into Central European food service channels.
Indonesia
Sulawesi and Sumatra copra plantations supply raw material to export-oriented processing joint ventures. National pharmaceutical regulator alignment with ASEAN harmonized standards facilitates cross-border facility certification. Surabaya manufacturing zones are expanding aseptic carton capacity for Middle Eastern and Australian export markets.
Cooking Coconut Milk Market Vendor Landscape
Capacity expansion dominates the current landscape as Thai and Philippine processors add aseptic tetra pack lines to capture food service distributor demand. The vendor base stratifies across integrated plantation-processor hybrids, specialized ethnic-channel marketers, and industrial ingredient suppliers. Three archetypes define competitive positioning: backward-integrated Southeast Asian exporters, Hispanic-market channel specialists, and R&D-intensive flavor technology developers. Geographic expansion and clean-label certification investments represent the dominant competitive moves.
Among integrated Thai processors, Theppadungporn Coconut and Thai Coconut Public Company Limited exemplify the plantation-to-canning archetype with captive copra supply chains. Goya Foods occupies a distinct position within Hispanic and Latin American channel control in US grocery retail. McCormick & Company represents the R&D-intensive tier focused on industrial sauce applications and flavor-stable emulsion technologies. These three anchors illustrate how procurement pattern restructuring favors players with either upstream raw material security or downstream channel captivity.
| Leading Market Players |
|---|
| McCormick & Company |
| Theppadungporn Coconut |
| Axelum Resources Corp. |
| Campbell Soup Company |
| Goya Foods |
| Thai Coconut Public Company Limited |
| Danone S.A. |
| So Delicious |
| Sambu Group |
| Others |
Supply Flow & Price Mechanics
Family-owned Thai copra processors with multi-generational plantation holdings exercise outsized influence on both raw material release timing and contract pricing discipline across export markets. Their captive supply control compresses spot market liquidity while amplifying premium capture for GMP-certified output destined for North American food service distributors.
Pricing Analysis
Distributor margin layers determine final landed cost structures more than factory-gate differentials. Three-tier pricing structure across organic-certified, conventional GMP-grade, and economy bulk segments reflects fat-standardization precision and EFSA-compliant labeling investments. Cost compression in economy tiers is intensifying because Philippine drought cycles propagate copra input volatility. Quick-service restaurant chains exhibit highest price sensitivity, while industrial sauce manufacturers prioritize batch consistency over unit economics.
Supply Chain Analysis
EU Green Deal domestic-content mandates for deforestation-free sourcing are reshaping procurement documentation requirements for European-bound shipments. Manufacturing gravity centers on Thailand, the Philippines, and Indonesia, with each jurisdiction feeding distinct regulatory compliance tiers. The network draws from Mindanao and Sulatani copra belts, aseptic carton packaging substrates, and refrigerated logistics providers. Single-country Thai GMP certification concentration creates geopolitical exposure for importers lacking alternative qualified suppliers. Distribution runs through direct-to-distributor models in Chicago and Toronto alongside traditional layered retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EFSA clean-label mandates and EU Green Deal traceability requirements are accelerating procurement shifts toward blockchain-verified, additive-free premium specifications.
For Market Incumbents: Anchor backward integration into Surat Thani and Samut Sakhon copra supply clusters to defend against Philippine drought-driven input volatility. Prioritize tetra pack capacity expansion for North American food service distributor direct relationships, compressing broker-mediated margin erosion. Accelerate R&D recruitment for flavor-stable emulsion talent pools before broader plant-based sectors exhaust technical pipelines. For New Entrants and Emerging Players: Begin with Caribbean restaurant chain expansion corridors in Miami and Houston, where Hispanic and Latin American culinary concepts are proliferating coconut milk-based menu development. Target independent Southeast Asian restaurant clusters seeking volume flexibility and cost transparency through bypassed import intermediaries. Pursue centrifugal separation and microfiltration technology partnerships to command clean-label premium positioning without chemical stabilizer dependencies. For Investors and Strategic Acquirers: Food service distributors with direct Thai facility relationships are the most active acquirer in this space, consolidating ethnic channel control and logistics compression advantages. The five-to-ten year viability window favors plantation-processor hybrids with captive copra security and GMP-certified export infrastructure. Monitor FDA plant-based dairy reclassification proceedings as the critical inflection signal for revised retail placement protocol disruptions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copra Supply | Captive raw material security from Surat Thani plantations insulates margin predictability against Philippine drought cycles. |
| Aseptic Tetra Pack Capacity Expansion | Reduced logistics weight and ambient storage flexibility capture food service distributor procurement shifts in Chicago and Toronto. |
| Blockchain-Verified Supply Chain Mapping | EU Green Deal deforestation-free documentation secures preferential placement with European retail consolidators. |
| Centrifugal Separation Technology Investment | Clean-label fat-standardized extracts without chemical stabilizers command premium positioning in specialty retail channels. |
| Direct-to-Food-Service Distribution Model | Bypassing import brokers accelerates volume growth among independent Southeast Asian restaurant clusters seeking cost transparency. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Thai copra processors, North American food service distributors, European retail consolidators, and industrial sauce R&D directors with secondary validation. Customs records, EU import clearance databases, FDA facility registration filings, and ASEAN harmonized standards documentation anchored external data triangulation. Bottom-up volume modeling and top-down value reconciliation ensured cross-verification integrity.
Segment-weighting approaches distributed value across product type, distribution channel, end user, and packaging format dimensions throughout the forecast period. CAGRs derived from historical trajectory analysis and demand elasticity modeling across restaurant, food service, household, and café applications. Copra price volatility indices, EFSA novel food dossier approval timelines, and tetra pack adoption curves served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including extreme weather disruptions beyond historical Philippine drought patterns, abrupt FDA plant-based dairy reclassification timing, and geopolitical trade restriction scenarios. Forecasts reflect documented assumptions around regulatory continuity and supply chain configuration stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Native Starch Market
Ingredients
Botanical Extracts Market
Ingredients
Mussel Oil and Powder Market
Ingredients
North America Brewing Enzymes Market
Ingredients
Textural Food Ingredients Market
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Textured Milk Protein Market
Ingredients
Asia-Pacific Agar Market
Ingredients
Glucuronolactone Market
Ingredients
Banana Flour Market
Ingredients
South America Algae Omega-3 Ingredients Market
Ingredients
Carob Protein Market
Ingredients
Rose Extract Market
Ingredients
Heart Health Ingredients Market
Ingredients
Canola Meal Market
Ingredients
Phytosterols Market