
 Cocoa Bean Extract Market | 2026-2036
Cocoa Bean Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Cocoa Bean Extract Market Analysis
The EU Deforestation Regulation is shifting how cocoa bean extract enters European supply chains, forcing traceability investments upstream. Barry Callebaut leverages its bean-to-extract infrastructure to sustain compliance advantages across multiple geographies. Cargill anchors its position through direct farmer partnerships in West Africa, while Olam International competes on sustainability certification breadth.
Cocoa bean extract comprises concentrated bioactive compounds—primarily flavanols, theobromine, and polyphenols—derived through solvent or supercritical CO2 extraction from fermented and dried Theobroma cacao seeds, serving functional food, cosmetic, and pharmaceutical formulations. Powder extract dominates current volume due to stability and ease of incorporation into dry beverage mixes and supplement tablets. Liquid extract represents the fastest-growing format as ready-to-drink functional beverages expand, while certified organic and fair trade segments command premium positioning in nutraceutical channels where ethical sourcing influences procurement decisions.
European regulators including EFSA and EMA shape extract purity standards and novel food approval pathways, while REACH compliance governs solvent residues in cosmetic-grade extracts. The FDA maintains separate GRAS and food additive frameworks for US-bound cocoa derivatives, creating divergent testing requirements. Stakeholders must monitor evolving deforestation-linked due diligence laws and adapt extraction certifications to match jurisdiction-specific enforcement timelines.
Market Dynamics
The EU Deforestation Regulation is compressing supplier timelines for traceable cocoa sourcing, forcing extractors to invest in farm-level verification systems or forfeit European market access.
Growth Catalysts
- Clean-label reformulation:Food and beverage manufacturers across Germany and Switzerland are substituting synthetic additives with cocoa-derived flavanols in functional beverages and supplement formulations.
- REACH compliance automation:Solvent residue testing protocols for cosmetic-grade extracts are streamlining cross-border batch approvals within EU member states.
- West African bean quality premiums:Fermentation protocol upgrades in Côte d'Ivoire and Ghana are elevating flavanol retention rates in raw material inputs.
Market Restraints
- Input cost volatility:Cocoa butter and cocoa powder price swings in commodity markets transmit directly to extract production economics, squeezing processor margins.
- Supply concentration risk:Over seventy percent of global cocoa bean originates from West African smallholder cooperatives, exposing extractors to regional climate shocks and political instability.
- Technical limitation:Supercritical CO2 extraction equipment requires specialized high-pressure vessel engineering that remains concentrated among German and Italian machinery suppliers.
Strategic Opportunities
- Underpenetrated nutraceutical channels in Japan:Functional food manufacturers in Osaka and Tokyo are piloting theobromine-enriched formulations for cardiovascular health positioning.
- Regulatory tailwind from EU Green Deal:Carbon footprint labeling requirements for imported agricultural derivatives are creating first-mover advantages for certified organic extractors.
- Technology convergence:Blockchain-enabled farm-to-facility tracking is merging with mass spectrometry authentication to create tamper-proof provenance documentation for premium cosmetic buyers.
Industry Challenges
- Specialized extraction chemist scarcity:Supercritical fluid process engineering expertise remains concentrated among retiring specialists in Basel and Milan, constraining facility expansion timelines.
- Organic certification timeline compression:Three-year conversion periods for conventional cocoa farms seeking EU organic status are mismatching with immediate procurement demands from certified-hungry formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocoa Bean Extract Market |
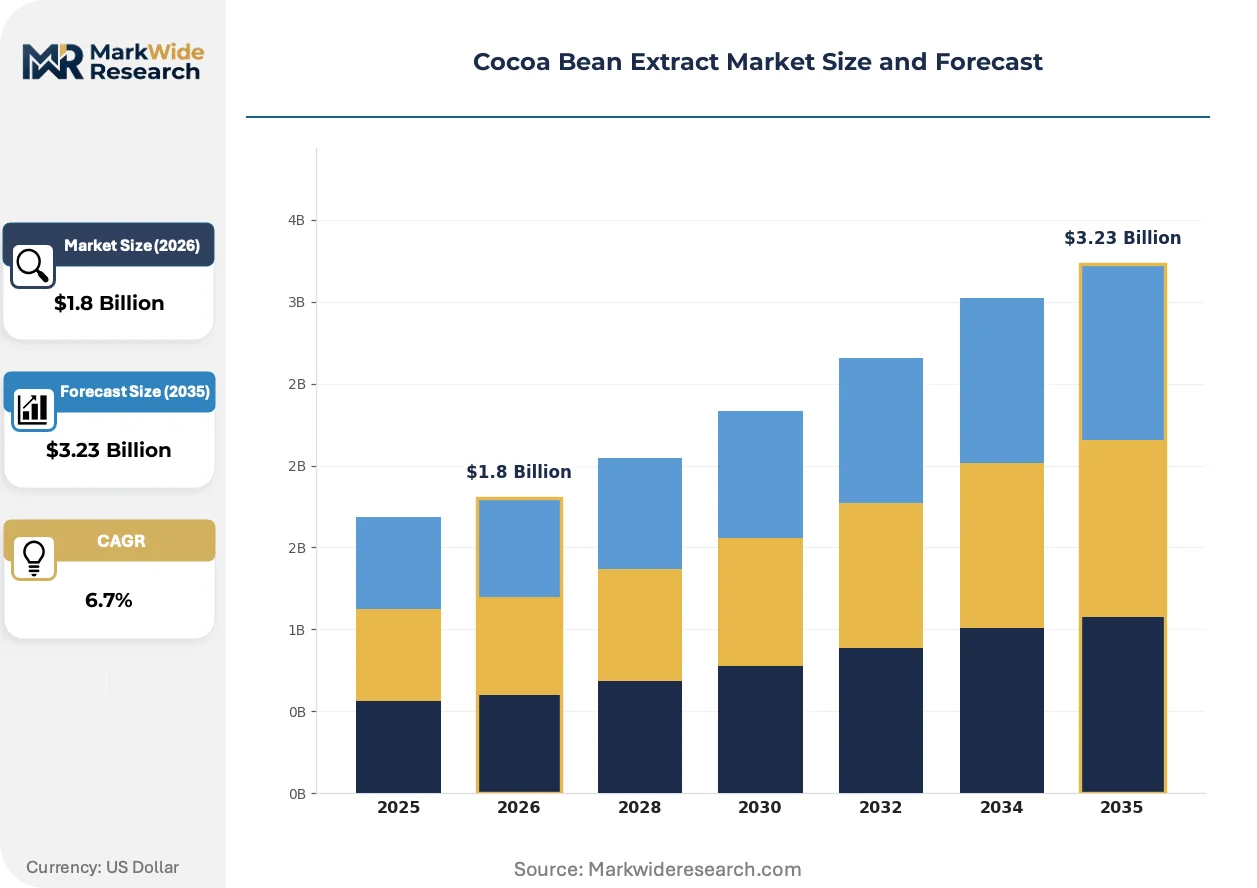
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granules, Whole Beans Application: Food & Beverage, Cosmetics, Pharmaceuticals, Nutraceuticals End User: Manufacturers, Retailers, Distributors, Foodservice Certification: Organic, Fair Trade, Non-GMO, Certified Gluten-Free |
| Companies Covered | Barry Callebaut, Cargill, Olam International, Blommer Chocolate Company, Naturex (Givaudan), Nestlé, Mondelez International, ECOM Agroindustrial, Nexira, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocoa Bean Extract Market Emerging Trajectories
Extraction technology and sourcing verification are converging to reshape how cocoa bioactives enter formulated products, with sustainability credentials becoming inseparable from technical specifications.
Supercritical CO2 extraction is absorbing market share from conventional solvent-based methods by eliminating residual petrochemical traces that trigger REACH scrutiny. Premium cosmetic formulators in France and Germany are specifying CO2-derived flavanol concentrates for dermal application products. The technology is absorbing capital investment that previously flowed toward ethanol extraction infrastructure, compressing the viable supplier base to equipment-heavy processors.
EMA novel food approval pathways are tightening evidentiary requirements for health claim substantiation on cocoa polyphenol products. Extractors must now submit human clinical trial data rather than in-vitro antioxidant assays for cardiovascular positioning. Nutraceutical distributors in the Netherlands and Belgium are restructuring product launch timelines to accommodate eighteen-to-twenty-four-month regulatory review cycles.
Direct farm partnerships are displacing spot-market bean purchasing among large-scale extractors seeking EUDR-compliant documentation. Tier-one processors are embedding agronomists in Côte d'Ivoire and Ghana cooperatives to control fermentation protocols and secure traceable supply. This procurement model shift is most visible in German and Swiss chocolate processor supply chains, where sustainability officers now hold veto power over raw material sourcing decisions.
Cocoa Bean Extract Market Segmentation
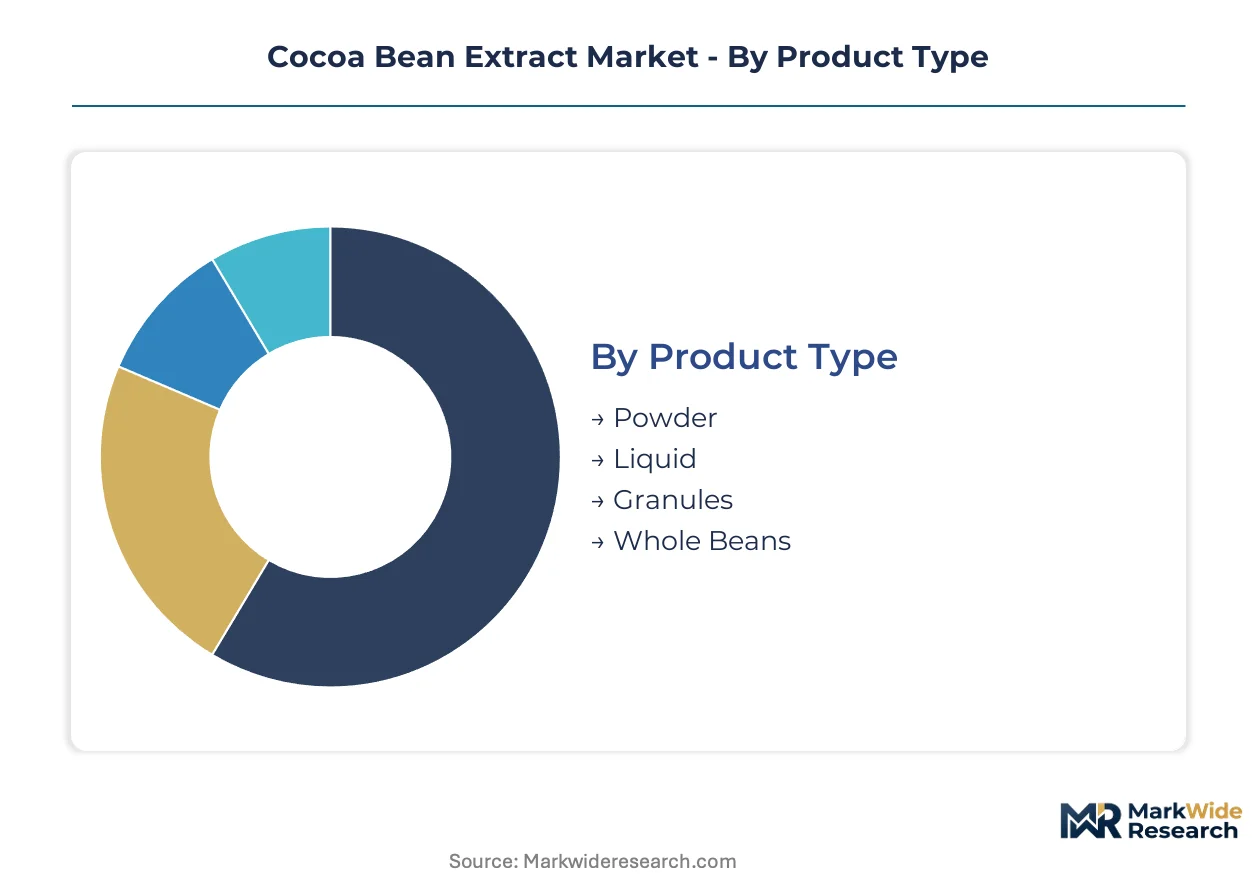
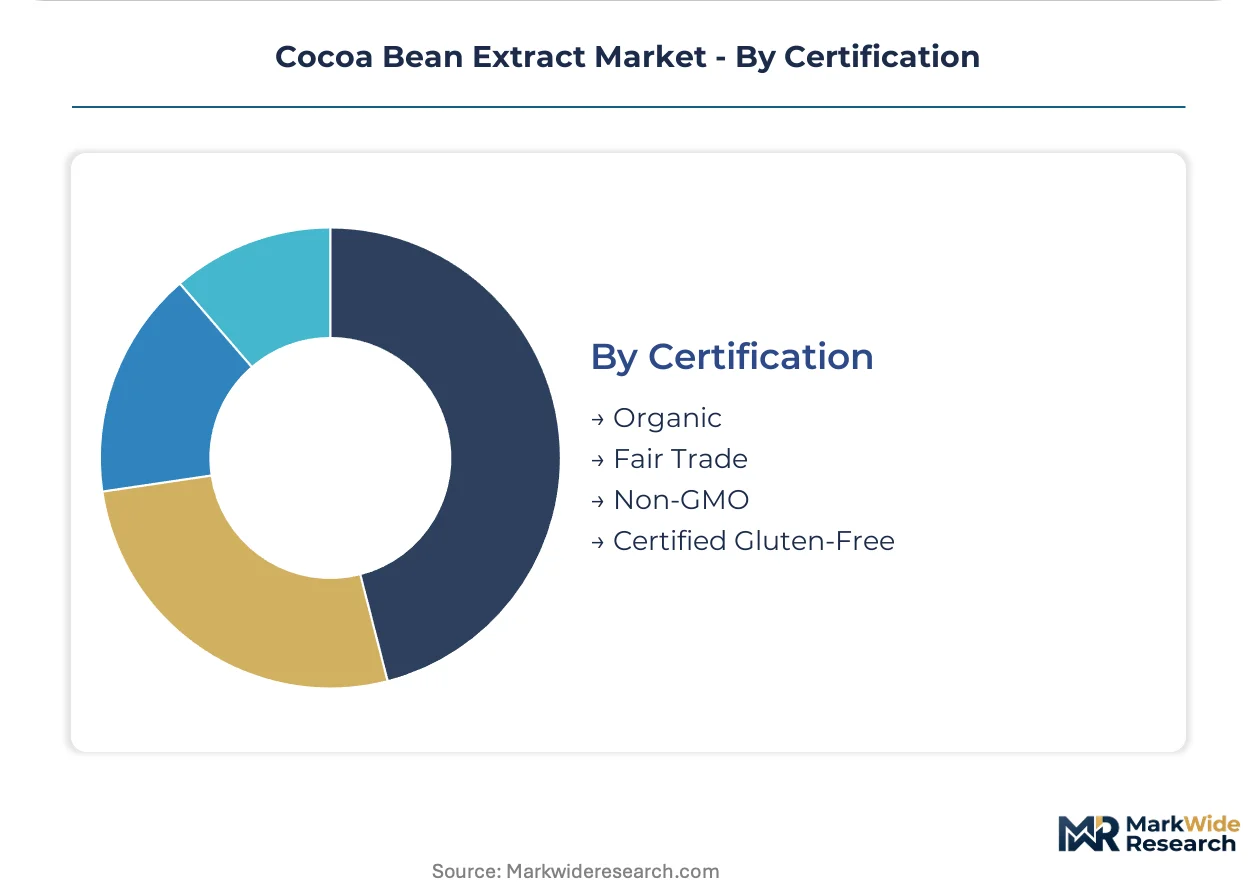
Cocoa bean extract procurement patterns diverge sharply across product formats and certification tiers, with extractors configuring production lines around stability requirements and regulatory compliance rather than volume maximization. Understanding these fault lines reveals where margin concentration and growth velocity separate winners from commodity players.
Product Type:
Supply concentration in extraction equipment shapes competitive access to each format, with supercritical CO2 capacity limiting premium liquid output to a handful of European and North American processors.
- Powder:Spray-dried or freeze-dried concentrates with standardized flavanol content between 10-20%, engineered for shelf-stable dry mixes and tablet compression. German chocolate processors and Dutch supplement formulators anchor procurement volumes, prioritizing batch-to-batch consistency for automated production lines.
- Liquid:Solvent or CO2-derived extracts in glycerin or ethanol carriers, specified for ready-to-drink functional beverages where rapid dissolution matters. Japanese nutraceutical manufacturers in Osaka and Tokyo are piloting theobromine-enriched cardiovascular formulations, driving the steepest expansion trajectory among all formats.
- Granules:Agglomerated particles balancing flowability with controlled release characteristics, serving encapsulation specialists in Switzerland and Italy.
- Whole Beans:Minimally processed fermented cacao for artisanal roasters and small-batch extractors seeking terroir-specific polyphenol profiles.
Today's leader: Powder. Tomorrow's challenger: Liquid.
Application:
Margin tiers stratify applications by regulatory burden and formulation complexity, with pharmaceutical pathways demanding eighteen-to-twenty-four-month approval cycles that filter out undercapitalized suppliers.
- Food & Beverage:Clean-label reformulation in functional beverages, protein bars, and dairy alternatives, with EFSA novel food approvals governing health claim deployment. Swiss and German manufacturers lead substitution of synthetic additives with cocoa-derived flavanols.
- Cosmetics:Dermal application products specifying CO2-derived flavanol concentrates to eliminate REACH-scrutinized solvent residues. French formulators in Grasse and German skincare brands in Hamburg drive premium positioning.
- Pharmaceuticals:API-grade extracts for cardiovascular and metabolic therapeutic candidates, requiring EMA-compliant GMP manufacturing and human clinical trial substantiation.
- Nutraceuticals:Dietary supplement capsules and powders, where ethical sourcing credentials influence procurement decisions among Dutch and Belgian distributors.
Food & Beverage commands current volume. Nutraceuticals capture expanding margin pools.
End User:
Procurement authority is shifting from spot-market traders to sustainability officers embedded in direct farm partnerships, restructuring how extraction capacity gets allocated across buyer types.
- Manufacturers:Tier-one processors with captive extraction infrastructure or long-term tolling agreements, including German chocolate processors and Swiss nutraceutical formulators requiring EUDR-compliant documentation chains.
- Retailers:Private-label specialists and specialty food chains sourcing certified organic extracts for store-brand supplement lines, concentrated in German and Austrian markets.
- Distributors:Regional wholesalers aggregating small-batch orders for mid-tier cosmetic and food manufacturers, facing margin compression from traceability cost pass-throughs.
- Foodservice:Artisanal chocolate makers and specialty beverage operators seeking single-origin extracts with verifiable fermentation protocols.
Manufacturers dictate terms today. Retailer direct-sourcing models are gaining negotiation leverage fastest.
Certification:
Certification premiums reflect compliance cost structures and procurement priority shifts, with organic and fair trade credentials becoming baseline requirements rather than differentiators in European channels.
- Organic:EU organic status requiring three-year farm conversion periods, creating supply-demand mismatches as certified-hungry formulators face immediate procurement needs. German and Austrian buyers pay substantial premiums for compliant extracts.
- Fair Trade:Farmgate price guarantees and cooperative governance standards, specified by Swiss and Dutch chocolate processors embedding sustainability officers in sourcing decisions.
- Non-GMO:Identity preservation systems from bean to extract, critical for US-bound shipments where FDA disclosure requirements apply.
- Certified Gluten-Free:Cross-contamination protocols for co-manufacturing facilities, demanded by celiac-safe supplement formulators in Italy and Spain.
Organic certification anchors current premium structures. Fair Trade is expanding fastest as EUDR enforcement tightens due diligence requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale cocoa processing originated in the Netherlands during the nineteenth century, establishing European expertise in bean fermentation and extraction chemistry that persists today. Germany and Switzerland subsequently developed specialized supercritical CO2 extraction infrastructure, while West African cultivation patterns fixed raw material geography. Contemporary demand clusters reflect this bifurcated heritage between processing technology centers and origin-country supply bases.
Germany
Chocolate processors in Hamburg and Cologne drive powder extract procurement for automated production lines, while cosmetic formulators in the Rhine-Ruhr region specify CO2-derived flavanol concentrates. EUDR enforcement through German customs authorities is accelerating farm-level verification investments among importers. The Baden-Württemberg machinery cluster around Stuttgart supplies high-pressure extraction vessels to domestic and export markets.
Switzerland
Nutraceutical formulators in Basel and Zurich anchor premium liquid extract demand for cardiovascular health positioning, with sustainability officers holding veto power over raw material sourcing. Swissmedic maintains stringent GMP requirements for pharmaceutical-grade extract manufacturing that filter out undercapitalized suppliers. The Lake Geneva corridor hosts bean-to-bar chocolate makers piloting single-origin extraction protocols with traceable fermentation documentation.
Côte d'Ivoire
Smallholder cooperatives in the Sud-Comoé and Lôh-Djiboua regions supply seventy percent of European-bound beans, with fermentation protocol upgrades elevating flavanol retention rates. The Conseil du Café-Cacao enforces minimum farmgate prices that transmit through fair trade certification premiums. Abidjan-based exporters are embedding blockchain-enabled tracking systems to satisfy EUDR traceability requirements for German and Swiss processors.
United States
FDA GRAS frameworks govern cocoa derivative approvals for functional beverage manufacturers in California and New York, creating divergent testing requirements from European pathways. Private-label supplement specialists in the Pacific Northwest source certified organic extracts for store-brand lines targeting ethical procurement preferences. Chicago-based distributors aggregate mid-tier orders while facing margin compression from traceability cost pass-throughs.
Japan
Functional food manufacturers in Osaka and Tokyo are piloting theobromine-enriched formulations for cardiovascular health claims, driving the steepest liquid extract expansion trajectory. METI guidelines on novel food substantiation require human clinical trial data rather than in-vitro antioxidant assays. The Kansai region's beverage conglomerates are reformulating ready-to-drink products with clean-label cocoa derivatives to replace synthetic additives.
Cocoa Bean Extract Market Vendor Landscape
Capital-heavy processors with captive bean-to-extract infrastructure compete with asset-light formulators relying on tolling agreements and spot-market sourcing. The supplier base concentrates among integrated chocolate manufacturers and specialized extraction houses, with mid-tier distributors facing compression from traceability cost pass-throughs. Three archetypes dominate: vertically integrated bean processors controlling fermentation protocols, equipment-heavy CO2 extraction specialists, and sustainability-certified organic operators. Competitive moves center on direct farm partnership expansion for EUDR compliance and supercritical capacity additions to capture premium cosmetic and nutraceutical demand.
Within the integrated processor tier, Barry Callebaut and Cargill exemplify archetypes of bean-to-extract infrastructure deployment. Barry Callebaut leverages Swiss-origin technical expertise across multiple geographies, while Cargill's US-based structure anchors direct farmer partnership models in West African supply bases. Olam International occupies a position emphasizing sustainability certification breadth, representing the sustainability-certified operator archetype that competes on ethical sourcing credentials rather than captive processing scale.
| Leading Market Players |
|---|
| Barry Callebaut |
| Cargill |
| Olam International |
| Blommer Chocolate Company |
| Naturex (Givaudan) |
| Nestlé |
| Mondelez International |
| ECOM Agroindustrial |
| Nexira |
| Others |
Supply Flow & Price Mechanics
Captive bean-to-extract infrastructure anchors both supply security and pricing power for tier-one processors, while tolling-dependent operators absorb margin compression from traceability cost pass-throughs. German chocolate manufacturers and Swiss nutraceutical formulators leverage direct farm partnerships in Côte d'Ivoire and Ghana to secure EUDR-compliant documentation chains that command premium positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CO2-derived organic extracts from solvent-based conventional grades and spot-market commodity lots. Price differentiation hinges on certification tier—EU organic and fair trade credentials command substantial premiums—and volume scale, with long-term offtake agreements smoothing input cost volatility. Pricing pressure stems from cocoa butter and powder commodity swings squeezing processor margins. Small-batch cosmetic formulators in France exhibit highest price sensitivity, while pharmaceutical-grade buyers in Basel tolerate premium positioning for GMP-compliant supply security.
Supply Chain Analysis
Reverse-logistics flows for certified organic cocoa involve three-year farm conversion documentation and blockchain-enabled batch recall systems that trace non-conforming inputs back to Sud-Comoé cooperatives. Raw material supply concentrates in Côte d'Ivoire, Ghana, and Nigeria, with fermentation protocol upgrades in West African smallholder networks elevating flavanol retention. The chain draws from high-pressure CO2 extraction equipment concentrated among German and Italian machinery suppliers, creating single-source vulnerability for premium liquid output. Distribution runs through Abidjan-based exporters embedding farm-level verification systems to satisfy German customs enforcement of EUDR traceability mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in certified organic extraction capacity and Japanese nutraceutical channel development, where supercritical CO2 infrastructure investments yield premium-tier positioning that outruns commodity input volatility.
For Market Incumbents: To counter EUDR compliance timeline compression threatening European market access, tier-one processors should embed agronomists in West African cooperatives to control fermentation protocols and secure traceable supply. Backward integration into high-pressure vessel engineering partnerships with Stuttgart-area machinery clusters reduces equipment procurement bottlenecks constraining facility expansion. For New Entrants and Emerging Players: Nutraceutical distributors in Osaka and Tokyo represent the most penetrable channel, with METI novel food approval pathways creating eighteen-to-twenty-four-month regulatory moats that favor agile specialists over incumbent bureaucracies. A certification-first go-to-market angle—securing EU organic status through three-year farm conversion partnerships—unlocks premium positioning in Dutch and Belgian supplement channels where ethical sourcing drives procurement decisions. For Investors and Strategic Acquirers: Roll-up economics work for sustainability-certified organic operators because EUDR enforcement is consolidating procurement authority among sustainability officers who veto non-compliant suppliers. Five-to-ten-year viability favors extractors with captive bean-to-extract infrastructure over tolling-dependent formulators. The signal to watch is German customs EUDR enforcement intensity, which will accelerate farm-level verification investments and compress spot-market supplier margins.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Farm Partnership Expansion | Barry Callebaut's embedded agronomists in Ghana secure EUDR-compliant traceability chains for German processors. |
| Supercritical CO2 Capacity Addition | Equipment-heavy processors capture premium cosmetic demand from Grasse formulators specifying solvent-free flavanol concentrates. |
| Organic Certification Pipeline Investment | Three-year farm conversion timelines in Côte d'Ivoire mismatch immediate certified-hungry formulator demand in Austria. |
| Blockchain-Enabled Provenance Tracking | Abidjan exporters merge distributed ledger systems with mass spectrometry authentication for tamper-proof cosmetic buyer documentation. |
| Japanese Nutraceutical Channel Entry | Osaka beverage conglomerates pilot theobromine-enriched cardiovascular formulations requiring liquid extract supply security. |
Methodological Framework
Coverage spans Germany, Switzerland, Côte d'Ivoire, Japan, and the United States, with primary inputs from each market combining interviews with extraction chemists, sustainability officers at chocolate processors, West African cooperative agronomists, and Dutch nutraceutical distributors. Secondary validation drew from EUDR implementation guidance, EMA novel food approval databases, Swissmedic GMP inspection records, and METI functional food substantiation guidelines. Bottom-up volume modeling triangulated against top-down value estimates across certification tiers.
Granularity-level modeling disaggregated volume and value across the projection horizon by product format, application, and certification status, with additional dimensioning for extraction technology type and regional regulatory cluster. CAGRs were derived from segment-level growth rate synthesis rather than single-point extrapolation. Industry-specific forecast inputs included cocoa commodity price volatility assumptions and EUDR enforcement phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to West African climate shocks, EUDR due diligence law evolution, and supercritical equipment supplier capacity constraints. Practitioners should monitor German customs EUDR inspection intensity, Ghanaian farmgate price negotiations, and Japanese METI novel food approval timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cacao Extracts Market
Ingredients
Black Cumin Seed Oil Market
Ingredients
Arrowroot Starch Market
Ingredients
Plant Sterols and Esters Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Ximenia Oil Market
Ingredients
Corn Oil Cake Market
Ingredients
North America Carrageenan Market
Ingredients
United States Avocado Oil Market
Ingredients
Yeast and Yeast Extract Market
Ingredients
Global Infant Nutrition Ingredients Market
Ingredients
Horny Goat Weed Extract Market
Ingredients
Agarwood Oil Market
Ingredients
Cheese Cultures Market
Ingredients
Bouillon Cubes Market
Ingredients
Beef Concentrate Market