
 Coating Resins Market | 2026-2036
Coating Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Coating Resins Market Intelligence
ISO 12944 corrosion-protection certification for protective coatings is collapsing the competitive field to suppliers with proven long-cycle testing capabilities. BASF SE leverages its integrated acrylic acid chain to secure raw material continuity across European and Asian plants. Arkema SA differentiates through specialty polyamide and fluoropolymer resin architectures for marine and industrial applications. Dow Inc. anchors North American supply with broad epoxy and polyurethane portfolios serving construction and vehicle assembly end users.
Coating resins are film-forming polymers—typically acrylic, epoxy, alkyd, or polyurethane chemistries with molecular weights between 10,000 and 100,000 g/mol—dispersed in liquid, powder, or emulsion form to create protective and decorative surface layers. These binders cure through oxidation, cross-linking, or solvent evaporation to deliver adhesion, hardness, and chemical resistance across substrates. Acrylic resins dominate architectural applications where exterior durability and color retention command premium positioning, while polyurethane formulations capture expanding share in automotive OEM clearcoats due to scratch resistance and gloss stability. Epoxy systems retain structural importance in marine and industrial machinery segments despite slower growth, as their two-component application complexity limits substitution in heavy-duty corrosion protection.
EPA VOC regulations in the United States restrict solvent-borne resin content, compelling reformulation toward waterborne and high-solids alternatives. REACH registration requirements and the EU Green Deal carbon-border adjustments in Europe impose lifecycle documentation burdens that favor producers with established environmental product declarations. China's MEE enforcement of dual carbon goals tightens emissions permits for alkyd and solvent-based manufacturing in the Yangtze and Pearl River deltas. Stakeholders must monitor regulatory divergence across these jurisdictions to align product development, certification investments, and regional capacity planning without assuming harmonized compliance pathways.
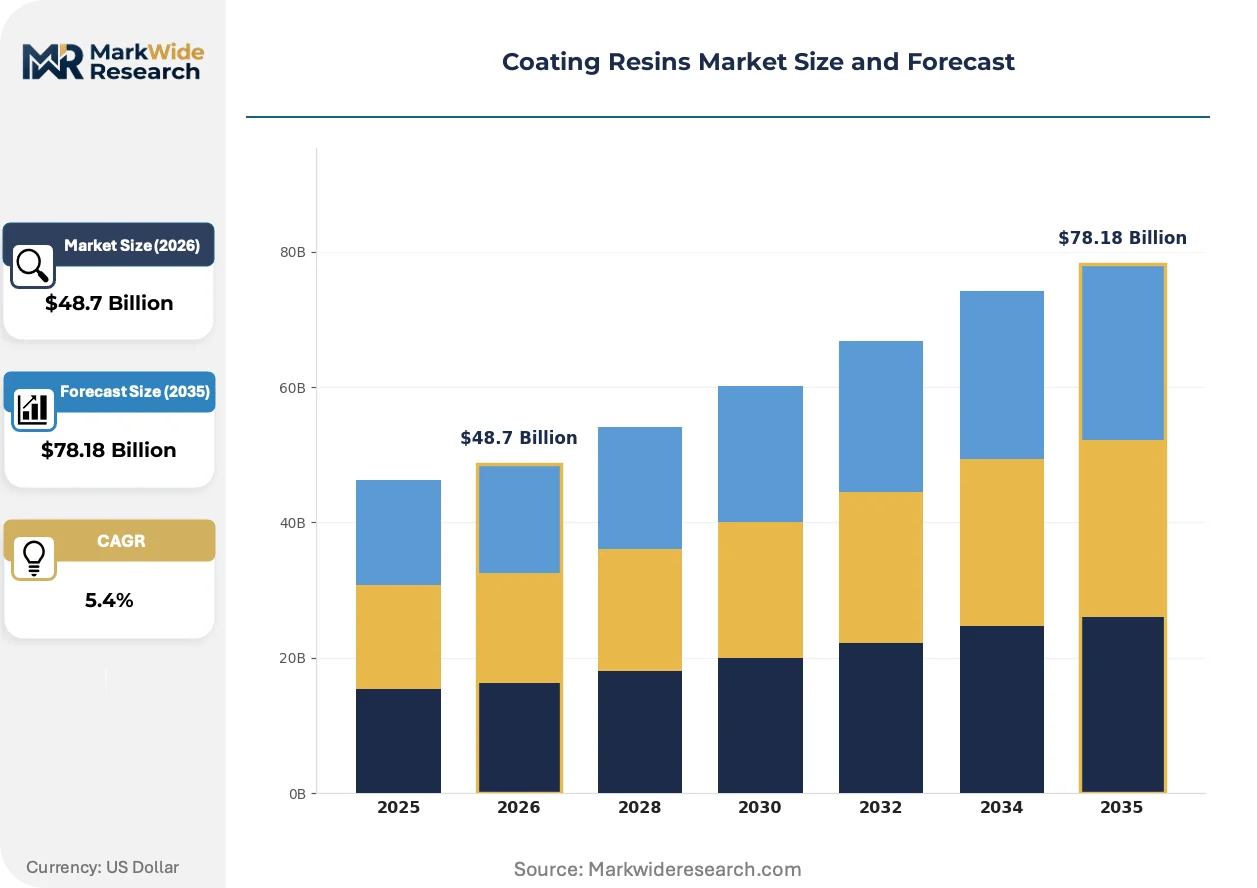
Market Dynamics
Automotive OEMs are consolidating coating specifications around ISO 12944-certified systems, collapsing supplier lists to those with proven long-cycle corrosion testing capabilities and forcing mid-tier resin producers into specialty niches or exit.
Growth Catalysts
- EU Green Deal carbon-border adjustments:European importers now face lifecycle documentation requirements that favor domestic and EPD-certified resin producers, accelerating facility upgrades across Germany, France, and the Netherlands.
- Waterborne acrylic substitution:Architectural coatings manufacturers in China are converting solvent-based lines to emulsion systems ahead of MEE enforcement in the Yangtze River delta.
- Marine coating specification tightening:Shipyards in South Korea and Japan are mandating higher solids-content epoxy and polyurethane formulations to meet IMO 2023 anti-fouling standards.
Market Restraints
- Propylene oxide supply concentration:Polyether polyol production for polyurethane resins depends on feedstock from integrated petrochemical complexes in the US Gulf Coast and Middle East, exposing formulators to margin compression during olefin volatility cycles.
- Two-component epoxy application complexity:Industrial machinery OEMs continue specifying these systems for heavy-duty protection, but the pot-life limitation and skilled-labor requirements constrain adoption in cost-sensitive construction segments.
- Bisphenol A regulatory scrutiny:ECHA's ongoing substance evaluation and state-level restrictions in California and Washington are forcing reformulation investments in can and coil coating segments.
Strategic Opportunities
- India construction chemicals penetration:Infrastructure spending under the PLI scheme and Smart Cities Mission is creating first-mover advantage for acrylic and epoxy resin suppliers establishing local blending operations.
- UV-curable powder convergence:Furniture and flooring manufacturers are piloting hybrid systems combining instant cure with zero-VOC profiles, opening premium positioning in European decorative segments.
- Digital tinting platform integration:Paint retailers in Brazil and Mexico are adopting cloud-based color-matching systems that lock in proprietary resin formulations through embedded software dependencies.
Industry Challenges
- ISO 12944 Part 6 certification timelines:Laboratory corrosion testing to 15-year durability claims requires 6,000+ hour exposure cycles, creating 18-24 month product validation gaps that delay market entry.
- Legacy alkyd line conversion:Southeast Asian producers face stranded asset risk as waterborne system investments compete for capital against established solvent-based capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coating Resins Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $78.18 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Alkyd, Polyurethane, Polyester, Phenolic Application: Architectural, Marine, Wood Finishing, Automotive OEMs, Coil Coating, Industrial Machinery Form: Liquid, Powder, Emulsion, Solid, Paste End User Industry: Construction, Shipbuilding, Furniture Manufacturing, Vehicle Assembly, Metal Fabrication |
| Companies Covered | Dow Inc., Allnex GmbH, BASF SE, Arkema SA, Covestro AG, Huntsman International, PPG Industries, Akzo Nobel, Synthomer plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coating Resins Market Strategic Shifts & Innovations
Coating resin technology is bifurcating between commodity waterborne platforms scaled for volume construction markets and specialty high-performance systems capturing automotive and marine specification premiums.
Bio-based polyol feedstocks derived from castor oil and soybean oil are supplanting petroleum-derived equivalents in polyurethane formulations. European automotive OEMs have accelerated qualification timelines for these materials from 36 months to 18 months. The shift is compressing the addressable market for conventional polyether polyols in premium clearcoat segments while opening supply partnerships with agricultural processors.
REACH registration requirements for polymer intermediates are tightening substance volume thresholds and extending data-sharing obligations. Formulators importing base resins into the European Economic Area now face consolidated dossier costs that favor larger producers with existing consortia memberships. Specialty polyurethane and fluoropolymer segments are absorbing the steepest compliance cost increases, driving regional sourcing from Arkema's French and Spanish facilities.
Direct procurement relationships between automotive OEMs and resin suppliers are displacing traditional paint manufacturer intermediaries in specification-setting. Tier-1 suppliers in Germany and Japan are losing technical influence as vehicle assemblers internalize coating chemistry selection to secure supply continuity. The pattern is most pronounced in electric vehicle platforms where thermal management coatings require co-development between battery pack engineers and resin R&D teams.
Coating Resins Market Segmentation
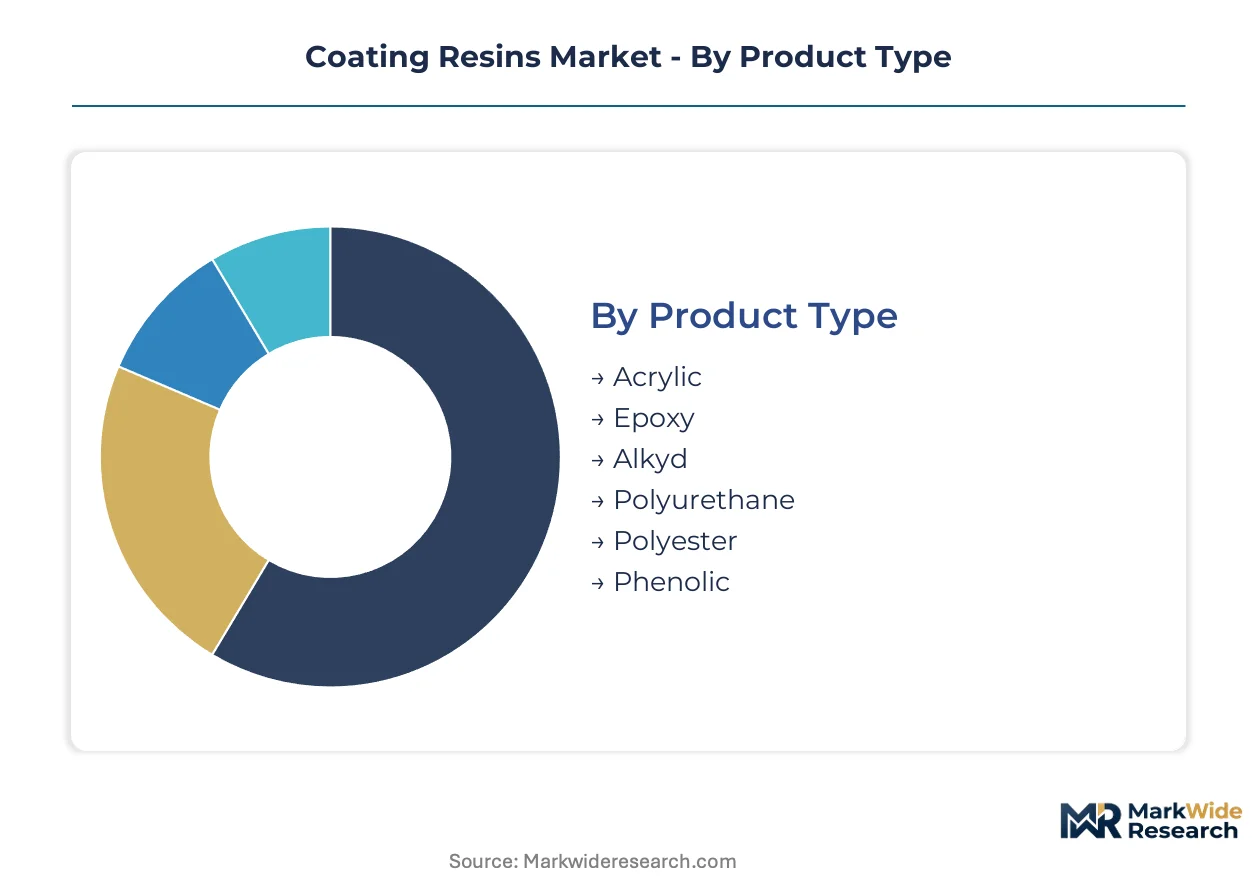
Coating resin selection determines regulatory compliance pathways, application economics, and performance certification eligibility across end-use sectors. Segmentation reveals where formulation investments concentrate versus where commodity substitution erodes margin.
Product Type:
REACH registration thresholds and carbon-border documentation requirements in Europe favor producers with established environmental product declarations and integrated feedstock chains.
- Acrylic:Thermoplastic copolymers derived from acrylic acid, methacrylic acid, and ester monomers deliver exterior durability and UV stability. Demand concentrates in Chinese architectural coatings where MEE enforcement in the Yangtze River delta accelerates waterborne emulsion conversions.
- Polyurethane:Polyether and polyester polyol backbones cross-linked with isocyanate hardeners provide scratch resistance and gloss retention. Automotive OEM clearcoats in Germany and Japan specify these systems for electric vehicle platforms requiring thermal management coating compatibility.
- Epoxy:Bisphenol A and epichlorohydrin condensation polymers cured with amine or anhydride hardeners. Marine and industrial machinery applications in South Korea dominate despite two-component application complexity.
- Alkyd:Oil-modified polyester resins curing through oxidative cross-linking. Southeast Asian producers face stranded asset risk as waterborne investments compete against established solvent-based capacity.
- Polyester:Saturated and unsaturated formulations for powder coating and coil applications. Metal fabrication end users in India specify these for infrastructure projects under the PLI scheme.
- Phenolic:Formaldehyde-condensed resins for heat-resistant and chemically inert coatings. Niche applications in industrial machinery and can coatings persist despite regulatory scrutiny of formaldehyde emissions.
Established volume favors acrylic; emerging adoption favors polyurethane.
Application:
Customer procurement patterns split between specification-driven OEM relationships and price-sensitive distributor channels.
- Architectural:Exterior and interior decorative coatings for residential and commercial buildings. Waterborne acrylic emulsions displace solvent-based systems in China ahead of MEE dual carbon enforcement.
- Automotive OEMs:Electrocoat, primer, basecoat, and clearcoat systems for vehicle assembly lines. Direct procurement relationships between assemblers and resin suppliers are displacing traditional paint manufacturer intermediaries in specification-setting.
- Marine:Anti-corrosive and anti-fouling coatings for ship hulls, decks, and ballast tanks. IMO 2023 standards drive higher solids-content epoxy and polyurethane formulations in South Korean and Japanese shipyards.
- Industrial Machinery:Protective coatings for manufacturing equipment, agricultural machinery, and infrastructure assets. ISO 12944 Part 6 certification requirements collapse supplier lists to those with proven long-cycle corrosion testing capabilities.
- Coil Coating:Continuous coating lines for metal sheets used in construction appliances and automotive components. Bisphenol A regulatory scrutiny from ECHA and California state agencies forces reformulation investments.
- Wood Finishing:Decorative and protective coatings for furniture, flooring, and joinery. UV-curable powder hybrid systems are gaining traction in European decorative segments for instant cure with zero-VOC profiles.
Specification premiums concentrate in automotive OEM; volume scale concentrates in architectural.
Form:
Environmental compliance trajectories in the US, Europe, and China are diverging formulation investments across liquid, solid, and dispersed systems.
- Liquid:Solvent-borne and waterborne resin solutions with adjustable viscosity for spray, dip, and flow-coat application. EPA VOC regulations restrict solvent-borne content, compelling reformulation toward waterborne and high-solids alternatives in the United States.
- Emulsion:Aqueous dispersions of acrylic, polyurethane, or hybrid polymers stabilized with surfactants. Chinese architectural manufacturers are converting solvent-based lines to emulsion systems ahead of MEE enforcement in the Yangtze and Pearl River deltas.
- Powder:Thermoset or thermoplastic resin particles applied via electrostatic spray and cured through heat. Zero-VOC profiles align with EU Green Deal carbon-border adjustments favoring lifecycle-documented formulations.
- Solid:Unsaturated polyester and epoxy resin blocks for hot-melt or reactive processing. Marine and industrial applications in Japan specify solid epoxy for heavy-duty corrosion protection.
- Paste:High-viscosity formulations with pre-dispersed pigments and fillers for trowel or knife application. Niche construction and repair segments in Brazil and Mexico utilize these for manual coating operations.
Regulatory pressure favors emulsion; performance premiums favor powder.
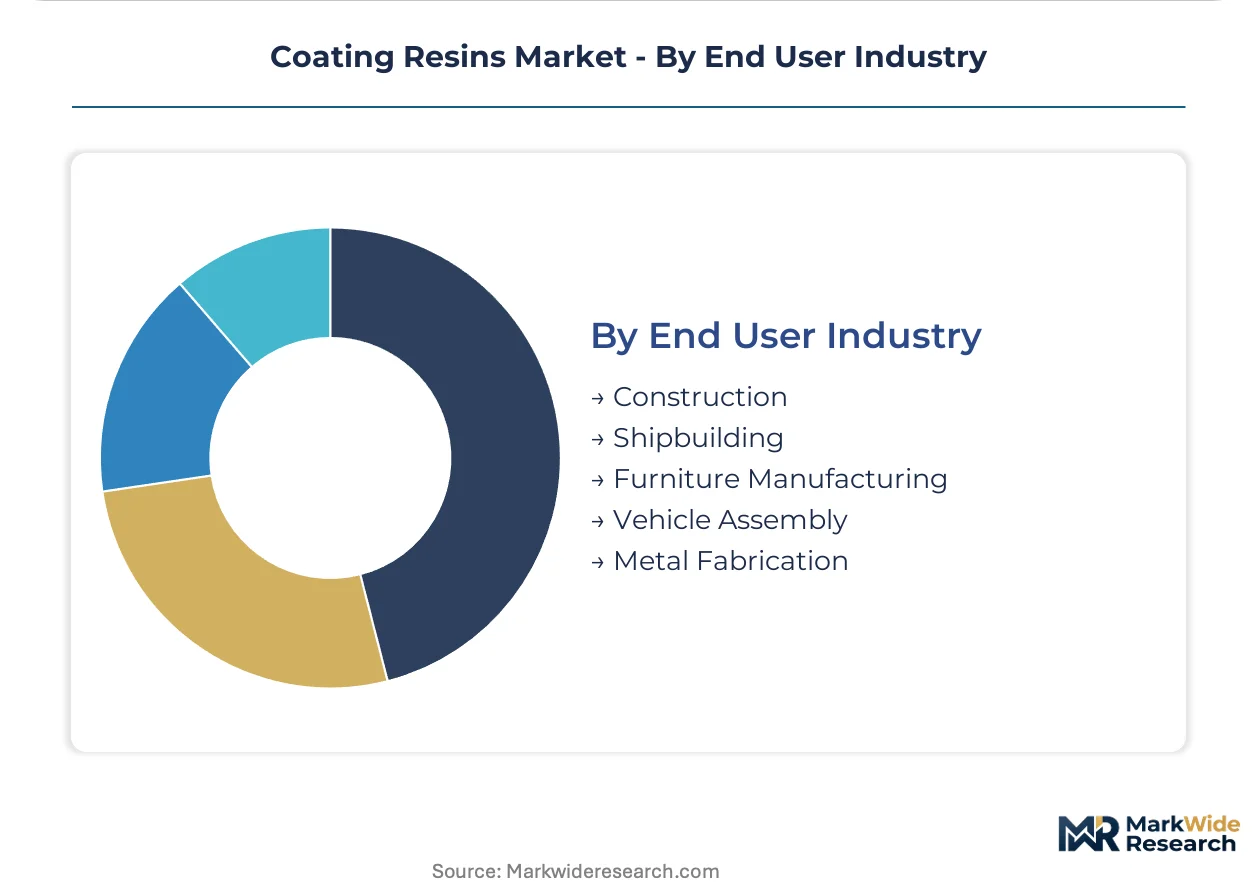
End User Industry:
Capital expenditure cycles and infrastructure investment programs determine regional demand timing and resin specification intensity.
- Construction:Residential, commercial, and infrastructure building projects driving architectural and protective coatings consumption. India's Smart Cities Mission and PLI scheme for construction chemicals create first-mover advantage for suppliers establishing local blending operations.
- Vehicle Assembly:Passenger car, commercial vehicle, and electric vehicle manufacturing requiring OEM coating systems. Battery pack engineers co-develop thermal management coatings with resin R&D teams, internalizing chemistry selection at German and Japanese assemblers.
- Shipbuilding:New vessel construction and maintenance coating for commercial and naval fleets. South Korean shipyards mandate higher solids-content formulations to meet IMO 2023 anti-fouling standards.
- Furniture Manufacturing:Residential and commercial furniture production utilizing wood finishing and decorative coatings. European furniture manufacturers pilot UV-curable powder convergence combining instant cure with zero-VOC profiles.
- Metal Fabrication:Steel and aluminum processing for construction, appliance, and automotive components. Coil coating specifications in Germany and France absorb compliance cost increases from REACH registration requirements for polymer intermediates.
Volume concentration favors construction; technology co-development favors vehicle assembly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and construction chemical buyers concentrate procurement decisions in manufacturing clusters where regulatory enforcement is tightening. Resin suppliers must align facility investments with jurisdiction-specific compliance timelines rather than assuming harmonized standards.
China
Construction and industrial machinery sectors drive substantial volume consumption of acrylic and epoxy formulations. MEE enforcement of dual carbon goals tightens emissions permits for alkyd and solvent-based manufacturing in the Yangtze and Pearl River deltas. Shanghai and Guangdong province manufacturers are converting solvent-based lines to waterborne emulsion systems ahead of regulatory deadlines.
Germany
Automotive OEM clearcoats and industrial machinery coatings command specification premiums from domestic vehicle assemblers. EU Green Deal carbon-border adjustments impose lifecycle documentation requirements that favor domestic and EPD-certified resin producers. BASF SE leverages integrated acrylic acid chains across Ludwigshafen and Schwarzheide plants to secure raw material continuity.
United States
Construction end users and automotive assembly plants anchor demand for epoxy and polyurethane portfolios. EPA VOC regulations restrict solvent-borne resin content, compelling reformulation toward waterborne and high-solids alternatives. Dow Inc. maintains North American supply breadth from integrated complexes along the US Gulf Coast.
Japan
Shipyards and automotive OEMs mandate higher solids-content epoxy and polyurethane formulations for corrosion protection. METI industrial standards align with IMO 2023 anti-fouling requirements for marine coating specifications. Kobe and Nagoya manufacturing clusters concentrate technical coating development for electric vehicle thermal management systems.
India
Infrastructure spending under the PLI scheme and Smart Cities Mission creates first-mover advantage for acrylic and epoxy resin suppliers. BIS certification requirements and construction chemical quality standards tighten import substitution timelines. Maharashtra and Gujarat industrial corridors attract local blending operations from multinational resin producers.
Coating Resins Market Key Industry Players
Player mix skews toward integrated petrochemical majors with captive feedstock positions and specialty chemical houses with specification-driven franchises. Market structure concentrates around three to five vertically integrated resin producers controlling critical acrylic acid and epoxy intermediate supply. Two strategic archetypes dominate: commodity-scale waterborne platforms serving construction volume, and performance-grade polyurethane and fluoropolymer systems capturing automotive and marine premiums. Competitive moves center on backward integration into olefin feedstocks and geographic expansion into enforcement-driven conversion markets.
Among integrated chemical majors, BASF SE, Dow Inc., and Arkema SA occupy positions spanning commodity and specialty tiers. BASF SE exemplifies the integrated archetype with captive acrylic acid chains across European and Asian manufacturing footprints. Dow Inc. anchors North American supply breadth through Gulf Coast petrochemical integration. Arkema SA represents the specialty-focused model with concentrated fluoropolymer and polyamide resin architectures serving specification-intensive marine and industrial segments.
| Leading Market Players |
|---|
| Dow Inc. |
| Allnex GmbH |
| BASF SE |
| Arkema SA |
| Covestro AG |
| Huntsman International |
| PPG Industries |
| Akzo Nobel |
| Synthomer plc |
| Others |
Cost & Logistics Intelligence
ISO 12944 Part 6 certification gates both supply qualification and price differentiation simultaneously, forcing resin producers to absorb 18-24 month validation costs that stratify pricing across corrosion-protection tiers. Buyers with 15-year durability specifications pay premiums for laboratory-proven systems while construction volume shifts toward commodity waterborne alternatives.
Pricing Analysis
Cost-plus contracts with propylene oxide indexation dominate polyurethane resin procurement, anchoring formulations to Gulf Coast olefin volatility. Three-tier pricing structure across premium, standard, and economy levels separates ISO-certified marine systems from architectural emulsions and generic alkyd replacements. Cost compression in solvent-borne tiers is intensifying because MEE enforcement in China accelerates waterborne conversion capex. Price-sensitive construction distributors in Southeast Asia resist specification premiums, while automotive OEMs in Germany and Japan accept thermal management coating premiums for electric vehicle platforms.
Supply Chain Analysis
Inventory cycles for epoxy intermediates stretch 8-12 weeks as bisphenol A and epichlorohydrin availability tightens around ECHA evaluation timelines. Supply concentrates in China, Germany, and the United States, with acrylic acid chains feeding waterborne emulsion demand across Asian construction markets. Raw material sourcing draws from integrated petrochemical complexes for olefin feedstocks, agricultural processors for bio-based polyols, and specialty chemical manufacturers for isocyanate hardeners. Single-source vulnerability around propylene oxide from US Gulf Coast and Middle Eastern complexes exposes formulators to margin compression. Distribution runs through direct procurement relationships with automotive OEMs and paint manufacturer intermediaries serving construction channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as bio-based polyol feedstocks compress addressable markets for petroleum-derived polyurethane clearcoats. Waterborne acrylic emulsions displace solvent-borne capacity faster than legacy producers can convert stranded assets.
For Market Incumbents: Consolidate backward integration into acrylic acid and epichlorohydrin intermediates to secure raw material continuity against olefin volatility. Lock in ISO 12944 certification pipelines with 6,000-hour testing investments that collapse competitor entry timelines. Prioritize capacity addition in Maharashtra and Gujarat industrial corridors to capture India infrastructure spending before local blending operations saturate procurement channels. For New Entrants and Emerging Players: ISO 12944 fast-track partnerships with German automotive OEMs offer specification entry points as direct procurement relationships displace traditional paint manufacturer intermediaries. Target UV-curable powder convergence in European furniture manufacturing where zero-VOC profiles command premium positioning. Penetrate India's Smart Cities Mission construction chemicals segment through BIS-certified local production partnerships rather than import-dependent distribution. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across waterborne emulsion systems as MEE enforcement mandates line conversion capex in China. Long-term viability favors producers with integrated feedstock positions spanning acrylic acid chains and captive epoxy intermediates. Acquisition target archetype: specialty polyurethane houses with fluoropolymer architectures serving IMO 2023 marine specifications. Watch for ECHA bisphenol A restriction signals that would force coil coating reformulation investments and consolidate supplier lists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | BASF's Ludwigshafen and Schwarzheide plants secure European supply continuity against feedstock volatility. |
| ISO 12944 Certification Investment | Long-cycle corrosion testing collapses competitive field to suppliers with proven 15-year durability claims. |
| Waterborne Line Conversion | Shanghai manufacturers absorb MEE dual carbon enforcement costs ahead of Yangtze River delta permit tightening. |
| Bio-based Polyol Partnership | European automotive OEMs compress qualification timelines from 36 months to 18 months for castor oil feedstocks. |
| Local Blending Operations in India | Maharashtra and Gujarat facilities capture PLI scheme infrastructure spending with BIS-certified construction chemicals. |
Research Approach
Desk research of customs trade data, ACC and Cefic industry reports, and SEC 10-K filings preceded structured interviews with plant managers at resin manufacturing facilities, procurement leads at automotive OEM coating divisions, distribution channel partners serving construction markets, and technical R&D directors developing thermal management formulations. Primary fieldwork with downstream formulators validated secondary estimates of waterborne conversion timelines and ISO certification backlog durations. Bottom-up segment sizing triangulated against top-down petrochemical demand forecasts.
Variance decomposition across product type, application, form, and end-use industry dimensions anchored volume and value outputs. Segmentation modeling captured grade tier differentiation between commodity waterborne platforms and specialty high-performance systems, end-use industry concentration in construction versus automotive specification intensity, and regional production hub clustering around enforcement-driven conversion markets. CAGRs derived from regression against macroeconomic drivers and regulatory compliance timeline assumptions. Forecast inputs incorporated MEE dual carbon enforcement schedules, EU Green Deal carbon-border adjustment implementation, and IMO 2023 anti-fouling standard adoption curves.
Decision-makers should treat outputs as directional under sustained regulatory enforcement timelines and feedstock price stability assumptions; material deviation in olefin volatility or certification timeline acceleration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Polyvinylidene Fluoride (PVDF) Coatings Market
Coatings
Coating Equipment Market
Coatings
Asia-Pacific Anti-Friction Coatings Market
Coatings
Perfluoroalkoxy (PFA) Coatings Market
Coatings
Electron Beam Curable Coating Market
Coatings
Global Polyurea Coating Market
Coatings
Global Automotive Specialty Coatings Market
Coatings
Global UV-Cured Coatings Market
Coatings
Global Metal Coatings Market
Coatings
Powder Coating Booth Market
Coatings
Japan Marine Coatings Market
Coatings
Stain Resistance Coatings Market
Coatings
Saudi Arabia Industrial Coatings Market
Coatings
Global Polytetrafluoroethylene (PTFE) Coatings Market
Coatings
Electrically Conductive Coating Market
Coatings
Electrical Insulation Coatings Market