
 Asia-Pacific Anti-Friction Coatings Market | 2026-2036
Asia-Pacific Anti-Friction Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Anti-Friction Coatings Market Outlook
Specialty chemical distribution across Southeast Asia is narrowing as regional distributors consolidate inventory positions around solvent-based and water-based formulations. DuPont leverages its fluoropolymer heritage to anchor premium PTFE supply relationships with Japanese automotive Tier 1s. Fuchs Petrolub SE competes through its tribology service network, while Aalberts Surface Technologies extends its coating application infrastructure into South Korean industrial zones.
Asia-Pacific anti-friction coatings comprise bonded solid-film lubricants, typically 5–50 microns thick, formulated with PTFE, molybdenum disulfide, or ceramic particles in thermosetting resin binders; these coatings reduce coefficient of friction to 0.02–0.20 while operating between -200°C and 450°C, serving primarily to extend component life and cut energy loss in mechanical assemblies. PTFE formulations dominate current volume owing to mature application protocols in automotive machinery, though graphene variants represent the fastest-expanding chemistry as thermal conductivity specifications tighten in electronics cooling applications. Water-based formulations now capture growing share from solvent-based systems as METI and China's MEE emissions protocols harden volatile organic compound limits across coating operations.
Japan's METI enforces JIS K 6891 fluoropolymer standards that constrain import qualification timelines, while China's MEE implements GB 30981 low-VOC content limits for industrial protective coatings that reshape formulation R&D priorities. India's BIS certification requirements for chemical imports add compliance layers for European suppliers entering the subcontinent. Stakeholders must monitor divergence between Japanese precision-specification regimes and China's scale-oriented environmental enforcement as they allocate technical service resources across the region.
Market Dynamics
Automotive electrification across China and Japan is compressing thermal management requirements, forcing coating formulators to engineer graphene-ceramic hybrids that dissipate heat while maintaining lubricity in compact electric powertrains.
Growth Catalysts
- China's dual carbon goals:MIIT production quotas for energy-efficient machinery accelerate replacement of solvent-based coatings with water-based PTFE formulations in Jiangsu manufacturing clusters.
- Powertrain electrification:Battery thermal interface materials demand coatings with 0.02-0.05 friction coefficients, pulling advanced molybdenum disulfide chemistries into Korean and Japanese EV supply chains.
- GB 30981 enforcement:China's MEE low-VOC mandates reshape R&D priorities, redirecting technical service resources toward compliant water-based resin systems.
Market Restraints
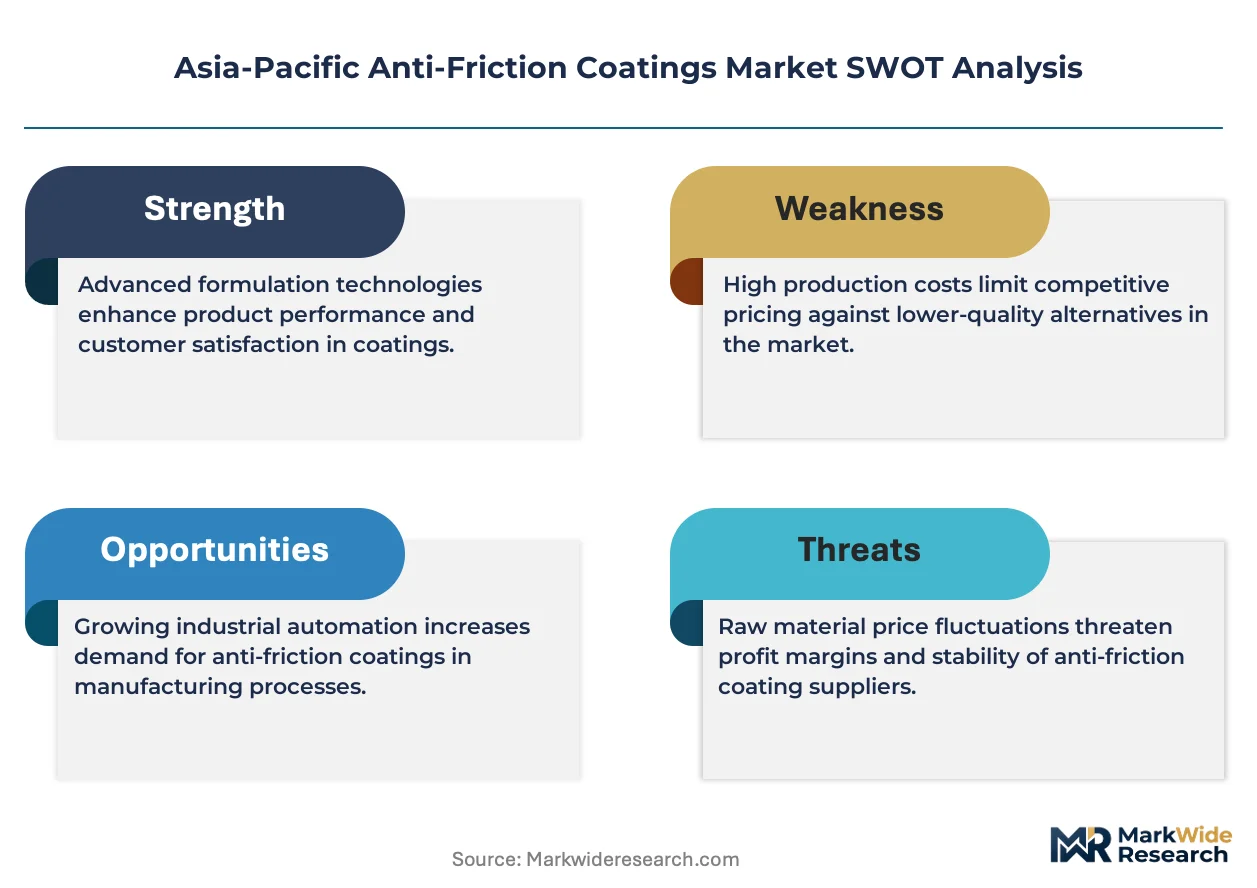
- Fluoropolymer feedstock concentration:PTFE precursor supply concentrates among three Japanese and Chinese chemical conglomerates, exposing coaters to price volatility and allocation risk.
- JIS K 6891 qualification timelines:METI fluoropolymer standards extend import certification cycles to 18-24 months, delaying European supplier market entry.
- Ceramic particle substitution:Hard chrome plating retains cost advantage in heavy-load industrial applications across India and Southeast Asia, limiting coating penetration.
Strategic Opportunities
- Vietnam industrial corridor expansion:Japanese and Korean automotive Tier 1s establish coating application facilities in Haiphong and Bac Ninh, creating captive demand for localized formulation supply.
- India PLI scheme for auto components:Domestic manufacturing incentives attract coating applicators to Tamil Nadu and Gujarat, opening technical service partnerships with emerging Indian machinery producers.
- 5G infrastructure thermal management:Base station heat sink specifications drive adoption of graphene-enhanced coatings in Chinese electronics manufacturing.
Industry Challenges
- Formulation chemist scarcity:Fluoropolymer compounding expertise concentrates among retiring Japanese specialists, constraining regional technical service expansion.
- Application equipment capex:Automated spray systems for 5-15 micron film control require $2-4 million facility investments, limiting mid-tier applicator scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Anti-Friction Coatings Market |
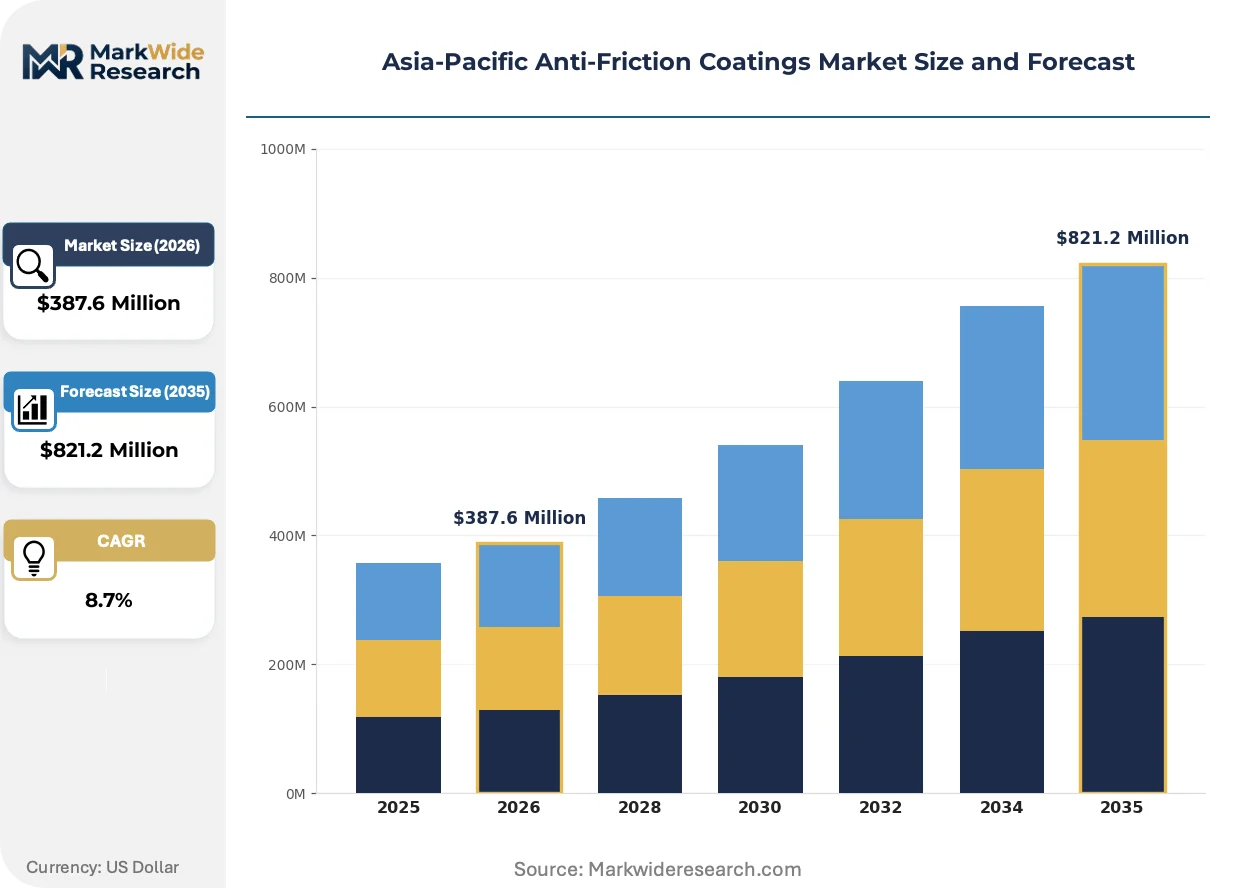
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, Graphene, Ceramics, Silicone End User: Automotive, Aerospace, Marine, Industrial Equipment Application: Machinery, Consumer Goods, Electronics, Medical Devices Formulation: Solvent-Based, Water-Based, Powder Coating, Liquid Coating |
| Companies Covered | DuPont, Carl Bechem GMBH, ASV Multichemie Private Limited, Endura Coatings, Poeton Industries Ltd., IKV Tribology Ltd., Aalberts Surface Technologies, Fuchs Petrolub SE, Parker Hannifin Corp, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Anti-Friction Coatings Market Strategic Shifts
Digital coating specification platforms and predictive wear modeling are compressing qualification cycles, while thermal conductivity requirements from electronics cooling applications pull graphene-ceramic hybrids into mainstream automotive consideration.
Hybrid graphene-PTFE formulations are virtualizing traditional ceramic-molybdenum thermal management architectures. Chinese EV battery manufacturers specify these coatings for cell-to-pack interfaces requiring simultaneous electrical insulation and heat dissipation. The technology is virtualizing legacy spray-and-bake application protocols into precision electrostatic deposition systems that reduce material waste.
METI's 2024 amendments to JIS K 6891 tighten perfluorinated compound disclosure thresholds for imported coatings. Japanese automotive Tier 1s now require complete formulation transparency from Korean and Chinese suppliers, extending qualification timelines. Korean coaters respond by establishing Tokyo-based regulatory compliance subsidiaries staffed with former METI officials.
Specification authority is migrating from procurement departments to tribology engineering teams embedded in automotive OEM design centers. Chinese and Japanese buyers now mandate coating performance warranties tied to component life rather than per-liter pricing, displacing spot-market purchasing. This shift concentrates contract volume among applicators with in-house wear-testing laboratories in Shanghai and Nagoya.
Asia-Pacific Anti-Friction Coatings Market Segmentation
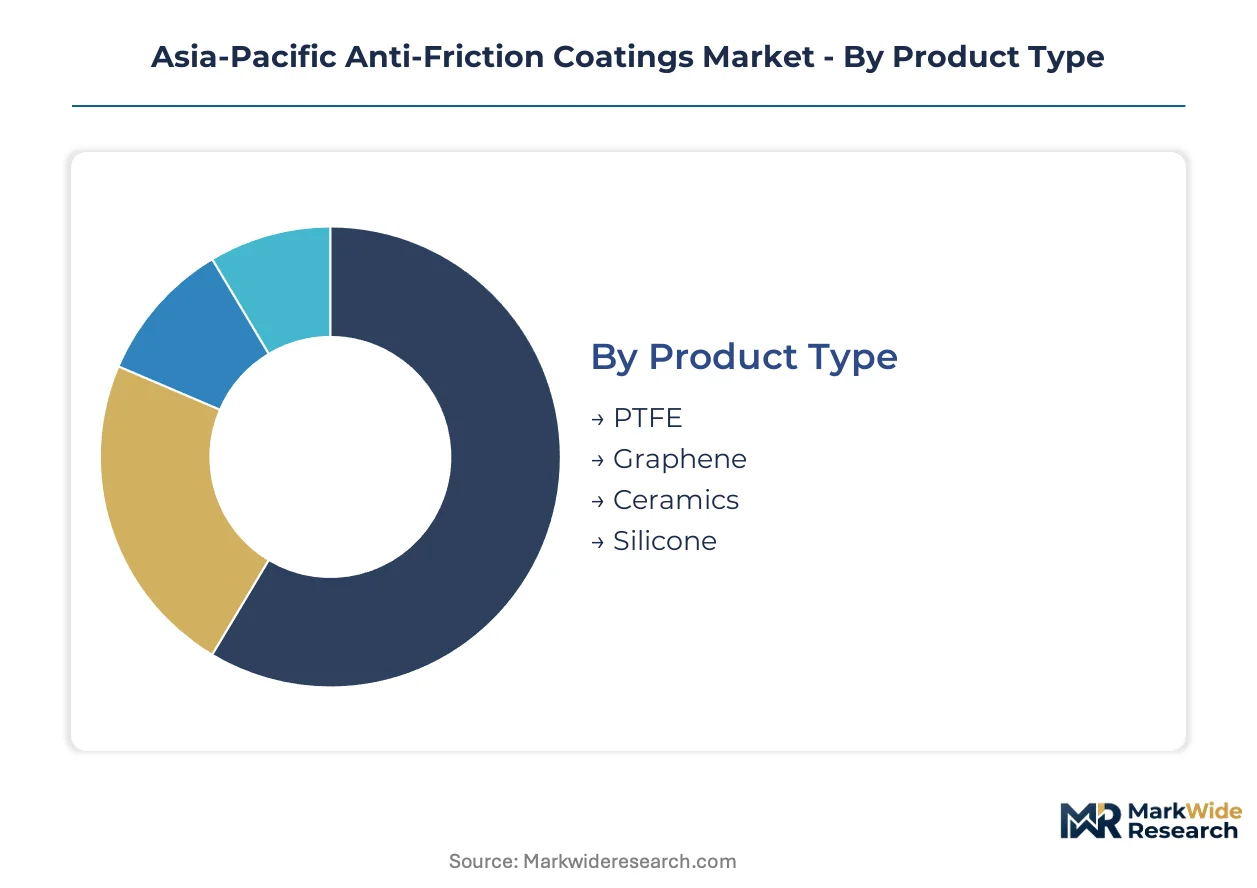
Segmentation reveals how coating specifications diverge across thermal loads, environmental compliance tiers, and application equipment requirements. Formulators must align R&D portfolios with the cycle-time disparities between automotive qualification programs and industrial maintenance schedules.
Product Type:
PTFE formulations turn inventory fastest through established automotive supply chains, while graphene coatings face extended validation cycles in electronics thermal management applications.
- PTFE:Fluoropolymer-based solid-film lubricants deliver coefficient of friction values between 0.02 and 0.20 across -200°C to 450°C operating windows. Chinese powertrain manufacturers in Jiangsu and Zhejiang provinces specify these formulations for transmission synchronizer rings and bearing races under MIIT energy-efficiency quotas.
- Graphene:Carbon lattice structures provide thermal conductivity exceeding 500 W/mK for battery cell-to-pack interfaces. Korean EV battery producers drive specification development as cell energy densities climb and thermal runaway protocols tighten.
- Ceramics:Oxide and nitride particle suspensions serve heavy-load industrial machinery in Indian steel and cement operations where abrasion resistance outweighs friction reduction priorities.
- Silicone:Organosiloxane binders flex across elastomeric substrates in Japanese automotive weatherseal applications, tolerating compression set under cyclic loading.
PTFE dominates installed base across automotive Tier 1 supply chains. Graphene is where expansion concentrates as thermal interface specifications harden in battery and 5G infrastructure applications.
End User:
Cost tier stratification separates specification-intensive automotive programs from price-sensitive industrial maintenance contracts.
- Automotive:Powertrain electrification compresses thermal management requirements into compact electric motor housings and reduction gearsets. Japanese and Korean OEMs now mandate 150,000-kilometer coating performance warranties.
- Aerospace:Landing gear and flight control actuators demand FAA-compliant formulations with traceable lot documentation. Singapore and Bangkok maintenance facilities drive aftermarket consumption.
- Marine:Salt-spray resistance specifications dominate propeller shaft and winch applications across Southeast Asian shipyards in Vietnam and Indonesia.
- Industrial Equipment:Mining conveyors and printing presses in Australia's Pilbara and China's Shanxi province prioritize cost-per-sq-meter over technical performance metrics.
Automotive commands premium formulation margins. Industrial Equipment is where volume expansion concentrates as Chinese machinery replacement cycles accelerate under dual carbon mandates.
Application:
Application geometry dictates film thickness precision requirements, with electronics demanding sub-10-micron control versus machinery tolerances above 25 microns.
- Machinery:Bearing races, gear teeth, and pump housings consume the majority of solvent-based PTFE volume. Japanese machine tool builders specify JIS K 6891-compliant formulations with 18-24 month qualification timelines.
- Consumer Goods:Cookware and appliance hinges utilize lower-temperature silicone variants with food-contact approvals from China's NMPA and Japan's Ministry of Health.
- Electronics:Heat sink and base station thermal interface materials pull graphene-ceramic hybrids into mainstream consideration as 5G infrastructure deployment accelerates.
- Medical Devices:Surgical instrument coatings require biocompatibility testing under MFDS and PMDA guidelines, extending development cycles to 36 months.
Machinery holds the largest installed coating base. Electronics is where formulation innovation concentrates as thermal conductivity specifications displace traditional lubricity metrics.
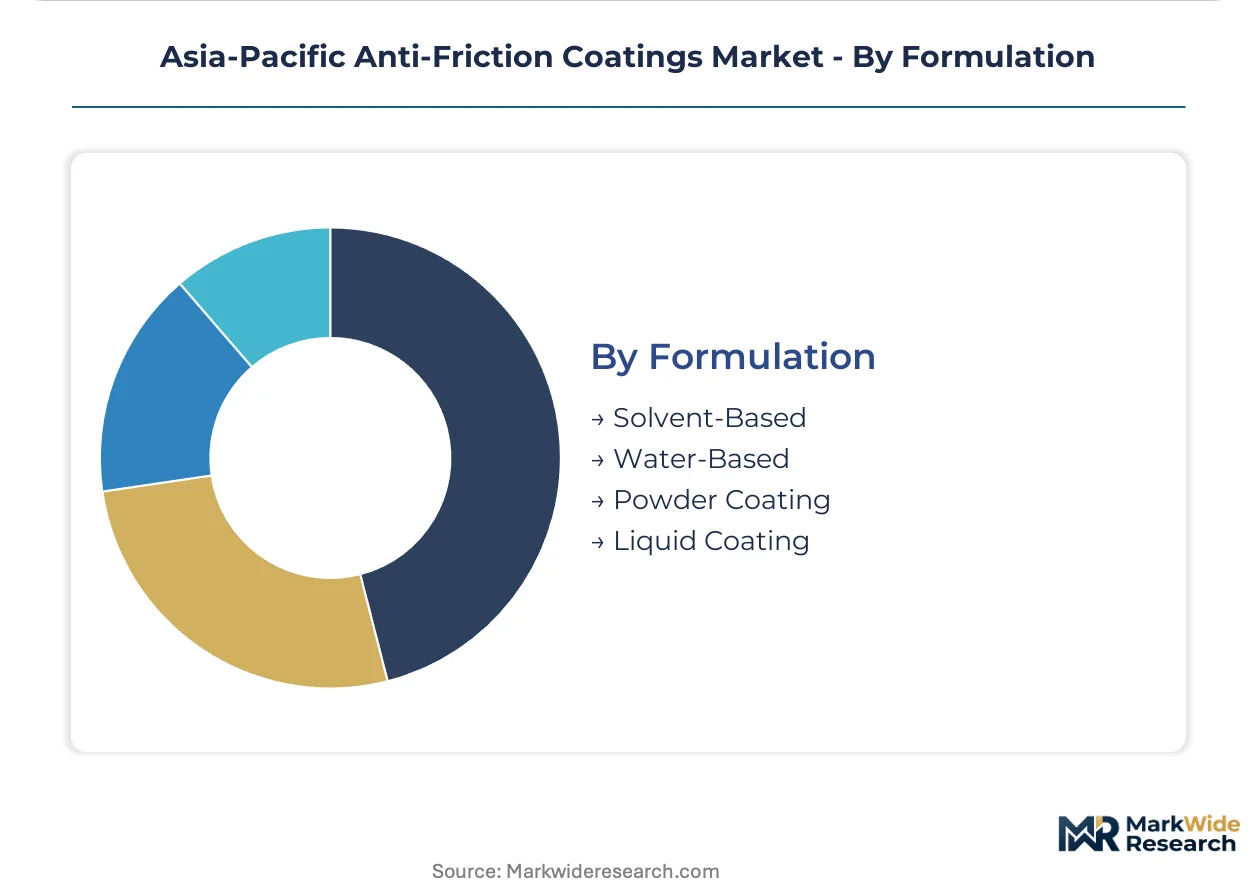
Formulation:
Environmental compliance tiering separates water-based systems qualifying for China's GB 30981 low-VOC mandates from legacy solvent-based production.
- Solvent-Based:Traditional resin systems using xylene and toluene carriers deliver proven adhesion on ferrous substrates. China's MEE enforcement is compressing permissible deployment to specialty aerospace and marine applications.
- Water-Based:Acrylic and epoxy emulsions now capture automotive machinery share as Jiangsu manufacturing clusters retool spray lines to meet dual carbon production quotas.
- Powder Coating:Thermosetting fluoropolymer powders serve architectural and heavy equipment applications where film builds exceed 50 microns.
- Liquid Coating:Dip and flow-coat processes dominate high-volume consumer goods manufacturing in Guangdong and Zhejiang provinces.
Solvent-Based retains aerospace and marine share where performance trumps compliance. Water-Based is where capacity expansion concentrates as METI and MEE protocols harden across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese precision-specification regimes while Chinese scale-oriented environmental enforcement compresses margins across solvent-based formulations. This asymmetry reshapes technical service resource allocation across the region.
China
MIIT production quotas for energy-efficient machinery accelerate water-based PTFE adoption across Jiangsu and Zhejiang manufacturing clusters. MEE enforcement of GB 30981 low-VOC content limits redirects R&D investment toward compliant resin systems. Eastern manufacturing corridors in Suzhou and Ningbo host the fastest coating line retooling activity.
Japan
METI's JIS K 6891 fluoropolymer standards constrain import qualification timelines to 18-24 months for European suppliers. Automotive Tier 1s now mandate complete formulation transparency from regional suppliers. Nagoya and Tokyo tribology engineering teams increasingly control specification authority previously held by procurement departments.
South Korea
EV battery manufacturers specify advanced molybdenum disulfide chemistries for thermal interface materials requiring 0.02-0.05 friction coefficients. MFDS guidelines extend medical device coating development cycles to 36 months. Korean coaters establish Tokyo-based regulatory compliance subsidiaries staffed with former METI officials.
India
BIS certification requirements for chemical imports add compliance layers for European suppliers entering the subcontinent. PLI scheme incentives for auto components attract coating applicators to Tamil Nadu and Gujarat. Domestic machinery replacement cycles accelerate under industrial efficiency mandates.
Vietnam
Japanese and Korean automotive Tier 1s establish coating application facilities in Haiphong and Bac Ninh industrial zones. Localized formulation supply demand emerges from captive manufacturing requirements. Marine coating consumption concentrates in Southeast Asian shipyards serving regional trade routes.
Asia-Pacific Anti-Friction Coatings Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in formulation and application equipment. The vendor base organizes around three strategic archetypes: fluoropolymer heritage suppliers, tribology service networks, and surface technology infrastructure extenders. Consolidation pressure concentrates among mid-tier applicators lacking automated spray system capabilities. Dominant competitive moves include geographic expansion into Vietnamese industrial corridors and portfolio diversification toward graphene-ceramic hybrids.
Within the fluoropolymer heritage tier, DuPont anchors premium PTFE supply relationships with Japanese automotive Tier 1s. Fuchs Petrolub SE exemplifies the tribology service network archetype, while Aalberts Surface Technologies occupies a position as surface technology infrastructure extender into South Korean industrial zones. These three represent distinct competitive postures: formulation chemistry control, technical service density, and application asset proximity respectively.
| Leading Market Players |
|---|
| DuPont |
| Carl Bechem GMBH |
| ASV Multichemie Private Limited |
| Endura Coatings |
| Poeton Industries Ltd. |
| IKV Tribology Ltd. |
| Aalberts Surface Technologies |
| Fuchs Petrolub SE |
| Parker Hannifin Corp |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Japanese and Chinese fluoropolymer conglomerates compresses both margin structures and procurement flexibility across the Asia-Pacific anti-friction coatings landscape. This concentration forces formulators to absorb feedstock volatility while buyers face extended allocation queues, widening spreads between spot-market solvent-based formulations and contracted water-based supply.
Pricing Analysis
Configured-to-order pricing for JIS K 6891-qualified PTFE formulations commands substantial premiums over standard water-based catalog offerings. Three-tier pricing structure across premium, standard, and economy levels separates METI-compliant Japanese automotive specifications from industrial maintenance grades in India and Southeast Asia. Cost compression in solvent-based tiers is intensifying because MEE enforcement of GB 30981 redirects volume toward compliant resin systems. Industrial Equipment buyers in Australia's Pilbara and China's Shanxi province exhibit highest price sensitivity, while Japanese automotive Tier 1s prioritize performance warranties over per-liter economics.
Supply Chain Analysis
Tariff exposure between China and key raw material sources elevates landed cost volatility for European formulation suppliers. PTFE precursor production concentrates in Japan, China, and South Korea, drawing from molybdenum mining operations in Chile and fluorite extraction in Mexico and Mongolia. Single-source vulnerability persists for graphene nanoplatelet supply anchored in Chinese producers. Distribution runs through regional chemical distributors consolidating inventory positions around solvent-based and water-based formulations, with technical service partnerships increasingly displacing spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and wear-testing warranties represent a service-attach opportunity expanding faster than base formulation volume. Tribology engineering engagements now generate recurring revenue streams that outpace hardware margins across Japanese and Korean automotive supply chains.
For Market Incumbents: Build regulatory compliance moats through Tokyo-based subsidiaries staffed with former METI officials. Deepen backward integration into fluoropolymer precursor supply to offset allocation risk from Japanese and Chinese chemical conglomerates. Capture Vietnamese industrial corridor expansion by establishing captive application facilities in Haiphong and Bac Ninh before emerging competitors secure Tier 1 relationships. For New Entrants and Emerging Players: India's Tamil Nadu and Gujarat industrial zones offer geographic underpenetration as domestic machinery replacement cycles accelerate under PLI scheme incentives. Target medical device coating development where MFDS and PMDA guidelines extend cycles to 36 months, creating barriers for impatient capital. Enter through technical service partnerships with emerging Indian machinery producers rather than direct formulation sales. For Investors and Strategic Acquirers: Regional tribology service networks with established wear-testing laboratories in Shanghai and Nagoya present the most defensible acquisition target archetype. Long-term viability hinges on specification authority migration from procurement to engineering teams. Watch for Korean coaters establishing Tokyo-based compliance subsidiaries as an inflection signal of regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Precursors | Mitigates allocation risk from concentrated Japanese and Chinese feedstock suppliers. |
| Tokyo-Based Regulatory Compliance Subsidiary | Accelerates JIS K 6891 qualification timelines through METI relationship leverage. |
| Vietnamese Industrial Corridor Facility | Captures captive demand from Japanese and Korean automotive Tier 1 expansion. |
| Graphene-Ceramic Hybrid R&D Partnership | Addresses thermal conductivity specifications in Korean EV battery interfaces. |
| Water-Based Formulation Capacity Expansion | Aligns with MEE GB 30981 enforcement across Jiangsu manufacturing clusters. |
Study Parameters
Operator-level perspectives from plant managers at coating application facilities, procurement leads at Japanese automotive Tier 1s, technical R&D directors at fluoropolymer formulators, and aftermarket service heads at industrial machinery OEMs anchored the qualitative base. These primary insights combined with customs and trade data, SEC 10-K filings from listed chemical companies, METI industrial standard documentation, and MEE regulatory enforcement records. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, application, and formulation segmentation dimensions.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated electrification pathways throughout the forecast period. Segmentation dimensions modeled include chemistry type, compliance tier, application equipment requirement, and regional production hub. CAGRs derived from fitted growth curves applied to disclosed capacity expansion timelines and OEM qualification pipeline visibility. Forecast inputs incorporated MIIT energy-efficiency quota implementation pace and METI fluoropolymer standard amendment trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-tier applicators or accelerated graphene substitution in thermal management would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Cold Gas Spray Coating Market
Coatings
Mexico Protective Coatings Market
Coatings
Urethane Surface Coatings Market
Coatings
Thailand Architectural Coatings Market
Coatings
Japan Automotive OEM Coatings Market
Coatings
Batters and Coatings Market
Coatings
Waterproof Coating Market
Coatings
BPA-Free Coatings Market
Coatings
Superhydrophobic Coatings Market
Coatings
Europe Metal Finishing Market
Coatings
Plastic-Coated Wires Market
Coatings
2K Coatings Market
Coatings
Epoxy Surface Coatings Market
Coatings
OEM Coatings Market
Coatings
Global Metal Coatings Market
Coatings
Global Diamond Coatings Market