
 Stain Resistance Coatings Market | 2026-2036
Stain Resistance Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Stain Resistance Coatings Market Analytics
The performance gap between premium fluoropolymer formulations and commodity acrylic alternatives is recalibrating procurement strategies across end-use sectors. BASF SE leverages its polymer science depth to sustain differentiated positions in high-performance industrial segments. PPG Industries anchors its portfolio through architectural and automotive OEM relationships where specification control matters. The Sherwin-Williams Company dominates North American distribution channels for protective coatings with stain-resistant properties.
Stain resistance coatings are formulated systems—typically incorporating fluorinated polymers, silicone resins, or nano-scale ceramic particles—that create low-surface-energy films to repel organic and inorganic contaminants. These coatings achieve contact angles exceeding 110 degrees on substrates such as textiles, wood, and concrete, enabling mechanical cleaning without aesthetic degradation. Fluoropolymer product types command the highest margin pools due to raw material scarcity and processing complexity, while acrylic systems compete on volume in residential construction applications. Aerospace end-user demand concentrates on cabin interior substrates where regulatory fire-smoke-toxicity standards overlap with cleanability requirements. Epoxy formulations lead metal substrate protection in industrial settings where chemical resistance and stain repellency must coexist.
EPA oversight of volatile organic compound emissions under the National Emission Standards for Hazardous Air Pollutants shapes formulation chemistry and manufacturing location decisions for suppliers serving the US market. REACH restrictions on per- and polyfluoroalkyl substances enforced by ECHA are forcing European formulators to validate alternative chemistries without sacrificing performance thresholds. China's GB standards for architectural coatings administered by SAMR establish migration limits that affect import qualification. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs that compound across multi-country supply chains.
Market Dynamics
REACH restrictions on per- and polyfluoroalkyl substances enforced by ECHA are forcing wholesale chemistry transitions across European supply chains, while automotive OEMs in China and Germany simultaneously escalate durability specifications for interior surfaces.
Growth Catalysts
- Automotive Interior Specifications:OEM procurement teams in Germany and China are mandating fluoropolymer-grade stain resistance for seat fabrics and dashboard polymers to meet 10-year warranty standards.
- REACH-Driven Reformulation:ECHA enforcement timelines are accelerating validation of silicone-modified acrylic alternatives that maintain performance thresholds without perfluorinated chemistry.
- Appliance Manufacturing Clusters:Domestic production concentration in Guangdong and Zhejiang provinces is specifying high-performance finishes for refrigerator interiors and washing machine drums.
Market Restraints
- Fluoropolymer Feedstock Concentration:Virgin PTFE resin supply concentrates among three Japanese and Chinese chemical conglomerates, exposing formulators to allocation risk during maintenance turnarounds.
- Reformulation Cost Burden:European coating houses face EUR 2-4 million per product line to validate PFAS-free alternatives through ECHA notification and OEM requalification protocols.
- Performance Gap Persistence:Silicone-acrylic hybrids still fail oil-repellency benchmarks above 90 degrees contact angle that fluoropolymers achieve routinely.
Strategic Opportunities
- India Appliance Export Hub:Tamil Nadu and Gujarat manufacturing zones are qualifying stain-resistant finishes for European-bound refrigerator and dishwasher OEM supply contracts.
- GB Standard Alignment:SAMR migration limit harmonization with EU REACH thresholds creates dual-qualification pathways for coatings qualified under both regulatory frameworks.
- Nano-Ceramic Convergence:Sol-gel silica particles combined with fluorine-free polymer backbones are opening aerospace cabin interior applications previously locked by fire-smoke-toxicity certification barriers.
Industry Challenges
- Formulation Chemistry Expertise Gap:European coating houses report 18-month average hiring cycles for polymer scientists capable of bridging silicone-acrylic compatibility without phase separation.
- Dual Certification Timeline Compression:Aerospace suppliers must complete FAA flammability testing concurrent with ECHA PFAS substitution validation, stretching R&D bandwidth across incompatible approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stain Resistance Coatings Market |
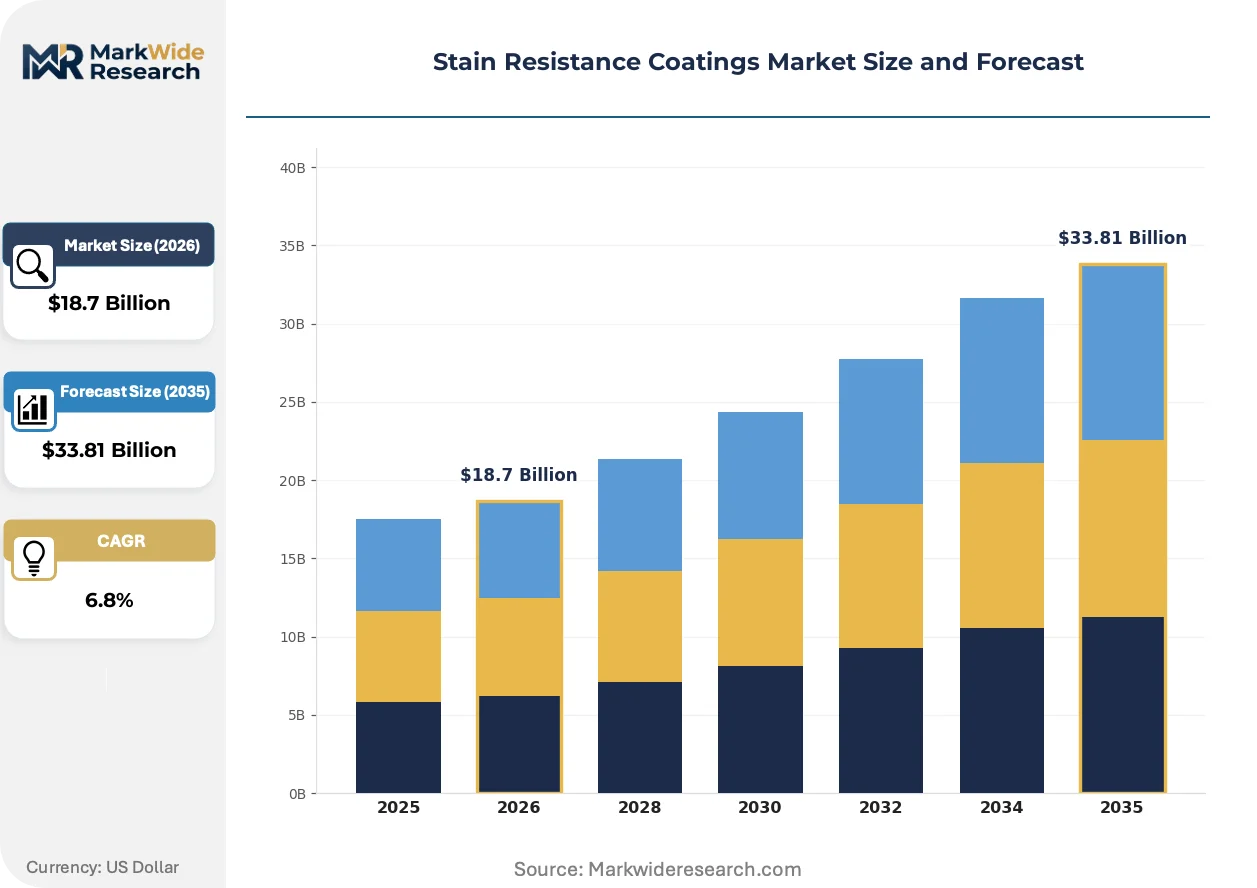
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Fluoropolymer Application: Textiles, Wood, Metal, Concrete End User: Automotive, Construction, Consumer Goods, Aerospace Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Jotun, BASF SE, PPG Industries, Inc, The 3M Company, Axalta Coating Systems, AkzoNobel N.V., Nippon Paint Holdings Co., Ltd., Hempel, The Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stain Resistance Coatings Market Evolving Landscape
Active chemistry substitution is compressing traditional product lifecycles as regulatory deadlines force parallel validation tracks, while nano-scale additive manufacturing opens performance tiers previously locked by raw material scarcity.
Silicone-modified acrylic hybrid systems are rewriting competitive positioning in automotive interior specifications. Tier-1 seating suppliers in Germany and China are qualifying these formulations for 2027 model year programs at substitution rates exceeding prior transition cycles. The technology is rewriting margin structures by collapsing the historical 40-50% price premium that fluoropolymer coatings commanded over commodity acrylics.
REACH Annex XVII restrictions on PFAS are forcing European formulators into accelerated substance notification timelines. ECHA's 2025 enforcement window for long-chain perfluorinated compounds has compressed reformulation cycles from 36 months to 18 months for architectural coating houses. Industrial maintenance coatings serving offshore platforms face the steepest compliance burden, as salt-spray resistance specifications are harder to achieve without fluorinated backbone chemistry.
Specification control is migrating from distributor inventory decisions to OEM engineering teams. Automotive and appliance manufacturers in China are consolidating approved vendor lists to three coating houses per substrate category, displacing the previous fragmented procurement through regional distributors. This concentration is most visible in Guangdong province, where Midea and Haier have implemented direct qualification protocols that bypass traditional channel intermediaries.
Stain Resistance Coatings Market Segmentation
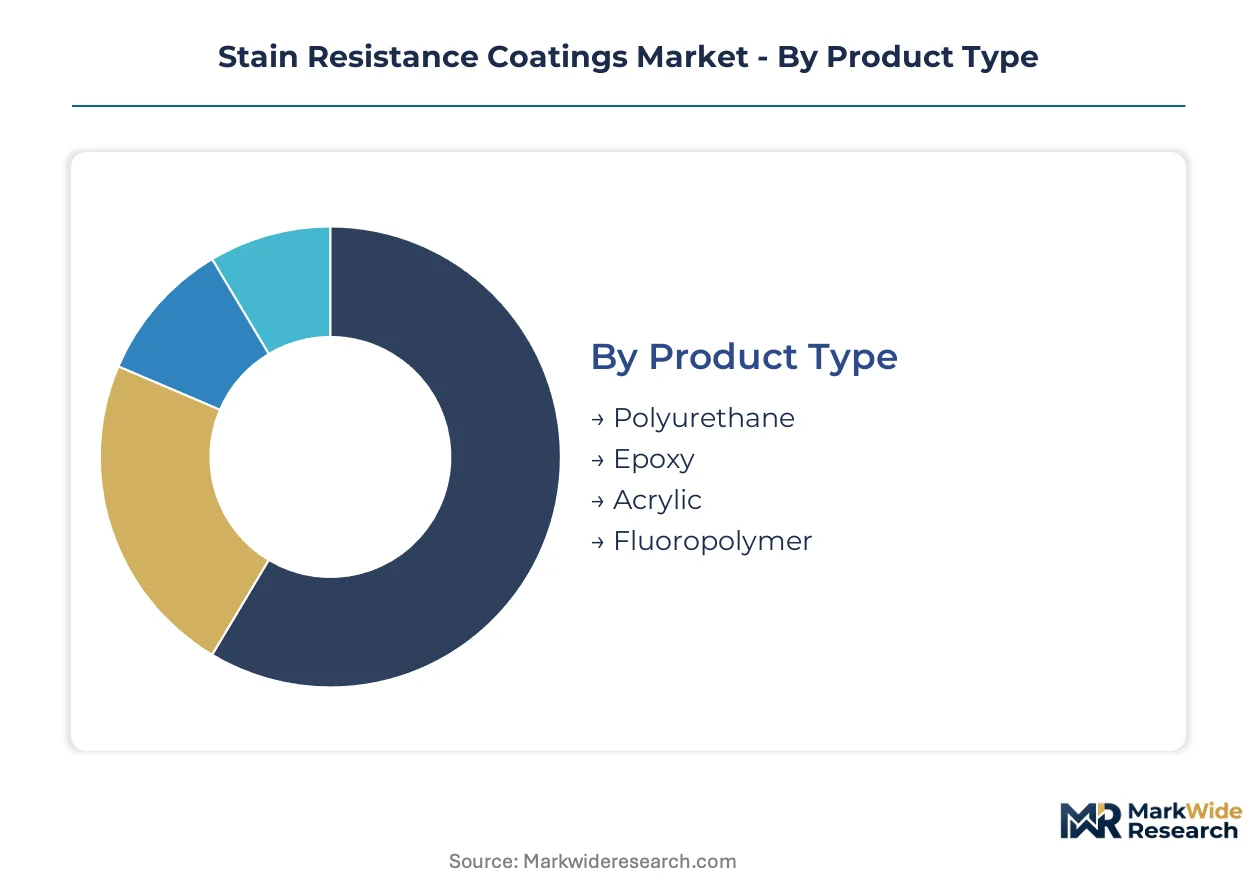
Formulation chemistry and substrate compatibility dictate procurement decisions across end-use sectors. Specification control migrates toward OEM engineering teams who consolidate approved vendor lists by performance tier rather than price point.
Product Type:
Cost tier determines qualification pathways from commodity construction to aerospace-grade specifications.
- Fluoropolymer:PTFE and PVDF backbones achieve contact angles exceeding 110 degrees for oil and solvent repellency. Automotive OEMs in Germany and China mandate these formulations for 10-year interior durability warranties, though REACH restrictions on PFAS chemistry threaten European supply continuity.
- Acrylic:Water-borne and solvent-borne variants compete on volume in residential construction where contact angle requirements stay below 90 degrees. Silicone-modified hybrids are displacing commodity grades in appliance manufacturing clusters across Guangdong province as specification thresholds rise.
- Polyurethane:Aliphatic isocyanate systems balance abrasion resistance with stain repellency on flexible substrates.
- Epoxy:Amine-cured formulations dominate industrial metal protection where chemical resistance and mechanical durability coexist.
Acrylic leads on scale; fluoropolymer leads on momentum despite regulatory headwinds.
Application:
Substrate porosity and thermal expansion coefficients drive binder selection and cure protocol design.
- Textiles:Fluorinated finishes on synthetic fibers serve automotive seating and aerospace cabin interiors where flammability standards intersect with cleanability requirements. Tier-1 suppliers in Germany are accelerating qualification of PFAS-free alternatives under ECHA enforcement timelines.
- Metal:Epoxy and polyurethane systems protect industrial equipment and appliance drums against chemical staining and corrosion. Offshore platform maintenance coatings face the steepest reformulation burden as salt-spray specifications resist non-fluorinated chemistry.
- Wood:Acrylic and polyurethane clear coats preserve aesthetic grain visibility while repelling waterborne stains on flooring and furniture.
- Concrete:Penetrating silane-siloxane sealers and film-forming acrylics protect architectural surfaces against oil and graffiti absorption.
Metal applications dominate current volume; textile coatings are expanding most quickly as automotive and aerospace specifications tighten.
End User:
Customer type determines whether procurement flows through distributor networks or direct OEM qualification protocols.
- Automotive:Interior surface specifications from German and Chinese OEMs mandate fluoropolymer-grade performance for seat fabrics, dashboard polymers, and door panels. Direct vendor consolidation to three approved coating houses per substrate category is displacing fragmented regional distributor procurement.
- Construction:Architectural coatings for residential and commercial buildings compete on price through retail and distributor channels. EPA National Emission Standards for Hazardous Air Pollutants constrain formulation chemistry and manufacturing location decisions for US-serving suppliers.
- Aerospace:Cabin interior substrates require overlapping fire-smoke-toxicity certification and stain resistance. FAA flammability testing cycles run concurrent with ECHA PFAS substitution validation, stretching R&D bandwidth.
- Consumer Goods:Appliance manufacturers in China specify high-performance finishes for refrigerator interiors and washing machine drums.
Construction leads on scale; automotive leads on specification intensity and vendor consolidation speed.
Distribution Channel:
Supply concentration shapes whether formulators capture margin through direct relationships or cede value to intermediaries.
- Direct Sales:OEM engineering teams in automotive and appliance sectors implement qualification protocols that bypass traditional channel intermediaries. Midea and Haier in Guangdong province have eliminated distributor layers for stain-resistant coating procurement.
- Distributors:Regional inventory decisions still dominate protective coatings for industrial maintenance and construction applications. The Sherwin-Williams Company anchors North American market presence through this channel structure.
- Retail:Big-box and specialty store networks serve residential DIY and small contractor segments with commodity acrylic and polyurethane formulations.
- Online:E-commerce platforms capture specification-grade product sales as OEM procurement teams digitize vendor discovery and qualification documentation.
Distributors lead on scale; direct sales channels are gaining share fastest as specification control migrates to OEM engineering teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces the strictest PFAS substitution timelines under ECHA, while China's domestic appliance manufacturers expand specification intensity without equivalent chemical restrictions. This regulatory divergence is fragmenting formulation strategies across multinational coating houses.
Germany
Automotive OEMs in Stuttgart and Munich mandate fluoropolymer-grade interior durability for 10-year warranty programs. ECHA's REACH Annex XVII enforcement compresses reformulation cycles to 18 months for seating suppliers. The Baden-Württemberg chemical cluster houses BASF SE polymer science operations validating silicone-modified acrylic alternatives.
China
Guangdong and Zhejiang appliance manufacturing clusters specify high-performance finishes for refrigerator interiors and washing machine drums. SAMR's GB standards for architectural coatings establish migration limits affecting import qualification. Midea and Haier in Foshan have implemented direct vendor qualification protocols bypassing traditional distributor channels.
United States
EPA National Emission Standards for Hazardous Air Pollutants constrain VOC emissions from architectural coating production. The Sherwin-Williams Company anchors North American distribution channels for protective coatings with stain-resistant properties. Midwest industrial maintenance demand concentrates around offshore platform reformulation challenges.
Japan
Virgin PTFE resin supply concentrates among domestic chemical conglomerates serving global formulators. METI industrial standards guide automotive interior material specifications for export-bound vehicles. Osaka-based coating specialists face allocation risk during maintenance turnarounds at feedstock facilities.
India
Tamil Nadu and Gujarat manufacturing zones qualify stain-resistant finishes for European-bound appliance OEM supply contracts. BIS certification requirements for imported coatings create dual-qualification complexity with EU REACH thresholds. Mumbai-headquartered distributors are consolidating specification-grade procurement for domestic construction growth.
Stain Resistance Coatings Market Competitive Landscape
Top-tier vendors anchor premium fluoropolymer formulations, while mid-tier coating houses compete on silicone-acrylic hybrid scale. The vendor base stratifies across three archetypes: integrated chemical conglomerates with captive polymer supply, specialized coating houses with OEM qualification depth, and regional distributors with construction channel density. Competitive moves concentrate on backward integration into resin production and direct qualification protocols that displace distributor intermediaries.
Within the integrated chemical tier, BASF SE and PPG Industries, Inc. exemplify polymer science depth sustaining differentiated positions in automotive and industrial segments. The Sherwin-Williams Company anchors North American market presence through distributor channel control for protective coatings. These three entities represent distinct strategic positions: European chemical integration, transnational OEM relationship management, and domestic distribution density.
| Leading Market Players |
|---|
| Jotun |
| BASF SE |
| PPG Industries, Inc |
| The 3M Company |
| Axalta Coating Systems |
| AkzoNobel N.V. |
| Nippon Paint Holdings Co., Ltd. |
| Hempel |
| The Sherwin-Williams Company |
| Others |
Value Network & Pricing Analysis
Automotive OEM mandates for 10-year interior durability warranties in Germany and China are forcing coating houses to secure fluoropolymer resin allocations or absorb reformulation costs, compressing margins across mid-tier suppliers while premium positions hold pricing power.
Pricing Analysis
Capacity additions in China are reshaping price floors for silicone-modified acrylic intermediates as domestic chemical conglomerates expand output. Three-tier pricing structure across premium fluoropolymer, standard hybrid, and economy commodity acrylic levels stratifies by contact angle performance and OEM certification depth. Pricing pressure stems from ECHA-driven reformulation timelines that compress validation windows and force parallel R&D investment. Construction distributors exhibit highest price sensitivity, while aerospace cabin interior specifications tolerate premium positioning.
Supply Chain Analysis
Single-source vulnerability sits with Japanese chemical conglomerates controlling virgin PTFE resin production for high-performance formulations. Feedstock supply draws from Japan, China, and Germany, with formulation expertise concentrated in European coating clusters. Raw material dependencies span fluorinated monomers, silicone resins, and nano-scale ceramic additives. Tariff exposure on Chinese-sourced intermediates threatens margin stability for North American formulators. Distribution runs through direct OEM qualification channels for automotive and appliance sectors, while regional distributors anchor construction and industrial maintenance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as procurement consolidation toward OEM engineering teams elevates specification-grade suppliers over commodity volume players.
For Market Incumbents: Anticipate REACH Annex XVII enforcement compressing product lifecycles and forcing accelerated PFAS substitution validation. Secure backward integration into silicone resin supply or captive fluoropolymer feedstock arrangements to defend formulation continuity. Deepen direct qualification protocols with Chinese appliance OEMs to displace distributor intermediaries before competitor consolidation locks out channel access. For New Entrants and Emerging Players: ECHA restrictions in Europe open a window for PFAS-free coating specialists to capture architectural and industrial maintenance share from incumbent reformulation lags. Target Tamil Nadu and Gujarat appliance export zones where European-bound OEM contracts demand dual REACH-BIS qualification that established players have not yet locked. Lead with nano-ceramic hybrid formulations that bypass fluoropolymer feedstock concentration entirely. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized coating houses possessing OEM qualification depth across automotive and aerospace fire-smoke-toxicity certifications. Five-to-ten year viability hinges on successful navigation of chemistry transitions without losing specification control. Watch for ECHA substance notification approvals as the inflection signal separating viable reformulators from stranded legacy portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive fluoropolymer or silicone supply secures allocation priority during Japanese and Chinese maintenance turnarounds. |
| PFAS-Free Formulation Certification | ECHA validation opens continued European market access as Annex XVII restrictions eliminate incumbent chemistry options. |
| Direct OEM Qualification Protocols | Bypassing distributor layers captures margin from Midea and Haier procurement consolidation in Guangdong province. |
| Nano-Ceramic Hybrid R&D Investment | Sol-gel silica particles enable aerospace cabin interior penetration without fire-smoke-toxicity certification barriers. |
| Dual-Standard Qualification Pathways | Aligning SAMR GB standards with REACH thresholds creates single-validation access to both Chinese and European demand. |
Research Methodology
Multiple input streams — technical interviews with coating formulators and polymer scientists, procurement discussions with automotive and appliance OEMs, regulatory tracking across ECHA and SAMR filings — were reconciled against trade data and SEC disclosures from listed chemical conglomerates. Primary fieldwork engaged plant managers at Guangdong manufacturing clusters, distribution channel partners in North American protective coatings, and R&D directors at European coating houses navigating REACH transitions. Secondary validation drew from customs records, ACC and Cefic industry reports, and patent filing databases. Bottom-up segment sizing and top-down market triangulation were cross-checked for consistency.
Historical volume trajectories were cross-referenced against expert panel assessments of substitution timelines and specification migration patterns across the projection horizon. Segmentation modeling spanned formulation chemistry tier, substrate application, end-use industry, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to validated base-year estimates. Industry-specific forecast inputs included ECHA enforcement phase-in schedules, Chinese appliance production capacity expansions, and aerospace OEM qualification cycle durations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS regulatory expansion or feedstock allocation disruptions. Forecasts reflect documented assumptions regarding substitution technology performance convergence and OEM vendor consolidation speed. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Waterborne Wood Coatings Market
Coatings
Electrically Conductive Coating Market
Coatings
UV Coatings Market
Coatings
Global Industrial Floor Coatings Market
Coatings
Antifouling Coatings Market
Coatings
Water-Based Alkyd Coatings Market
Coatings
Japan Marine Coatings Market
Coatings
Europe Metal Finishing Market
Coatings
Electrical Insulation Coatings Market
Coatings
Anti-Graffiti Coatings Market
Coatings
Cladding Coatings Market
Coatings
Corrosion Protection Polymer Coating Market
Coatings
Antimicrobial Coil Coating Market
Coatings
Acrylic Surface Coating Market
Coatings
Mexico Protective Coatings Market
Coatings
Liquid-Applied Roof Coating Market