
 Global Automotive Specialty Coatings Market | 2026-2036
Global Automotive Specialty Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Specialty Coatings Market Analysis
OEM procurement concentration is shifting toward vertically integrated coating suppliers capable of delivering compliant systems at EV scale. PPG Industries leverages its global color-matching infrastructure to serve premium electric vehicle programs. Axalta Coating Systems anchors its position through high-performance base coat technology for commercial truck fleets. BASF SE differentiates via integrated resin-to-coating R&D pipelines that reduce formulation cycle times.
Automotive specialty coatings are engineered films comprising polyurethanes, acrylics, and ceramic-enhanced chemistries applied to vehicle substrates for corrosion protection, aesthetic finish, and functional durability under thermal and mechanical stress. Waterborne technology leads volume adoption among OEMs seeking compliance with tightening volatile organic compound limits, while UV-cured coatings represent the fastest-expanding segment for motorcycle and specialty vehicle applications where throughput and energy efficiency command premium positioning. Powder coatings occupy a mature, cost-driven niche concentrated on heavy-duty truck chassis and underbody components.
The EPA enforces VOC emission thresholds under the National Emission Standards for Hazardous Air Pollutants, compelling U.S. manufacturers to reformulate solventborne systems. REACH registration requirements in Europe restrict specific isocyanate and heavy-metal additives, redirecting R&D investment toward compliant catalysts and crosslinkers. China's MEE implements dual carbon targets that penalize high-solvent coating processes in automotive manufacturing zones. Stakeholders must monitor regulatory divergence across these jurisdictions to avoid stranded formulation investments and secure multi-region supply qualifications.
Market Dynamics
OEM procurement concentration is forcing coating suppliers to integrate resin production with application systems, compressing qualification timelines as EV platforms demand compliant formulations at unprecedented scale.
Growth Catalysts
- EU Green Deal emission mandates:Automakers must achieve carbon-neutral coating operations by 2035, accelerating solvent-to-waterborne conversion across assembly plants in Germany, France, and Italy.
- China's dual carbon targets:MEE enforcement in automotive manufacturing zones penalizes high-VOC processes, redirecting investment toward closed-loop waterborne systems.
- Ceramic-enhanced chemistry platforms:Thermal barrier coatings for battery enclosures and power electronics are displacing conventional underhood protection as EV thermal management intensifies.
Market Restraints
- Isocyanate feedstock volatility:Polyurethane precursor costs fluctuate with crude oil and natural gas derivatives, compressing margin predictability for formulated coating suppliers.
- REACH registration friction:ECHA restrictions on specific crosslinkers and catalysts force reformulation cycles that extend qualification timelines by 18-24 months.
- UV-curing equipment capex:Retrofitting solventborne lines for ultraviolet polymerization demands substantial capital outlay that smaller tier suppliers cannot absorb.
Strategic Opportunities
- India automotive coating penetration:Domestic OEM expansion and PLI scheme incentives for EV manufacturing create first-mover advantage for compliant waterborne suppliers.
- Autonomous sensor integration:Radar-transparent and LiDAR-compatible coating formulations represent unaddressed specification gaps as ADAS penetration deepens.
- Repair network consolidation:Certified refinish programs tied to OEM warranty systems are compressing independent distributor channels in the United States and Germany.
Industry Challenges
- Formulation chemist scarcity:Expertise in waterborne polymer stabilization and UV photoinitiator selection concentrates among senior specialists approaching retirement.
- Multi-jurisdiction qualification:Simultaneous EPA, REACH, and GB standard compliance requires parallel testing protocols that strain R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Specialty Coatings Market |
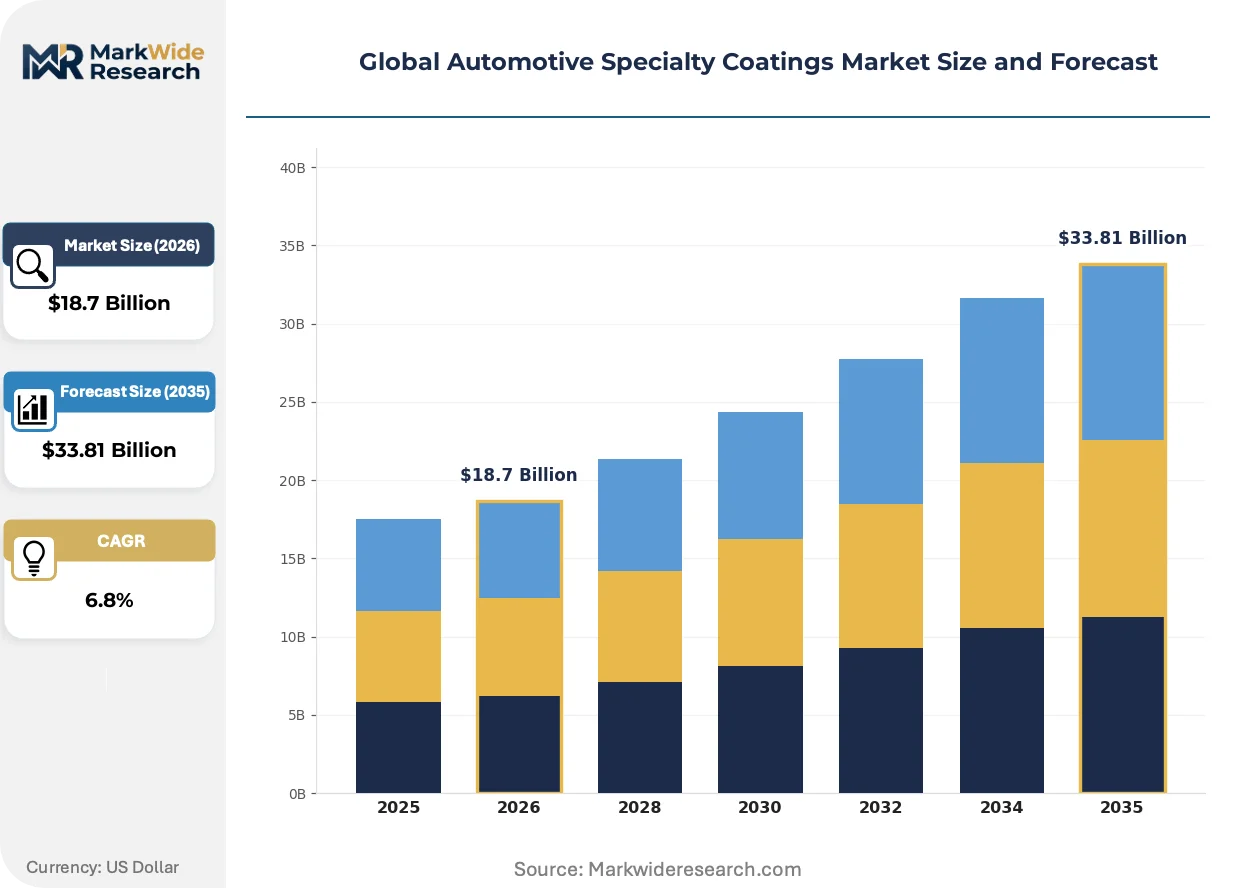
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Clear Coatings, Base Coatings, Primer Coatings, Effects Coatings Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles Technology: Waterborne, Solventborne, Powder Coatings, UV-Cured Coatings End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops |
| Companies Covered | PPG Industries, Inc., Axalta Coating Systems Ltd., BASF SE, Akzo Nobel N.V., Nippon Paint Holdings Co., Ltd., Kansai Paint Co., Ltd., Sherwin-Williams, RPM International Inc., KCC Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Specialty Coatings Market Emerging Trajectories
Coating technology convergence with electrification architectures is redefining performance specifications, while regulatory stringency and procurement consolidation reshape competitive requirements.
Self-healing polyurethane clearcoats with microcapsule-based scratch recovery are electrifying premium EV exterior programs. Luxury electric vehicle manufacturers in Germany and California specify these systems for their resistance to automated car wash abrasion and minor parking damage. The technology is electrifying supplier R&D priorities as conventional scratch-resistant hardcoats lose specification share.
REACH authorization requirements for diisocyanates now mandate worker training and exposure monitoring across EU coating operations. Formulators are accelerating aliphatic polyurethane and non-isocyanate alternatives to preempt supply disruption. Commercial vehicle OEMs in Poland and the Czech Republic face the steepest compliance costs due to concentrated solventborne truck cab production.
Direct-to-OEM digital color matching is compressing traditional distributor and jobber networks. Major automakers now require cloud-connected spectrophotometry that links body shops to centralized formulation databases. This channel restructuring is most advanced in Japan and South Korea, where consolidated dealer networks enable seamless data integration.
Global Automotive Specialty Coatings Market Segmentation
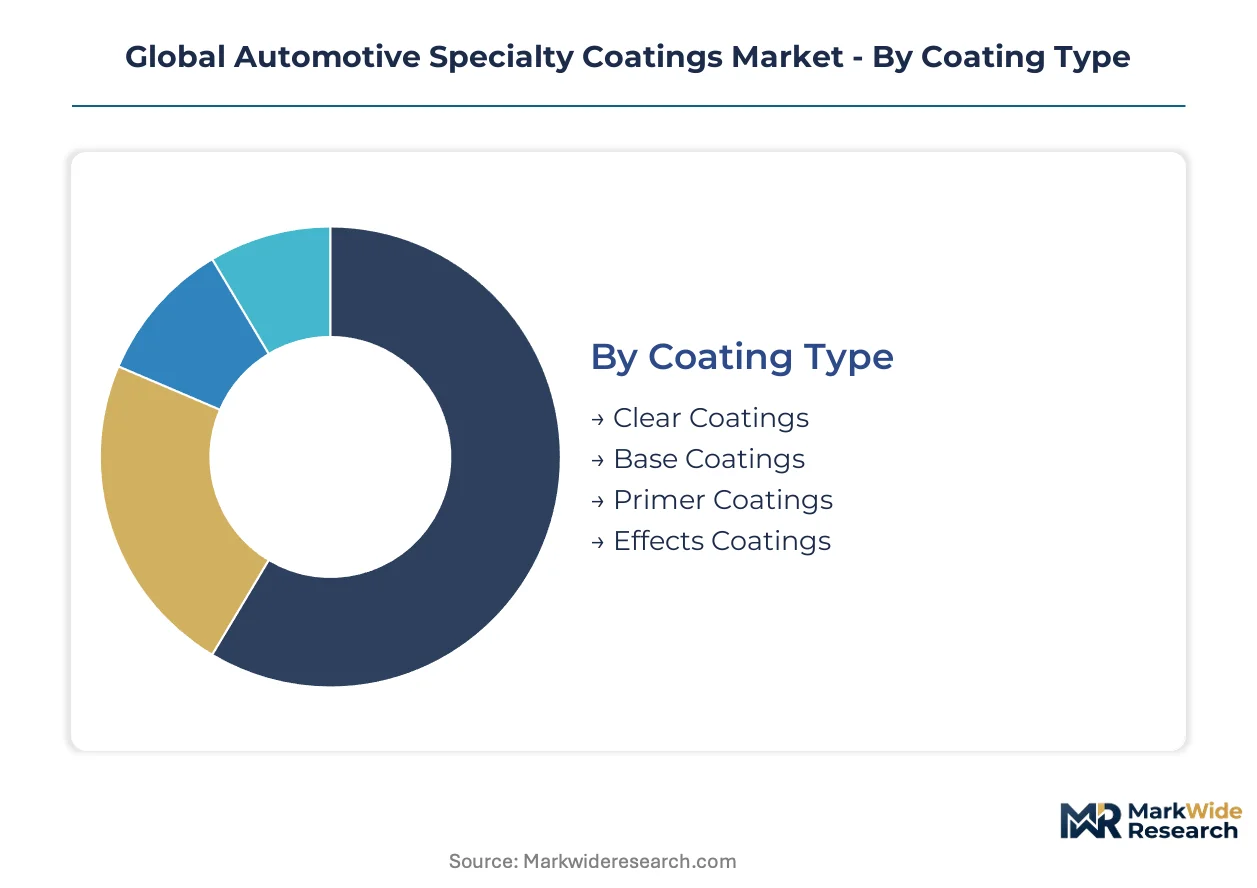
Segmentation in automotive specialty coatings reflects divergent certification burdens across regulatory jurisdictions. Coating suppliers must align formulation portfolios with distinct EPA, REACH, and GB standard requirements that vary by end-use and technology platform.
Coating Type:
Clear Coatings carry the heaviest REACH authorization burden due to isocyanate crosslinker content, while Effects Coatings face dual carbon scrutiny in China for metallic flake dispersion processes.
- Clear Coatings:Polyurethane-dominated films providing gloss retention and UV protection for exterior surfaces. German and California EV manufacturers specify self-healing variants for automated car wash durability, though isocyanate feedstock volatility compresses margin stability.
- Base Coatings:Pigmented layers delivering color and aesthetic depth beneath clearcoat protection. Waterborne acrylic-urethane hybrids dominate OEM procurement in France and Italy as assembly plants convert solvent lines to meet EU Green Deal mandates.
- Primer Coatings:Corrosion-inhibiting films applied directly to metal substrates, with epoxy-polyester hybrids standard for heavy-duty truck chassis.
- Effects Coatings:Specialty finishes incorporating metallic or pearlescent pigments for premium vehicle programs.
Clear Coatings sits at the top of the volume ranking, with Effects Coatings climbing the fastest.
Application:
Passenger vehicle programs absorb the majority of waterborne conversion capex, while commercial vehicle fleets prioritize total cost of ownership over compliance-driven technology shifts.
- Passenger Vehicles:Light-duty cars and SUVs requiring full exterior coating systems. Battery enclosure thermal management in Chinese and German EV platforms is redirecting specification toward ceramic-enhanced chemistries.
- Commercial Vehicles:Delivery vans and light trucks with high-cycle durability requirements. Polish and Czech truck cab producers face concentrated REACH compliance costs for solventborne production lines.
- Heavy-Duty Trucks:Long-haul tractors and trailers with chassis corrosion protection needs, where powder coatings retain cost advantage for underbody components.
- Motorcycles:Two-wheelers with compact coating footprints favoring UV-cured systems for throughput efficiency in Japanese and South Asian assembly plants.
Passenger Vehicles commands the largest formulation volume, though Heavy-Duty Trucks maintains the steadiest replacement cycle demand.
Technology:
Waterborne systems require the most extensive multi-jurisdiction qualification protocols, while UV-cured coatings face capital barriers that filter supplier participation.
- Waterborne:Low-VOC acrylic and polyurethane dispersions meeting EPA NESHAP and MEE dual carbon thresholds. OEM procurement in the United States, Germany, and China is accelerating conversion from solventborne baselines.
- Solventborne:Conventional high-solids systems with superior application latitude, now restricted to repair shop and specialty vehicle niches by tightening emission standards.
- Powder Coatings:Thermoset epoxy and polyester powders for heavy-duty chassis, offering zero VOC emissions but limited color-matching flexibility.
- UV-Cured Coatings:Rapid-polymerizing acrylates for motorcycle and component applications, gaining share fastest where energy costs and throughput pressure intersect.
Waterborne technology leads installed base, with UV-Cured Coatings expanding most quickly in high-throughput segments.
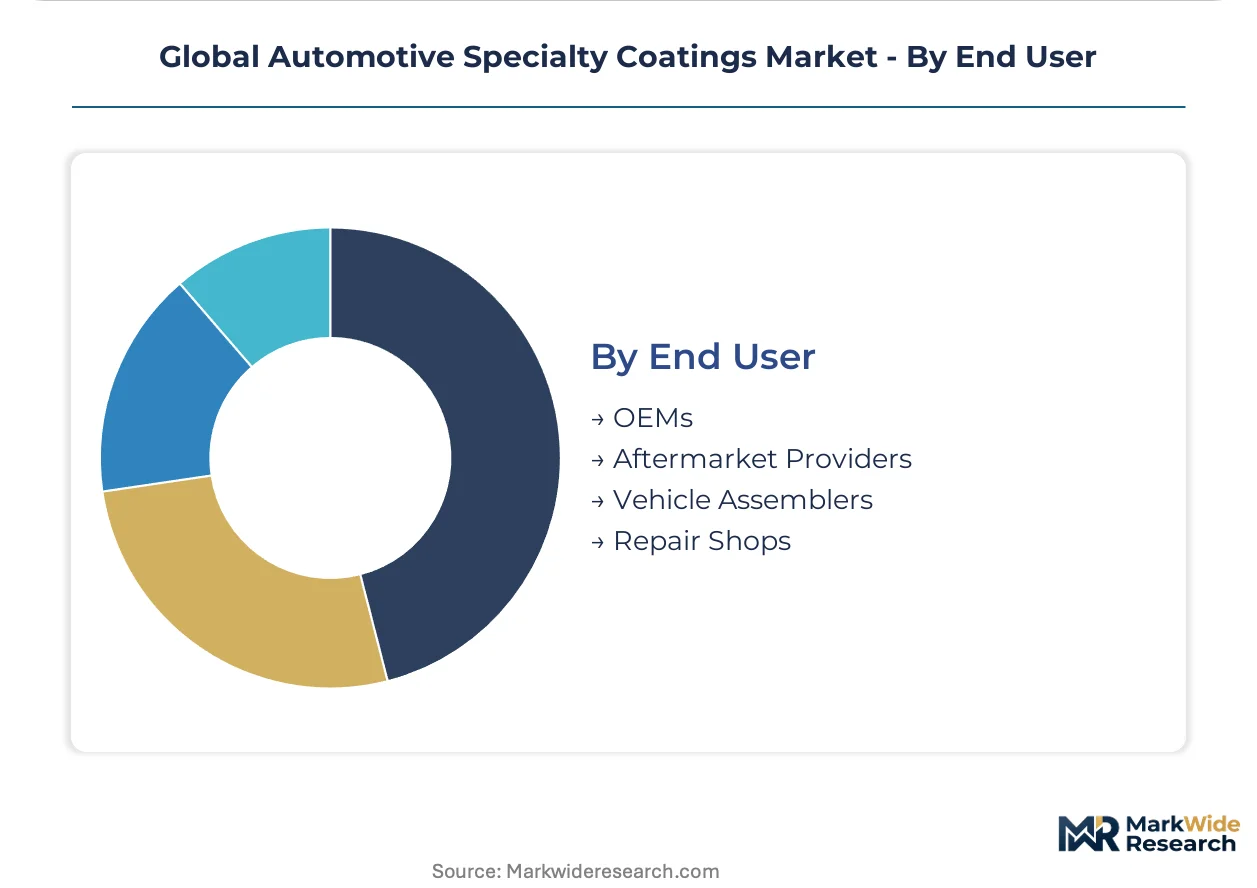
End User:
OEMs impose the most stringent formulation qualification timelines, while repair shops face channel compression from direct-to-manufacturer digital color matching.
- OEMs:Original equipment manufacturers with integrated assembly plant coating operations. Volkswagen, BMW, and BYD procurement teams demand vertically integrated resin-to-coating supply with cloud-connected spectrophotometry compliance.
- Aftermarket Providers:Independent distributors and jobber networks serving collision repair, losing specification share to certified refinish programs tied to OEM warranty systems in the United States and Germany.
- Vehicle Assemblers:Contract manufacturers and tier-one integrators requiring rapid formulation turnaround for platform launches.
- Repair Shops:Body shops and collision centers, where EPA VOC thresholds and OSHA worker exposure rules constrain solventborne inventory.
OEMs dominate value capture, with Repair Shops experiencing the steepest channel restructuring pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's EV coating procurement scale dwarfs Germany's premium automotive programs, yet both markets impose incompatible qualification protocols that fragment supplier investment.
China
BYD and CATL battery enclosure demand is redirecting specification toward ceramic-enhanced thermal barrier coatings. MEE dual carbon enforcement in automotive manufacturing zones penalizes solventborne processes, accelerating closed-loop waterborne conversion. Yangtze River Delta coating plants in Shanghai and Suzhou are absorbing the majority of compliant system capacity expansion.
Germany
BMW and Volkswagen procurement teams demand vertically integrated resin-to-coating supply with cloud-connected color matching. EU Green Deal mandates require carbon-neutral coating operations by 2035, forcing solvent-to-waterborne line conversion in Bavarian and Baden-Württemberg assembly plants. Stuttgart and Munich industrial clusters concentrate self-healing clearcoat R&D for premium EV exterior programs.
United States
EPA NESHAP VOC thresholds compel reformulation of solventborne systems across Detroit Three operations. Tesla and Rivian battery thermal management specifications are displacing conventional underhood coatings with ceramic-enhanced chemistries. Michigan and California assembly plants lead waterborne conversion capex, though Texas truck production retains powder coating dominance for chassis applications.
Japan
Toyota and Honda procurement maintains stringent qualification timelines that filter supplier participation to established resin-integrated players. METI energy efficiency standards favor UV-cured systems for motorcycle and compact vehicle throughput. Nagoya and Osaka industrial corridors concentrate high-performance basecoat technology for export-oriented passenger vehicle programs.
India
Domestic OEM expansion and PLI scheme EV manufacturing incentives are creating first-mover advantage for compliant waterborne suppliers. BIS emission standards are tightening faster than supplier reformulation cycles can accommodate. Tamil Nadu and Maharashtra automotive clusters in Chennai and Pune are absorbing the majority of imported coating technology licensing agreements.
Global Automotive Specialty Coatings Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a consolidated structure where resin integration capability determines procurement access. Three archetypes dominate: integrated chemical majors with captive resin production, coating specialists with application system partnerships, and regional formulators with cost-positioned solventborne portfolios. Competitive moves concentrate on backward integration into resin manufacturing and strategic partnerships with EV platform engineers.
Among diversified chemical majors, PPG Industries, BASF SE, and Axalta Coating Systems exemplify the integrated archetype. PPG represents North American infrastructure leverage, BASF SE anchors European resin-to-coating R&D pipelines, and Axalta occupies the specialist position with focused coating technology. These three sit within the premium procurement tier where OEM qualification timelines compress supplier lists to single-digit counts.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| Axalta Coating Systems Ltd. |
| BASF SE |
| Akzo Nobel N.V. |
| Nippon Paint Holdings Co., Ltd. |
| Kansai Paint Co., Ltd. |
| Sherwin-Williams |
| RPM International Inc. |
| KCC Corp. |
| Others |
Supply Flow & Price Mechanics
Isocyanate feedstock indices cascade through automotive coating supply chains into three distinct pricing tiers shaped by resin integration depth and regulatory compliance burden. Waterborne system premiums reflect captive polyurethane dispersion capacity, while solventborne discounts narrow as EPA NESHAP and REACH authorization costs erode margin buffers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for compliant waterborne systems. Three-tier pricing structure across premium, standard, and economy levels separates vertically integrated suppliers from regional formulators dependent on merchant resin. Price differentiation hinges on REACH certification tier and volume scale commitments to OEM procurement teams. Cost compression in economy-grade solventborne tiers is intensifying because MEE dual carbon enforcement redirects demand toward qualified waterborne alternatives. Commercial vehicle fleet buyers in Poland and Czechia exhibit highest price sensitivity, while German premium EV manufacturers absorb premium clearcoat pricing without volume negotiation.
Supply Chain Analysis
Freight costs for isocyanate precursors from China and Germany to formulation plants in the United States and India have compressed margin predictability for non-integrated suppliers. Raw material sourcing draws from aromatic and aliphatic polyurethane feedstocks, ceramic nanoparticle additives, and photoinitiator chemistries concentrated in Chinese and Japanese production clusters. Single-source vulnerability in diisocyanate crosslinkers exposes formulators to ECHA authorization disruption. Distribution runs through direct-to-OEM channels for qualified suppliers, while independent jobber networks serve repair shop segments facing channel compression from cloud-connected color matching systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal carbon-neutral coating mandates by 2035 and China's dual carbon enforcement are accelerating demand for compliant formulation capacity.
For Market Incumbents: Acquire captive resin manufacturing assets to compress qualification timelines for EV platform procurement. Consolidate cloud-connected spectrophotometry infrastructure to defend against direct-to-OEM digital color matching. Prioritize aliphatic polyurethane R&D pipelines to preempt REACH diisocyanate authorization disruption. For New Entrants and Emerging Players: Begin with ceramic-enhanced thermal barrier coatings for battery enclosure applications in India's Tamil Nadu and Maharashtra automotive clusters. Target autonomous sensor-compatible formulations where radar-transparent specifications remain unaddressed. Pursue PLI scheme-aligned partnerships with domestic OEMs seeking first-mover waterborne suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier formulators possessing regional GB standard compliance and latent resin integration capability. Long-term viability centers on suppliers capable of simultaneous EPA, REACH, and MEE qualification without parallel testing redundancy. Watch for inflection in OEM procurement consolidation toward single-digit qualified supplier lists per platform.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Manufacturing | Captive polyurethane dispersion capacity compresses OEM qualification timelines and stabilizes margin predictability against isocyanate volatility. |
| Ceramic-Enhanced Thermal Barrier Development | Battery enclosure specifications from BYD and CATL redirect R&D investment toward EV thermal management applications. |
| Cloud-Connected Color Matching Deployment | Direct-to-OEM digital infrastructure displaces independent jobber networks in German and Japanese consolidated dealer systems. |
| Non-Isocyanate Crosslinker Pipeline Investment | REACH authorization mandates for diisocyanates force reformulation cycles that extend competitive moats for compliant suppliers. |
| India Manufacturing Footprint Expansion | PLI scheme incentives and BIS emission tightening create first-mover positioning in domestic OEM EV coating procurement. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate supply-side capacity with demand-side procurement patterns. Primary engagement captured coating formulator R&D directors, OEM platform engineers at Volkswagen and BMW, Tier 1 supplier procurement leads, and aftermarket distributor operations heads. Secondary validation drew from EPA NESHAP enforcement records, ECHA REACH authorization databases, MEE dual carbon policy filings, and automotive production registration data. Bottom-up formulation volume estimates reconciled against top-down OEM coating content per vehicle assumptions.
Segment-weighting approaches distributed value across coating type, application, technology platform, and end-user channel dimensions. Vehicle class, propulsion architecture, and regional production cluster variables informed penetration modeling across the projection horizon. CAGRs derived from regression analysis of historical conversion rates from solventborne to waterborne systems, adjusted for regulatory enforcement intensity and OEM platform launch cadence. EV thermal management content and autonomous sensor compatibility specifications served as forward-looking demand drivers.
Several conditions sit outside the modeled scope, including potential REACH authorization scope expansion beyond diisocyanates, abrupt MEE enforcement escalation in Chinese manufacturing zones, and breakthrough non-polyurethane coating chemistries. Forecasts reflect documented assumptions regarding regulatory timeline adherence and OEM procurement consolidation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Waterproof Coating Market
Coatings
Global Heat Resistant Coatings Market
Coatings
Spain Automotive OEM Coatings Market
Coatings
South Korea Automotive OEM Coatings Market
Coatings
Technical Coil Coatings Market
Coatings
South Africa Automotive OEM Coatings Market
Coatings
Global Antiviral Coatings Market
Coatings
Ultraviolet (UV) Coatings Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
Polymer Modified Cementitious Coatings Market
Coatings
Anti Soiling Coating Market
Coatings
Hard Coating Market
Coatings
Solar Reflective Film Market
Coatings
Topcoat Market
Coatings
Acrylic Protective Coating Market
Coatings
Anti-Microbial Powder Coatings Market