
 Electrically Conductive Coating Market | 2026-2036
Electrically Conductive Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Electrically Conductive Coating Market Analysis
REACH compliance is hardening the cost-of-entry calculus for conductive coating suppliers seeking European market access. PPG Industries sustains technology leadership through in-house resin synthesis capabilities that reduce reliance on restricted precursor chemicals. Henkel AG & Co. KGaA leverages its adhesive-coating convergence expertise to dominate medical device grounding applications. BASF SE anchors its position with backward integration into specialty carbon black and silver flake supply chains.
Electrically conductive coatings are thin-film formulations incorporating metallic or carbonaceous fillers that achieve surface resistivity below 10 ohms per square while maintaining adhesion to polymer, metal, or ceramic substrates. These coatings serve primarily to dissipate static charge, provide electromagnetic interference shielding, and create conductive traces on non-metallic surfaces in electronics and transportation equipment. Silver-based formulations command premium positioning due to unmatched conductivity and oxidation stability, though carbon-based alternatives are gaining share in cost-sensitive automotive sensor housings. Application segmentation shows electronics consuming the largest volume share, with aerospace representing the highest margin pool because of qualification barriers and lot-traceability requirements.
The EPA regulates volatile organic compound emissions from coating operations under NESHAP standards, while the EU Green Deal and F-Gas Regulation constrain fluorinated solvent use in formulation processes. China's MEE enforces GB standards on hazardous substance limits in electronics coatings, creating divergent compliance obligations for multinational suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation customization or unified global product platforms deliver superior returns on compliance investment.
Market Dynamics
Silver flake supply concentration in East Asian refineries is forcing formulation houses to restructure procurement strategies and accelerate carbon-based filler substitution programs.
Growth Catalysts
- 5G Infrastructure Deployment:Massive MIMO antenna arrays and base station enclosures require conformal EMI shielding coatings. China's MIIT spectrum allocation timeline compresses supplier qualification windows.
- EU Green Deal Chemical Transition:REACH SVHC restrictions on hexavalent chromium and certain solvents are redirecting automotive OEM specifications toward waterborne conductive primers.
- EV Battery Pack Scaling:Cell-to-pack architectures demand flame-retardant conductive coatings for thermal runaway mitigation. Korean and Chinese battery makers specify these for module housings.
Market Restraints
- Silver Price Volatility:London Bullion Market Association spot pricing swings above 20% annually compress coating gross margins and destabilize long-term supply contracts.
- Carbon Black Feedstock Concentration:US Gulf Coast petrochemical complexes supply 60% of furnace-grade conductive blacks; hurricane disruptions cascade through electronics coating supply chains.
- Fluorinated Solvent Constraints:EU F-Gas Regulation phase-down schedules eliminate perfluorinated carriers used in precision spray deposition of thin-film conductive layers.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and PCB fabrication are creating first-mover advantages for coating suppliers establishing local blending operations.
- Biocompatible Medical Grounding:ISO 10993-compliant silver-silver chloride formulations for implantable device shielding remain underpenetrated relative to cardiovascular device growth trajectories.
- Photovoltaic Junction Box Integration:Conductive backsheet coatings that replace mechanical grounding hardware are gaining traction in utility-scale solar installations across Spain and Italy.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in conductive filler percolation thresholds and polymer rheology convergence commands premium compensation; talent pipelines from materials science programs remain thin.
- Aerospace Qualification Timelines:SAE AMS and MIL-PRF certification cycles extend 18-24 months; lot traceability documentation burdens strain mid-tier coating houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrically Conductive Coating Market |
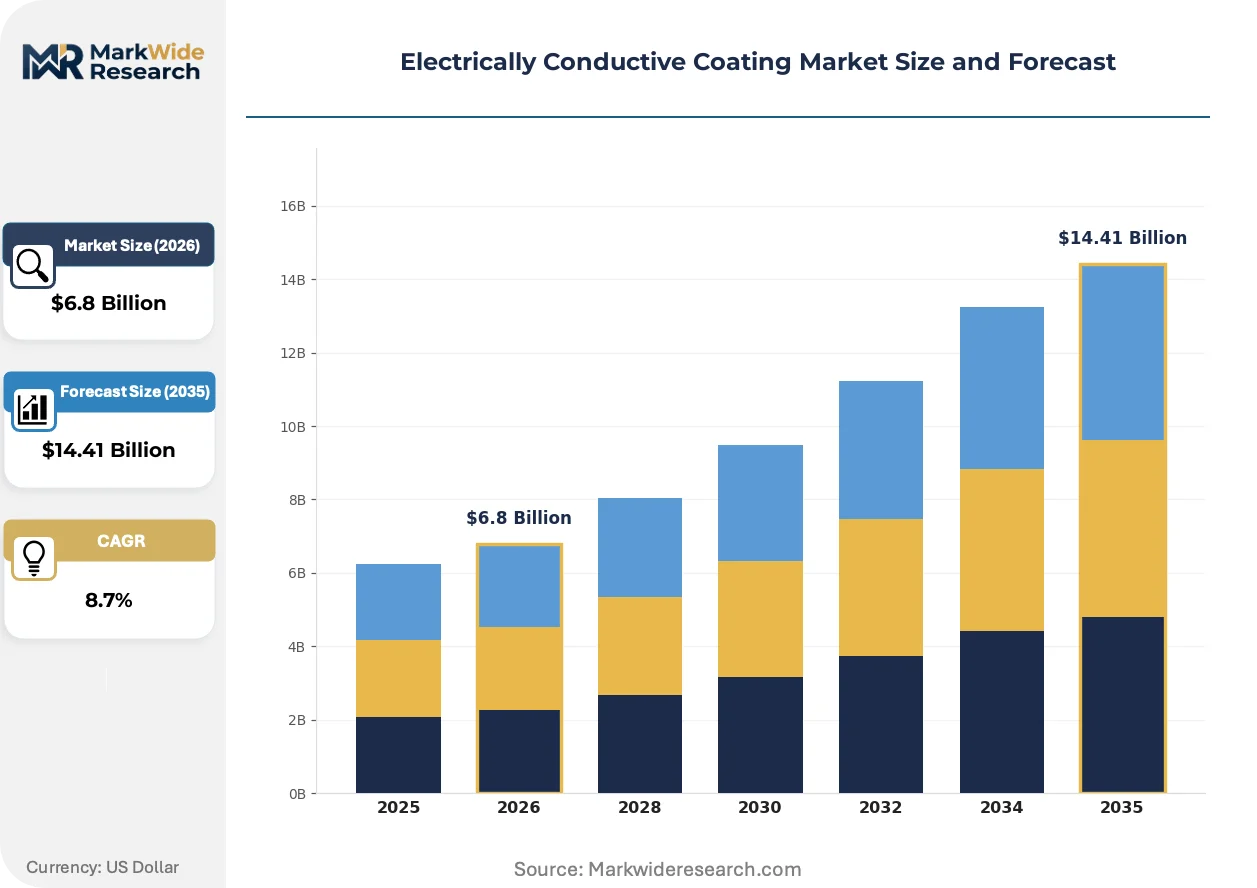
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Silver-Based, Carbon-Based, Nickel-Based, Copper-Based Application: Electronics, Automotive, Aerospace, Medical Devices Formulation: Organic, Inorganic, Hybrid, Water-Based Substrate: Plastic, Metal, Glass, Ceramic |
| Companies Covered | Akzo Nobel NV, PPG Industries Inc., The Sherwin-Williams Company, Henkel AG & Co. KGaA, Axalta Coating Systems, Creative Materials Inc., Altana AG, BASF SE, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrically Conductive Coating Market Emerging Trajectories
Nanostructured filler architectures and solvent-free deposition methods are compressing traditional process boundaries between coating application and electronics assembly.
Graphene nanoplatelet dispersions are decentralizing conductive coating formulation away from precious metal dependence. Automotive sensor manufacturers in Germany and Japan are adopting these for radar housing EMI shielding at 40% lower material cost. The shift is compressing silver flake demand growth in cost-sensitive automotive tiers while elevating dispersion stability as the critical technical differentiator.
REACH authorization requirements for nickel compounds are forcing hard chrome replacement in aerospace grounding applications. European coating houses must reformulate by 2026 submission deadlines or surrender aviation connector market positions. Suppliers with pre-qualified cobalt-free alternatives are capturing specification lock-in from Airbus and Safran procurement teams.
Buyers are consolidating coating procurement through tier-one electronics manufacturing services providers. Foxconn and Pegatron now specify approved coating vendor lists for their PCB subcontractors across Vietnam and Mexico. This concentration is squeezing independent coating distributors and forcing raw material suppliers to pursue direct qualification with EMS technical teams rather than traditional channel partnerships.
Electrically Conductive Coating Market Segmentation
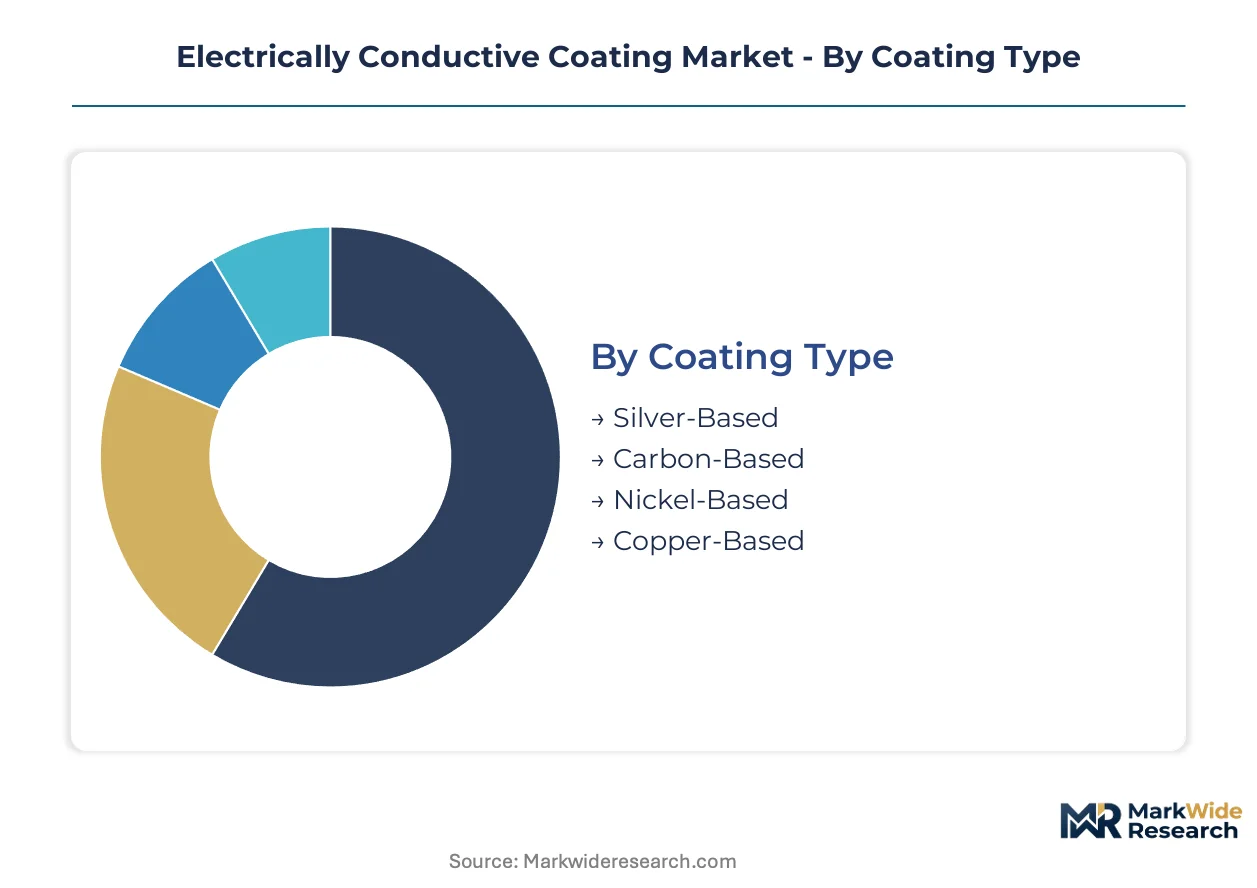
Conductive coating procurement splits sharply between performance-critical specifications demanding precise filler loading and cost-optimized formulations where conductivity thresholds flex. Segmentation discipline separates premium silver systems from carbon alternatives competing on raw material arbitrage.
Coating Type:
Customization intensity varies from precious metal formulations requiring tight particle size distribution to commodity carbon blacks tolerating broader specification bands.
- Silver-Based:Flake or spherical silver particles suspended in epoxy or acrylic carriers achieve surface resistivity below 0.1 ohms per square. Demand concentrates in aerospace connector grounding and medical device shielding where oxidation stability outweighs material cost. London Bullion Market Association pricing volatility forces annual contract renegotiation.
- Carbon-Based:Furnace or acetylene black dispersions in solvent-borne systems target 10-100 ohms per square for automotive sensor housings and consumer electronics enclosures. Chinese EV battery manufacturers specify these for cell-to-pack module thermal management where cost-per-kilogram drives specification.
- Nickel-Based:Spherical nickel powder coatings serve corrosion-resistant grounding applications in marine and industrial equipment. REACH SVHC authorization timelines are compressing European availability.
- Copper-Based:Oxidation-prone copper flake formulations occupy price-sensitive EMI shielding niches with protective topcoat requirements. Korean PCB fabricators dominate procurement volume.
Leading the category by volume: Carbon-Based. Expanding most quickly: Silver-Based in medical device applications.
Application:
End-use concentration determines formulation complexity, with aerospace qualification burdens separating premium tiers from automotive scale economics.
- Electronics:Conformal coatings for PCB trace repair, antenna patterning, and flex circuit termination absorb the largest formulation volumes. Foxconn and Pegatron vendor list consolidation in Vietnam and Mexico is squeezing independent coating distributors.
- Automotive:Radar housing EMI shielding and battery pack thermal runaway coatings specify flame-retardant conductive primers. German and Japanese OEMs are qualifying graphene nanoplatelet alternatives to silver flake for cost-sensitive ADAS sensor tiers.
- Aerospace:SAE AMS-certified coatings for airframe lightning strike protection and avionics grounding command the highest margins. Airbus and Safran procurement teams are locking in cobalt-free alternatives ahead of REACH nickel compound deadlines.
- Medical Devices:ISO 10993-compliant silver-silver chloride formulations for implantable cardioverter-defibrillator shielding remain underpenetrated relative to cardiovascular device growth trajectories.
Widest margin pool: Aerospace. Steepest volume climb: Automotive battery applications.
Formulation:
Carrier chemistry selection hinges on substrate compatibility, deposition method, and evaporative emission constraints tightening across manufacturing jurisdictions.
- Organic:Solvent-borne epoxy and polyurethane systems dominate established electronics coating lines. EPA NESHAP volatile organic compound limits and EU F-Gas Regulation perfluorinated solvent phase-downs are forcing reformulation investment.
- Inorganic:Silicate-bonded coatings withstand temperatures exceeding 500°C for ceramic substrate metallization. Solar junction box manufacturers in Spain and Italy specify these for conductive backsheet integration replacing mechanical grounding hardware.
- Hybrid:Organic-inorganic sol-gel systems balance processability with thermal stability for automotive under-hood sensors. Japanese tier-one suppliers lead formulation patent activity.
- Water-Based:Acrylic and polyurethane dispersions are capturing automotive OEM specifications as REACH drives hexavalent chromium and solvent elimination. PPG Industries and Henkel AG sustain technology leadership through in-house resin synthesis reducing restricted precursor dependence.
Highest regulatory pressure: Organic. Gaining specification share fastest: Water-Based.
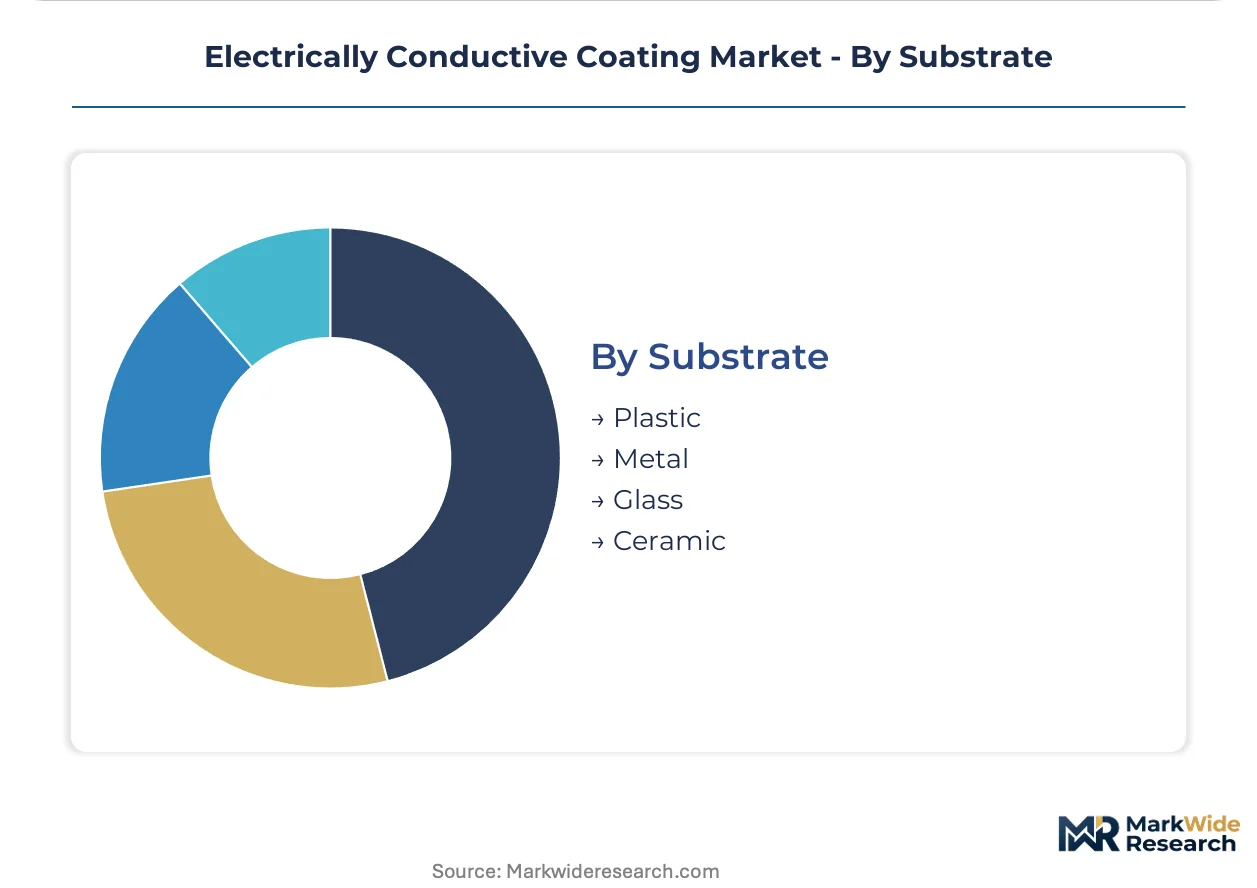
Substrate:
Surface energy and thermal expansion mismatches dictate primer architecture, with polymer substrates demanding adhesion promoters absent from metal or ceramic applications.
- Plastic:ABS, polycarbonate, and polyamide housings for consumer electronics and automotive sensors require plasma or chemical etching pretreatment. China's coastal manufacturing zones concentrate demand from PCB and EV battery production clusters.
- Metal:Aluminum and magnesium alloys for aerospace connectors and automotive enclosures need conversion coating compatibility. REACH hexavalent chromium restrictions are redirecting specifications toward trivalent or cobalt-free alternatives.
- Glass:Display panel edge shielding and photovoltaic junction box terminations specify sputtered or sprayed conductive layers. Utility-scale solar installations across Southern Europe are driving conductive backsheet adoption.
- Ceramic:High-temperature cofired ceramic packages for power electronics and LED substrates demand fired-on silver or nickel pastes. Korean semiconductor packaging houses dominate procurement.
Processing volume leader: Plastic. Technical specification intensity peak: Ceramic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal special economic zones concentrate conductive coating demand as PCB and EV battery production clusters expand manufacturing footprints. MIIT spectrum allocations for 5G infrastructure compress supplier qualification windows across East Asian manufacturing hubs.
China
PCB fabricators in Shenzhen and Dongguan drive silver-based formulation volumes for smartphone antenna patterning. MEE enforcement of GB standards on hazardous substance limits forces reformulation of solvent-borne systems. Yangtze River Delta battery manufacturers specify carbon-based thermal management coatings for cell-to-pack architectures.
United States
EPA NESHAP volatile organic compound limits constrain coating operations serving aerospace connector manufacturers. Defense contractors in Connecticut and California sustain qualification-driven demand for SAE AMS-certified lightning strike protection. Gulf Coast petrochemical disruptions propagate through carbon black supply chains serving electronics fabricators.
Germany
Automotive OEMs in Stuttgart and Munich qualify graphene nanoplatelet alternatives for ADAS sensor radar housings. REACH authorization deadlines for nickel compounds force hard chrome replacement in aviation grounding applications. Bavarian coating houses with cobalt-free pre-qualifications capture specification lock-in from Airbus procurement teams.
Japan
Tier-one automotive suppliers in Nagoya lead hybrid sol-gel formulation patent activity for under-hood sensors. METI industrial standards shape conductive backsheet specifications for utility-scale solar installations. Kansai region electronics manufacturers consolidate procurement through approved vendor lists.
India
PLI scheme incentives for semiconductor fabrication attract coating suppliers establishing local blending operations in Gujarat and Karnataka. BIS certification requirements create entry barriers for imported formulations. Maharashtra electronics manufacturing zones concentrate demand from emerging PCB substrate producers.
Electrically Conductive Coating Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation complexity tiers. The market structure separates precious metal systems requiring tight particle size distribution from commodity carbon blacks tolerating broader specification bands. Three archetypes dominate: integrated chemical majors with captive filler supply, coating specialists converging adhesive and conductive expertise, and regional blenders serving cost-optimized automotive tiers. Competitive moves center on backward integration into specialty carbon black and silver flake supply chains, plus direct qualification with tier-one electronics manufacturing services providers.
Among integrated chemical majors, BASF SE and DuPont de Nemours, Inc. exemplify archetypes combining resin synthesis capabilities with filler supply chain control. PPG Industries occupies a position representing coating houses sustaining technology leadership through in-house production reducing restricted precursor dependence. Henkel AG & Co. KGaA sits within the adhesive-coating convergence tier, anchoring medical device grounding applications through ISO 10993-compliant formulation expertise.
| Leading Market Players |
|---|
| Akzo Nobel NV |
| PPG Industries Inc. |
| The Sherwin-Williams Company |
| Henkel AG & Co. KGaA |
| Axalta Coating Systems |
| Creative Materials Inc. |
| Altana AG |
| BASF SE |
| DuPont de Nemours, Inc. |
| Others |
Supply Flow & Price Mechanics
Silver flake procurement costs cascade through conductive coating pricing tiers, with London Bullion Market Association spot volatility forcing annual contract renegotiations between East Asian refineries and formulation houses serving aerospace and medical device segments.
Pricing Analysis
Short lead-time premiums for REACH-compliant formulations separate aerospace-qualified suppliers from spot-market carbon-black blenders serving automotive sensor tiers. Three-tier pricing structure across premium silver systems, mid-grade nickel alternatives, and economy carbon blacks reflects certification burden and filler loading precision. Cost compression in carbon-based tiers is intensifying because Chinese EV battery manufacturers specify cost-per-kilogram thresholds. Automotive OEM procurement teams exhibit highest price sensitivity, while medical device shielding applications tolerate material cost premiums for oxidation stability.
Supply Chain Analysis
Refurbishment flows for spent silver flake from electronics manufacturing scrap recovery feed secondary material streams back into lower-grade coating formulations. Raw material sourcing draws from East Asian silver refineries, US Gulf Coast carbon black complexes, and German specialty chemical resin producers. Single-source vulnerability concentrates in furnace-grade conductive blacks where hurricane disruptions propagate through electronics coating supply chains. Distribution runs through tier-one electronics manufacturing services providers consolidating approved vendor lists across Vietnam and Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Graphene nanoplatelet dispersions are displacing silver flake in cost-sensitive automotive radar housings, compressing precious metal dependence while elevating dispersion stability as the critical technical differentiator.
For Market Incumbents: Deepen backward integration into specialty carbon black and silver flake supply chains to offset raw material volatility. BASF SE's captive filler production anchors margin defense against spot market swings. Accelerate cobalt-free alternative pre-qualification with Airbus and Safran procurement teams ahead of REACH nickel compound authorization deadlines. For New Entrants and Emerging Players: The mid-tier pricing gap between SAE AMS-certified aerospace coatings and commodity automotive primers offers white-space entry for hybrid sol-gel formulations. India's PLI scheme electronics manufacturing zones present the most penetrable geography for local blending operations. Pursue direct qualification with Foxconn and Pegatron technical teams rather than traditional distributor channel partnerships. For Investors and Strategic Acquirers: REACH authorization submission deadlines for nickel compounds are the leading indicator that cobalt-free formulation capabilities will command acquisition premiums. Five-to-ten year viability favors coating houses with in-house resin synthesis reducing restricted precursor dependence. Monitor EU F-Gas Regulation phase-down enforcement as inflection signal for solvent-free deposition technology adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filler Supply | BASF SE's captive carbon black production insulates margin from Gulf Coast petrochemical disruptions. |
| REACH-Compliant Formulation Pre-Qualification | Henkel AG's ISO 10993 expertise captures medical device grounding specification lock-in ahead of competitors. |
| Direct EMS Technical Qualification | PPG Industries' resin synthesis capabilities secure Foxconn vendor list placement squeezing independent distributors. |
| Graphene Nanoplatelet Patent Development | Japanese tier-one suppliers' sol-gel formulation activity targets 40% material cost reduction in ADAS sensor tiers. |
| Local Blending Operations in India | PLI scheme incentives in Gujarat and Karnataka attract coating suppliers establishing BIS-certified production. |
Methodological Framework
Trade databases, SEC filings from coating and chemical majors, and ECHA REACH authorization registers formed the secondary backbone for supply chain mapping and regulatory timeline analysis. Primary interviews with formulation chemists, aerospace procurement managers at Airbus and Safran, and automotive Tier 1 supplier technical directors validated filler substitution trends and qualification timeline assumptions. Bottom-up and top-down triangulation cross-checked regional volume estimates against customs data and electronics manufacturing production indices.
Bottom-up modeling aggregated coating consumption across PCB fabrication, EV battery module assembly, and aerospace connector manufacturing lines. Segmentation dimensions included filler type, carrier chemistry, substrate compatibility, and end-use qualification tier. CAGRs were derived from regression analysis against 5G infrastructure deployment schedules and EV production scaling curves. Silver price volatility bands and REACH authorization timelines fed scenario-based forecast ranges.
Inputs from ECHA registration databases and MIIT spectrum allocation announcements were available through the study window; gaps in real-time silver flake inventory data introduce uncertainty bands around near-term pricing assumptions. Forecasts reflect documented assumptions about graphene nanoplatelet adoption rates and F-Gas Regulation enforcement intensity. Practitioners should monitor REACH SVHC list updates and Korean battery maker specification shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Coating Equipment Market
Coatings
ASEAN Automotive OEM Coatings Market
Coatings
Corrosion Protection Polymer Coating Market
Coatings
United States Industrial Wood Coatings Market
Coatings
Asia-Pacific Flat Glass Coating Market
Coatings
Mexico Floor Coatings Market
Coatings
Sol-Gel Coatings Market
Coatings
Global Laser Cladding Service Market
Coatings
US Antifouling Yacht Coatings Market
Coatings
PACVD-Based Coatings Market
Coatings
Anti-Microbial Coatings Market
Coatings
Liquid-Applied Roof Coating Market
Coatings
In-Mold Coatings Market
Coatings
Asia-Pacific Floor Coatings Market
Coatings
Epoxy Surface Coatings Market
Coatings
Asia-Pacific Protective Coatings Market