
 Classic Organic Pigments Market | 2026-2036
Classic Organic Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Classic Organic Pigments Market Intelligence
The unbundling of pigment sales from proprietary solvent systems is shifting procurement patterns among large-scale industrial users. Clariant AG leverages its broad portfolio to serve diverse end-markets from textiles to plastics. BASF SE sustains its market position through significant R&D investment in high-performance pigments and sustainable formulations. Sudarshan Chemical Industries Limited competes on manufacturing scale and cost-efficiency, particularly in the azo pigment category.
Classic organic pigments are carbon-based chemical compounds that impart color to a substrate through selective absorption of light. Unlike dyes, they are insoluble in the application medium, such as water or solvents, requiring dispersion to achieve coloration. Synthetic organic pigments, including azo and phthalocyanine types, constitute the largest product category by volume. Within applications, the paints and inks segments command the majority of consumption, driven by construction and packaging industries respectively.
Regulatory frameworks such as the EU's REACH legislation and the US EPA's Toxic Substances Control Act (TSCA) govern chemical registration and safety. In China, compliance with GB standards for hazardous substances in coatings and plastics is mandatory for market entry. Future competitiveness will depend on developing cost-effective, compliant formulations that meet rising performance expectations in demanding applications.
Market Dynamics
The central tension between rising performance demands from end-users and tightening global chemical regulations is the primary force shaping the classic organic pigments market. Manufacturers must innovate formulations to meet stricter safety and environmental standards without compromising on coloristic properties.
Growth Catalysts
- Automotive Coatings Demand:The automotive sector in industrial economies, including China and India, requires vibrant and durable pigments for OEM and refinish coatings, supporting consumption of high-performance azo and phthalocyanine types.
- High-Performance Pigments:Development of pigments with superior weatherability and lightfastness expands their use in demanding exterior applications like architectural paints and industrial coatings, commanding premium pricing.
- Urbanization in Developing Economies:Rapid construction activity in Southeast Asian countries fuels demand for decorative paints and coatings, which represent a major volume application for classic organic pigments.
Market Restraints
- Raw Material Volatility:Price fluctuations of petrochemical derivatives, such as aromatic intermediates for azo pigments, create margin pressure and make production cost forecasting difficult for manufacturers.
- Regulatory Compliance Costs:Frameworks like the EU's REACH legislation impose significant costs and administrative burdens for chemical registration, testing, and documentation, slowing new product introductions.
- Substitution from Inorganic Pigments:In certain high-heat or extreme-durability applications, high-performance inorganic and specialty effect pigments present a technical substitution threat to classic organic options.
Strategic Opportunities
- Digital Printing Inks:Formulating pigments with nano-scale particle sizes and high purity opens opportunities in the growing market for inkjet inks used in packaging, textiles, and ceramic decoration.
- Bio-Based Formulations:Developing pigments from renewable feedstocks addresses demand for sustainable materials driven by corporate ESG goals and consumer preference, creating a new product category.
- Plastics Market in Latin America:Targeting the masterbatch and compounding sectors in manufacturing hubs like Mexico and Brazil offers growth potential as local production of high-performance pigments is limited.
Industry Challenges
- Global Regulatory Divergence:Managing compliance with disparate chemical control laws, such as the US TSCA and China's GB standards, requires significant legal and technical expertise, complicating global trade.
- Capital-Intensive Production:Achieving the consistent particle size and dispersion quality required by coatings and plastics customers necessitates substantial capital investment in advanced milling, finishing, and quality control equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Classic Organic Pigments Market |
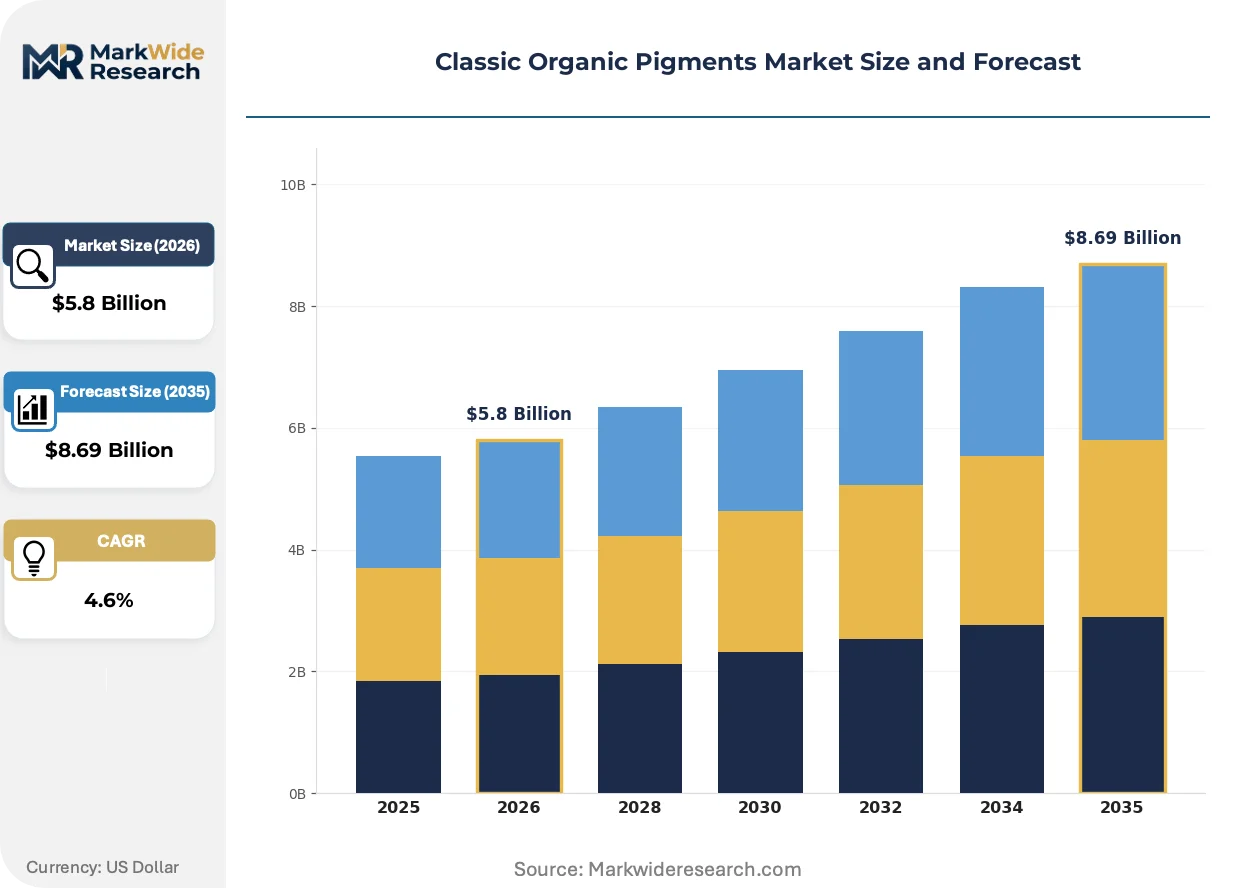
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lake Pigments, Natural Dyes, Synthetic Organic Pigments, Carbon Black Application: Paints, Inks, Plastics, Textiles End User: Manufacturers, Artists, DIY Enthusiasts, Educational Institutions Packaging Type: Bulk Bags, Glass Jars, Plastic Containers, Sachets |
| Companies Covered | Clariant AG, Huntsman Corporation, Cabot Corporation, Lanxess AG, Sudarshan Chemical Industries Limited, DIC Corporation, Sun Chemical Corporation, Ferro Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Classic Organic Pigments Market Strategic Shifts & Innovations
The industry's evolution is defined by a push toward functional and sustainable materials. This shift compels manufacturers to move beyond simple coloration and develop pigments that contribute to the final product's performance and environmental profile, particularly under pressure from regulations.
Encapsulation technology, which coats pigment particles with a protective layer, improves dispersion and chemical resistance. Automotive coatings and plastics compounders are adopting these functionalized pigments to achieve superior durability and processing efficiency. This development of value-added pigments is overtaking the traditional business model of supplying basic, untreated colorants to the market.
The European Union's REACH framework continues to influence product development by restricting or requiring authorization for certain chemical substances. This forces pigment producers to invest in toxicological testing and seek safer alternatives for substances of very high concern (SVHC). The azo and diarylide pigment categories are most affected, prompting a shift toward more complex, compliant chemistries.
A notable behavioral change involves the unbundling of pigment supply from proprietary solvent or resin systems, especially among large industrial users. This allows for more flexible sourcing based on technical specifications rather than being locked into a single supplier's ecosystem. This pattern is most visible in the North American paints and coatings sector, where procurement teams use performance data to optimize cost and quality across multiple vendors.
Classic Organic Pigments Market Segmentation
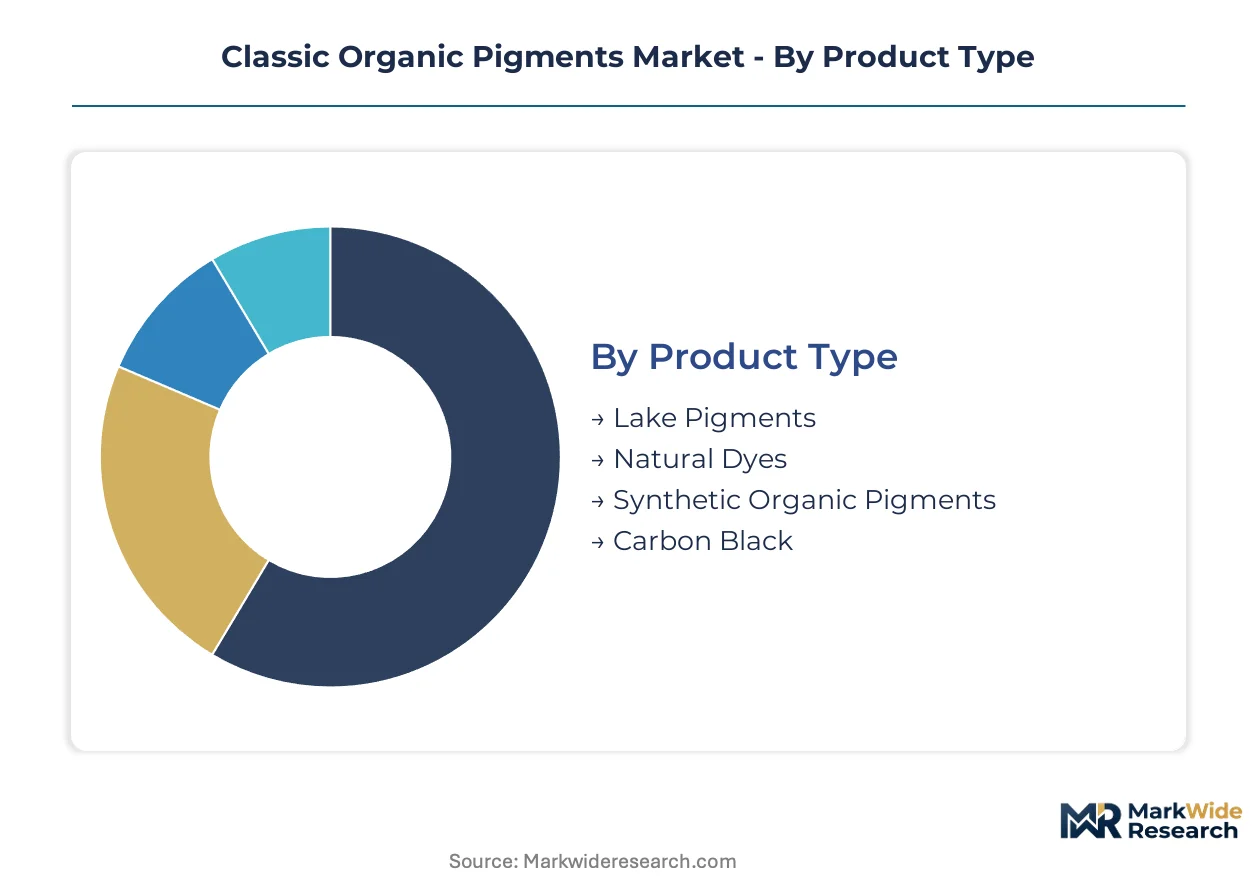
Segmentation within the classic organic pigments market clarifies diverse material compositions and application demands. Understanding these categories guides strategic investment in manufacturing capabilities and R&D. This granular view reveals where specialized production processes are most critical for market differentiation.
Product Type:
The capital intensity of pigment production varies significantly across product types, reflecting diverse synthesis routes and purification requirements.
- Synthetic Organic Pigments:Carbon-based compounds like azo and phthalocyanine types constitute the largest volume category. Demand from the automotive coatings industry in industrial economies like China drives consumption of these high-performance variants.
- Carbon Black:This material is an amorphous carbon form produced by incomplete combustion of hydrocarbons. Its widespread use in rubber, plastics, and printing inks necessitates large-scale, continuous production facilities.
- Lake Pigments:These are insoluble pigments produced by precipitating dyes onto an inert binder. They find use in food, cosmetics, and certain printing inks.
- Natural Dyes:Derived from plant or animal sources, these colorants offer bio-based alternatives. Their production volumes are generally smaller than synthetic options.
Synthetic Organic Pigments absorbs the bulk of installed capacity; Carbon Black is expanding most quickly.
Application:
Application segments exhibit distinct cost-performance requirements, influencing pigment formulation and pricing strategies.
- Paints:This segment consumes a majority of classic organic pigments for architectural, industrial, and automotive coatings. Construction activity in Southeast Asian countries fuels demand for decorative paints.
- Inks:Packaging and digital printing industries drive significant pigment consumption for various ink formulations. The need for high purity and fine particle size is critical for inkjet applications.
- Plastics:Pigments impart color and UV stability to polymers used in consumer goods and automotive components. Masterbatch and compounding sectors are key users.
- Textiles:These pigments provide colorfastness and durability for fabrics. Environmental regulations increasingly influence material selection in this sector.
The paints segment consistently commands the largest volume; digital printing inks are gaining share fastest.
End User:
End-user categories dictate procurement volumes and technical support needs, from large industrial buyers to individual consumers.
- Manufacturers:Industrial-scale producers of coatings, plastics, and inks represent the largest procurement segment. Their technical teams demand precise specifications and consistent supply.
- Artists:This segment requires pigments for fine art applications, prioritizing color intensity and lightfastness. Smaller batch sizes and specialized formulations characterize this niche.
- DIY Enthusiasts:Consumers engaged in home improvement projects utilize pigments in craft paints and hobby supplies. Ease of use and safety are primary considerations.
- Educational Institutions:Schools and universities purchase pigments for teaching purposes and research. Material safety and cost-effectiveness are important.
Manufacturers drive the vast majority of demand; DIY Enthusiasts show consistent, albeit smaller, expansion.
Packaging Type:
Packaging types reflect the scale of procurement and the handling requirements of different customer segments.
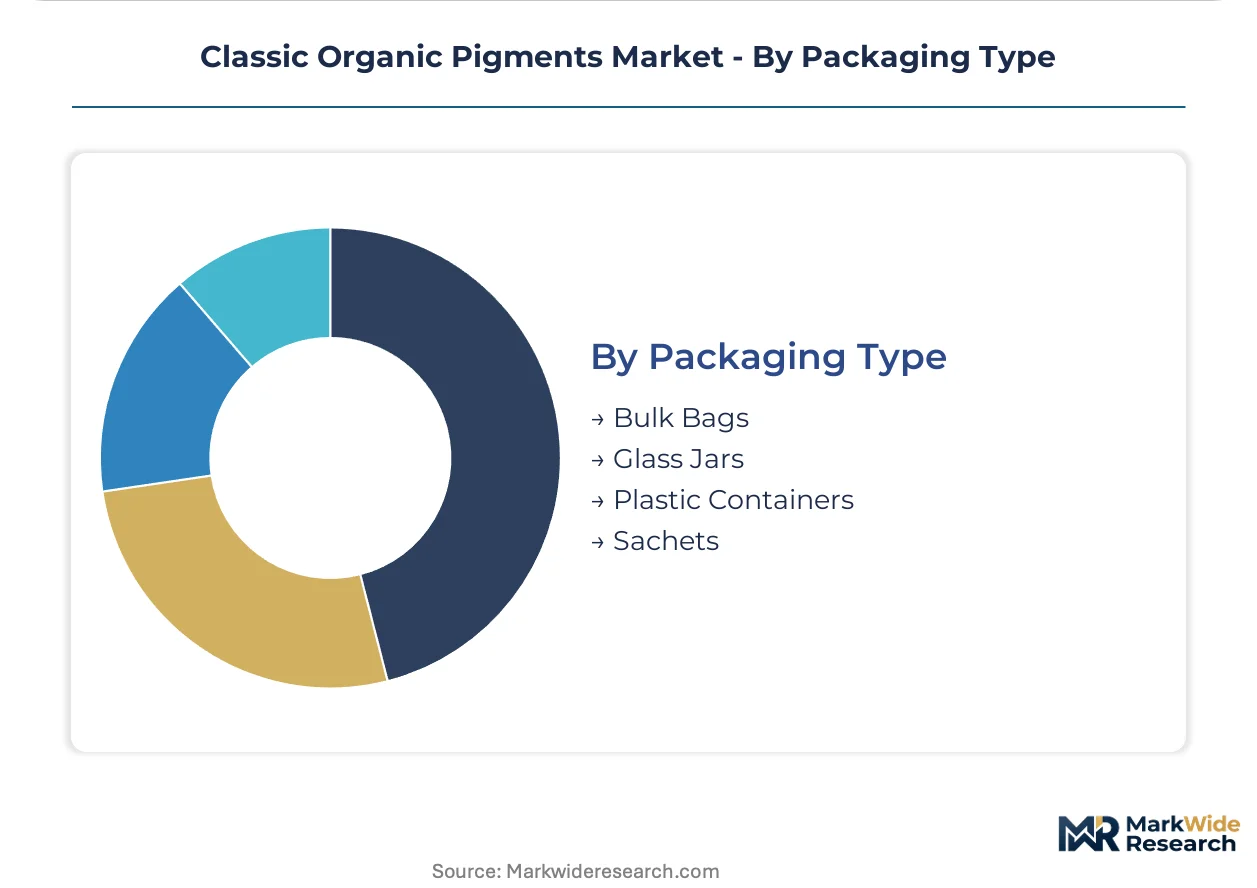
- Bulk Bags:Large industrial users, such as major paint and plastics manufacturers, procure pigments in bulk bags. This packaging minimizes unit cost and streamlines large-volume processing.
- Glass Jars:Specialty pigment suppliers often use glass jars for high-value or sensitive formulations. Artists and R&D laboratories favor this packaging for precise dispensing and storage.
- Plastic Containers:These containers offer versatility for mid-sized orders and various industrial applications. They balance protection with ease of handling.
- Sachets:Small-volume applications or sampling often utilize sachets. They provide convenience for specific craft or hobby markets.
Bulk Bags handle the predominant share of industrial pigment volume; sachets are experiencing growth in niche consumer markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The classic organic pigments market exhibits a distinct production-consumption divide, with manufacturing heavily concentrated in a few industrial powerhouses while demand spans diverse global applications. Key regions drive consumption through their established manufacturing bases and evolving regulatory landscapes. This dynamic influences investment in new capacity and product development across different geographies.
China
Demand for classic organic pigments in China is driven by the automotive and construction sectors, requiring high-performance colorants. The Ministry of Ecology and Environment (MEE) enforces stringent GB standards for hazardous substances in coatings and plastics. Industrial clusters in the Yangtze River Delta actively invest in sustainable pigment production and advanced dispersion technologies.
United States
The United States experiences strong demand from its paints and plastics industries, particularly for exterior architectural coatings and consumer goods. The US EPA's Toxic Substances Control Act (TSCA) governs chemical registration and safety, impacting market access for new pigment formulations. Manufacturing hubs in the Gulf Coast region focus on cost-effective production and supply chain optimization for bulk organic pigments.
Germany
Germany's automotive and specialty inks sectors require premium classic organic pigments with superior lightfastness and weatherability. The EU's REACH framework significantly influences product development, mandating rigorous testing and authorization for chemical substances. Chemical parks like Ludwigshafen specialize in advanced pigment synthesis and sustainable manufacturing processes.
India
Construction and packaging industries in India fuel substantial consumption of classic organic pigments, especially for decorative paints and printing inks. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for chemical products, guiding local manufacturers. Manufacturing zones in Gujarat are expanding production capacities for azo pigments to meet domestic and export demand.
Japan
Japan's electronics and automotive sectors demand high-purity organic pigments for precision coatings and specialized plastics. METI regulations guide chemical management and promote the development of eco-friendly materials within the industry. Industrial centers around Tokyo and Osaka concentrate on R&D for functional pigments and nano-scale dispersion technologies.
Classic Organic Pigments Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered market structure for classic organic pigments. Large chemical producers leverage extensive R&D capabilities and global distribution networks to serve diverse end-user industries. Mid-sized manufacturers often specialize in specific pigment chemistries or application areas, offering tailored solutions. Key strategic archetypes include integrated chemical giants, regional specialists, and niche innovators. Portfolio diversification and strategic partnerships are dominant competitive moves among market participants.
Within the integrated chemical giant archetype, Clariant AG, a Swiss-based chemical company, exemplifies broad portfolio management across various pigment types and applications. German-based BASF SE occupies a position as a leader in high-performance and sustainable pigment formulations, driven by significant investment in research and development. India's Sudarshan Chemical Industries Limited represents a scale-driven specialist, particularly strong in the azo pigment category through cost-efficient manufacturing. These entities anchor the market through their established presence and capacity.
| Leading Market Players |
|---|
| Clariant AG |
| Huntsman Corporation |
| Cabot Corporation |
| Lanxess AG |
| Sudarshan Chemical Industries Limited |
| DIC Corporation |
| Sun Chemical Corporation |
| Ferro Corporation |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Vertically integrated producers of classic organic pigments leverage in-house raw material sourcing, influencing both supply stability and cost-plus pricing models. This structure helps mitigate the impact of volatile input costs across the value chain.
Pricing Analysis
Margin tightening in the bulk organic pigments segment reflects intense competition and overcapacity in certain product categories. The dominant pricing model involves contract-based long-term offtake agreements for large industrial buyers, supplemented by transactional spot pricing for smaller volumes.
Price differentiation stems from quality grade, particularly for high-performance variants, and the volume scale of procurement. Buyer price sensitivity is highest among large manufacturers due to their volume requirements, while artists and specialized niche users are less sensitive, prioritizing color intensity and lightfastness.
Supply Chain Analysis
Azo pigment production rests heavily on petrochemical derivatives, such as aromatic intermediates, sourced primarily from industrial hubs in China and India. Geographic supply concentration for key inputs creates single-source vulnerability as a structural risk.
The distribution model for classic organic pigments predominantly runs through direct sales channels to large industrial manufacturers of paints and plastics. Smaller customers and niche applications often rely on a network of specialized distributors and regional agents for product access and technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The classic organic pigments market is entering a consolidation phase, driven by escalating regulatory compliance costs that disproportionately burden smaller manufacturers.
For Market Incumbents: Lock in long-term supply agreements with key automotive and construction coating manufacturers to secure demand against new entrants. Invest in R&D for compliant, high-performance pigments to counter substitution threats from inorganic alternatives. Leverage global distribution networks and technical support capabilities for deeper market penetration.
For New Entrants and Emerging Players: E-commerce platforms offer a direct route to niche markets like digital printing inks and bio-based formulations. Target the Latin American plastics market with masterbatch solutions, leveraging unmet demand for high-performance options. Focus on developing pigments with nano-scale particle sizes for specialized inkjet applications.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized specialists in European markets, especially those with strong intellectual property in compliant chemistries. Long-term viability rests on innovation in sustainable and functional pigment technologies. Watch for increased M&A activity among regional players as regulatory burdens intensify.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Scaling production in compliant regions reduces per-unit costs for high-volume customers like automotive manufacturers. |
| Green Manufacturing Transition | Adopting sustainable processes attracts environmentally conscious brands and ensures long-term regulatory adherence in Europe. |
| Long-term Supply Agreement | Securing raw material inputs stabilizes production costs amidst petrochemical price volatility for large producers. |
| Joint Venture | Partnering with local distributors in Southeast Asia accelerates market entry for decorative paints and coatings. |
| Product Launch | Introducing new functionalized pigments with improved dispersion enhances performance for plastics compounders. |
Research Approach
Industry association reports, regulatory filings, and company annual statements formed the secondary backbone for this market analysis. Primary interviews with R&D directors, procurement leads, plant managers, and regulatory affairs specialists provided qualitative insights and market validation. This approach ensured bottom-up data aggregation and top-down market consistency.
Bottom-up analysis aggregated segment-level data, while top-down validation ensured market consistency across the analysis window. The forecast framework modeled market dynamics across product type, application, end-user, packaging type, and regional production hubs. Compound annual growth rates were derived through regression analysis and expert consensus, incorporating inputs like raw material price trends and construction spending over the projection horizon.
Inputs from national statistical agencies and major chemical manufacturers were available through the study window; gaps in granular end-user consumption data introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory stability and technological advancements. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Global Cosmetic Dyes Market
Dyes and Pigments
Bio Based Pigments and Dyes Market
Dyes and Pigments
Acid Orange Market
Dyes and Pigments
Thermochromic Labels Market
Dyes and Pigments
Methylene Blue Market
Dyes and Pigments
Plastic Color Concentrates Market
Dyes and Pigments
Titanium Dioxide Pigment Market
Dyes and Pigments
Fluorescent Pigments Market
Dyes and Pigments
Zinc Oxide Pigments Market
Dyes and Pigments
Oil-Dispersible Colors Market
Dyes and Pigments
Pigment Dispersions Market
Dyes and Pigments
Pigment Additive Film Market
Dyes and Pigments
Phthalocyanine Blue Market
Dyes and Pigments
Pearl Pigment Market
Dyes and Pigments
Hair Colorants Market
Dyes and Pigments
Water-Based Pigments Market