
 Africa Polyether Ether Ketone (PEEK) Market | 2026-2036
Africa Polyether Ether Ketone (PEEK) Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Polyether Ether Ketone (PEEK) Market Insights
South Africa's Department of Trade, Industry and Competition is broadening local content requirements for advanced materials in public infrastructure and healthcare procurement. Victrex plc leverages its technical service centers to sustain premium positioning among African medical device converters. Ensinger anchors supply security through regional distribution partnerships that reduce lead times for injection-molded components. Jilin Joinature Polymer Co. Ltd. competes on cost-adjusted purity grades suited to automotive underhood applications.
Polyether ether ketone is a semi-crystalline thermoplastic polymer in the polyaryletherketone family, synthesized through step-growth polymerization of difluorobenzophenone and hydroquinone to achieve a melting point near 343°C and tensile strength exceeding 90 MPa. Its primary purpose is to replace metals in extreme environments where chemical resistance, radiation stability, and continuous service temperatures above 250°C are mandatory. Glass-filled PEEK dominates volume in African aerospace maintenance operations where stiffness-to-weight ratios determine component qualification. Carbon-filled PEEK captures the fastest expansion in automotive lightweighting programs targeting fuel efficiency compliance. Medical-grade natural PEEK commands the deepest margin pools due to biocompatibility certification burdens and surgeon preference consolidation.
Egypt's Ministry of Trade and Industry enforces import conformity assessment protocols that filter substandard polymer grades from entering North African manufacturing channels. South Africa's National Regulator for Compulsory Specifications mandates flame-retardant testing alignment with SANS standards for electrical and transportation applications. Kenya's Bureau of Standards is developing polymer identification protocols that will reshape customs clearance procedures for engineering thermoplastics. Stakeholders must monitor which national standards bodies achieve mutual recognition first, as this will determine regional distribution hub status and captive compounder investment flows.
Market Dynamics
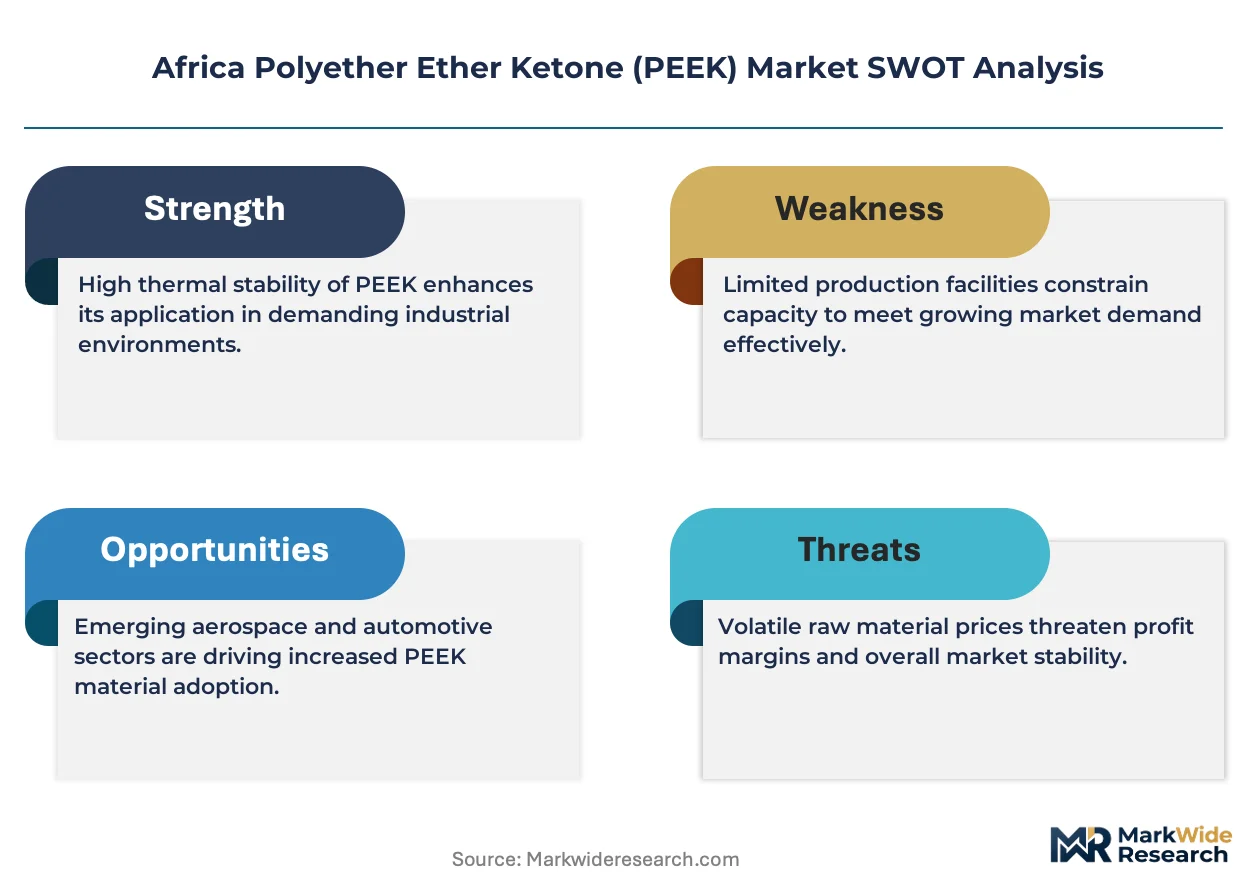
Medical-grade certification requirements are compressing supplier margins while amplifying the premium capture of compounders with biocompatibility dossiers already filed with South Africa's National Regulator for Compulsory Specifications.
Growth Catalysts
- Orthopedic implant demand:Egyptian hospitals are expanding arthroplasty programs that specify PEEK for spinal cages and trauma plates. Cairo's medical device cluster now sources compounded resin locally.
- SANS flame-retardant mandates:South Africa's transportation electrification standards require halogen-free thermoplastics in battery enclosures. PEEK satisfies thermal runaway containment specifications where PA66 fails.
- Suez automotive corridor:Component manufacturers near the canal zone are qualifying carbon-filled grades for underhood brackets. European OEMs with Egyptian satellite plants drive specification pull-through.
Market Restraints
- Fluorobenzophenone feedstock volatility:Difluorobenzophenone prices track Chinese fluorspar export quotas. African compounders lack backward integration into this monomer supply.
- Import conformity friction:Egypt's Ministry of Trade and Industry assessment protocols add 6-8 week clearance delays for non-pre-registered polymer grades. Small converters cannot absorb this working capital burden.
- PEI substitution in electronics:Polyetherimide offers comparable heat resistance at 40% lower resin cost for non-structural electrical connectors. Kenyan appliance assemblers are switching where load-bearing is not required.
Strategic Opportunities
- Kenya polymer identification protocols:The Bureau of Standards is drafting customs testing rules that will favor suppliers with pre-certified material traceability systems. Early compliance investments secure preferred importer status.
- Additive manufacturing convergence:Laser sintering of PEEK powder is enabling patient-specific cranial implants. Johannesburg medical centers are piloting point-of-care printing to bypass import lead times.
- Regional distribution hub consolidation:Mutually recognized standards between South Africa and Egypt would allow single-warehouse stocking for sub-Saharan and North African demand. The first compounder to achieve dual certification captures logistics arbitrage.
Industry Challenges
- Medical-grade compounding expertise scarcity:ISO 13485 auditors with polymer-specific experience are concentrated in Cape Town and Johannesburg. Egyptian and Kenyan converters face 12-18 month quality system implementation timelines.
- Injection molding equipment capex intensity:Processing PEEK requires barrel temperatures above 380°C and corrosion-resistant screws. African toll compounders cannot amortize this machinery without minimum 500-tonne annual volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Polyether Ether Ketone (PEEK) Market |
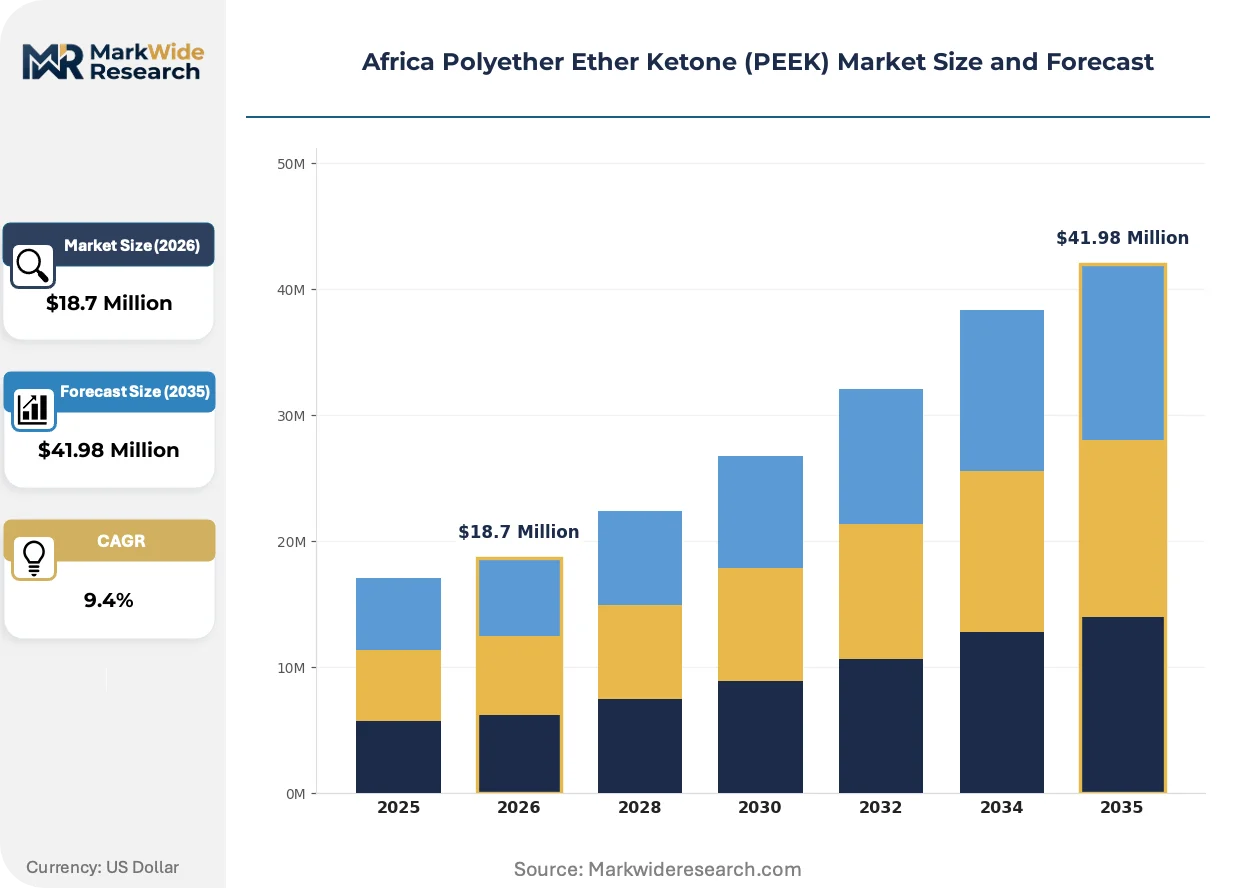
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $41.98 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural PEEK, Glass-Filled PEEK, Carbon-Filled PEEK, Chemical-Resistant PEEK End Use Industry: Aerospace, Automotive, Medical, Electrical Form: Sheet, Rod, Tube, Coating Technology: Injection Molding, 3D Printing, Thermoforming, Compression Molding |
| Companies Covered | Jilin Joinature Polymer Co. Ltd., Ensinger, Victrex plc, Zhejiang PFLUON, Solvay, Evonik Industries AG, Pan Jin Zhongrun High-Performance Polymer Co. Ltd., ZYPEEK, Syensqo, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Polyether Ether Ketone (PEEK) Market Trends and Innovations
Processing technology advances and regulatory harmonization pressures are redrawing competitive boundaries between regional compounders and direct resin importers across North and sub-Saharan Africa.
Carbon-filled PEEK compounds are overtaking glass-filled alternatives in automotive structural brackets. Tier-1 suppliers in Egypt's Suez corridor are specifying 30% carbon fiber grades for engine mount applications where stiffness targets previously demanded aluminum. This material transition is compressing the qualification timeline for metal replacement programs from 18 months to 9 months.
South Africa's National Regulator for Compulsory Specifications is aligning SANS electrical safety standards with IEC thermal endurance test protocols. This regulatory convergence forces compounders to retest legacy formulations against revised glow-wire and tracking resistance benchmarks. Medical device exporters targeting both African and European markets now favor dual-certified resin stocks to avoid separate inventory pools.
Converter procurement patterns are fragmenting toward project-specific spot purchasing. Large Egyptian automotive assemblers are bypassing annual resin contracts in favor of quarterly tenders indexed to European polymer futures. This behavioral shift concentrates volume risk with compounders while transferring price volatility exposure downstream to resin distributors in Alexandria and Port Said.
Africa Polyether Ether Ketone (PEEK) Market Segmentation
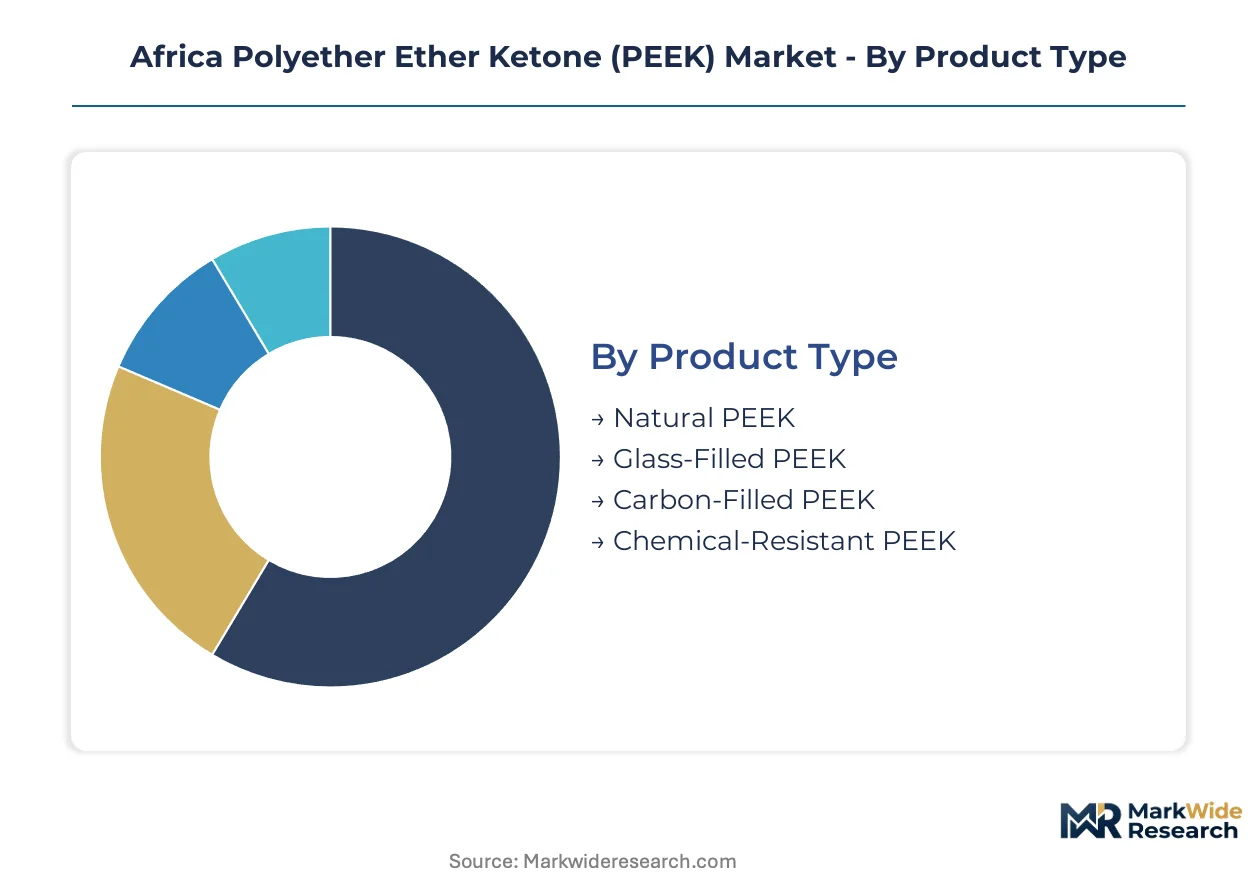
Certification requirements fragment PEEK demand across Africa, with medical-grade natural resin commanding premium positioning while automotive carbon-filled grades scale volume. Segmentation discipline reveals where compounders must build dossiers versus where cost-adjusted purity wins procurement.
Product Type:
ISO 10993 biocompatibility testing burdens fall heaviest on natural PEEK, while SANS flame-retardant mandates reshape glass-filled and carbon-filled qualification pathways.
- Natural PEEK:Unfilled resin achieves crystallinity above 30% after controlled cooling, delivering the purest mechanical properties for implantable devices. Egyptian spinal cage manufacturers now source medical-grade natural PEEK locally to bypass import lead times for arthroplasty programs.
- Carbon-Filled PEEK:30% carbon fiber loading pushes flexural modulus past 15 GPa, enabling aluminum replacement in engine brackets. Suez corridor automotive plants specify this grade for underhood structural components where European OEMs drive specification pull-through.
- Glass-Filled PEEK:30% glass fiber reinforcement balances cost against stiffness for non-structural electrical housings. Kenyan appliance assemblers favor this grade where load-bearing demands are moderate.
- Chemical-Resistant PEEK:Modified formulations withstand concentrated acids in process equipment. South African mining chemical processors specify this variant for pump housings and valve components.
Glass-filled PEEK sits at the top of the volume ranking, with carbon-filled PEEK climbing the fastest.
End Use Industry:
Application-specific thermal and mechanical thresholds determine whether compounders compete on certification depth or cost-adjusted performance.
- Aerospace:Glass-filled grades dominate MRO operations where stiffness-to-weight ratios determine component qualification for interior brackets and cable management systems.
- Automotive:Carbon-filled PEEK captures structural bracket applications as Egyptian plants serving European OEMs accelerate metal replacement programs.
- Medical:Natural PEEK commands the deepest margin pools due to biocompatibility certification burdens and surgeon preference consolidation in Cairo and Johannesburg hospital systems.
- Electrical:Flame-retardant formulations align with SANS transportation electrification standards for battery enclosures where thermal runaway containment is mandatory.
Medical applications generate the highest margin per kilogram, though automotive volumes are expanding most rapidly.
Form:
Stock shape availability shapes converter procurement patterns, with near-net forms reducing machining waste for low-volume medical applications.
- Sheet:Compression-molded plates serve aerospace panel fabricators and semiconductor fixture builders requiring flat stock for CNC machining.
- Rod:Extruded round stock dominates general machining applications across South African industrial distributors serving multiple end-use sectors.
- Tube:Hollow profiles reduce material waste for bearing cages and seal housings in chemical processing equipment.
- Coating:Powder and dispersion forms enable corrosion protection on metal substrates for oilfield components in North African extraction operations.
Rod forms account for the broadest distribution footprint, while tube configurations are gaining share fastest in precision mechanical applications.
Technology:
Processing temperature requirements and equipment capital intensity stratify converter capabilities across the continent.
- Injection Molding:Barrel temperatures above 380°C and corrosion-resistant screws demand specialized machinery. African toll compounders cannot amortize this equipment without minimum volume commitments.
- 3D Printing:Laser sintering of PEEK powder enables patient-specific cranial implants. Johannesburg medical centers pilot point-of-care production to bypass import lead times entirely.
- Thermoforming:Sheet heating and vacuum forming suit aircraft interior panels where complex curves are required at lower tooling cost than injection molding.
- Compression Molding:Direct powder consolidation serves thick-section components like semiconductor wafer handling fixtures where uniform crystallinity is critical.
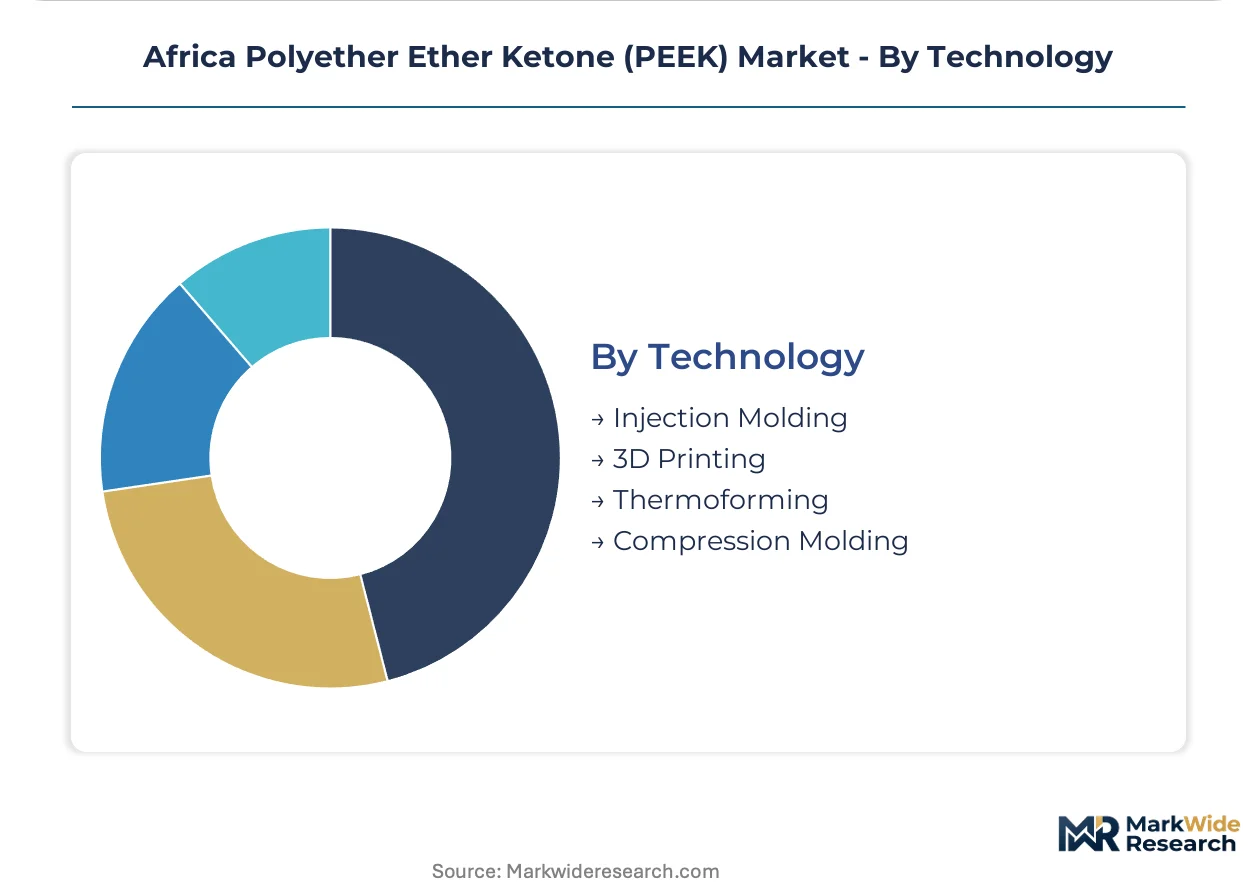
Injection molding retains the largest installed base, with 3D printing posting the steepest expansion trajectory in medical device fabrication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PEEK polymer commercialization traces to 1978 when Imperial Chemical Industries first scaled production in the United Kingdom. African demand emerged later through South African mining equipment imports and Egyptian petrochemical infrastructure. Today the continent's consumption concentrates in five national markets with divergent regulatory maturity and industrial specialization.
South Africa
Orthopedic implant manufacturers in Johannesburg and Cape Town drive medical-grade PEEK consumption for spinal cages and trauma fixation devices. The National Regulator for Compulsory Specifications enforces SANS flame-retardant standards for transportation electrification components. Gauteng Province hosts the continent's deepest concentration of ISO 13485-certified polymer compounders serving hospital procurement networks.
Egypt
Automotive component suppliers near the Suez Canal specify carbon-filled PEEK for European OEM satellite plants producing underhood structural brackets. The Ministry of Trade and Industry operates import conformity assessment protocols that filter substandard polymer grades through 6-8 week clearance procedures. Cairo's medical device cluster now sources compounded resin locally for expanding arthroplasty programs.
Kenya
Appliance assemblers in Nairobi are substituting polyetherimide for PEEK in non-structural electrical connectors where load-bearing demands are absent. The Bureau of Standards is drafting polymer identification protocols that will reshape customs clearance procedures for engineering thermoplastics. Mombasa port logistics determine regional distribution economics for East African converters.
Morocco
Aerospace maintenance operations in Casablanca utilize glass-filled PEEK for interior bracket applications where stiffness-to-weight ratios determine component qualification. The country's national standards body maintains alignment with EASA maintenance protocols for polymer qualification in aircraft interior applications. Tangier Med port infrastructure supports just-in-time resin delivery for Moroccan industrial distributors.
Nigeria
Oilfield equipment fabricators in Lagos specify chemical-resistant PEEK formulations for pump housings and valve components in hydrocarbon extraction operations. The country's national petroleum regulator is developing performance standards for high-performance polymers used in critical downhole applications. Port Harcourt's industrial zone hosts the largest concentration of polymer converters serving West African energy infrastructure.
Africa Polyether Ether Ketone (PEEK) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and biocompatibility dossier completeness. The vendor base stratifies into three tiers: integrated resin producers with African technical service centers, regional distribution partners securing supply security through inventory positioning, and cost-adjusted purity specialists competing on automotive underhood specifications. Dominant competitive moves include strategic partnerships with local compounders to bypass import conformity friction and technology licensing arrangements that transfer medical-grade processing expertise.
Within the premium-tier certification vector, Victrex plc and Ensinger occupy positions anchored by technical service infrastructure and regional distribution partnerships respectively. Jilin Joinature Polymer Co. Ltd. exemplifies the cost-adjusted purity archetype competing on automotive-grade specifications. These three entities represent the competitive spectrum from biocompatibility-certified medical resin to industrial-grade compounds suited for underhood metal replacement programs.
| Leading Market Players |
|---|
| Jilin Joinature Polymer Co. Ltd. |
| Ensinger |
| Victrex plc |
| Zhejiang PFLUON |
| Solvay |
| Evonik Industries AG |
| Pan Jin Zhongrun High-Performance Polymer Co. Ltd. |
| ZYPEEK |
| Syensqo |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed Chinese resin producers and family-owned European compounders anchor supply-side ownership patterns that compress margin capture for African distributors while reinforcing certificate-based pricing discipline across medical-grade tiers.
Pricing Analysis
Three-tier pricing structure across medical-certified, industrial-performance, and automotive-economy levels stratifies PEEK procurement across African converter networks. Price differentiation rests on ISO 13485 biocompatibility dossier completeness versus SANS flame-retardant compliance versus raw purity grades for underhood applications. Cost compression in industrial-performance tiers is intensifying because Egyptian automotive assemblers index quarterly tenders to European polymer futures. Medical device manufacturers in Johannesburg exhibit the lowest price sensitivity due to surgeon preference consolidation, while Kenyan appliance assemblers drive the sharpest procurement negotiation on non-structural electrical grades.
Supply Chain Analysis
Dual-sourcing qualification requirements from European OEM satellite plants in Egypt's Suez corridor mandate multi-supplier approval for carbon-filled PEEK grades, fragmenting volume commitments across compounders. Feedstock supply concentrates in China for difluorobenzophenone monomer, the United Kingdom for virgin resin polymerization, and Germany for medical-grade compounding expertise. Raw material dependencies draw from Chinese fluorspar export quotas, European hydroquinone availability, and regional carbon fiber tow supply. Single-source vulnerability runs through Chinese monomer export license volatility. Distribution runs through Alexandria and Port Said port complexes for North African demand, with Johannesburg logistics hubs serving sub-Saharan converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where orthopedic implant specification shifts toward patient-specific additive manufacturing deepen premium-grade PEEK demand across Egyptian and South African hospital systems.
For Market Incumbents: Deploy technical service center expansion as the primary lever to sustain premium positioning against cost-adjusted purity specialists entering from Chinese resin producers. Deepen backward integration into medical-grade compounding expertise through Cape Town and Johannesburg facility investment to counter ISO 13485 auditor scarcity threatening Egyptian and Kenyan converter qualification timelines. Fortify distribution partnerships that reduce lead times for injection-molded components, insulating against import conformity friction at Egyptian ports. For New Entrants and Emerging Players: Begin with Kenya's polymer identification protocol compliance to secure preferred importer status before Bureau of Standards customs testing rules reshape East African engineering thermoplastic clearance procedures. Target additive manufacturing powder supply for Johannesburg medical centers piloting point-of-care cranial implant production, bypassing established resin distributor networks entirely. Pursue toll compounding arrangements with Egyptian automotive assemblers seeking carbon-filled grade qualification without captive injection molding equipment capex burden. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distribution partners lacking dual-certification dossiers for both South African SANS and Egyptian import conformity protocols. Long-term viability centers on compounders achieving mutually recognized standards status to capture logistics arbitrage across sub-Saharan and North African warehouse consolidation. Monitor which national standards bodies achieve mutual recognition first as the signal for regional distribution hub investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Medical-Grade Compounding Capacity Expansion | Cairo compounders bypass import lead times for Egyptian arthroplasty program demand. |
| Backward Integration into Difluorobenzophenone Feedstock | African resin producers reduce exposure to Chinese fluorspar export quota volatility. |
| Additive Manufacturing Powder Supply Partnership | Johannesburg hospitals secure patient-specific implant material for point-of-care printing. |
| Dual-Certification Logistics Hub Consolidation | Single-warehouse stocking captures arbitrage across SANS and Egyptian conformity protocols. |
| Regional Distribution Partnership Restructuring | Ensinger-style inventory positioning reduces lead times for Suez corridor automotive plants. |
Research Methodology
Multiple input streams — technical discussions with polymer compounder plant managers, procurement leads at Egyptian automotive OEM satellite plants, distribution channel partners in Alexandria and Mombasa, and biomedical engineers at Johannesburg hospital systems — were reconciled against customs and trade data, SEC filings from listed resin producers, SANS standards documentation, and Egyptian Ministry of Trade import conformity protocols. Secondary validation drew from engineering thermoplastic industry association reports and medical device regulatory filings. Bottom-up volume estimates from converter procurement patterns and top-down demand modeling from end-use industry consumption were triangulated to produce segmentation outputs.
Data-stream reconciliation across the projection horizon applied grade-tier, end-use industry, and regional production hub dimensions to model natural, carbon-filled, glass-filled, and chemical-resistant PEEK demand. CAGRs were derived from elasticity-adjusted consumption trajectories across medical implant, automotive lightweighting, and electrical enclosure applications. Forecast inputs incorporated SANS flame-retardant mandate implementation timelines, Egyptian import conformity assessment clearance patterns, and Kenya polymer identification protocol development status.
Several conditions sit outside the modeled scope, including unannounced changes to Chinese fluorspar export licensing, sudden SANS-IEC standard divergence, and Egyptian regulatory body restructuring. Forecasts reflect assumptions regarding continued European OEM satellite plant operation in the Suez corridor and sustained Johannesburg medical center additive manufacturing pilot program expansion. Deviation in Chinese monomer supply policy or South African-Egyptian standards mutual recognition timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyurethane Dispersions Market
Polymers & Resins
Biopolymer Tubes Market
Polymers & Resins
Asia-Pacific Fluoropolymer Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Resins Market
Polymers & Resins
Middle-East and Africa Epoxy Resins Market
Polymers & Resins
Polyethylene Naphthalate Market
Polymers & Resins
Global Polymer Stabilizer Market
Polymers & Resins
Global Ultra-High Molecular Weight Polyethylene Market
Polymers & Resins
Rotomolding Compound Market
Polymers & Resins
Global Polybutene Market
Polymers & Resins
Polyamide 12 Market
Polymers & Resins
Global Polyethyleneimine Market
Polymers & Resins
Hybrid Polymer Market
Polymers & Resins
Polyvinyl Alcohol (PVA) Market
Polymers & Resins
Biobased Thermosetting Polymers Market