
 Electron Beam Curable Coating Market | 2026-2036
Electron Beam Curable Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Electron Beam Curable Coating Market Analysis
REACH is pivoting the European cost-of-entry calculus for new EB coating suppliers by mandating exhaustive substance registration and downstream communication obligations. Arkema leverages its integrated acrylic oligomer supply chain to sustain margin pressure from compliance outlays. BASF SE anchors its position through cationic epoxy formulations that navigate tighter VOC ceilings in automotive clear coats. Allnex GmbH specializes in radiation-cure resin platforms that dominate wood coating applications across Central European furniture clusters.
Electron beam curable coatings are solvent-free formulations that polymerize instantly under accelerated electron bombardment, typically operating at 150–300 kV with dose rates of 20–150 kGy to achieve full cure in milliseconds without thermal degradation of temperature-sensitive substrates. Their primary purpose is delivering high-performance surface protection for automotive interiors, flexible packaging films, and electronic components where heat-based curing risks warping or discoloration. Clear coating formulations occupy the largest value pool due to their dominance in automotive topcoats and optical film laminates, while pigmented coating systems represent the fastest-expanding segment as electronics manufacturers adopt colored EB finishes for device housings. Free radical technology leads unit volume through its maturity in acrylate-based systems, though hybrid cure platforms are capturing margin-rich niches in multi-substrate packaging lines requiring sequential UV-EB processing.
The EPA enforces stringent VOC emission thresholds under the National Emission Standards for Hazardous Air Pollutants that constrain conventional solvent-borne coating operations and redirect capital toward EB infrastructure. ECHA administers REACH substance restrictions that shape monomer selection and crosslinker chemistry across European formulation labs. OSHA workplace exposure limits for acrylate monomers influence equipment enclosure standards and operator safety protocols at EB installation sites. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as fluorinated additives common in EB release coatings face prospective phase-downs that could force reformulation cycles across packaging and electronics end uses.
Market Dynamics
REACH substance registration obligations are restructuring European entry economics for electron beam coating suppliers, forcing exhaustive downstream communication protocols that favor incumbents with captive oligomer production.
Growth Catalysts
- EPA NESHAP VOC thresholds:The National Emission Standards for Hazardous Air Pollutants constrain solvent-borne coating operations across automotive finishing lines, redirecting capital expenditure toward electron beam infrastructure in Michigan and Ohio manufacturing clusters.
- Automotive interior trim:OEM specifications for under-hood components now mandate EB-cured finishes to meet volatile organic compound limits without thermal degradation of polypropylene substrates.
- Acrylate oligomer availability:Backward integration into acrylic monomer supply secures formulation continuity for radiation-cure resin platforms serving Central European furniture coating applications.
Market Restraints
- Electron beam equipment capex:Industrial-grade accelerators operating at 150–300 kV require substantial upfront investment, limiting adoption to tier-one suppliers with multi-line throughput.
- Acrylate monomer supply concentration:Feedstock availability clusters around integrated petrochemical complexes, exposing formulators to input cost volatility during cracker maintenance cycles.
- Substrate thickness limitations:Electron penetration depth constraints restrict EB curing to films and coatings under 100 micrometers, excluding heavy-duty industrial protective applications.
Strategic Opportunities
- Hybrid UV-EB platforms:Sequential processing lines combining ultraviolet pre-gel with electron beam final cure enable multi-substrate packaging applications previously unreachable for pure EB systems.
- India automotive belt:PLI scheme incentives for domestic component manufacturing create first-mover advantage for EB coating installation near Chennai and Pune assembly plants.
- Pigmented electronics housings:Colored EB finishes for consumer device enclosures represent an emerging application segment as electronics manufacturers seek solvent-free alternatives to thermal powder coatings.
Industry Challenges
- Accelerator technician scarcity:Specialized expertise in high-voltage electron beam system maintenance remains concentrated among legacy equipment operators, constraining line expansion timelines.
- OSHA acrylate exposure compliance:Workplace monomer concentration limits demand engineered enclosure systems and continuous monitoring infrastructure at installation sites.
- Legacy thermal cure integration:Retrofitting existing coating lines with electron beam capability requires extensive conveyor reconfiguration and shielding installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electron Beam Curable Coating Market |
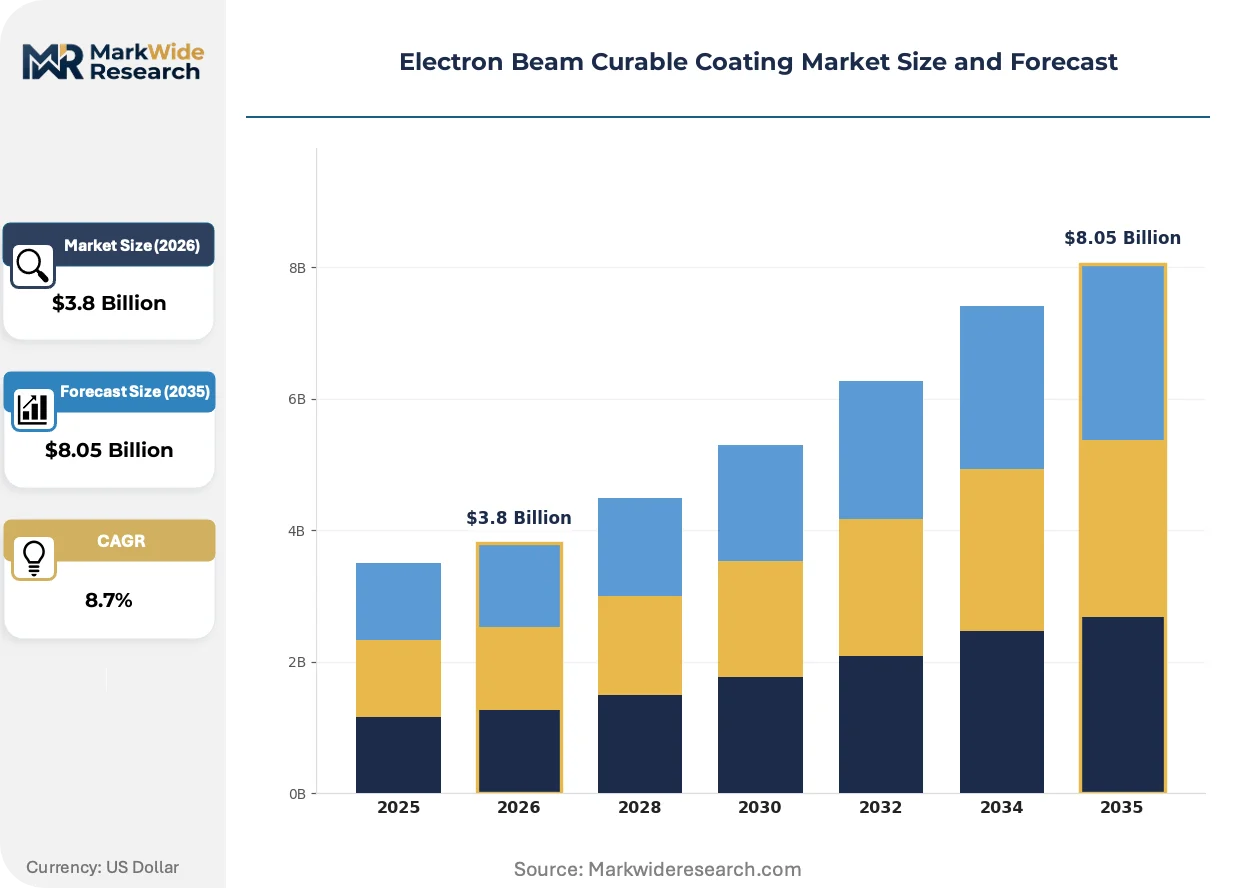
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Coating, Pigmented Coating, Flexible Coating, UV Curable Coating Application: Automotive, Electronics, Packaging, Wood Coatings Technology: Free Radical, Cationic, Hybrid, Radiation Cure End User: Manufacturers, Contractors, Retailers, Distributors |
| Companies Covered | Arkema, BASF SE, PPG Industries, Sun Chemical, Covestro AG, Allnex GmbH, AkzoNobel, IGM Resins BV, Beckers Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electron Beam Curable Coating Market Emerging Trajectories
Formulation chemistry is pivoting toward oligomer-heavy systems as regulatory pressure on monomer content intensifies, while equipment manufacturers advance hybrid processing architectures that bridge UV and EB curing modalities.
Water-dilutable EB coatings are overtaking conventional solvent-free formulations in automotive clear coat applications. Tier suppliers in Germany's manufacturing belt are adopting these systems to maintain film performance while reducing handling viscosity. This technology is overtaking standard 100% solids acrylates in facilities requiring ambient-temperature application without heated tanks.
ECHA REACH restrictions on residual monomer content are compelling formulators to redesign crosslinker architectures. The industrial consequence is accelerated R&D spending on hyperbranched oligomer platforms that achieve equivalent cure response with lower molecular weight extractables. Wood coating applications across Bavarian furniture clusters are most affected, with manufacturers reformulating to preempt downstream communication obligations.
Buyer concentration among automotive OEMs is compressing supplier qualification timelines. Tier-one coating houses now face accelerated validation cycles for new EB formulations, replacing traditional 18-month approval windows with compressed six-month programs. This pattern is most visible in Stuttgart and Wolfsburg supply sheds, where just-in-sequence delivery requirements dominate procurement specifications.
Electron Beam Curable Coating Market Segmentation
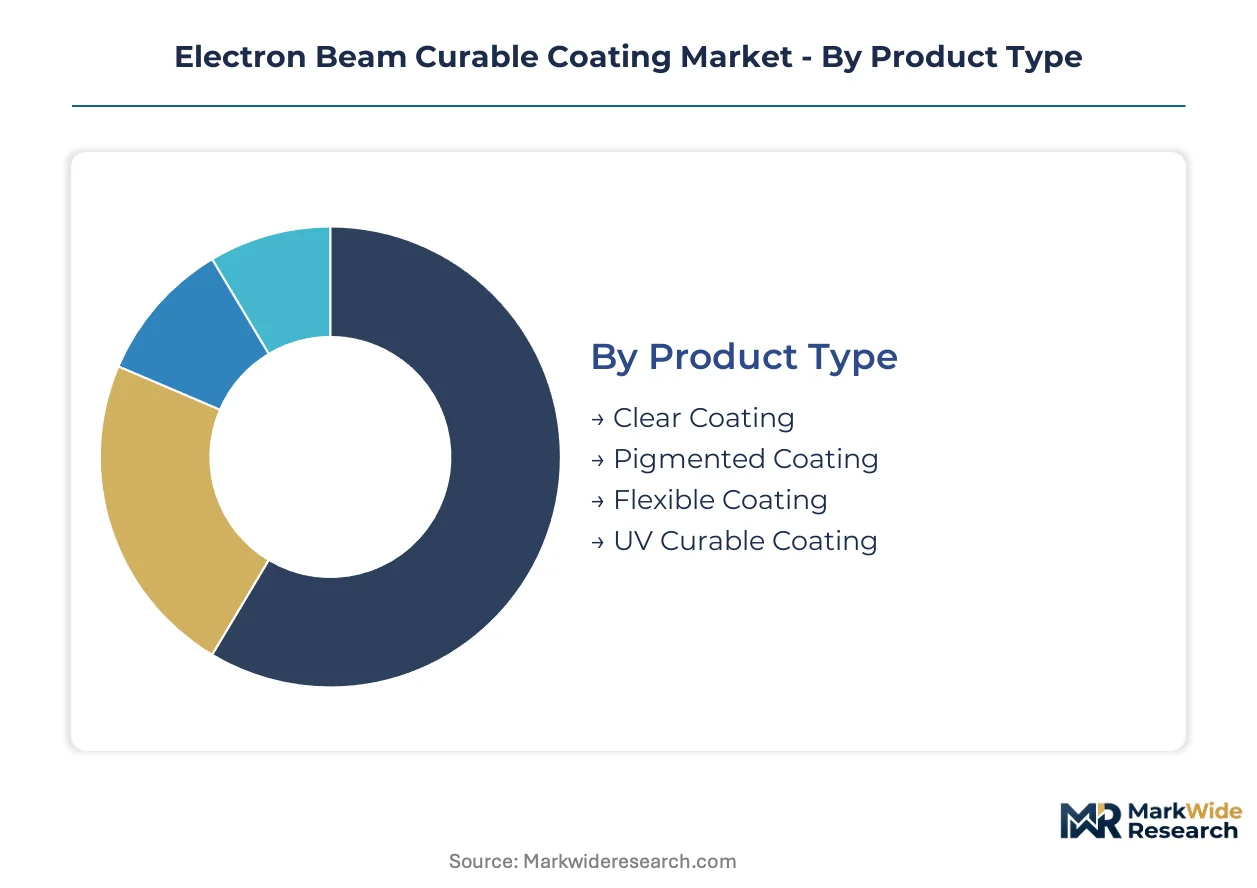
Electron beam curable coatings fragment across formulation chemistry, substrate requirements, and curing architecture. Each axis carries distinct margin profiles and regulatory exposure. Understanding these divisions clarifies where capital deployment concentrates versus where incumbent positions prove defensible.
Product Type:
Formulation transparency and pigment load determine electron penetration efficiency and final surface aesthetics.
- Clear Coating:Solvent-free acrylate oligomer systems dominate automotive topcoats and optical film laminates where clarity and scratch resistance are paramount. Demand concentrates in Germany's automotive belt, where tier suppliers operate electron beam lines at scale to meet OEM volatile organic compound specifications for interior trim components.
- Pigmented Coating:Colored EB finishes incorporate dispersed colorants that scatter electron beams and require adjusted dose rates to achieve through-cure without surface defects. Electronics manufacturers in Asian assembly hubs are adopting these systems for device housings, displacing thermal powder coatings to eliminate solvent handling entirely.
- Flexible Coating:Low-modulus formulations accommodate substrate elongation in packaging films and conformable electronics.
- UV Curable Coating:Photoinitiator-dependent systems that overlap with EB technology in hybrid processing architectures.
Mature deployment sits with Clear Coating. Newer deployment is concentrated in Pigmented Coating.
Application:
Substrate thermal tolerance and production throughput requirements dictate curing modality selection across end-use verticals.
- Automotive:Under-hood components and interior trim specifications mandate EB-cured finishes to satisfy volatile organic compound limits without warping temperature-sensitive polypropylene substrates. Michigan and Ohio manufacturing clusters are redirecting capital expenditure toward electron beam infrastructure as EPA NESHAP thresholds tighten.
- Electronics:Printed circuit board conformal coatings and device housing finishes demand instantaneous cure to protect heat-sensitive components. The segment is expanding most quickly as manufacturers seek solvent-free alternatives to thermal curing processes that risk solder joint damage.
- Packaging:Flexible film laminates and folding carton coatings prioritize speed and food-contact compliance.
- Wood Coatings:Furniture and flooring applications in Central European clusters favor radiation-cure systems for scratch resistance and chemical durability.
Established volume sits with Automotive. Steepest expansion trajectory belongs to Electronics.
Technology:
Polymerization mechanism determines formulation latitude, substrate compatibility, and equipment configuration requirements.
- Free Radical:Acrylate-based systems cure through radical chain propagation initiated by electron bombardment, offering the broadest formulation maturity and raw material availability. The technology anchors unit volume across automotive and packaging applications where oxygen inhibition is manageable through nitrogen inerting.
- Cationic:Epoxy and vinyl ether systems polymerize via acid-catalyzed ring-opening, enabling through-cure in thick films and pigmented systems with minimal oxygen sensitivity. BASF SE anchors its market position through these formulations, navigating tighter VOC ceilings in automotive clear coats where latency and adhesion are critical.
- Hybrid:Sequential UV-EB processing lines combine photoinitiator pre-gel with electron beam final cure for multi-substrate packaging applications.
- Radiation Cure:Encompassing both EB and UV modalities, this broader category captures formulation platforms designed for energy-beam processing generally.
Process maturity clusters around Free Radical. Technical differentiation is migrating toward Cationic.
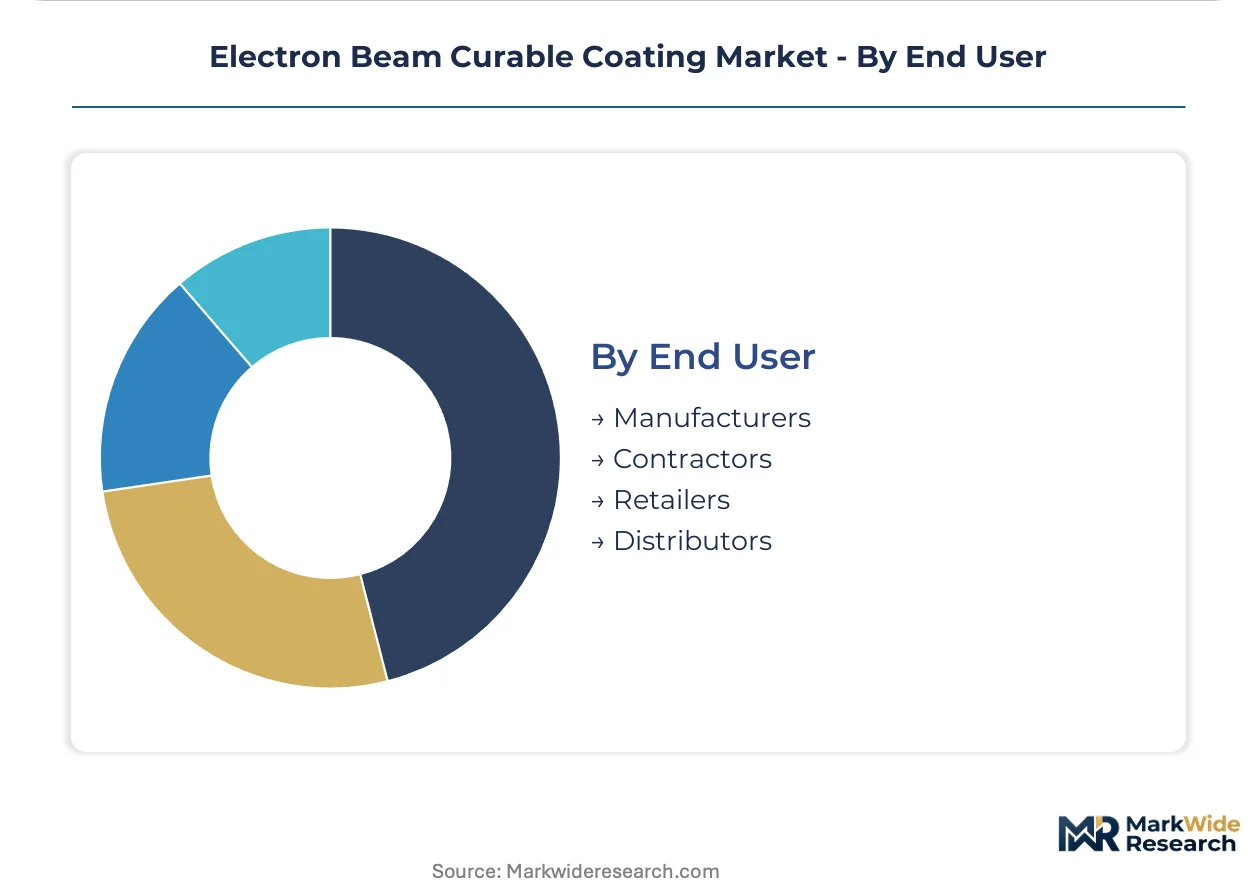
End User:
Purchasing sophistication and formulation control requirements segment the customer base across the value chain.
- Manufacturers:OEMs and tier suppliers with captive coating operations specify EB systems to integrate surface finishing with assembly sequences. These buyers concentrate demand in Germany's automotive belt and Michigan manufacturing clusters, where just-in-sequence delivery requirements dominate procurement specifications and compress supplier qualification timelines.
- Contractors:Specialty applicators serving fragmented wood coating and industrial maintenance markets purchase formulated systems for job-shop deployment.
- Retailers:Consumer-facing channels for DIY and small-volume professional segments represent minimal EB penetration due to equipment requirements.
- Distributors:Intermediaries stocking radiation-cure resins and formulated coatings serve regional formulators without captive oligomer supply.
Contractor relationships dominate Wood Coatings. Direct manufacturer integration commands Automotive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive scheme for automotive component manufacturing is concentrating EB coating demand near Chennai and Pune assembly corridors. Special economic zones in Vietnam and Mexico are attracting packaging film producers seeking duty-free export access.
United States
EPA NESHAP VOC thresholds are redirecting capital expenditure toward electron beam infrastructure in Michigan and Ohio automotive manufacturing clusters. Tier suppliers operate multi-line EB systems to satisfy OEM volatile organic compound specifications for interior trim and under-hood polypropylene components.
Germany
REACH substance registration obligations favor incumbents with captive oligomer production in Baden-Württemberg and Bavaria. Stuttgart and Wolfsburg supply sheds compress supplier qualification timelines to six-month programs for just-in-sequence coating delivery to automotive OEMs.
China
Electronics manufacturers in the Yangtze River Delta are adopting pigmented EB finishes for device housings to displace thermal powder coatings. MIIT industrial standards for solvent-free processing accelerate adoption across Shenzhen and Dongguan assembly hubs.
Japan
METI energy efficiency directives support EB curing adoption for flexible packaging films in the Chubu industrial corridor. Nagoya-based film laminators integrate hybrid UV-EB processing lines to serve food-contact applications with reduced thermal degradation risk.
India
PLI scheme incentives for domestic automotive component manufacturing create first-mover advantage for EB coating installation near Chennai and Pune. BIS standards for volatile organic compound emissions in industrial coatings align with tier supplier qualification requirements from multinational OEMs.
Electron Beam Curable Coating Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and equipment integration vectors. Market structure tilts toward consolidated oligomer supply chains with fragmented downstream formulation houses. Three archetypes dominate: integrated petrochemical players with captive acrylic feedstock, radiation-cure resin specialists, and diversified coating houses with automotive OEM relationships. Competitive moves cluster around backward integration into monomer supply and hybrid processing technology licensing.
Among European-based chemical conglomerates, Arkema and BASF SE exemplify integrated archetypes with oligomer production capabilities. Allnex GmbH occupies a position as a radiation-cure resin platform specialist serving Central European furniture clusters. These three anchors represent divergent strategic postures: petrochemical integration versus formulation focus versus application-specific resin development.
| Leading Market Players |
|---|
| Arkema |
| BASF SE |
| PPG Industries |
| Sun Chemical |
| Covestro AG |
| Allnex GmbH |
| AkzoNobel |
| IGM Resins BV |
| Beckers Group |
| Others |
Supply Flow & Price Mechanics
Hybrid UV-EB processing architectures are compressing unit economics while redistributing bargaining power toward equipment-integrated formulators with captive oligomer supply. This technology transition simultaneously elevates capital barriers for new entrants and rewards backward-integrated incumbents with margin capture across formulation and curing system supply.
Pricing Analysis
Lead-time-driven pricing stratification separates emergency spot orders from scheduled contract volumes across EB coating procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from acrylate monomer feedstock volatility during cracker maintenance cycles. Tier-one automotive OEMs exhibit lowest price sensitivity due to just-in-sequence delivery requirements, while wood coating contractors face acute margin compression from oligomer cost pass-through.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for automotive coating lines near Chennai and Pune assembly corridors. Feedstock availability clusters around integrated petrochemical complexes in Germany, China, and the United States, exposing formulators to input cost volatility. Supply chain risk centers on single-source vulnerability for specialized acrylate oligomers. Distribution runs through direct manufacturer relationships in automotive and distributor networks serving fragmented wood coating applicators.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive oligomer production determines formulation continuity and margin defense. Players are pursuing upstream control over acrylic monomer supply to secure input cost stability.
For Market Incumbents: Deepen backward integration into acrylate monomer supply to neutralize feedstock volatility threats from cracker maintenance cycles. Expand high-voltage accelerator technician training programs to alleviate capability scarcity constraining line expansion timelines. Prioritize cationic epoxy formulation R&D to differentiate beyond commoditized free-radical acrylate platforms. For New Entrants and Emerging Players: The gap between premium cationic clear coats and economy free-radical pigmented systems offers white-space entry near India's PLI scheme automotive clusters. Target electronics housing applications in Asian assembly hubs where solvent-free alternatives to thermal powder coatings face minimal incumbent saturation. Pursue licensing arrangements with hybrid UV-EB equipment manufacturers to bypass capital-intensive accelerator ownership. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified chemical conglomerates seeking radiation-cure resin platform capabilities. Long-term viability hinges on regulatory tailwinds from REACH monomer restrictions and EPA NESHAP thresholds sustaining substitution demand. Monitor ECHA per- and polyfluoroalkyl substance restriction proposals as inflection indicators forcing reformulation cycles across packaging and electronics end uses.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Supply | Arkema's integrated oligomer chain demonstrates margin resilience against REACH compliance cost pass-through. |
| Hybrid UV-EB Processing Line Deployment | Nagoya-based film laminators leverage sequential curing to serve food-contact applications with reduced thermal risk. |
| Cationic Epoxy Formulation Development | BASF SE anchors automotive clear coat positioning through acid-catalyzed systems navigating tighter VOC ceilings. |
| High-Voltage Accelerator Technician Training | Specialized maintenance expertise scarcity constrains line expansion timelines across tier-one supplier installations. |
| PLI Scheme Geographic Capacity Addition | First-mover EB coating installation near Chennai and Pune captures domestic automotive component manufacturing incentives. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with coating formulators, Tier 1 automotive procurement officers, electron beam equipment technicians, and radiation-cure resin R&D directors complemented bottom-up volume modeling. Secondary sources included EPA NESHAP enforcement databases, ECHA REACH substance registration records, SEC 10-K disclosures from diversified chemical conglomerates, and MIIT industrial standard filings. Top-down validation cross-checked against customs trade flows and regional automotive production databases.
Data-stream reconciliation across shipment volumes, formulation patent filings, and equipment installation permits informed projection architecture. Segmentation modeling spanned product type transparency, application substrate requirements, technology polymerization mechanism, and end-user purchasing sophistication across the analysis window. CAGRs derived from slope-log regression on normalized volume trajectories, with cross-reference to oligomer capacity expansion announcements and OEM qualification timeline compression patterns.
Inputs from regulatory agencies and trade associations were available through the study window; gaps in private equipment utilization rates and spot oligomer pricing introduce uncertainty bands around margin projections. Forecasts reflect assumptions regarding REACH substance restriction implementation pacing and PLI scheme incentive continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
PACVD-Based Coatings Market
Coatings
Acrylic Protective Coating Market
Coatings
Global Abrasion Resistant Coatings Market
Coatings
Global Optical Coating Market
Coatings
Noise and Vibration Coatings Market
Coatings
Silicone Coating Market
Coatings
United States Automotive OEM Coatings Market
Coatings
Asia-Pacific Marine Coatings Market
Coatings
Wire Enamels Market
Coatings
US Industrial Coatings Market
Coatings
Qatar Protective Coatings Market
Coatings
Cold Gas Spray Coating Market
Coatings
Global Smart Coating Market
Coatings
United Kingdom Protective Coatings Market
Coatings
Cladding Coatings Market
Coatings
Waterproof Coating Market