
 Global Polytetrafluoroethylene (PTFE) Coatings Market | 2026-2036
Global Polytetrafluoroethylene (PTFE) Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polytetrafluoroethylene (PTFE) Coatings Market Foresight
Buyer concentration across semiconductor manufacturers is decoupling from traditional petrochemical procurement patterns as chip fabrication capacity expands in East Asia. The Chemours Company leverages its vertical integration from fluorspar mining to formulated dispersions to sustain pricing power in high-purity electronic grades. Daikin Industries anchors its position through captive resin production in Japan and spray coating technology leadership for wafer processing equipment. Gujarat Fluorochemicals Limited competes on manufacturing scale from its Indian chlor-alkali-fluoropolymer complex, supplying mechanical equipment suppliers across South Asia and the Middle East.
Polytetrafluoroethylene coatings are fluoropolymer films derived from tetrafluoroethylene polymerization, typically applied at thicknesses of 25 to 50 microns through thermal sintering to achieve surface energies below 20 dynes per centimeter for extreme chemical inertness and low friction. Their primary industrial purpose is to protect substrates from corrosive process environments while eliminating adhesion in food handling, chemical reactor, and precision electronics applications. Lubricious coatings dominate medical device and semiconductor tooling segments where particulate shedding must stay below Class 1 cleanroom thresholds, while non-stick coatings command premium positioning in commercial bakeware and industrial food processing lines. Spray coating technology leads the technology dimension due to its adaptability for complex geometries in oilfield downhole equipment and electronic component housings.
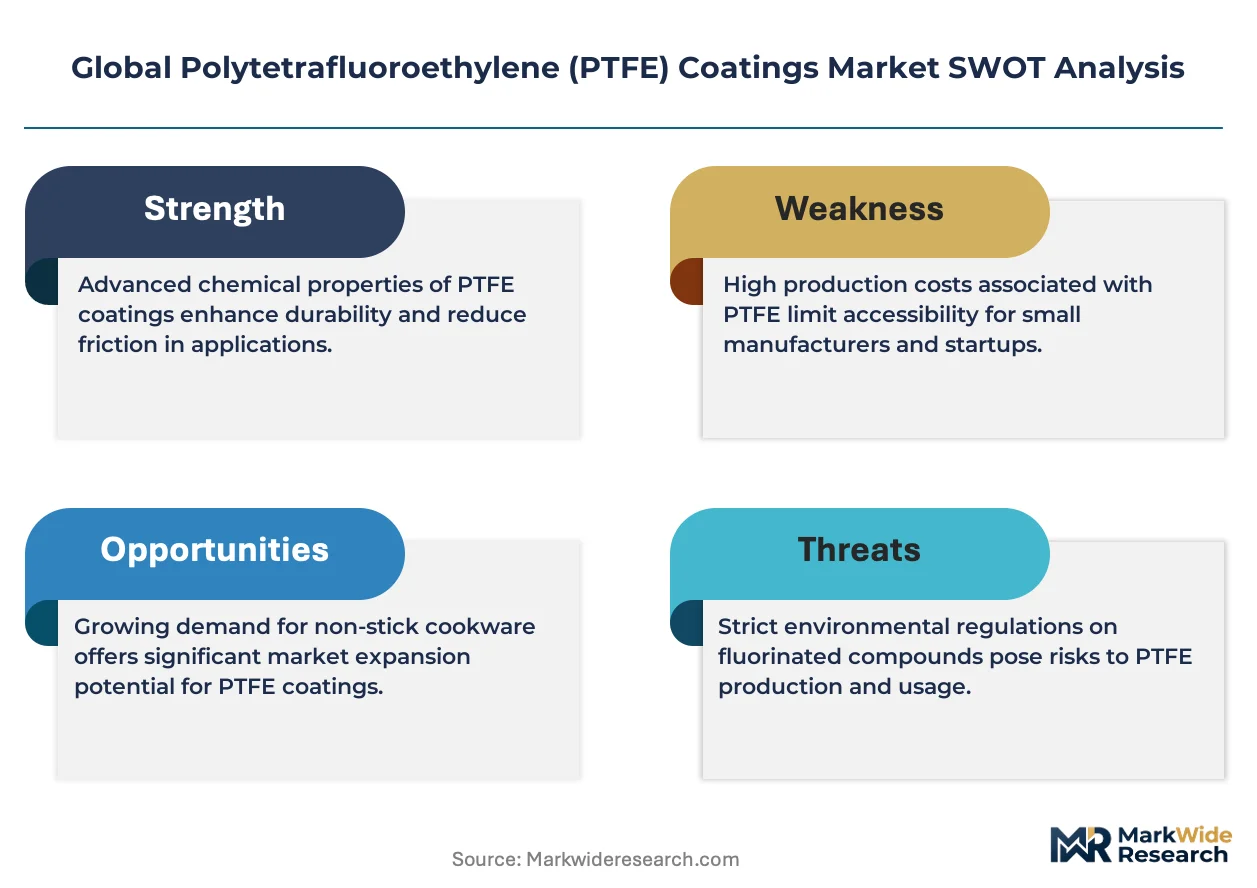
REACH in Europe and EPA fluorinated substance oversight in the United States are restricting long-chain perfluoroalkyl chemistries, compelling coating producers to reformulate with short-chain fluorosurfactants or hybrid ceramic-fluoropolymer systems to maintain market access. China's MEE enforces discharge standards on fluoropolymer manufacturing that favor integrated producers with aqueous waste treatment capabilities, reshaping competitive entry barriers. Stakeholders must monitor regulatory divergence between jurisdictions on acceptable fluoropolymer chemistries to avoid stranded formulation investments as compliance timelines tighten without harmonization.
Market Dynamics
REACH compliance timelines and China's MEE discharge mandates are forcing coating producers to abandon long-chain fluorosurfactants, redirecting capital toward aqueous dispersion systems and integrated waste treatment infrastructure.
Growth Catalysts
- Semiconductor fabrication expansion:East Asian chip foundries are specifying high-purity PTFE coatings for wafer processing equipment, creating specification pull-through for electronic-grade formulations.
- F-Gas Regulation phase-down:Europe's fluorinated gas restrictions are accelerating substitution toward PTFE-coated heat exchangers and sealing systems in industrial refrigeration.
- Food safety mandates:FDA and EFSA compliance requirements for commercial food contact surfaces are mandating non-stick coating upgrades across industrial bakery and meat processing lines.
Market Restraints
- Fluorspar supply concentration:Acid-grade fluorspar mining concentrates in China and Mexico, exposing coating resin producers to export quota volatility and geopolitical supply interruptions.
- Long-chain PFAS substitution complexity:Technical performance gaps in short-chain fluorosurfactants limit coating durability in chemical processing equipment, forcing hybrid formulations with uncertain field validation.
- EPA fluorinated substance oversight:United States regulatory scrutiny of perfluoroalkyl substances is extending compliance timelines and raising litigation exposure for legacy coating inventories.
Strategic Opportunities
- Indian chemical equipment manufacturing:Gujarat and Maharashtra industrial corridors are expanding fluoropolymer coating demand for corrosion-resistant reactor vessels and piping systems serving pharmaceutical exports.
- Hybrid ceramic-fluoropolymer convergence:Sol-gel ceramic integration with PTFE matrices is opening temperature-resistant applications in aerospace turbine components previously served by pure fluoropolymers.
- EU Green Deal industrial decarbonization incentives:Coating producers qualifying for sustainable process technology grants can offset aqueous system conversion costs while securing preferred supplier status with European OEMs.
Industry Challenges
- Cleanroom coating technician scarcity:Semiconductor and medical device manufacturers face shortages of applicators certified to Class 1 particulate control standards, constraining capacity expansion timelines.
- Cross-jurisdictional formulation registration:Divergent acceptable fluoropolymer chemistries between EPA, REACH, and China's MEE are fragmenting product portfolios and multiplying compliance documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polytetrafluoroethylene (PTFE) Coatings Market |
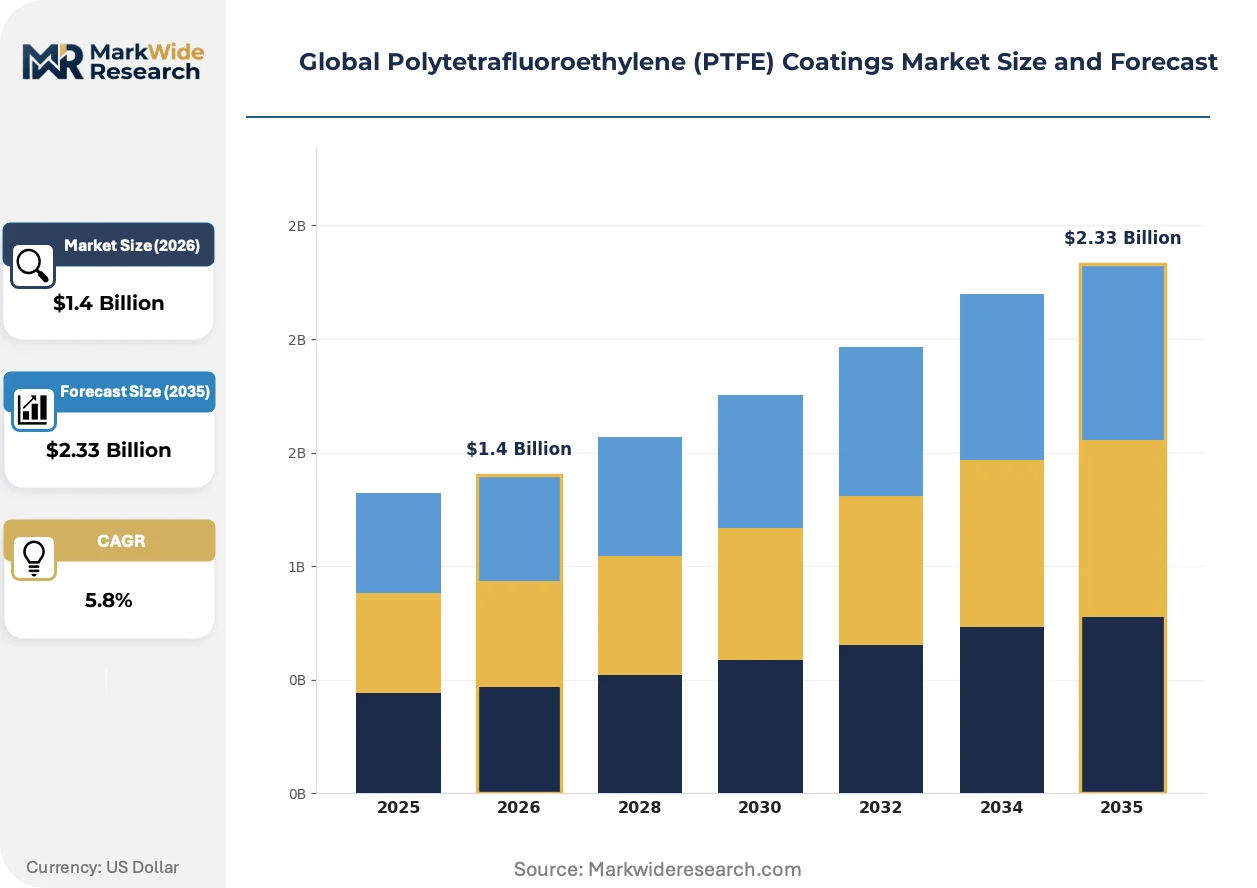
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lubricious Coatings, Anti-Corrosion Coatings, Wear-Resistant Coatings, Non-Stick Coatings Application: Oilfield Equipment, Electronic Components, Food Processing, Chemical Processing Technology: Spray Coating, Dip Coating, Electrostatic Coating, Powder Coating End User: Semiconductor Manufacturers, Food & Beverage Plants, Petrochemical Producers, Mechanical Equipment Suppliers |
| Companies Covered | The Chemours Company, Daikin Industries, 3M Company, Solvay, Gujarat Fluorochemicals Limited, AGC Inc., Dongyue Group, HaloPolymer, Shanghai 3F New Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polytetrafluoroethylene (PTFE) Coatings Market Shifts & Advancements
Formulation chemistry, application technology, and procurement specifications are converging around aqueous systems and performance-verified sustainability claims, compressing the viable technology set for new market entrants.
Sol-gel ceramic-fluoropolymer hybrid coatings are unifying thermal stability and low-friction properties in single-layer architectures. Aerospace turbine manufacturers in France and Germany are qualifying these systems for 300°C-plus operating environments. This unifying technology is collapsing the traditional segmentation between pure ceramic and pure fluoropolymer coating suppliers.
REACH restriction proposals on per- and polyfluoroalkyl substances are compelling coating producers to validate short-chain fluorosurfactant alternatives by 2025. Industrial chemical equipment OEMs in the Netherlands and Belgium are demanding third-party certified formulations to preempt liability exposure. European food processing machinery buyers are accelerating specification updates to exclude legacy long-chain chemistries.
Specification-driven procurement is consolidating vendor qualification lists around integrated resin-to-coating producers with verified aqueous waste treatment. Semiconductor equipment manufacturers in Japan and South Korea are reducing qualified supplier pools from twelve to four firms. This concentration is most visible in Hsinchu and Pyeongtaek industrial clusters where foundry construction timelines demand pre-qualified coating partners.
Global Polytetrafluoroethylene (PTFE) Coatings Market Segmentation
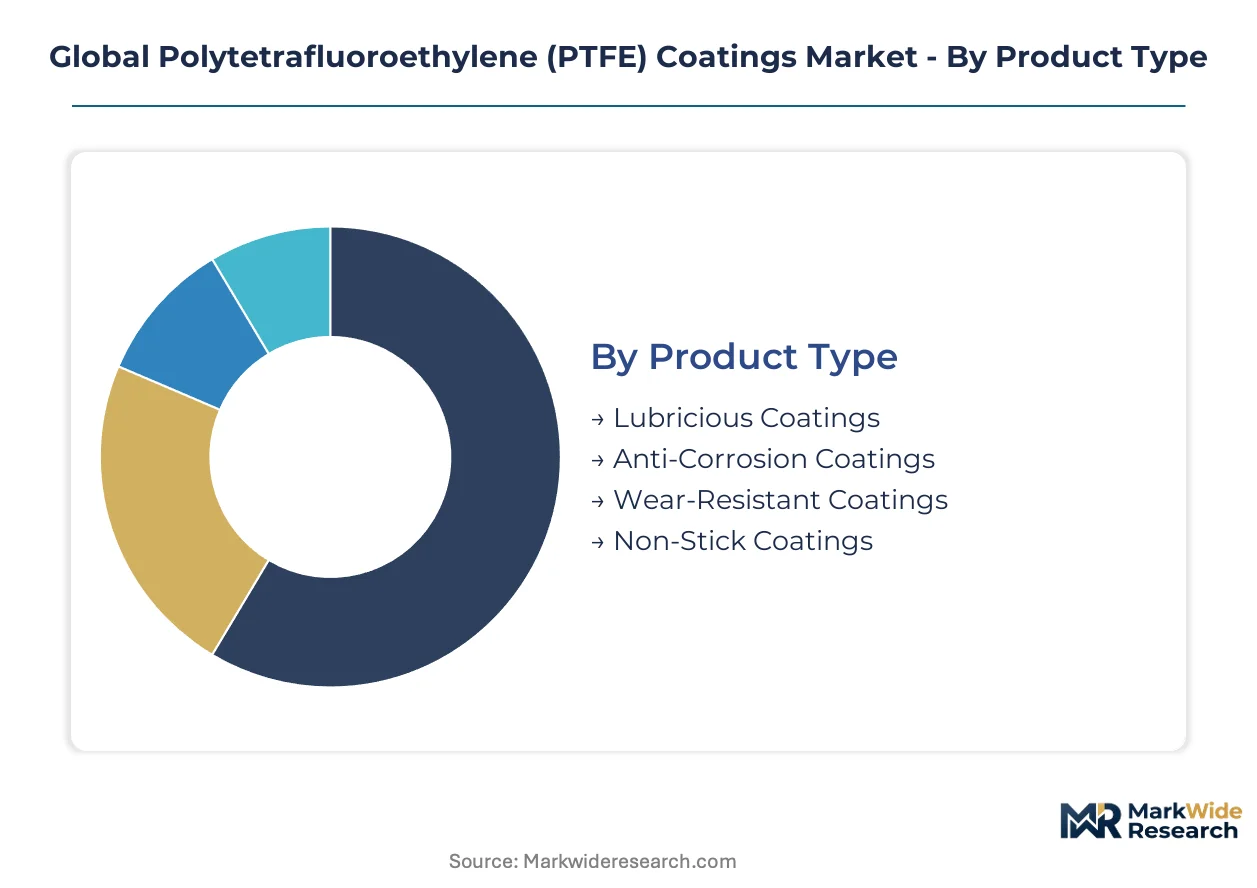
PTFE coating procurement specifications diverge sharply across end-use verticals, with semiconductor cleanroom standards imposing particulate thresholds that food processing and chemical equipment applications rarely match. Formulation chemistry and application technology selection cascade from these initial specification gates, locking in supplier qualification pathways early in equipment design cycles.
Product Type:
Capital intensity escalates with formulation complexity, as lubricious coatings demand sub-micron particle control infrastructure that non-stick variants avoid entirely.
- Lubricious Coatings:Ultra-low friction films engineered for Class 1 cleanroom compatibility with particulate shedding below 0.1 microns. Demand concentrates in Hsinchu and Pyeongtaek semiconductor clusters where wafer processing equipment manufacturers specify pre-qualified coating partners. REACH short-chain fluorosurfactant mandates are forcing reformulation investments that smaller compounders cannot absorb.
- Non-Stick Coatings:Food-contact formulations applied at 25-50 micron thickness for industrial bakeware and meat processing lines. FDA and EFSA compliance documentation requirements favor integrated resin producers with established regulatory filing histories over regional job shops.
- Anti-Corrosion Coatings:Chemical-resistant barrier systems for reactor vessels and piping in fluoropolymer production facilities.
- Wear-Resistant Coatings:Reinforced PTFE matrices with ceramic fillers for downhole drilling tools and pump components.
Most installed capacity flows through non-stick formulations. Expansion is steepest in lubricious coatings for semiconductor tooling.
Application:
Specification stringency varies by process criticality, with electronic component applications demanding lot-level traceability that oilfield equipment procurement rarely requires.
- Electronic Components:High-purity coatings for connector housings and semiconductor handling fixtures requiring ionic contamination below 10 ppm. Japanese and South Korean electronics OEMs are consolidating qualified supplier lists from twelve to four firms to accelerate foundry construction timelines. EPA fluorinated substance oversight is extending compliance documentation burdens for legacy formulations.
- Food Processing:Industrial conveyor belts, molding surfaces, and commercial bakeware requiring FDA 21 CFR 177.1550 compliance. European machinery buyers in the Netherlands and Belgium are accelerating specification updates to exclude long-chain PFAS chemistries ahead of REACH restriction enforcement.
- Chemical Processing:Reactor linings and heat exchanger coatings for corrosive process environments.
- Oilfield Equipment:Downhole tools and valve components for high-pressure hydrocarbon extraction.
Volume concentration sits with food processing equipment. Value expansion is fastest in electronic components for semiconductor fabrication.
Technology:
Application method selection determines coating uniformity and geometric reach, with spray systems commanding premium positioning for complex component architectures.
- Spray Coating:Atomized dispersion deposition adaptable to intricate geometries in electronic housings and oilfield downhole tools. Daikin Industries anchors technology leadership through captive resin production and precision spray systems for Japanese wafer processing equipment. Aqueous dispersion conversion investments are reshaping competitive entry barriers under China's MEE discharge mandates.
- Powder Coating:Electrostatic application of sintered PTFE particles for thick-film industrial applications.
- Dip Coating:Immersion-based deposition for uniform coverage of simple geometries in batch processing.
- Electrostatic Coating:Charged particle attraction for controlled thickness on conductive substrates.
Equipment base concentrates in spray coating systems. Technology transition is most rapid toward aqueous dispersion spray platforms.
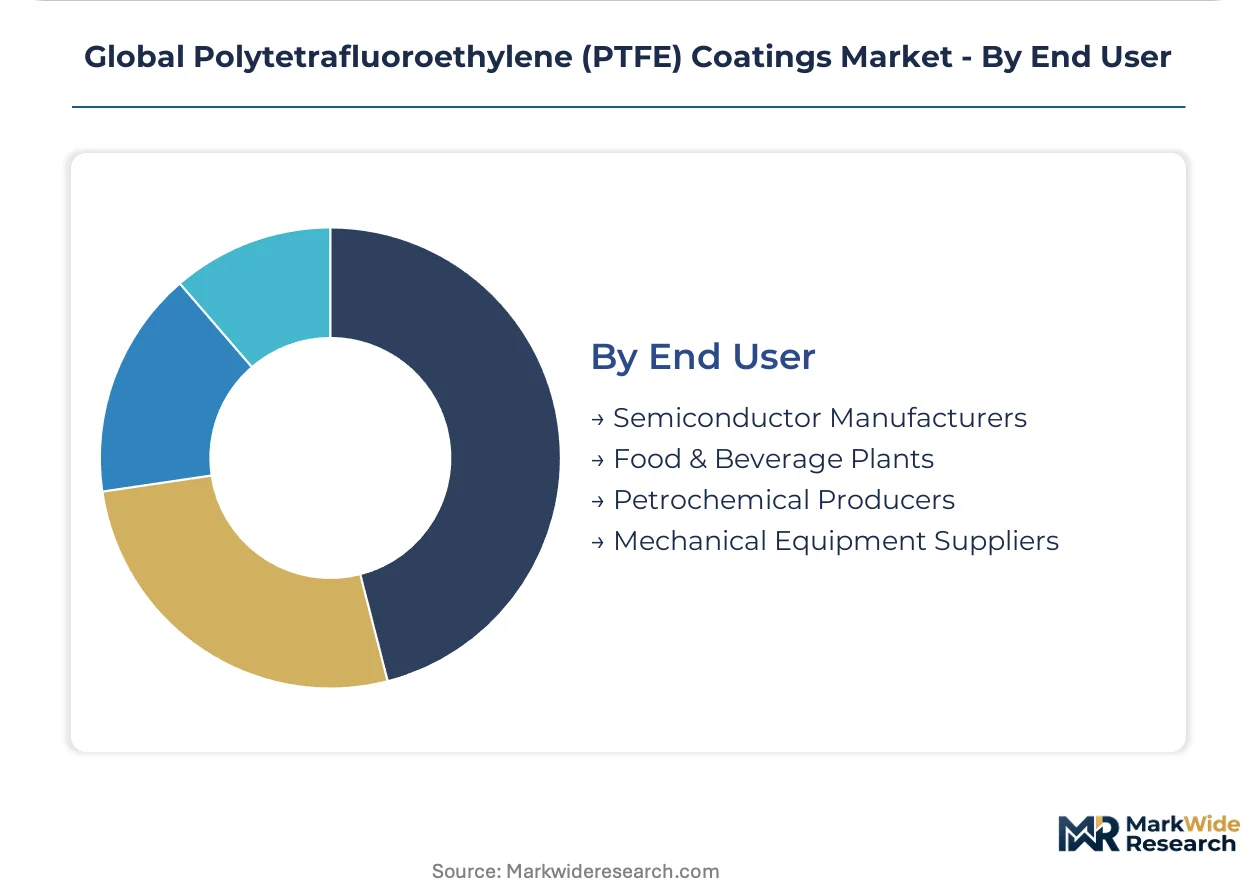
End User:
Procurement consolidation patterns separate specification-driven buyers with captive coating operations from merchant market purchasers.
- Semiconductor Manufacturers:Direct specification of high-purity coatings for wafer processing equipment with pre-qualified vendor requirements. East Asian foundry expansion in Taiwan and South Korea is decoupling procurement from traditional petrochemical patterns. Cleanroom coating technician scarcity is constraining capacity expansion timelines.
- Petrochemical Producers:Corrosion protection for reactors and distillation columns in integrated refining complexes.
- Food & Beverage Plants:Equipment upgrade cycles for industrial bakery and meat processing lines.
- Mechanical Equipment Suppliers:Component coating for pumps, valves, and compressors serving distributed industrial markets.
Procurement volume flows through mechanical equipment suppliers. Specification intensity is highest among semiconductor manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern industrial corridor commands integrated fluoropolymer resin output while Germany's chemical equipment sector drives specification-grade demand, revealing divergent regional specializations in the PTFE coatings value chain.
China
Semiconductor fabrication expansion in Hsinchu and Pyeongtaek industrial clusters is redirecting coating procurement toward electronic-grade formulations. The MEE enforces discharge standards favoring producers with aqueous waste treatment capabilities. Domestic resin output in the Yangtze River Delta feeds coating operations serving chemical equipment exports.
United States
EPA fluorinated substance oversight extends compliance timelines for legacy coating inventories while chip foundry construction accelerates specification pull-through. FDA 21 CFR 177.1550 mandates govern food-contact surface upgrades across industrial bakery lines. Gulf Coast petrochemical corridors concentrate demand for corrosion-resistant reactor linings.
Germany
F-Gas Regulation phase-down accelerates substitution toward PTFE-coated heat exchangers in industrial refrigeration systems. EU Green Deal decarbonization incentives offset aqueous system conversion costs for qualifying producers. Aerospace turbine manufacturers in Bavaria and Baden-Württemberg qualify hybrid ceramic-fluoropolymer systems for 300°C-plus environments.
Japan
Wafer processing equipment manufacturers specify pre-qualified coating partners with Class 1 cleanroom compatibility. METI industrial standards reinforce particulate shedding thresholds below 0.1 microns for semiconductor tooling. Kanto and Kansai industrial belts anchor captive resin production integrated with precision spray coating technology.
India
Gujarat and Maharashtra industrial corridors expand fluoropolymer coating demand for pharmaceutical export reactor vessels. BIS standards compliance documentation favors integrated producers with established regulatory filing histories. The PLI scheme for chemical manufacturing incentivizes domestic coating capacity expansion.
Global Polytetrafluoroethylene (PTFE) Coatings Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation complexity tiers, creating a bifurcated structure where scale advantages concentrate in commodity non-stick grades and technical differentiation dominates electronic-grade segments. The vendor base organizes around three strategic archetypes: integrated resin-to-coating producers with captive fluorspar supply, regional compounders serving mechanical equipment distributors, and application-technology specialists holding semiconductor qualification status. Dominant competitive moves include backward integration into fluorspar mining and resin polymerization, alongside strategic partnerships with foundry equipment OEMs to secure pre-qualified supplier status.
Within the integrated-producer tier, The Chemours Company exemplifies archetype dominance through its span from mineral extraction to formulated dispersions. Daikin Industries occupies a comparable position in East Asian markets, representing technology leadership in spray application systems for wafer processing equipment. Gujarat Fluorochemicals Limited anchors the manufacturing-scale archetype from its Indian chlor-alkali-fluoropolymer complex, supplying mechanical equipment fabricators across South Asia and Middle Eastern export corridors.
| Leading Market Players |
|---|
| The Chemours Company |
| Daikin Industries |
| 3M Company |
| Solvay |
| Gujarat Fluorochemicals Limited |
| AGC Inc. |
| Dongyue Group |
| HaloPolymer |
| Shanghai 3F New Materials |
| Others |
Supply & Pricing Matrix
Semiconductor equipment OEMs with pre-qualified vendor requirements command contract-based long-term offtake agreements that lock in electronic-grade formulation premiums. Their specification intensity creates pricing power asymmetry against merchant market purchasers of commodity non-stick grades.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard-grade non-stick formulations. Three-tier pricing structure across premium, standard, and economy levels separates Class 1 cleanroom-certified electronic grades from FDA-compliant food-contact variants and industrial mechanical equipment coatings. Price differentiation hinges on certification tier and captive resin integration. Cost compression in commodity non-stick segments is intensifying because domestic Chinese producers are scaling aqueous dispersion output. Mechanical equipment suppliers exhibit highest price sensitivity; semiconductor foundries demonstrate lowest sensitivity due to qualification switching costs.
Supply Chain Analysis
Refurbishment flows for used semiconductor processing equipment create secondary coating demand channels in Taiwan and South Korea. Acid-grade fluorspar mining concentrates in China and Mexico; tetrafluoroethylene polymerization capacity clusters in Japan and the United States. The supply chain draws from fluorspar export quota volatility as its dominant structural risk. Distribution runs through integrated resin-to-coating producers with direct foundry equipment OEM relationships rather than merchant chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PTFE coatings market functions as a stable compounder anchored by semiconductor fabrication capacity expansion in East Asia. Equipment qualification timelines create sticky demand that sustains incumbent positioning across technology cycles.
For Market Incumbents: Acquire aqueous dispersion formulation assets to preempt REACH short-chain fluorosurfactant mandates. Consolidate fluorspar mining access in Mexico to offset Chinese export quota exposure. Certification investment for Class 1 cleanroom compatibility defends against emerging regional compounders in India. For New Entrants and Emerging Players: Mechanical equipment distributors in Gujarat and Maharashtra industrial corridors represent the most penetrable channel partner type for corrosion-resistant reactor vessel coatings. Target pharmaceutical export equipment fabricators with BIS-compliant documentation packages. Sol-gel ceramic-fluoropolymer hybrid formulations offer differentiation entry angle for aerospace turbine qualification. For Investors and Strategic Acquirers: Chemical equipment OEMs are the most active acquirer in this space, seeking captive coating capabilities for pharmaceutical reactor exports. Five-to-ten year viability rests on aqueous waste treatment infrastructure ownership. Monitor EPA fluorinated substance enforcement intensity as inflection indicator for legacy formulation asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Mining | Chemours secures acid-grade supply against Chinese export quota volatility. |
| Aqueous Dispersion System Conversion | Daikin meets China's MEE discharge standards for Yangtze River Delta operations. |
| Hybrid Ceramic-Fluoropolymer Qualification | Solvay accesses 300°C-plus aerospace turbine applications in Bavaria. |
| Semiconductor Equipment OEM Partnership | Gujarat Fluorochemicals gains pre-qualified supplier status for Hsinchu foundry construction. |
| REACH Short-Chain Surfactant Reformulation | AGC preempts restriction enforcement for European food machinery specifications. |
Research Methodology
Bottom-up semiconductor fabrication capacity modeling reconciled against top-down fluoropolymer resin production tracking forms the analytical core. Primary interviews with wafer processing equipment procurement managers, coating applicators certified to Class 1 standards, chemical plant maintenance directors, and regulatory affairs specialists at ECHA and EPA combined with secondary validation from customs trade data, SEC 10-K filings, and ACC industry reports. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of electronic-grade formulation premiums versus commodity non-stick spreads established baseline price elasticity patterns. Segmentation modeling spanned lubricious versus non-stick versus anti-corrosion grades, spray versus powder versus dip coating technologies, and semiconductor versus food processing versus chemical equipment end-uses. CAGRs derived from capacity expansion announcements and foundry construction timelines across the analysis window. Forecast inputs incorporated REACH restriction proposal adoption probability and China's MEE enforcement trajectory.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to fluorspar export policy shifts and hybrid ceramic-fluoropolymer field validation results. Practitioners should monitor EPA fluorinated substance litigation exposure and EU Green Deal sustainable process technology grant allocation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
United States Industrial Wood Coatings Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Chemical Resistant Coatings Market
Coatings
Acrylic Coating Market
Coatings
Polyurethane Powder Coatings Market
Coatings
Anti-Graffiti Coatings Market
Coatings
Vacuum Coating Machine Market
Coatings
Global Anti-Smudge Coatings Market
Coatings
Corrosion Protection Polymer Coating Market
Coatings
Tablet Coatings Market
Coatings
In-Mold Coatings Market
Coatings
PU Coatings Market
Coatings
South Korea Protective Coatings Market
Coatings
US Concrete Floor Coatings Market
Coatings
Bio-Fouling Prevention Coatings Market
Coatings
Zero Friction Coatings Market