
 Coating Equipment Market | 2026-2036
Coating Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Coating Equipment Market Intelligence
Equipment-as-a-service (EaaS) and leasing models are rewriting the competitive landscape for smaller contract manufacturers. Nordson Corporation specializes in precision dispensing technology for electronics and medical applications. Meanwhile, Dürr AG dominates large-scale automated coating systems for the global automotive industry. Graco Inc. leverages a broad distribution network for fluid handling and spray equipment across multiple industrial sectors.
Coating equipment encompasses machinery designed to apply a liquid, powder, or gaseous layer onto a substrate. These systems control critical parameters such as film thickness, typically measured in microns, and surface uniformity to achieve specific protective or functional properties. Powder coating technology leads in industrial applications due to its durability and low VOC emissions, while UV curing systems are gaining share in electronics manufacturing. Spray coaters remain the most versatile product type, serving a wide array of end-use applications.
Regulations from the US Environmental Protection Agency (EPA) on volatile organic compounds (VOCs) drive investment in compliant technologies. Similarly, the EU's REACH and RoHS directives, alongside China's GB standards for industrial emissions, govern material use and equipment safety standards. Vendor selection will increasingly hinge on the ability to provide integrated systems that optimize both material usage and energy consumption.
Market Dynamics
The market's central dynamic is the mandatory shift toward environmentally compliant coating technologies. This transition is driven by stringent volatile organic compound (VOC) emission standards from global regulators, compelling investment in powder coating and UV curing systems over traditional solvent-based methods.
Growth Catalysts
- Advanced Aerospace Materials:The fabrication of composite structures in the aerospace and defense sector requires precision coating systems for applying thermal barrier and anti-corrosion layers, driving demand for automated spray and robotic equipment.
- Chinese Emission Standards:China's dual carbon goals and stricter GB standards for industrial emissions are accelerating the replacement of outdated, high-VOC solvent-based systems with compliant powder coating and waterborne technologies.
- Electronics Miniaturization:The need for conformal coatings on printed circuit boards and microelectronics to protect against moisture and corrosion fuels demand for selective and precision dispensing equipment.
Market Restraints
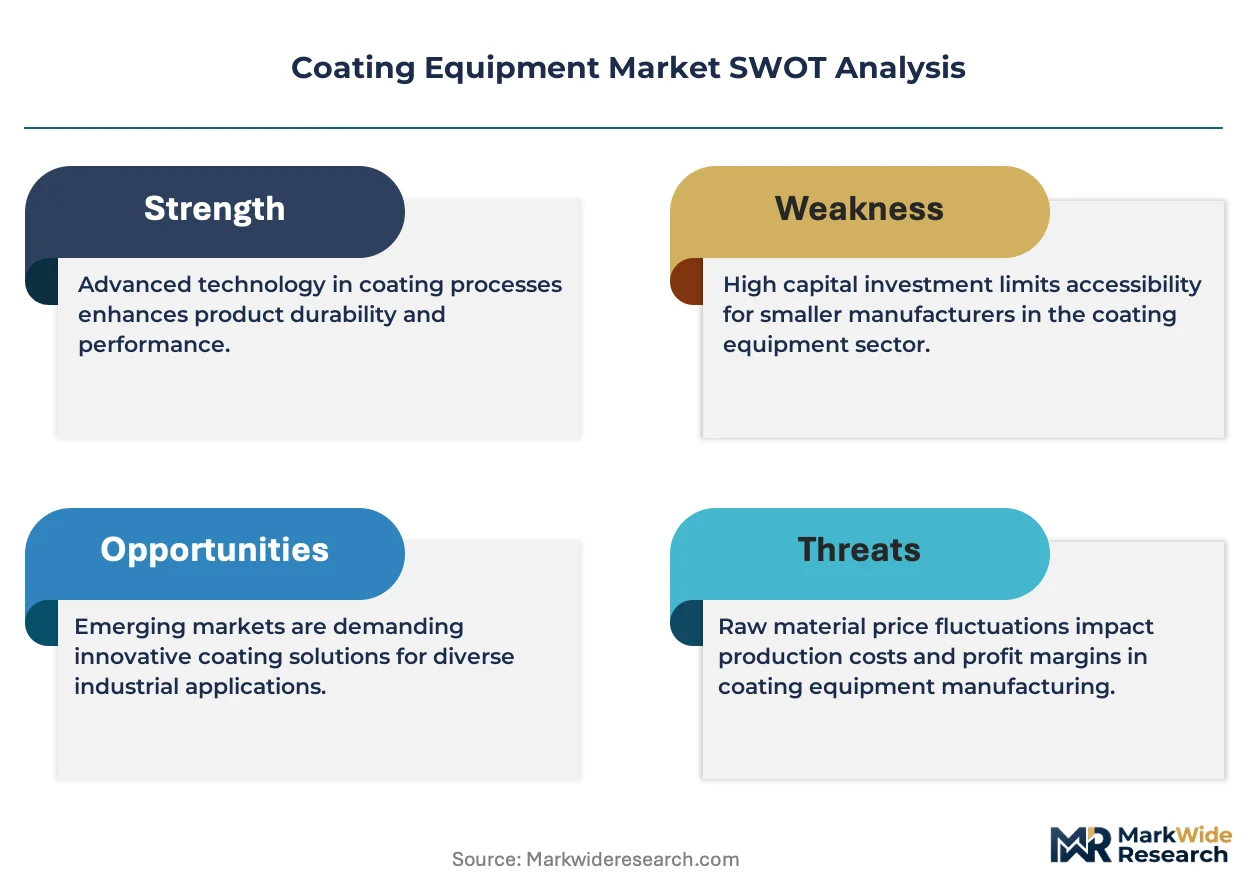
- High Capital Expenditure:The significant upfront investment required for automated coating lines, including robotics, curing ovens, and environmental controls, presents a substantial barrier for small and medium-sized enterprises.
- Substrate Sensitivity:Certain advanced coating technologies, such as powder coating, are limited by the substrate's ability to withstand high curing temperatures, restricting their use on heat-sensitive materials like wood or plastics.
- Raw Material Volatility:Price fluctuations in key inputs for coating powders, such as titanium dioxide and epoxy resins, create cost uncertainty for equipment users and can delay large-scale technology adoption.
Strategic Opportunities
- EV Battery Manufacturing:The production of electric vehicle batteries creates new applications for specialized coating equipment to apply functional layers on electrodes and separator films, representing a significant white-space opportunity.
- Integration with Additive Manufacturing:Combining coating systems with 3D printing processes offers the ability to apply functional or protective surfaces directly onto newly fabricated parts, creating value-added, integrated manufacturing cells.
- Equipment-as-a-Service Models:Offering coating equipment through subscription or leasing models can lower the adoption barrier for smaller manufacturers, opening new customer segments previously constrained by high capital costs.
Industry Challenges
- Skilled Operator Scarcity:A shortage of technicians trained to operate, program, and maintain complex automated coating systems and robotic applicators hinders optimal equipment utilization and efficiency.
- System Integration with Legacy Plants:Integrating modern, data-driven coating equipment with existing factory infrastructure and MES systems presents significant technical and software compatibility challenges for many industrial end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coating Equipment Market |
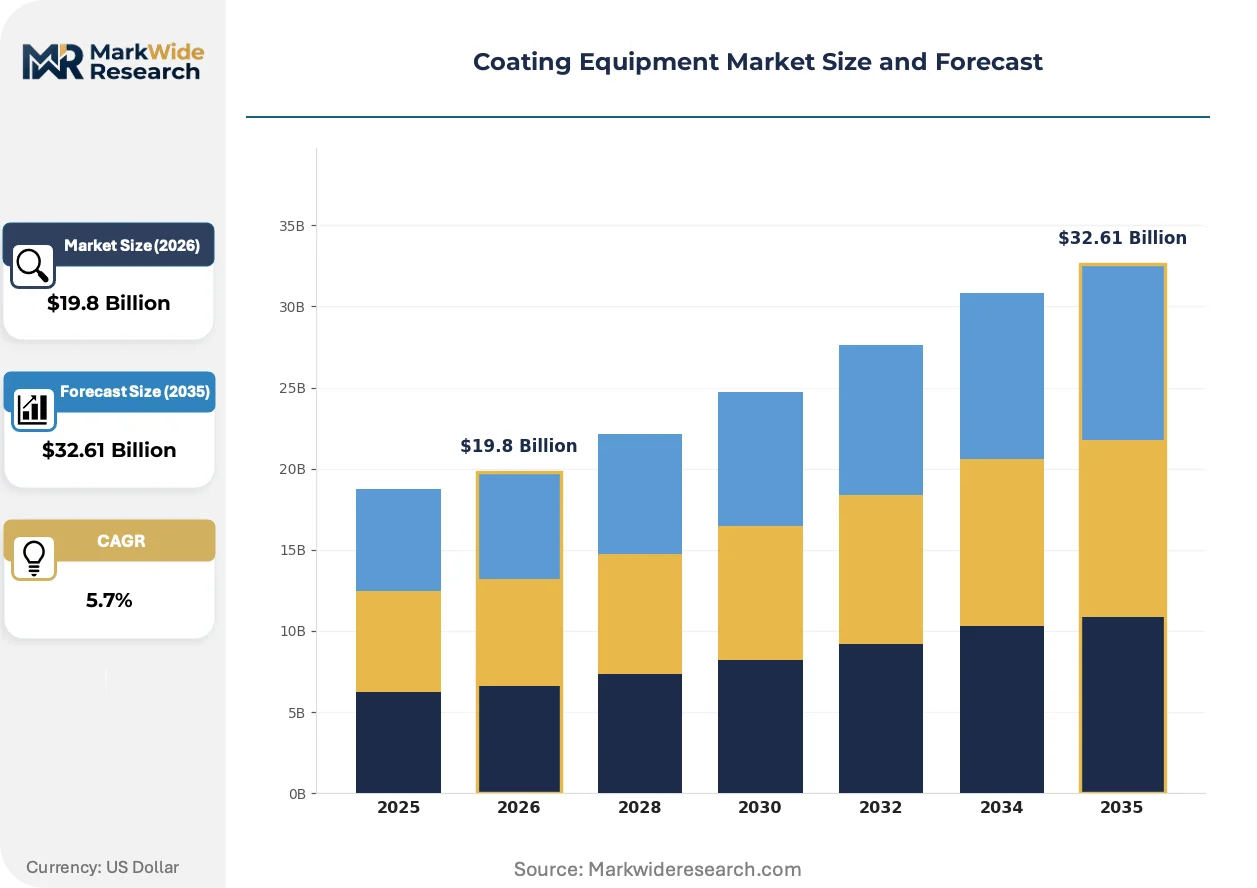
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $32.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray Coaters, Dip Coaters, Flow Coaters, Curtain Coatters, Roll Coatters Technology: Electrostatic, Vacuum, Thermal, UV Curing, Powder Coating Application: Electronics Manufacturing, Aerospace Fabrication, Construction Materials, Packaging Production, Textile Finishing End User: OEMs, Contract Manufacturers, Surface Treatment Operators, Equipment Suppliers, Fabricators |
| Companies Covered | OC Oerlikon Management AG, SATA GmbH & Co. KG, Nordson Corporation, Wagner Group, ASAHI Sunac Corporation, Graco Inc., ANEST IWATA Corporation, Dürr AG, IHI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coating Equipment Market Strategic Shifts & Innovations
The evolution of coating equipment is defined by a push for greater process control and resource efficiency. Innovations are focused on minimizing material waste, reducing energy consumption during curing, and integrating digital monitoring for real-time quality assurance and process documentation.
Digital front-end control systems integrate fluid dynamics simulation with real-time sensor feedback to optimize spray patterns and film thickness. Automotive and aerospace manufacturers are rapidly adopting these systems to ensure micron-level precision and reduce costly rework. As a result, the basis of competition is migrating from purely mechanical hardware performance to the sophistication of the software and control algorithms that govern the coating process.
The European Union's REACH regulation continues to restrict the use of certain chemical substances, including specific solvents and heavy metals commonly found in traditional coatings. This regulatory pressure forces coating material reformulation and requires equipment modifications or replacement to handle new waterborne, powder, or UV-curable formulations. Industrial finishing and automotive refinishing sectors are most affected, accelerating investment in compliant application technologies.
A shift towards flexible, usage-based consumption models is gaining traction over outright capital purchase of large-scale coating systems. This disrupts the traditional sales model, with third-party financiers and original equipment manufacturers offering Equipment-as-a-Service (EaaS) contracts that bundle hardware, consumables, and maintenance. This trend is most visible in the contract manufacturing sector for electronics and general industrial finishing, where production volumes can be highly variable.
Coating Equipment Market Segmentation
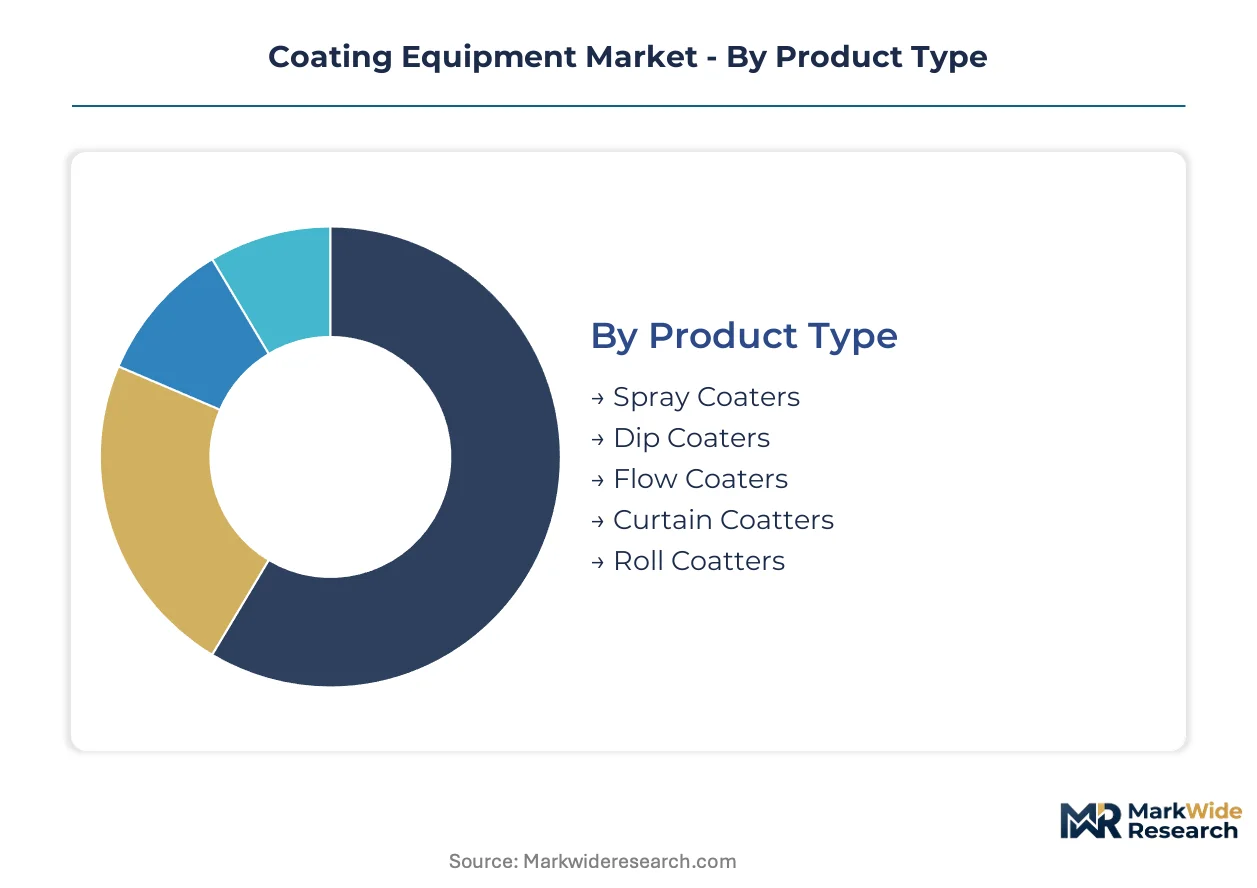
The Coating Equipment Market's intricate structure reflects the diverse industrial needs and technological advancements driving its evolution. Understanding these distinct segments provides clarity on demand drivers, technological preferences, and strategic opportunities for market participants.
Product Type:
The operational versatility of coating equipment is defined by its core product type, each designed for specific application methods and substrate characteristics.
- Spray Coaters:These highly versatile systems apply liquid or powder coatings through atomization, often utilizing compressed air or electrostatic charges for even distribution. Demand concentrates in automotive and aerospace manufacturing for uniform, high-precision finishes on complex geometries.
- Dip Coaters:Submerge parts into a liquid coating bath, suitable for complex geometries and internal surfaces, frequently used in anticorrosion treatments for industrial components.
- Flow Coaters:Apply coating material via a continuous stream or cascade over the substrate, ideal for components with irregular shapes in general industrial finishing sectors.
- Curtain Coatters:Form a continuous curtain of liquid coating for flat panels, ensuring high transfer efficiency and uniform coverage in furniture and wood panel manufacturing.
- Roll Coatters:Equipment using rollers to apply liquid coatings directly onto flat substrates, ensuring consistent film thickness and high throughput. Packaging production and graphic arts sectors drive demand for high-speed, continuous-process applications.
Spray Coaters command the established base. The steepest expansion runs through Roll Coaters.
Technology:
Technological advancements are driving efficiency and environmental compliance in coating processes, influencing equipment design and material compatibility.
- Electrostatic:This technology applies charged particles or droplets to an oppositely charged substrate, maximizing transfer efficiency and reducing material waste in various industrial applications.
- Vacuum:Conducts coating processes within a vacuum chamber, enabling ultra-thin and highly pure film deposition for optics, medical devices, and semiconductor fabrication.
- Thermal:Involves heat application to cure or fuse coatings, commonly used for powder coatings and certain liquid formulations in heavy industry and general manufacturing.
- UV Curing:Systems utilize ultraviolet light to rapidly polymerize liquid coatings, offering instant drying, minimal heat exposure to substrates, and high throughput. Electronics manufacturing and medical device production increasingly adopt UV curing for precision and speed.
- Powder Coating:This technology applies dry powder electrostatically, then cures it with heat to form a hard, durable finish with zero VOC emissions. Demand concentrates in architectural and automotive components due to its durability and environmental benefits.
Environmental mandates position Powder Coating as a dominant solution, while UV Curing technology is gaining significant momentum.
Application:
The diverse functional requirements across industries shape the specialized application of coating equipment, from protection to aesthetics.
- Electronics Manufacturing:Requires precision coating for printed circuit boards and microelectronics to protect against moisture, dust, and corrosion. Conformal coating systems are critical for reliability in consumer electronics and automotive control units.
- Aerospace Fabrication:Utilizes advanced coating equipment to apply thermal barrier, anti-corrosion, and erosion-resistant layers on critical aircraft components. Robotic spray systems ensure uniform coverage on complex geometries for engine parts and airframes.
- Construction Materials:Employs coating equipment for protective and aesthetic finishes on architectural panels, roofing, and structural elements, enhancing durability and appearance.
- Packaging Production:Applies functional coatings to films, foils, and containers for barrier properties, adhesion, and visual appeal in food and pharmaceutical packaging.
- Textile Finishing:Uses coating processes to impart water repellency, flame resistance, or enhanced durability to fabrics for apparel, automotive interiors, and technical textiles.
High-value sectors like Electronics Manufacturing drive specialized equipment demand, with Aerospace Fabrication also showing robust expansion.
End User:
The operational models of various end-user segments dictate their specific requirements for coating equipment solutions, influencing procurement and integration strategies.
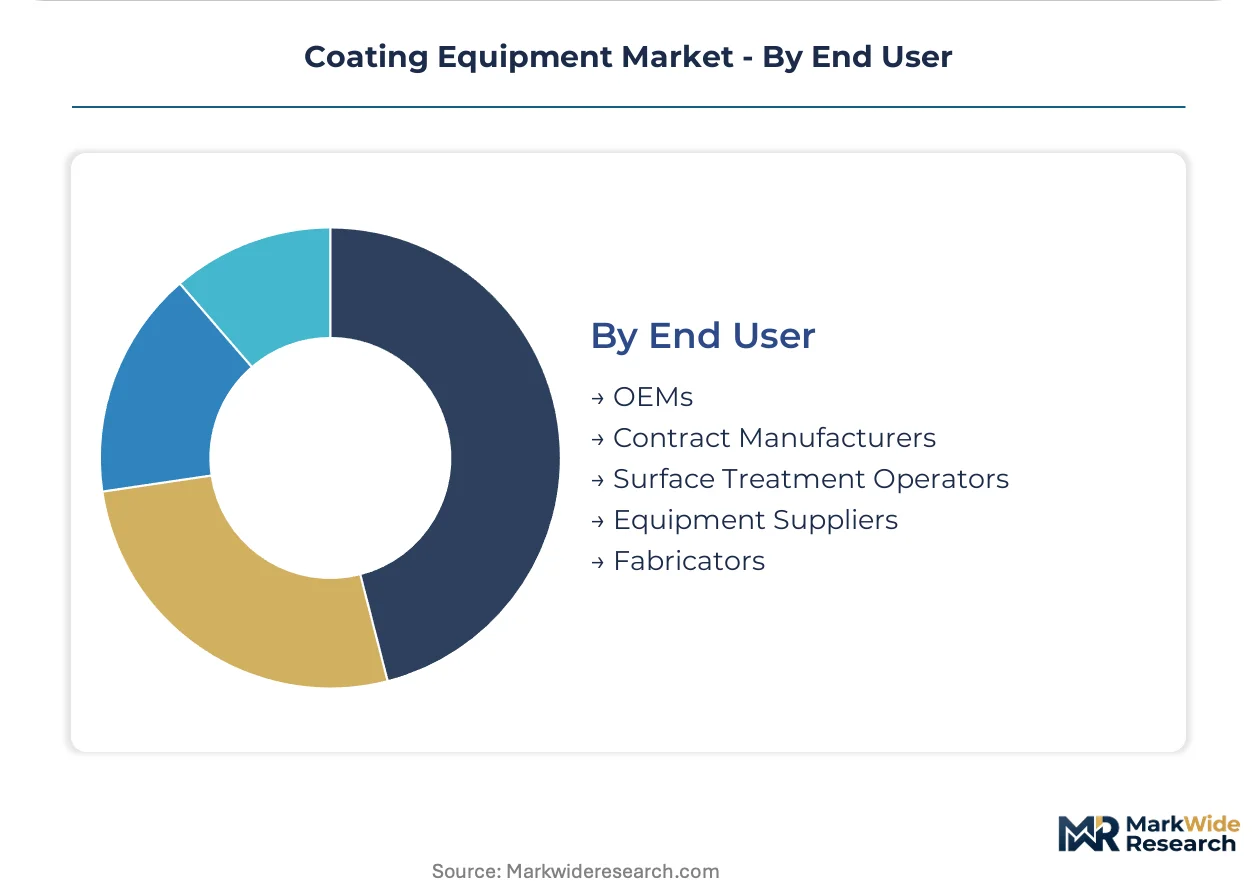
- OEMs (Original Equipment Manufacturers):Integrate coating equipment directly into their production lines for in-house finishing of their manufactured goods, such as automotive bodies or appliance components. These users prioritize high throughput and seamless automation.
- Contract Manufacturers:Provide specialized coating services to multiple clients, requiring flexible and versatile equipment capable of handling diverse materials and specifications. Their focus is on cost-effectiveness and rapid changeover capabilities.
- Surface Treatment Operators:Offer specialized coating and finishing services, often for challenging materials or complex geometries, serving a broad industrial client base.
- Equipment Suppliers:Provide coating machinery and related components, often offering integrated solutions and technical support to various industrial customers.
- Fabricators:Apply coatings to metal or plastic parts that they have manufactured or modified, typically for protective or aesthetic purposes in construction and general industry.
OEMs represent a foundational customer base for high-volume systems, while Contract Manufacturers are increasingly driving demand for flexible, adaptable solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stringent environmental regulations are compelling global investment in advanced coating equipment. These mandates, particularly concerning VOC emissions, accelerate the adoption of compliant technologies worldwide. This shift impacts manufacturing processes across diverse industrial sectors.
United States
Demand for precision coating systems stems from advanced aerospace fabrication and electronics miniaturization. The US Environmental Protection Agency (EPA) regulations on volatile organic compounds drive investment in compliant technologies. Manufacturers in California's tech hubs and the aerospace clusters of Washington State are adopting selective dispensing equipment.
Germany
European Union's REACH regulation influences material use and equipment safety standards for industrial finishing. High-volume automated coating systems are critical for the automotive and general manufacturing industries. The industrial heartland of Bavaria sees significant adoption of powder coating and UV curing systems.
China
China's dual carbon goals and stricter GB standards are accelerating the replacement of outdated solvent-based systems. This drives demand for waterborne and powder coating technologies in its vast manufacturing base. The Yangtze River Delta region is a hub for adopting environmentally compliant coating solutions for automotive and electronics.
Japan
Precision requirements for electronics miniaturization and advanced automotive components stimulate demand for specialized coating equipment. Policies from the Ministry of Economy, Trade and Industry (METI) support industrial efficiency and technological upgrades. Manufacturers in the Kanto region, including Tokyo, increasingly integrate selective and automated coating processes.
India
Industrial expansion in automotive and infrastructure sectors fuels the need for durable and protective coatings. The Bureau of Indian Standards (BIS) promotes quality and safety in industrial equipment and processes. Manufacturing centers in Maharashtra and Tamil Nadu are investing in modern coating lines for various industrial applications.
Coating Equipment Market Key Industry Players
On the supply side, the industry is characterized by a mix of established players offering comprehensive solutions and specialized providers focusing on niche applications. Large, diversified industrial conglomerates often compete with dedicated coating equipment manufacturers. Strategic archetypes include high-volume automated system providers and precision dispensing technology specialists. Competitive moves frequently involve geographic expansion and portfolio diversification to meet evolving regulatory and technological demands.
Specialists in precision dispensing technology, such as Nordson Corporation, exemplify the focus on high-value applications in electronics and medical sectors, where micron-level accuracy is paramount. Dürr AG, a German industrial conglomerate, anchors the segment for large-scale automated coating systems, particularly for the global automotive industry, emphasizing efficiency and integration. Graco Inc. represents a broad distribution model, supplying fluid handling and spray equipment across multiple industrial sectors, indicating a diverse market presence that caters to varied industrial needs and scales. These companies illustrate the market's segmentation by application precision, system scale, and distribution reach.
| Leading Market Players |
|---|
| OC Oerlikon Management AG |
| SATA GmbH & Co. KG |
| Nordson Corporation |
| Wagner Group |
| ASAHI Sunac Corporation |
| Graco Inc. |
| ANEST IWATA Corporation |
| Dürr AG |
| IHI Corporation |
Cost & Logistics Intelligence
The Yangtze River Delta's high-volume manufacturing capacity for coating equipment significantly influences downstream pricing power across Asia. This concentration provides cost efficiencies that impact global equipment procurement.
Pricing Analysis
Compliance with EU REACH and US EPA standards creates the primary spread in coating equipment pricing. Project-based pricing dominates for large-scale automated systems, while hybrid models incorporating Equipment-as-a-Service are emerging. Price differentiation also stems from integration with advanced automation and comprehensive after-sales service bundles. Pricing softness reflects intense competition and the accessibility offered by EaaS models, with contract manufacturers exhibiting higher price sensitivity compared to large automotive OEMs.
Supply Chain Analysis
Upstream feedstock for coating equipment, particularly precision dispensing components and control system electronics, draws from concentrated manufacturing hubs. Germany, Japan, and the United States anchor the supply of advanced coating systems. The supply chain faces structural risk from commodity price volatility in key inputs like titanium dioxide, impacting equipment users. Distribution runs through direct sales channels for complex automated lines and broad networks of industrial distributors for versatile spray equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coating equipment market presents a significant service-attach opportunity, with recurring revenue from maintenance contracts and software subscriptions expanding faster than hardware sales. This trend reflects the growing complexity and digital integration of modern coating systems.
For Market Incumbents: Insulate core market share by deepening software integration for predictive maintenance and real-time process optimization. Expand Equipment-as-a-Service models to counter high capital expenditure barriers for smaller manufacturers, a key entry point for emerging players. Invest in R&D for AI-driven control algorithms to maintain a technological lead against specialized software providers. This strategy protects against margin pressure from commoditization and new entrants focusing on compliant technologies.
For New Entrants and Emerging Players: Build out specialized coating solutions for electric vehicle battery manufacturing, targeting functional layers on electrodes and separator films. Focus on integrating coating systems with additive manufacturing processes to apply functional surfaces directly onto 3D-printed parts. The contract manufacturing sector, particularly for UV curing applications, presents the most penetrable segment. A go-to-market angle centered on outcome-based Equipment-as-a-Service models can lower adoption barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a growth-through-compliance play because stringent environmental regulations and advanced manufacturing trends will drive sustained demand for new equipment over the next decade. Target acquisition profiles include niche specialists in AI-driven process control software and precision dispensing technologies for EV battery production or electronics. A key signal to watch for inflection is the accelerating adoption rate of Equipment-as-a-Service models by small and medium-sized enterprises.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand EaaS Offerings | Lowers capital expenditure for contract manufacturers, expanding customer base. |
| Invest in AI-driven Controls | Optimizes spray patterns and film thickness, reducing material waste. |
| Develop EV Battery Coating Solutions | Captures new demand from electric vehicle manufacturing growth. |
| Acquire Software Specialists | Enhances integrated system capabilities and data analytics. |
| Strengthen Global Service Networks | Ensures rapid maintenance support for complex automated systems. |
Research Approach
Initial hypotheses were tested against primary input from plant managers, R&D directors, and procurement leads at OEMs, then refined through iterative analysis. This involved combining insights from targeted interviews with secondary validation from US EPA regulations, EU REACH directives, company financial filings, and industrial association reports. A robust bottom-up and top-down triangulation approach ensured comprehensive market sizing and segmentation.
Demand-supply balance modeling formed the core analytical framework across the analysis window. Segmentation dimensions modeled included product type, technology, application, end user, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical trends and projected market dynamics, incorporating key inputs such as evolving VOC emission standards and advanced material adoption rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by global industrial conglomerates or specialized technology providers would shift outcomes. This analysis reflects current assumptions regarding geopolitical stability and raw material price trends. Quarterly review of regulatory changes and key technology adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Protective and Marine Coatings Market
Coatings
Epoxy Surface Coatings Market
Coatings
United Arab Emirates Floor Coatings Market
Coatings
Solar Reflective Film Market
Coatings
Global Powder Coating Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Anti-Microbial Nano Coatings Market
Coatings
Compound Coating Market
Coatings
Stain Resistant Coatings Market
Coatings
Global Fire-Resistant Coating Market
Coatings
US Industrial Coatings Market
Coatings
Paper Coating Binders Market
Coatings
Global Automotive Specialty Coatings Market
Coatings
Global Polytetrafluoroethylene (PTFE) Coatings Market
Coatings
Middle East and Africa Super Hydrophobic Coatings Market
Coatings
E-Coat Market