
 Global Metal Coatings Market | 2026-2036
Global Metal Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal Coatings Market Foresight
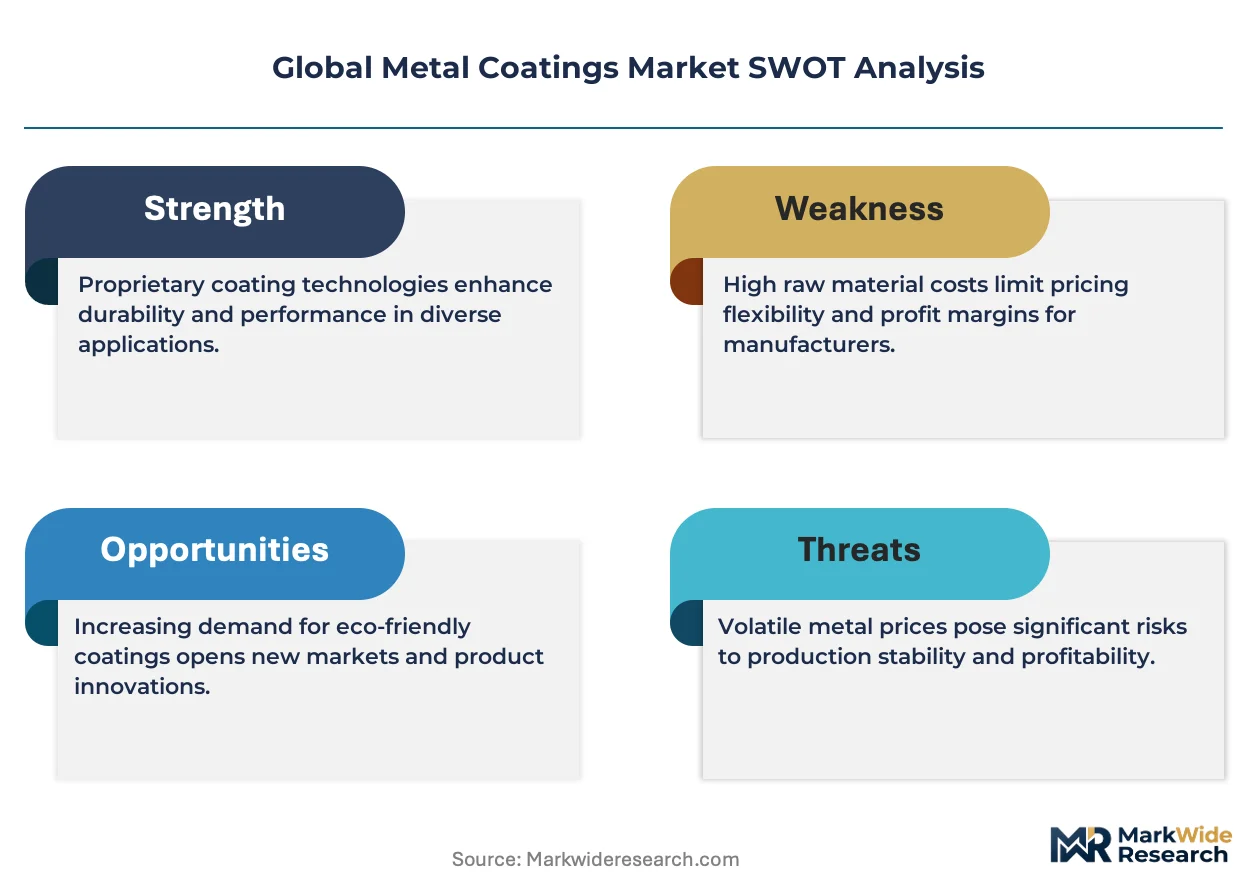
Chinese galvanizing capacity is expanding across the Yangtze River Delta, feeding regional steel mills with zinc-aluminum alloy outputs. PPG Industries leverages its North American coil coating infrastructure to sustain long-term supply agreements with appliance manufacturers. AkzoNobel anchors European marine coating demand through specialized anti-corrosive formulations for Baltic and North Sea fleets.
Metal coatings encompass protective and decorative layers applied to ferrous and non-ferrous substrates, typically ranging from 25 microns to 300 microns in dry film thickness, engineered to resist oxidation, chemical attack, and mechanical wear in industrial environments. Powder coatings now dominate volume in appliance and architectural segments due to near-zero VOC emission profiles and overspray recyclability. Thermal spraying occupies premium aerospace and power generation niches where tungsten carbide-cobalt composites deliver extreme temperature resistance.
EPA regulations in the United States enforce National Emission Standards for Hazardous Air Pollutants on coating operations, while REACH and RoHS in Europe restrict hexavalent chromium and cadmium content in anticorrosive pretreatments. China's MEE enforces GB standards limiting solvent-borne coating use in heavy manufacturing zones. Stakeholders must monitor evolving carbon border adjustments and substrate-specific compliance deadlines to align capital allocation with regulatory trajectories.
Market Dynamics
Automotive OEMs in Germany and Japan are accelerating procurement of corrosion-resistant substrates as EV platforms demand lighter, more durable metal architectures. This shift is compressing traditional coating cycles and forcing reformulation investments across the supply base.
Growth Catalysts
- REACH compliance deadlines:European manufacturers are retrofitting pretreatment lines to eliminate hexavalent chromium ahead of ECHA phase-out dates, generating replacement demand for compliant zinc-flake and trivalent chrome systems.
- India's industrial corridor expansion:Contract manufacturers in Gujarat and Tamil Nadu are scaling captive galvanizing capacity to serve export-bound automotive and appliance fabricators.
- Thermal spray robotics:Automated high-velocity oxy-fuel systems are cutting aerospace MRO turnaround times by enabling precise tungsten carbide-cobalt reclamation of turbine components.
Market Restraints
- Zinc price volatility:Galvanizing operations face margin compression when London Metal Exchange zinc futures swing, forcing hedging costs onto smaller coaters lacking treasury scale.
- China's Yangtze Delta concentration:Over half of Asia's hot-dip capacity clusters within 200 kilometers of Shanghai, creating single-point vulnerability to riverine logistics disruptions or regional power rationing.
- Solvent-borne substitution limits:High-performance fluoropolymer topcoats for chemical processing equipment still lack viable water-borne alternatives, trapping some segments in VOC-intensive formulations.
Strategic Opportunities
- Vietnam's fabrication boom:Japanese and Korean appliance brands are relocating metal stamping and coating to northern industrial zones near Haiphong, creating greenfield demand for coil coating infrastructure.
- EU Green Deal carbon border adjustments:Importers of coated steel into Europe face embedded emissions reporting from 2026, advantaging coaters with renewable-powered facilities and verified low-carbon zinc sourcing.
- Digital coating thickness monitoring:Eddy-current and ultrasonic sensors integrated with MES platforms are enabling real-time quality control that reduces rework rates in high-volume automotive lines.
Industry Challenges
- Surface preparation automation:Shot blasting and chemical pretreatment lines require skilled technicians to calibrate media flow and pH chemistry, but vocational pipelines in industrial regions are thinning.
- Multi-substrate certification lag:Coatings qualified for cold-rolled steel require separate validation cycles for aluminum-intensive EV body-in-white architectures, extending OEM approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal Coatings Market |
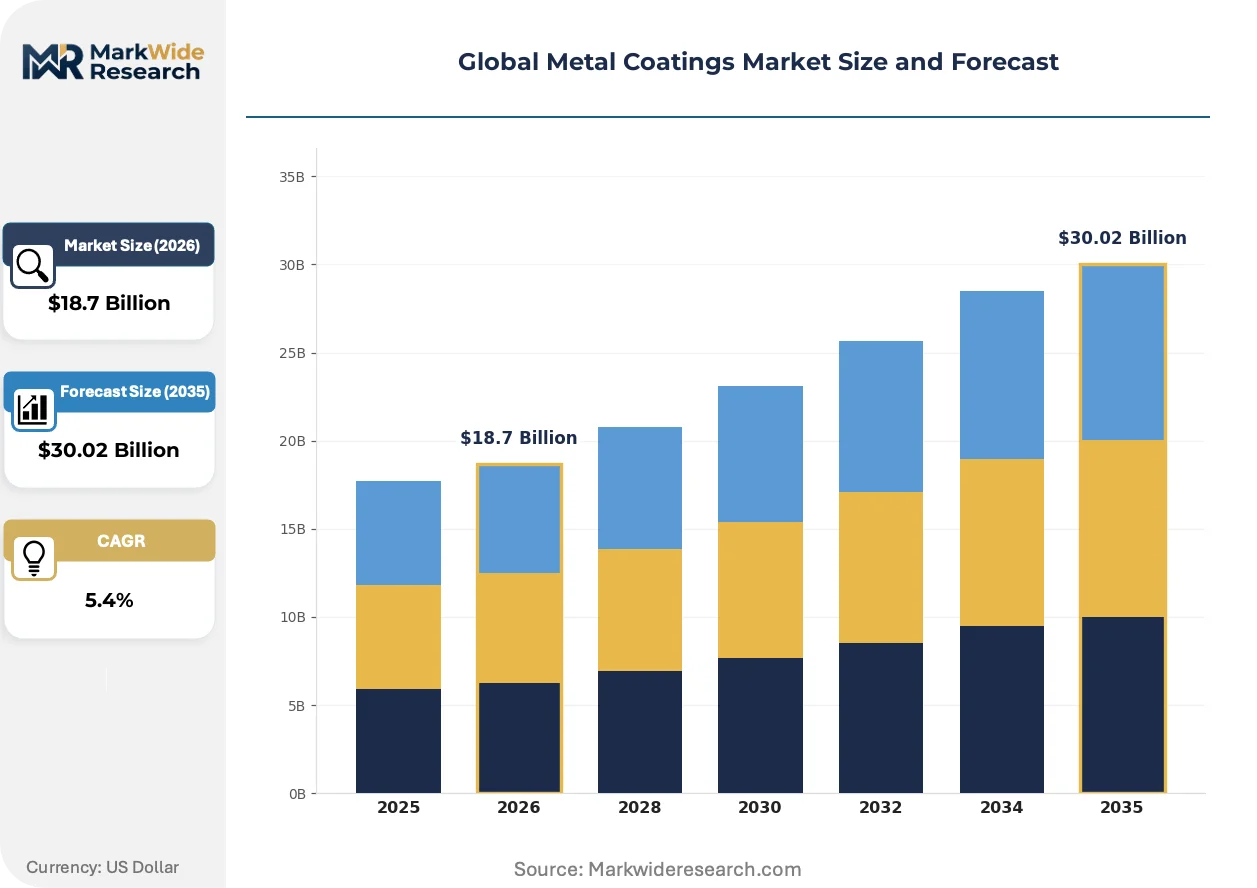
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Powder Coatings, Epoxy, Polyurethane, Acrylic, Fluoropolymer, Silicone Technology: Electroplating, Anodizing, Thermal Spraying, Chemical Vapor Deposition, Sol-Gel Processing, Galvanizing Application: Construction Equipment, Marine Vessels, Consumer Electronics, Aerospace Components, Packaging Foil, Heavy Machinery End User Industry: OEMs, Aftermarket Suppliers, Contract Manufacturers, Metal Fabricators, Defense Contractors, Transportation Specialists |
| Companies Covered | The Sherwin-Williams Company, Nippon Paint Holdings, PPG Industries, Henckler AG & Co. KGaA, The Valspar Corporation, Axalta Coating Systems, BASF, Beckers Group, AkzoNobel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal Coatings Market Shifts & Advancements
Formulation chemistry and application hardware are converging to eliminate process waste while extending service intervals in corrosive environments. These advances are redrawing competitive boundaries between commodity coaters and technology-integrated suppliers.
Self-healing microcapsule coatings is electrifying protective systems for offshore wind monopiles and subsea connectors. Shell-encapsulated corrosion inhibitors release when mechanical damage cracks the polymer matrix. Danish and UK North Sea developers are specifying these systems for 25-year design lives. The technology is compressing maintenance vessel schedules and shifting total-cost calculations toward higher upfront material spend.
China's MEE enforcement of GB 30981-2020 is restricting solvent-borne industrial coatings in the Yangtze River Delta and Pearl River Delta manufacturing belts. Provincial environmental bureaus are conducting unannounced stack testing, with non-compliant facilities facing production suspensions. Powder coating and water-borne UV-curable lines are capturing displaced volume in appliance and general industrial segments.
Appliance manufacturers are unbundling coating specifications from integrated metal supplier contracts. Procurement teams at Korean and German white-goods producers now issue separate RFQs for substrate, pretreatment, and topcoat, enabling direct relationships with specialized coil coaters. This disintermediation is most advanced in Mexico's appliance corridor, where OEMs seek tariff-advantaged regional coating capacity independent of Asian steel mill bundles.
Global Metal Coatings Market Segmentation
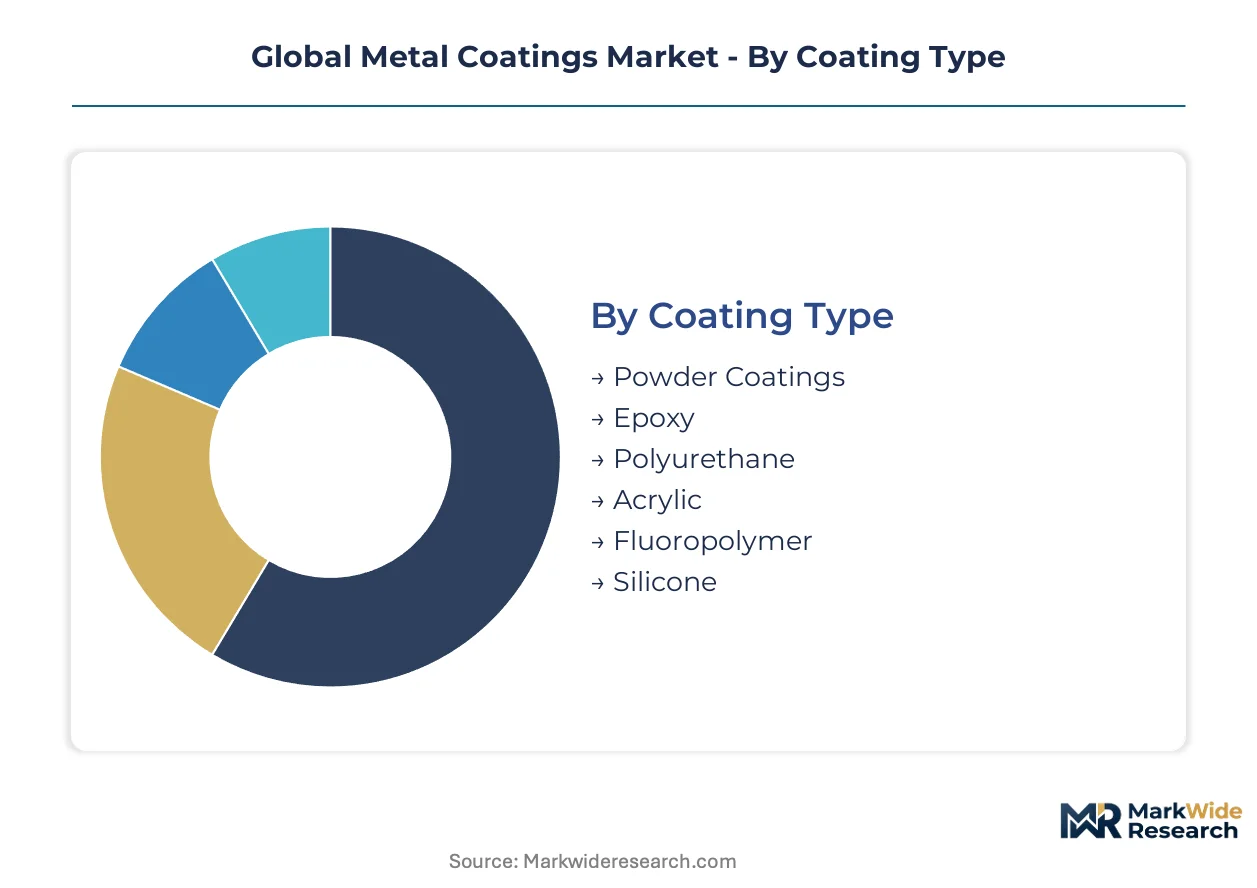
Metal coatings exhibit divergent formulation and application economics across substrate types, forcing suppliers to align R&D portfolios with specific performance tiers rather than pursuing universal solutions. Procurement patterns in this market fragment sharply between high-volume coil coating operations and precision-engineered thermal spray niches.
Coating Type:
Supply concentration tilts toward powder formulations as environmental enforcement tightens across manufacturing belts.
- Powder Coatings:Thermosetting polymer systems applied electrostatically and cured at 180-200°C deliver near-zero VOC profiles with 95%+ transfer efficiency. Appliance manufacturers in Mexico and Vietnam are migrating entire coating lines to powder systems ahead of customer sustainability audits.
- Epoxy:Two-part amine-cured systems provide exceptional chemical resistance and adhesion to ferrous substrates. Offshore wind developers in the North Sea specify epoxy-based primers for monopile foundations exposed to salt spray and cathodic protection currents.
- Polyurethane:Aliphatic formulations dominate exterior architectural applications requiring UV stability and color retention across decades of weathering exposure.
- Acrylic:Water-borne acrylics serve light-duty industrial and decorative metal finishing where cost sensitivity outweighs extreme durability requirements.
- Fluoropolymer:PVDF and FEVE resin systems command premium positioning in chemical processing equipment and high-rise curtain walls demanding 30-year color warranties.
- Silicone:Heat-resistant silicone coatings protect exhaust systems and industrial ovens operating continuously above 250°C.
Powder coatings absorb the bulk of installed capacity; fluoropolymer formulations are expanding most quickly in infrastructure specifications.
Technology:
Cost tier differentiation separates commodity metal finishing from precision deposition methods serving aerospace and power generation.
- Electroplating:Electrolytic deposition of zinc, nickel, or chromium layers provides controlled thickness from 5-25 microns for automotive fasteners and electronics housings. German and Japanese OEMs are phasing out hexavalent chromium electroplating ahead of REACH deadlines, redirecting investment toward trivalent alternatives.
- Thermal Spraying:High-velocity oxy-fuel and plasma spray systems deposit tungsten carbide-cobalt and ceramic composites at 300-800 microns for turbine blades and pump impellers. Aerospace MRO facilities in the United States and France are automating robotic thermal spray cells to compress component turnaround times.
- Anodizing:Electrochemical oxidation thickens natural aluminum oxide layers to 5-25 microns for architectural extrusions and consumer electronics enclosures.
- Chemical Vapor Deposition:Thin-film CVD coatings below 5 microns protect precision cutting tools and semiconductor processing equipment.
- Sol-Gel Processing:Liquid-phase deposition creates hybrid organic-inorganic coatings for optical and corrosion-resistant applications at moderate curing temperatures.
- Galvanizing:Hot-dip and continuous galvanizing lines deposit 7-20 micron zinc layers on steel coil and structural sections for construction and automotive applications.
Galvanizing operations command the greatest cumulative throughput; thermal spraying is gaining share fastest in maintenance-intensive industrial segments.
Application:
Volume concentration tracks capital equipment replacement cycles and infrastructure buildout intensity across regional manufacturing corridors.
- Construction Equipment:Heavy-duty polyurethane and epoxy systems protect excavator booms and loader buckets from abrasion and hydraulic fluid exposure. Chinese and Indian equipment manufacturers are localizing coating operations to reduce import dependency on finished components.
- Marine Vessels:Multi-layer anti-fouling and anti-corrosive systems extend dry-dock intervals for commercial shipping and offshore platforms. Baltic and North Sea operators are specifying self-healing microcapsule coatings to compress maintenance vessel schedules.
- Consumer Electronics:Thin-film PVD and anodized finishes on aluminum enclosures balance aesthetic differentiation with electromagnetic shielding performance.
- Aerospace Components:Thermal barrier coatings and specialized primers protect turbine hot sections and landing gear from thermal cycling and salt corrosion.
- Packaging Foil:Food-grade lacquers and laminated polymer films protect aluminum and steel container stock from acidic contents.
- Heavy Machinery:Abrasion-resistant hardfacing and epoxy formulations extend service life in mining and agricultural equipment operating in abrasive environments.
Construction equipment coatings represent the largest addressable volume; marine applications are climbing the fastest as offshore wind installation accelerates.
End User Industry:
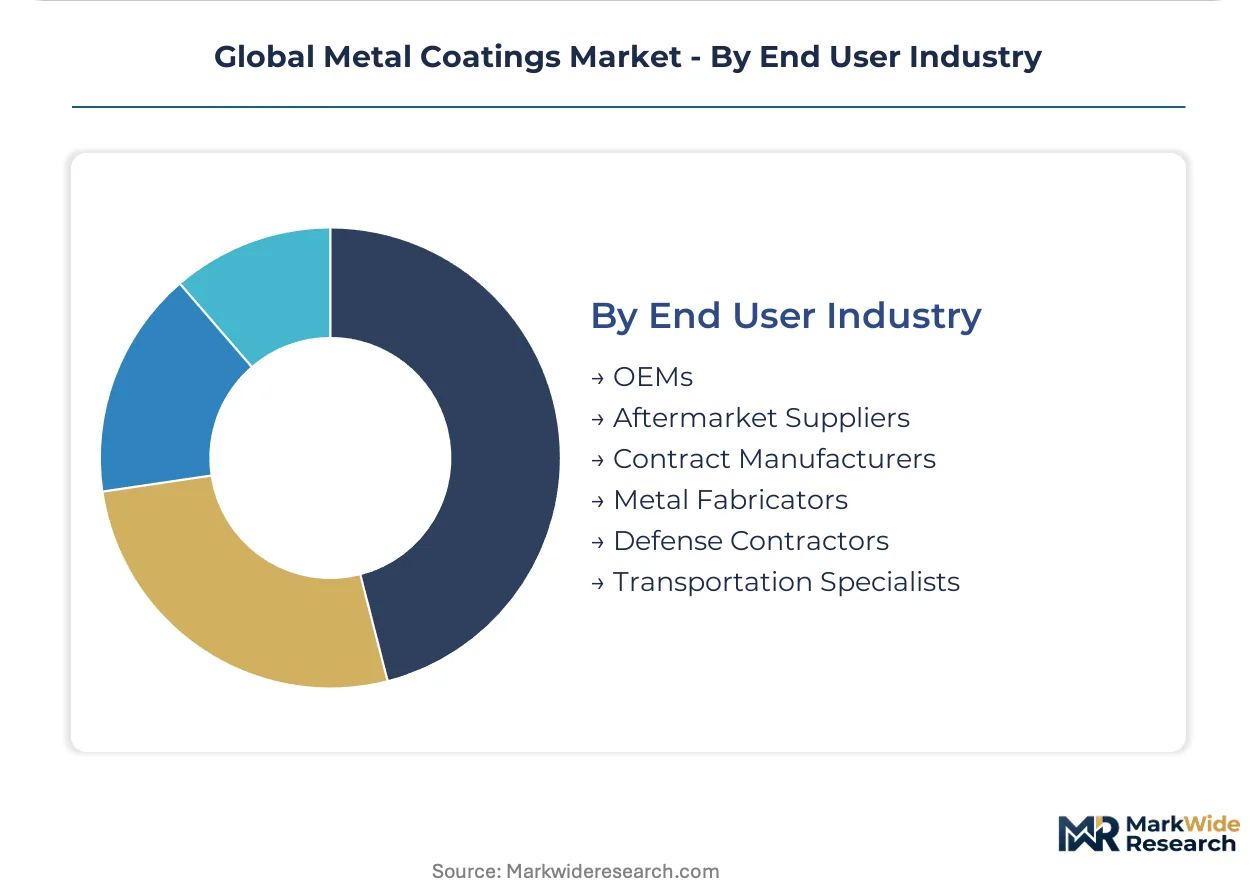
Customer type determines specification authority, with OEMs retaining direct coating control in automotive and aerospace while outsourcing dominates appliance and general fabrication.
- OEMs:Integrated automotive and heavy equipment manufacturers operate captive coating lines or issue direct specifications to qualified applicators. German automotive OEMs are consolidating approved coating supplier lists to simplify compliance verification across multi-continent production networks.
- Contract Manufacturers:Electronics and appliance fabricators in Vietnam and Mexico are investing in coil coating and powder coating infrastructure to capture relocated production from Asian steel mill bundles.
- Aftermarket Suppliers:Independent distributors and job shops provide recoating, repair, and refurbishment services for aged infrastructure and equipment.
- Metal Fabricators:Custom fabrication shops apply protective finishes to architectural and industrial components prior to site installation.
- Defense Contractors:Military specification coatings for naval vessels, armored vehicles, and aircraft require specialized qualification protocols and traceability documentation.
- Transportation Specialists:Railcar, truck trailer, and shipping container manufacturers specify high-durability systems for extended service intervals in corrosive environments.
OEMs direct the greatest coating specification authority; contract manufacturers are expanding most quickly as appliance brands disintermediate integrated steel supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zinc ore deposits and galvanizing capacity cluster around specific industrial corridors, with coating demand tracking steel production, automotive assembly, and export manufacturing intensity across five dominant national markets.
China
Hot-dip galvanizing lines along the Yangtze River Delta feed regional steel mills serving construction and automotive sectors. MEE enforcement of GB 30981-2020 restricts solvent-borne coatings in manufacturing belts, accelerating powder coating adoption in Jiangsu and Zhejiang provinces where appliance exporters face customer sustainability audits.
United States
Automotive OEMs in Michigan and Ohio specify corrosion-resistant substrates for EV platforms, compressing traditional coating cycles. EPA National Emission Standards for Hazardous Air Pollutants govern coating operations, while coil coating infrastructure in the Southeast serves relocated appliance manufacturing.
Germany
Automotive manufacturers in Bavaria and Baden-Württemberg are consolidating approved coating supplier lists across multi-continent production networks. REACH deadlines from ECHA are forcing pretreatment line retrofits to eliminate hexavalent chromium, generating replacement demand for compliant zinc-flake systems in Stuttgart's industrial corridor.
India
Contract manufacturers in Gujarat and Tamil Nadu are scaling captive galvanizing capacity to serve export-bound automotive and appliance fabricators. BIS certification requirements and state-level pollution control mandates are tightening formulation standards in the Delhi-Mumbai Industrial Corridor.
Japan
Automotive OEMs in Aichi Prefecture and Kanto region are accelerating procurement of lighter, more durable metal architectures for EV platforms. METI industrial standards and JIS specifications govern coating performance, while thermal spray robotics in Nagoya-area aerospace facilities compress component turnaround times.
Global Metal Coatings Market Competitive Landscape
Global majors compete with regional champions across formulation technology and application equipment, producing a tiered structure where scale-driven suppliers hold coil coating and powder systems while specialized operators capture thermal spray and marine niches. Three archetypes dominate: integrated chemical conglomerates with resin-to-coating pipelines, independent coating specialists with regional formulation expertise, and equipment-integrated applicators controlling deposition hardware. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players seeking captive zinc sourcing and automated application technology.
Among diversified chemical conglomerates, BASF and AkzoNobel occupy positions spanning resin production through formulated coatings, exemplifying vertical integration archetypes that control raw material cost exposure. PPG Industries anchors the North American coil coating infrastructure tier, representing scale-driven suppliers with long-term appliance manufacturer relationships. Nippon Paint Holdings exemplifies Asia-Pacific regional champions with concentrated exposure to automotive OEM specifications in Japan and expanding Southeast Asian manufacturing zones.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| Nippon Paint Holdings |
| PPG Industries |
| Henckler AG & Co. KGaA |
| The Valspar Corporation |
| Axalta Coating Systems |
| BASF |
| Beckers Group |
| AkzoNobel |
| Others |
Supply & Pricing Matrix
Automated powder coating lines displacing solvent-borne systems across China's Yangtze Delta manufacturing belt are compressing unit economics while redistributing margin capture toward equipment-integrated applicators with captive zinc sourcing. This technology transition concentrates pricing power among operators who control both formulation and deposition hardware, forcing commodity coaters into cost-pass-through relationships with volatile London Metal Exchange zinc futures.
Pricing Analysis
Warranty bundling separates premium fluoropolymer specifications for offshore wind monopiles from unbundled construction equipment coatings where OEMs self-insure performance risk. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with REACH-compliant trivalent chrome systems commanding 15-25% premia over legacy hexavalent formulations. Price erosion runs through commodity galvanizing tiers as Chinese capacity expansion outpaces regional demand growth. Contract manufacturers in Vietnam and Mexico exhibit highest price sensitivity due to thin working capital buffers, while North Sea offshore developers prioritize total-cost-of-ownership over upfront material spend.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke patterns for formulated coatings, feeding just-in-time replenishment to automotive and appliance clusters. Zinc concentrate draws from Australia, Peru, and China; resin systems hinge on petrochemical feedstocks from South Korea and Germany; specialty pigments rest on rare earth processing in China. Single-source vulnerability concentrates in Yangtze Delta hot-dip capacity, where riverine logistics disruptions or regional power rationing cascade through Asian steel mill supply chains. Distribution runs through direct mill-coater relationships for coil coating volumes, while thermal spray ceramics and fluoropolymer formulations move through authorized distributor networks with technical service attachments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global metal coatings markets are traversing a formulation-technology transition as powder systems and water-borne UV-curable chemistries displace solvent-borne legacy lines under tightening MEE and EPA enforcement. This shift rewards capital deployment toward integrated deposition equipment and captive raw material sourcing.
For Market Incumbents: Deploy backward integration into zinc alloy smelting and resin synthesis to defend margin compression from London Metal Exchange volatility. Consolidate approved supplier lists across multi-continent automotive networks to simplify REACH and GB 30981-2020 compliance verification, while automating robotic thermal spray cells in aerospace MRO facilities to compress component turnaround times against emerging equipment-integrated competitors.
For New Entrants and Emerging Players: Direct-to-appliance-brand digital procurement platforms offer white-space entry in Mexico and Vietnam, where Korean and German OEMs are disintermediating integrated steel mill bundles. Target Vietnam's northern industrial zones near Haiphong for greenfield coil coating infrastructure, leveraging tariff-advantaged regional capacity and sustainability audit requirements to bypass established Asian supplier relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with equipment-integrated applicators controlling automated deposition hardware given thermal spray robotics adoption in aerospace and power generation maintenance cycles. Long-term viability favors operators with verified low-carbon zinc sourcing and renewable-powered facilities positioned for EU Green Deal carbon border adjustment compliance. Monitor provincial environmental bureau enforcement actions in Jiangsu and Zhejiang as inflection indicators for powder coating demand displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Smelting | Captive alloy supply insulates margins from London Metal Exchange volatility cycles. |
| Automated Thermal Spray Robotics Deployment | High-velocity oxy-fuel cells compress aerospace MRO turnaround times in Nagoya and Toulouse clusters. |
| REACH-Compliant Pretreatment Line Retrofit | Trivalent chrome and zinc-flake system adoption eliminates hexavalent chromium ahead of ECHA deadlines. |
| Greenfield Coil Coating Infrastructure | Vietnam and Mexico capacity captures appliance brand procurement disintermediation from Asian steel mills. |
| Digital Coating Thickness Monitoring Integration | Eddy-current sensors linked to MES platforms reduce automotive line rework rates in Stuttgart and Detroit. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with coating plant managers, automotive OEM procurement leads, appliance brand sustainability directors, and thermal spray robotics engineers. European Chemicals Agency REACH documentation, China MEE enforcement bulletins, and EPA National Emission Standards for Hazardous Air Pollutants compliance databases provided regulatory trajectory inputs. Bottom-up capacity assessments across galvanizing, coil coating, and thermal spray facilities were triangulated against top-down consumption estimates derived from steel production and automotive assembly data.
Data-stream reconciliation across coating type, technology, application, and end-user industry dimensions enabled segmentation-level growth trajectory modeling across the projection horizon. CAGRs were derived from elasticity-adjusted demand functions incorporating EV platform corrosion-resistant substrate specifications, offshore wind installation intensity, and appliance export manufacturing relocation patterns. Zinc price volatility scenarios, regulatory compliance deadline schedules, and carbon border adjustment implementation timelines informed scenario-weighted outputs.
Inputs from plant-level capacity surveys and customs trade records were available through the study window; gaps in real-time inventory positioning data and unannounced provincial environmental enforcement actions introduce uncertainty bands around near-term volume estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Asia-Pacific Radiation Curable Coatings Market
Coatings
Global Automotive Specialty Coatings Market
Coatings
Europe Thermal Spray Market
Coatings
Japan Automotive OEM Coatings Market
Coatings
France Automotive OEM Coatings Market
Coatings
Insulation Coating Market
Coatings
Automotive Refinish Coatings Market
Coatings
Anti Soiling Coating Market
Coatings
Coatings and Fillings Market
Coatings
Urethane Surface Coatings Market
Coatings
Middle East and Africa Super Hydrophobic Coatings Market
Coatings
Diamond-Like Carbon Coatings Market
Coatings
FBE Coatings Market
Coatings
Flexible Waterproof Coating Market
Coatings
High Performance Coatings Market
Coatings
2K Protective Coatings Market