
 Furniture Wood Coatings Market | 2026-2036
Furniture Wood Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Furniture Wood Coatings Market Analysis
China is fragmenting as new coating capacity comes online across Guangdong and Zhejiang provinces. PPG Industries Inc. anchors North American supply through integrated resin-to-coating operations. Akzo Nobel N.V. differentiates via water-based technology leadership in European architectural and furniture segments. Asian Paints Ltd. dominates Indian distribution through extensive retailer networks reaching secondary cities.
Furniture wood coatings encompass stains, sealants, varnishes, and paints formulated with urethane, acrylic, or alkyd binders at solids contents ranging from 20% to 45%, applied by spray, roll, or vacuum coating to protect timber substrates from moisture, UV degradation, and mechanical wear. The technology dimension shows water-based formulations gaining share against solvent-based alternatives as VOC thresholds tighten across major economies; UV-cured systems occupy premium factory-applied segments where line speed and film durability justify capital investment. Application splits reveal residential furniture as the mature volume base while outdoor furniture commands higher per-unit coating values due to weathering-performance requirements.
REACH in Europe, EPA regulations in the United States, and China's MEE standards collectively restrict solvent emissions and mandate hazard communication across coating formulations. These frameworks push manufacturers toward low-VOC and bio-based chemistries while raising compliance costs for smaller compounders. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation investments as compliance thresholds continue tightening.
Market Dynamics
Water-based coating technology is virtualizing solvent-based formulations as REACH and EPA VOC thresholds tighten, forcing resin suppliers and applicators to retool curing lines and reformulate at commercial scale.
Growth Catalysts
- REACH VOC limits:European furniture manufacturers face mandatory solvent reduction timelines, accelerating water-based system trials across factory-applied residential segments.
- UV-cured line speeds:Flat-pack furniture producers in Guangdong province adopt electron-beam and UV curing to compress coating cycles from hours to minutes.
- Vietnam export manufacturing:Coastal industrial zones near Ho Chi Minh City attract coating applicators serving North American and European furniture supply chains.
Market Restraints
- Titanium dioxide volatility:Pigment cost swings compress margins for white and pastel furniture coatings, forcing reformulation toward extenders and opacity aids.
- Isocyanate supply concentration:Polyisocyanate hardener production clusters in Germany and China expose coating compounders to cross-border logistics disruptions.
- Water-based durability gaps:Exterior furniture applications still require solvent-borne alkyds for hydrolysis resistance, limiting full technology substitution.
Strategic Opportunities
- India secondary cities:Tier-2 and Tier-3 furniture manufacturing hubs lack dedicated coating distribution, creating whitespace for localized blending operations.
- Bio-based binders:Epoxidized soybean oil and lignin-derived resins qualify for EU Green Deal procurement preferences in public-sector furniture.
- Direct-to-factory digital color matching:Cloud-linked spectrophotometry eliminates distributor inventory carrying costs for custom stain formulations.
Industry Challenges
- Formulation chemist scarcity:Water-based resin compatibility expertise remains concentrated among senior technicians at established coating houses.
- Legacy spray booth conversion:Existing solvent-optimized application infrastructure requires capital-intensive humidity control and flash-off zone extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Furniture Wood Coatings Market |
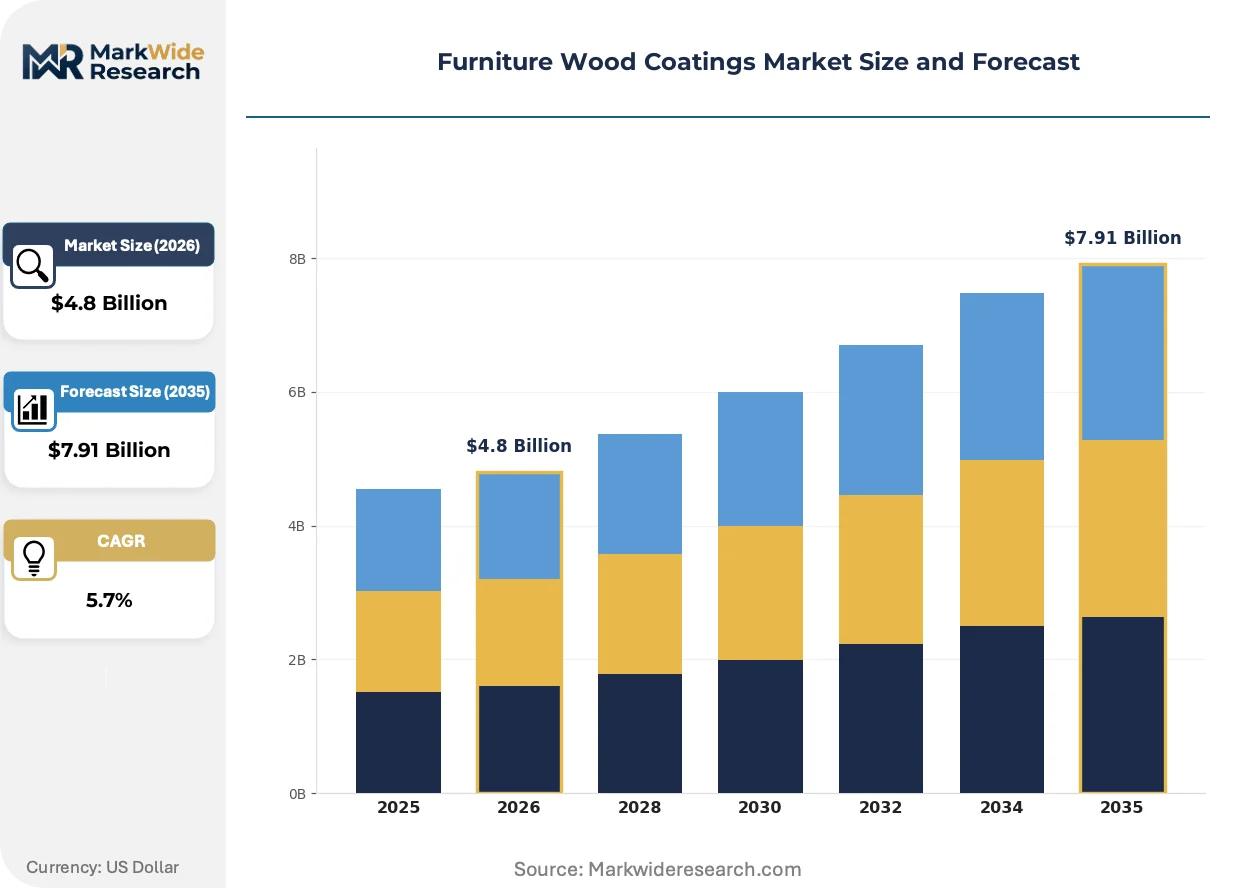
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stains, Sealants, Varnishes, Paints Application: Residential Furniture, Commercial Furniture, Outdoor Furniture, DIY Projects Technology: Water-based, Solvent-based, UV-cured, Bio-based End User: Manufacturers, Retailers, Contractors, Hobbyists |
| Companies Covered | The Sherwin-Williams Company, PPG Industries Inc., Akzo Nobel N.V., Axalta Coating Systems, RPM International Inc., Asian Paints Ltd., Nippon Paint Holdings Co., Ltd., BASF SE, Jotun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Furniture Wood Coatings Market Emerging Trajectories
Digital color libraries and predictive curing algorithms are compressing the gap between specification and production, while regulatory chemistry constraints force binder innovation at the molecular level.
UV-LED curing systems is virtualizing conventional mercury-arc installations in high-volume furniture lines. Flat-panel producers in Zhejiang province are retrofitting vacuum coating machines with 395-nanometer LED arrays to eliminate mercury handling and reduce energy draw. This shift is virtualizing the capital equipment upgrade cycle, compressing payback periods for coating line investments.
F-Gas Regulation in the European Union restricts hydrofluorocarbon propellants in aerosolized wood coatings. Aerosol packagers face reformulation toward compressed air or hydrocarbon alternatives, raising per-unit production costs. Decorative touch-up sprays and DIY furniture repair kits bear the highest compliance burden, with manufacturers accelerating water-based pump-spray development.
Specification authority is migrating from distributors to end-use furniture brands with centralized color stewardship. Large-format retailers now mandate coated-component color tolerance bands tighter than traditional industry norms. This concentration of quality enforcement is most visible in Scandinavian contract furniture, where brand-owned color labs pre-approve supplier batches before factory release.
Furniture Wood Coatings Market Segmentation
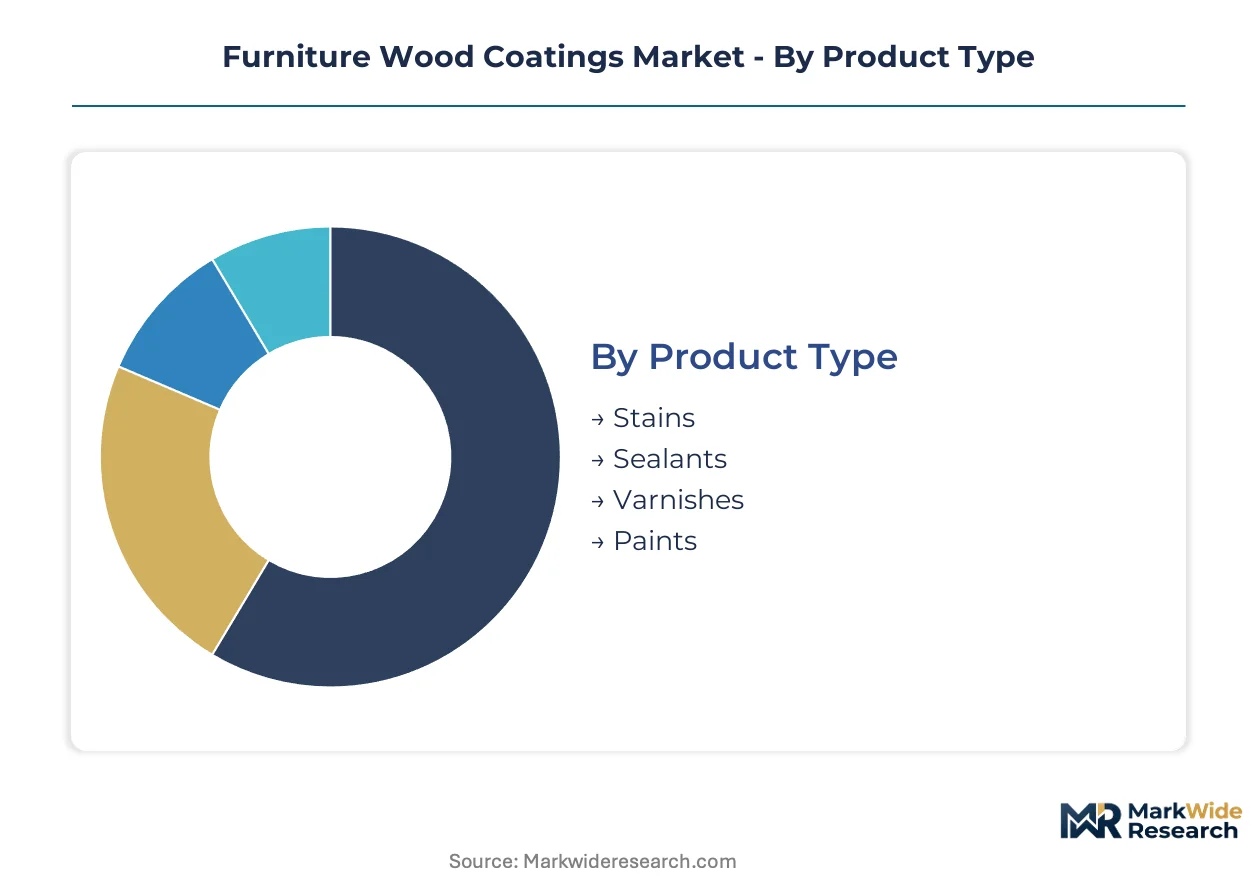
Segmentation in furniture wood coatings reveals how formulation chemistry, application environment, and buyer sophistication create distinct competitive arenas. Each dimension carries different margin structures, regulatory exposure, and technology substitution timelines.
Product Type:
The use-case spectrum spans protective clear finishes to pigmented systems, with transparency level and film build determining substrate visibility and weathering performance.
- Stains:Penetrating dye-pigment hybrids that color wood grain without obscuring texture, formulated at 5-15% solids for absorption into open-pored species like oak and ash. Demand concentrates in North American residential cabinetry where natural aesthetics command premium positioning, though water-based stain compatibility with tropical hardwoods remains technically challenging.
- Sealants:Low-build penetrating oils and acrylic emulsions that block moisture ingress while maintaining tactile wood feel. Factory-applied sealants for flat-pack bedroom furniture in Vietnam are displacing traditional wax finishes as export quality standards tighten.
- Varnishes:Film-forming urethane or alkyd resins delivering glossy to satin sheens with abrasion resistance. Marine-grade varnishes for teak outdoor furniture in coastal Mediterranean markets retain solvent-borne formulations for hydrolysis stability.
- Paints:Opaque pigmented systems that obscure substrate entirely, requiring higher titanium dioxide loadings and multiple coat sequences. White and pastel furniture coatings face raw material cost pressure from pigment volatility.
The dominant share belongs to varnishes, while stains are closing the gap fastest.
Application:
Volume distribution follows construction cycle intensity and replacement frequency, with outdoor exposure creating the most demanding specification environment.
- Residential Furniture:Beds, tables, and storage systems coating at 20-35 microns dry film thickness for indoor durability. Guangdong province factories supply both domestic Chinese consumption and export assembly for North American retailers.
- Commercial Furniture:Contract seating and workstations requiring fire-retardant and high-traffic wear resistance. Scandinavian brand-owned color labs enforce tolerance bands tighter than traditional industry norms.
- Outdoor Furniture:Teak, eucalyptus, and acacia pieces facing UV degradation and cyclic wet-dry exposure. Per-unit coating values run highest here due to weathering-performance requirements and frequent re-coat cycles.
- DIY Projects:Consumer-applied touch-up and refinishing activity, concentrated in home improvement retail channels. F-Gas Regulation compliance costs hit aerosolized decorative sprays hardest.
Residential furniture anchors volume, yet outdoor applications generate the steepest expansion trajectory as climate-adaptive formulations improve.
Technology:
Regulatory chemistry constraints and capital equipment decisions partition the market between legacy solvent systems and emerging low-emission alternatives.
- Water-based:Acrylic and polyurethane dispersions at 30-45% solids with VOC content below regulatory thresholds. REACH and EPA limits are accelerating factory-applied trials across European and North American residential segments.
- Solvent-based:Alkyd and nitrocellulose systems delivering fast dry and high gloss, still required for exterior hydrolysis resistance where water-based durability gaps persist.
- UV-cured:Acrylate oligomers polymerized by electron-beam or ultraviolet irradiation in seconds. Zhejiang flat-panel producers retrofit vacuum coaters with 395-nanometer LED arrays to compress cycle times.
- Bio-based:Epoxidized soybean oil and lignin-derived binders qualifying for EU Green Deal procurement preferences in public-sector furniture.
Solvent-based coatings retain the largest installed base, though UV-cured systems are gaining share fastest in high-volume factory lines.
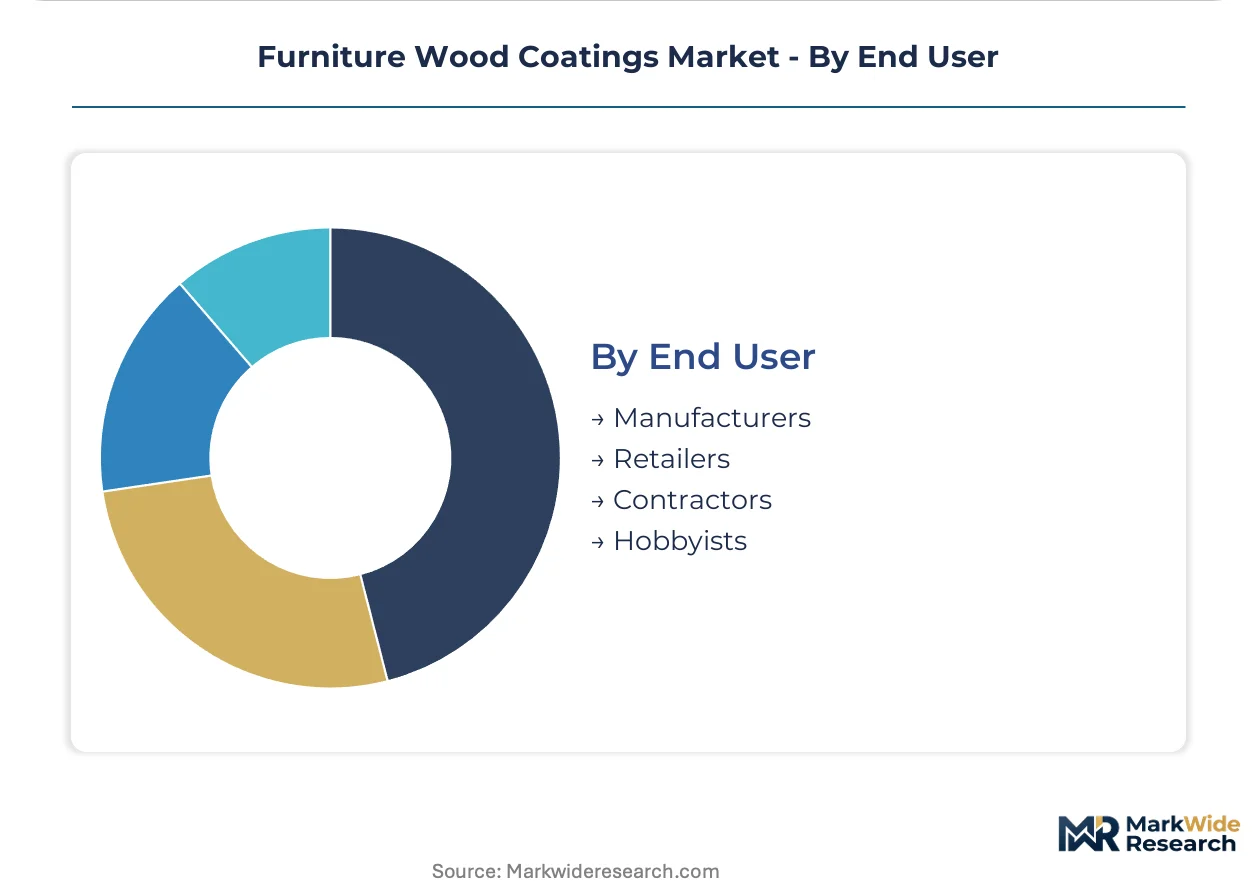
End User:
Buying behavior diverges sharply between specification professionals with centralized color stewardship and price-sensitive fragmented purchasers.
- Manufacturers:Integrated coating operations or toll-applied systems with batch consistency requirements. Tier-2 Indian furniture hubs lack dedicated coating distribution, creating whitespace for localized blending.
- Retailers:Large-format chains mandating coated-component color tolerance bands and direct-to-factory digital color matching to eliminate distributor inventory carrying costs.
- Contractors:Professional refinishers and installation crews requiring rapid availability and technical support. Water-based resin compatibility expertise concentrates among senior technicians at established coating houses.
- Hobbyists:Consumer DIY segment sensitive to application ease and cleanup convenience. Pump-spray formats are displacing aerosols under F-Gas Regulation pressure.
Manufacturers command the dominant procurement volume, while retailers are restructuring supply relationships fastest through centralized color authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal manufacturing zones in China concentrate coating formulation capacity, while regulatory divergence between REACH, EPA, and MEE standards fragments compliance requirements across export destinations.
China
Guangdong and Zhejiang provinces host vacuum coating line retrofits serving flat-pack furniture exports to North America. MEE standards tighten VOC thresholds for solvent-based formulations. Dongguan industrial clusters adopt UV-LED curing arrays to compress production cycles.
United States
Residential furniture manufacturers source water-based coatings for cabinetry and bedroom sets. EPA regulations mandate hazard communication and solvent emission controls. Southeast industrial zones near Atlanta attract toll-coating applicators serving mass-market retailers.
Germany
Polyisocyanate hardener production clusters expose coating compounders to cross-border logistics exposure. REACH VOC limits accelerate water-based system trials across factory-applied residential segments. Bavarian chemical parks anchor resin-to-coating integration for European supply.
Vietnam
Coastal industrial zones near Ho Chi Minh City attract coating applicators serving North American and European furniture supply chains. Export volume growth drives coating adoption among residential furniture manufacturers. Binh Duong province hosts expanding blending operations for secondary finishers.
India
Tier-2 and Tier-3 furniture manufacturing hubs lack dedicated coating distribution, creating whitespace for localized blending operations. BIS standards govern product quality and labeling requirements. Gujarat and Maharashtra industrial corridors concentrate emerging manufacturing capacity.
Furniture Wood Coatings Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying resin and pigment intermediates. The vendor base organizes around three strategic archetypes: integrated multinationals with captive resin production, regional formulators serving localized distribution networks, and technology licensors specializing in UV-cured or bio-based chemistries. Consolidation pressures concentrate among mid-scale compounders facing REACH and EPA compliance cost escalation. Dominant competitive moves include backward integration into resin manufacturing and geographic expansion into Vietnamese and Indian industrial zones.
Within the integrated multinational tier, PPG Industries Inc. and Akzo Nobel N.V. exemplify platform-scale operations spanning formulation through application support. Asian Paints Ltd. occupies a position anchoring Indian distribution through extensive retailer networks. These three companies represent distinct geographic anchoring—North American, European, and South Asian respectively—while sitting within the broader pattern of technology leadership migration toward water-based and UV-cured systems.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries Inc. |
| Akzo Nobel N.V. |
| Axalta Coating Systems |
| RPM International Inc. |
| Asian Paints Ltd. |
| Nippon Paint Holdings Co., Ltd. |
| BASF SE |
| Jotun |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Guangdong coating facilities compresses margins for commodity varnish grades while simultaneously pressuring suppliers toward extended payment terms and technical service bundling to defend account relationships.
Pricing Analysis
REACH dictates the pricing tier structure across European supply, separating certified low-VOC water-based systems from legacy solvent formulations facing compliance cost escalation. Price differentiation rests on certification grade and volume scale, with flat-pack furniture producers commanding standard-tier contracts while premium outdoor applications absorb higher per-unit coating values. Cost compression in white and pastel pigmented coatings intensifies because titanium dioxide volatility forces reformulation toward extenders. DIY hobbyists exhibit highest price sensitivity, whereas Scandinavian contract furniture brands prioritize color tolerance precision over unit cost.
Supply Chain Analysis
Extended payment terms from German polyisocyanate hardener producers expose coating compounders to working capital strain, particularly when cross-border logistics disruptions interrupt just-in-time resin deliveries. Supply concentrates in China, Germany, and Vietnam, with raw material dependencies spanning titanium dioxide pigments, acrylic emulsions, and UV-curable acrylate oligomers. Single-source vulnerability clusters around isocyanate hardener production, where geographic concentration creates chokepoint exposure. Distribution runs through toll-coating applicators integrated with flat-pack furniture assembly lines, supplemented by direct-to-factory digital color matching platforms eliminating distributor inventory carrying costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where cloud-linked spectrophotometry and predictive curing algorithms are redefining specification authority, shifting value capture from compounders toward integrated color-stewardship platforms.
For Market Incumbents: Build captive resin production moats through backward integration into polyurethane dispersion manufacturing in Vietnamese industrial zones. PPG Industries Inc. and Akzo Nobel N.V. anchor positions through integrated resin-to-coating operations, yet emerging UV-LED technology licensors threaten premium factory-applied segments. Incumbents should deepen upstream control over acrylic emulsion supply while accelerating certification investment for EU Green Deal procurement eligibility.
For New Entrants and Emerging Players: Tier-2 and Tier-3 Indian furniture manufacturing hubs present whitespace for localized blending operations with dedicated distribution infrastructure. Secondary cities in Gujarat and Maharashtra lack coating formulator presence despite expanding manufacturing capacity. New entrants should pursue toll-manufacturing partnerships with established resin suppliers to bypass formulation chemist scarcity constraints.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because jurisdictional divergence between REACH, EPA, and MEE standards creates persistent formulation complexity that rewards compliance-specialist compounders. Acquisition targets include mid-scale regional formulators with water-based technology portfolios and established Vietnamese coating applicator relationships. The signal to watch is F-Gas Regulation enforcement intensity accelerating aerosol format displacement toward pump-spray alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Manufacturing | Captive polyurethane dispersion supply insulates margin pressure from German and Chinese hardener concentration. |
| UV-LED Curing Line Retrofit | Zhejiang flat-panel producers compress cycle times while eliminating mercury handling compliance costs. |
| Localized Blending Operations in India | Tier-2 hub proximity reduces logistics burden for Gujarat and Maharashtra furniture manufacturers. |
| Bio-based Binder Certification | Epoxidized soybean oil formulations qualify for EU Green Deal public-sector procurement preferences. |
| Direct-to-Factory Digital Color Matching | Cloud-linked spectrophotometry platforms disintermediate distributor inventory carrying costs for custom stains. |
Methodological Framework
The analysis maps water-based, solvent-based, UV-cured, and bio-based formulation sub-sectors, each validated through coating compounder technical directors, furniture manufacturer procurement leads, and resin supplier account managers. Primary interviews with factory-applied coating applicators in Guangdong and Zhejiang provinces combined with secondary validation against customs trade data, MEE regulatory filings, and ECHA REACH registration databases. Bottom-up capacity utilization estimates triangulated against top-down export volume projections from Vietnamese industrial zone authorities.
Assumptions held fixed include REACH and EPA VOC threshold trajectories, while variables spanned titanium dioxide price volatility bands and UV-LED equipment adoption curves across the projection horizon. Segmentation dimensions modeled encompass technology type, application environment, and end-user procurement sophistication, with regional production hub clustering as an industry-specific overlay. CAGRs derived from capacity expansion announcements correlated with export order flow data from North American furniture retailers. Forecast inputs included MEE enforcement intensity scenarios and F-Gas Regulation aerosol displacement timelines.
Practitioners should monitor REACH amendment proposals and EPA hazardous air pollutant reviews for early signals of regulatory threshold acceleration. Forecasts reflect documented assumptions regarding water-based durability gap closure rates and UV-cured equipment payback period compression. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Global Construction Paints and Coatings Market
Paints & Coatings
Paint Buckets Market
Paints & Coatings
Road Marking Paint Market
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
Hybrid Paint Cans Market
Paints & Coatings
Saudi Arabia Paints and Coatings Market
Paints & Coatings
United Arab Emirates (UAE) Paints and Coatings Market
Paints & Coatings
Global Thinners and Paint Strippers Market
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
Iraq Paints and Coatings Market
Paints & Coatings
Automotive Paints Market
Paints & Coatings
Epoxy Paint Thinner Market
Paints & Coatings
Paints and Coatings Additives Market
Paints & Coatings
Bio-Based and Low VOC Paints Market
Paints & Coatings
India Paints and Coatings Market
Paints & Coatings
Europe Paints and Coatings Market