
 Tris Nonylphenyl Phosphite Market | 2026-2036
Tris Nonylphenyl Phosphite Market Size, Share, and Industry Trends Forecast 2026-2036
Tris Nonylphenyl Phosphite Market Outlook
Asian phosphite producers is repositioning capacity toward higher-purity grades to serve automotive and electronics-grade polymer specifications. Valtris Specialty Chemicals leverages backward integration into phenol chemistry to secure feedstock cost advantages across North American supply chains. Songwon Industrial Co., Ltd. anchors its position through dedicated antioxidant R&D centers in South Korea that develop customized stabilizer packages for polyolefin processors.
Tris nonylphenyl phosphite is an organophosphorus compound with the formula C45H69O3P, functioning primarily as a secondary antioxidant and heat stabilizer that decomposes hydroperoxides formed during polymer processing. Manufacturers typically synthesize the material through the transesterification of phenyl phosphite with nonylphenol, yielding a viscous liquid with phosphorus content around 4.0% that interrupts oxidative degradation chains in hydrocarbon polymers. The application segmentation reveals plastics as the dominant consumption channel, where polyethylene and polypropylene processors absorb the majority of volume, while the rubber segment is gaining traction as tire manufacturers reformulate compounds for extended durability under thermal stress. End-user demand from the automotive sector commands premium pricing due to stringent long-term heat-aging requirements, whereas packaging applications operate on thinner margins driven by high-volume, specification-grade procurement.
EPA chemical safety evaluations under the Toxic Substances Control Act and REACH substance restrictions in Europe are compelling reformulation toward lower-free-phenol variants, directly influencing product development roadmaps and manufacturing investments. BIS certification requirements in India for imported chemical additives create compliance barriers that favor local producers such as Sterling Auxiliaries Pvt. Ltd. and Krishna Antioxidants Pvt. Ltd. Stakeholders must monitor regulatory divergence between jurisdictions, as divergent purity thresholds threaten to fragment product specifications and complicate global inventory management.
Market Dynamics
REACH substance restrictions and EPA chemical safety reviews under the Toxic Substances Control Act are forcing manufacturers to reengineer tris nonylphenyl phosphite toward lower-free-phenol grades, compressing legacy product margins while opening premium tiers for compliant variants.
Growth Catalysts
- Automotive polymer stabilization:Polyethylene and polypropylene processors serving under-the-hood applications require secondary antioxidants that withstand sustained thermal stress above 150°C.
- REACH compliance mandates:European formulators must substitute legacy phosphite grades with purified variants below 0.1% free phenol content, redirecting procurement toward certified suppliers.
- China domestic polymer scaling:Local polyolefin production capacity expansion is absorbing greater volumes of stabilizers through integrated formulation facilities in Jiangsu and Zhejiang provinces.
Market Restraints
- Nonylphenol feedstock volatility:Crude oil-linked benzene and propylene costs transmit directly into phenol pricing, squeezing phosphite producer margins during upstream spikes.
- Substitution by phenolic antioxidants:Hindered phenol chemistries from Songwon and BASF are capturing share in general-purpose polyethylene where cost sensitivity outweighs synergistic performance needs.
- BIS certification barriers:India's Bureau of Indian Standards mandates separate testing protocols for each phosphite import shipment, extending lead times and favoring domestic auxiliary producers.
Strategic Opportunities
- Electronics-grade polymer demand:High-purity phosphite specifications for connector housings and circuit board substrates command 40-60% pricing premiums over standard industrial grades.
- Southeast Asia tire manufacturing:Thailand and Vietnam rubber compounding facilities are reformulating for extended heat-aging performance, opening new antioxidant specification channels.
- EU Green Deal chemical sustainability:The European Commission's Safe and Sustainable by Design framework incentivizes bio-based phenol feedstock development for phosphite synthesis.
Industry Challenges
- Process analytical chemistry talent scarcity:Manufacturers struggle to recruit specialists capable of validating sub-500 ppm free phenol detection methods for regulatory submissions.
- Multi-jurisdiction specification fragmentation:Divergent purity thresholds between EPA, REACH, and BIS regimes complicate global inventory pooling and force SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tris Nonylphenyl Phosphite Market |
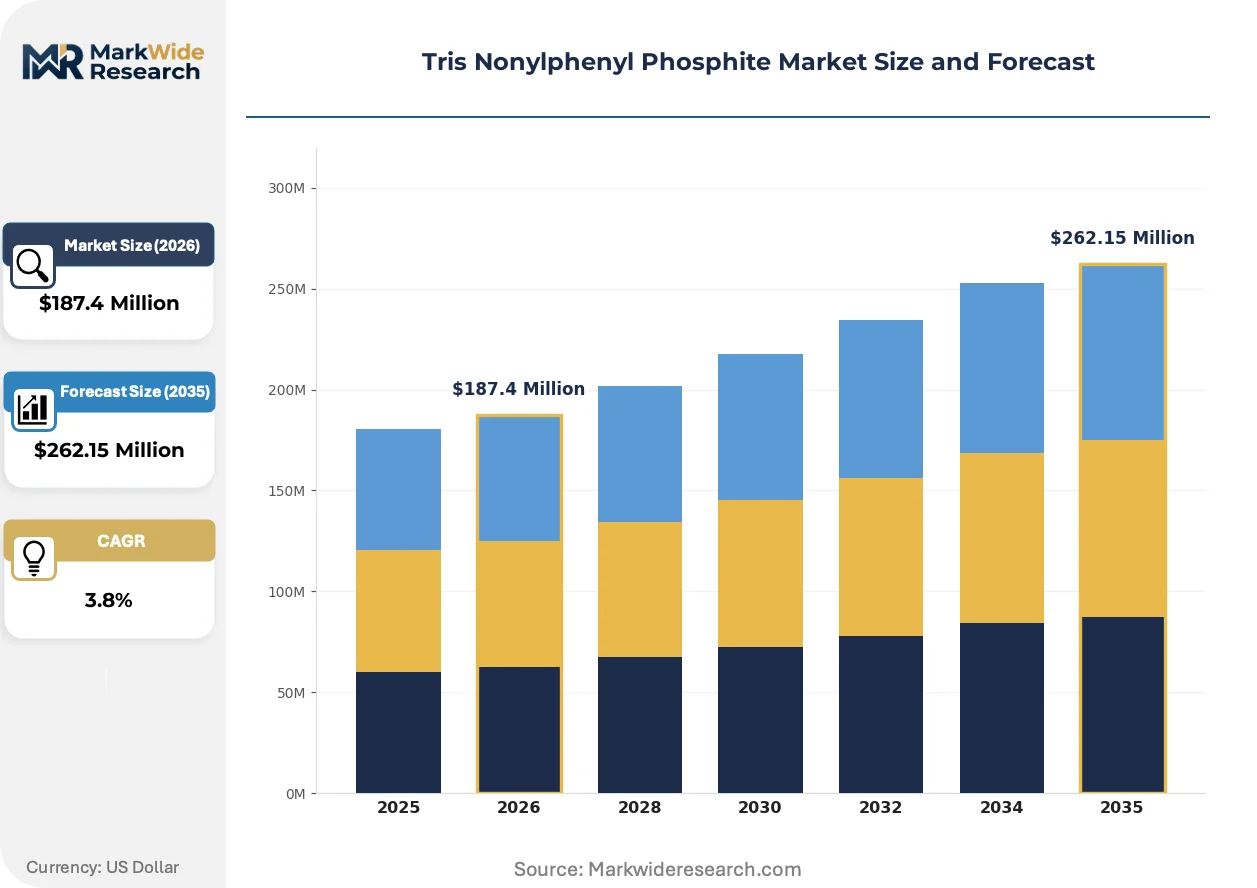
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidants, Stabilisers, Additives, Processing Aids Application: Plastics, Rubber, Coatings, Adhesives End User: Chemical Industry, Automotive Sector, Packaging, Electronics Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Valtris Specialty Chemicals, Addivant USA LLC, Songwon Industrial Co., Ltd., Sterling Auxiliaries Pvt. Ltd., Krishna Antioxidants Pvt. Ltd., Dover Chemical Corporation, Sandhya Group, Gulf Stabilizers Industries, Galata Chemicals Holding GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tris Nonylphenyl Phosphite Market Strategic Shifts
Continuous reactor technology and real-time spectroscopic monitoring are displacing batch phosphite synthesis, enabling tighter quality control while reducing solvent waste streams. Formulation houses now demand stabilizer packages with documented carbon footprints.
Continuous flow reactor systems for transesterification are modularizing phosphite manufacturing, allowing producers to scale output in 500-ton increments rather than committing to multi-thousand-ton batch trains. Polymer compounders in Germany and Japan are adopting these flexible supply arrangements to match stabilizer procurement with volatile order books. The technology is modularizing capital deployment strategies across mid-tier antioxidant suppliers.
EPA chemical safety evaluations under the Toxic Substances Control Act are scrutinizing organophosphorus compounds for endocrine disruption potential, compelling formulators to maintain detailed substance volume records and exposure assessments. The agency's 2024-2028 chemical work plan explicitly targets phenol derivatives used in polymer additives. North American automotive suppliers are accelerating qualification of alternative phosphite architectures to preempt supply interruptions.
Compounders are consolidating stabilizer procurement through direct long-term agreements with phosphite manufacturers, bypassing traditional distributor networks that carried 15-20% markups. Tier 1 automotive suppliers in Michigan and Stuttgart now negotiate annual volume contracts specifying free phenol ceilings and lot traceability. This channel compression is most pronounced in specifications governed by OEM thermal aging protocols exceeding 5,000 hours.
Tris Nonylphenyl Phosphite Market Segmentation
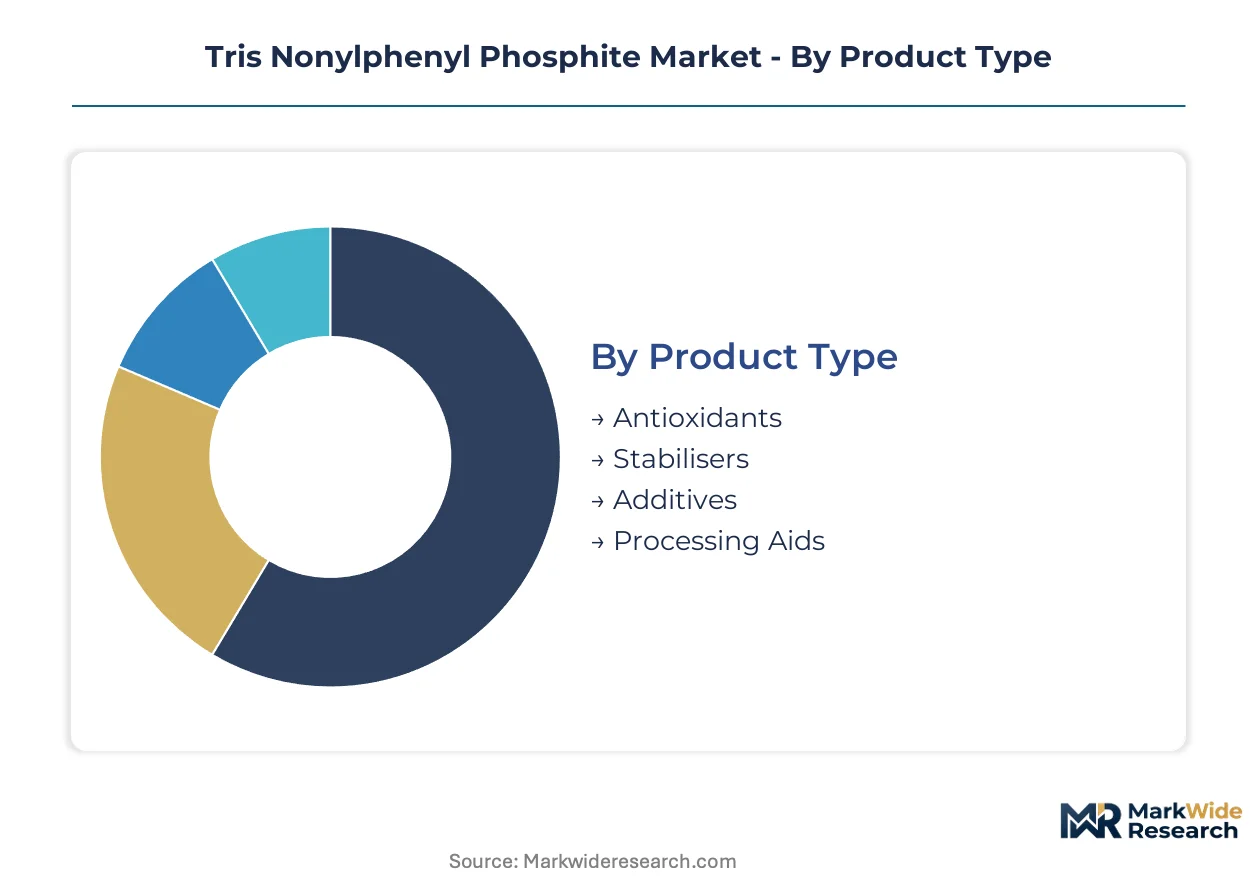
Segmentation in tris nonylphenyl phosphite reveals how purity thresholds, thermal performance requirements, and regulatory compliance reshape procurement patterns across polymer value chains. Buyers sort by functional chemistry, application severity, and supply chain reliability rather than commodity specifications alone.
Product Type:
Cost tier separates commodity buyers from specification-driven formulators seeking certified low-free-phenol grades.
- Antioxidants:Secondary phosphite antioxidants decompose hydroperoxides in polyolefin processing, with automotive under-the-hood specifications demanding sub-500 ppm free phenol certification from qualified suppliers. Tier 1 automotive suppliers in Michigan and Stuttgart negotiate annual volume contracts with lot traceability requirements exceeding 5,000-hour thermal aging protocols. Volume sits with standard industrial grades; growth tilts toward automotive-certified low-phenol variants.
- Stabilisers:Heat stabiliser formulations combine phosphites with hindered phenols in synergistic packages, where electronics-grade specifications for connector housings command substantial pricing premiums over industrial applications. Compounders in Germany and Japan adopt flexible supply arrangements matching procurement to volatile order books through modular manufacturing commitments.
- Additives:Multi-functional additive blends integrate phosphites with UV absorbers and metal deactivators for outdoor polymer applications.
- Processing Aids:Lubricant-compatible phosphite variants reduce torque during high-shear extrusion of filled polypropylene compounds.
Margin compression in commodity antioxidants redirects R&D investment toward stabiliser synergies and certified additive systems.
Application:
Application severity determines whether buyers prioritize cost efficiency or thermal endurance certification.
- Plastics:Polyethylene and polypropylene processors absorb the majority of phosphite volume, with sustained thermal stress above 150°C in automotive applications requiring secondary antioxidant architectures that interrupt oxidative degradation chains. REACH substance restrictions compel European formulators to substitute legacy grades with purified variants below 0.1% free phenol content. Volume concentrates in polyolefin stabilization; expansion accelerates in high-purity electronics-grade specifications.
- Rubber:Tire manufacturers reformulate compounds for extended durability under thermal stress, with Thailand and Vietnam rubber compounding facilities opening new antioxidant specification channels for heat-aging performance. Southeast Asian tire production scaling drives reformulation toward phosphite-phenol synergies in tread and sidewall compounds.
- Coatings:Powder coating resin stabilization employs phosphites to prevent yellowing during high-temperature curing cycles.
- Adhesives:Hot-melt adhesive formulations incorporate phosphites to maintain bond strength through thermal cycling in automotive assembly applications.
Plastics maintains volume dominance; rubber applications gain share fastest as tire durability specifications tighten.
End User:
End-user maturity determines whether procurement flows through distributor networks or direct manufacturer agreements.
- Chemical Industry:Polymer additive formulators and compounders serve as the primary demand channel, with integrated formulation facilities in Jiangsu and Zhejiang provinces absorbing greater stabilizer volumes as domestic Chinese polyolefin production scales. These chemical intermediaries blend phosphites into customized antioxidant packages for downstream polymer processors.
- Automotive Sector:Under-the-hood applications command premium pricing due to stringent long-term heat-aging requirements, with OEM thermal aging protocols driving direct long-term agreements that bypass traditional 15-20% distributor markups. Procurement consolidation through annual volume contracts specifies free phenol ceilings and mandatory lot traceability.
- Packaging:High-volume, specification-grade procurement operates on thinner margins driven by food-contact compliance and cost sensitivity in flexible film production.
- Electronics:Connector housings and circuit board substrates require high-purity phosphite specifications with documented carbon footprints and sub-500 ppm contamination thresholds.
Automotive direct procurement expands fastest; packaging remains the highest-volume consumption channel.
Distribution Channel:
Channel selection reflects buyer scale, specification complexity, and inventory pooling requirements across fragmented purity standards.
- Direct Sales:Tier 1 automotive suppliers and large polymer compounders negotiate direct manufacturer relationships, with EPA, REACH, and BIS regulatory divergence complicating global inventory pooling and forcing SKU proliferation that favors dedicated supply agreements. Direct channels capture specification-heavy buyers requiring lot traceability.
- Distributors:Regional chemical distributors maintain inventory of standard industrial grades for mid-tier processors, though channel compression pressures traditional markup structures as compounders consolidate procurement.
- Online Retail:E-procurement platforms serve small-volume buyers and research laboratories requiring rapid sample access and technical documentation.
- Wholesalers:Bulk wholesalers aggregate demand from smaller polymer processors in developing markets with limited specification requirements.
Direct sales gain share in automotive and electronics; distributors retain position in standard industrial grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phenol feedstock availability along the US Gulf Coast anchors North American phosphite production, while polymer processing clusters in Germany and China absorb the majority of stabilizer volume. Regulatory divergence across EPA, REACH, and BIS regimes fragments product specifications and complicates cross-border inventory pooling.
United States
Automotive under-the-hood applications in Michigan and Ohio drive demand for sub-500 ppm free phenol certified grades. EPA chemical safety reviews under the Toxic Substances Control Act scrutinize organophosphorus compounds for endocrine disruption potential. Houston-area phenol producers supply feedstock to Gulf Coast phosphite manufacturers serving Tier 1 automotive suppliers.
China
Domestic polyolefin production scaling in Jiangsu and Zhejiang provinces concentrates stabilizer consumption through integrated formulation facilities. MIIT industrial chemical standards govern additive purity thresholds for domestic polymer processors. Yangtze River Delta chemical parks host backward-integrated phosphite producers serving electronics-grade polymer specifications.
Germany
REACH substance restrictions compel formulators to substitute legacy phosphite grades with purified variants below 0.1% free phenol content. The EU Green Deal Safe and Sustainable by Design framework incentivizes bio-based phenol feedstock development. Stuttgart-based automotive suppliers negotiate direct annual volume contracts specifying lot traceability and thermal aging certification.
India
BIS certification requirements for imported chemical additives create compliance barriers favoring domestic auxiliary producers. Maharashtra and Gujarat polymer compounders reformulate stabilizer packages to meet automotive OEM specifications. Mumbai-headquartered Sterling Auxiliaries and Krishna Antioxidants leverage local certification advantages to capture import substitution demand.
South Korea
Electronics-grade polymer specifications for connector housings and circuit board substrates command substantial pricing premiums over industrial grades. MFDS chemical safety assessments align with international purity standards for semiconductor packaging materials. Songwon Industrial anchors antioxidant R&D capabilities through dedicated research centers serving regional polyolefin processors.
Tris Nonylphenyl Phosphite Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue electronics-grade certification and modular manufacturing partnerships. The vendor base stratifies across three maturity levels: multinational chemical conglomerates with backward-integrated phenol supply, regional specialists serving domestic certification regimes, and mid-tier modular producers leveraging continuous flow reactor technology. Two dominant competitive moves define current positioning: direct long-term procurement agreements that bypass traditional distributor markups, and capacity repositioning toward higher-purity grades for automotive and electronics specifications.
Among US-based chemical manufacturers, Valtris Specialty Chemicals and Addivant USA LLC occupy positions within the integrated feedstock tier, while Songwon Industrial Co., Ltd. represents the Asia-Pacific R&D-centric archetype. Sterling Auxiliaries Pvt. Ltd. and Krishna Antioxidants Pvt. Ltd. exemplify domestic certification specialists capitalizing on BIS import barriers. These five entities collectively illustrate the geographic and capability fragmentation shaping procurement patterns across automotive, electronics, and packaging end-uses.
| Leading Market Players |
|---|
| Valtris Specialty Chemicals |
| Addivant USA LLC |
| Songwon Industrial Co., Ltd. |
| Sterling Auxiliaries Pvt. Ltd. |
| Krishna Antioxidants Pvt. Ltd. |
| Dover Chemical Corporation |
| Sandhya Group |
| Gulf Stabilizers Industries |
| Galata Chemicals Holding GmbH |
| Others |
Value Chain & Pricing Dynamics
Backward integration into phenol chemistry anchors both supply security and pricing leverage for established phosphite manufacturers serving automotive and electronics-grade specifications. Gulf Coast phenol producers and Yangtze River Delta chemical parks concentrate feedstock control, compressing margins for non-integrated compounders while rewarding captive supply with cost advantages during benzene and propylene volatility.
Pricing Analysis
Warranty-bundled certification packages separate automotive-grade suppliers from commodity sellers, with lot traceability and sub-500 ppm free phenol guarantees commanding substantial premiums over unbundled industrial grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with electronics specifications for connector housings at the apex. Cost compression in standard industrial grades stems from hindered phenol substitution in general-purpose polyethylene. Packaging compounders exhibit highest price sensitivity, while Tier 1 automotive suppliers prioritize thermal aging certification over unit economics.
Supply Chain Analysis
Freight cost differentials between Gulf Coast phenol hubs and Asian formulation centers reshape procurement geography for North American compounders. Supply concentrates in the United States, China, and Germany, with phenol feedstock drawn from crude oil-linked benzene and propylene chains. Single-source vulnerability looms for nonylphenol derivatives tied to specialty phenol producers. Distribution runs through direct manufacturer agreements for specification-grade buyers, bypassing traditional distributor networks that served mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around regulatory compliance capabilities, with REACH, EPA, and BIS purity mandates forcing undercapitalized producers toward exit or acquisition. Margin compression in legacy grades accelerates shakeout among non-integrated compounders lacking certification infrastructure.
For Market Incumbents: Deploy continuous flow reactor technology to modularize capacity expansion in 500-ton increments, matching volatile automotive order books while reducing solvent waste streams. Deepen captive phenol supply through Gulf Coast or Yangtze River Delta integration, insulating margins from benzene-propylene volatility. Hindered phenol substitution from Songwon and BASF threatens general-purpose polyethylene share; defend position through automotive certification lock-in exceeding 5,000-hour thermal aging protocols. For New Entrants and Emerging Players: E-procurement platforms for research laboratories and small-volume compounders offer the lowest barrier to initial revenue, bypassing entrenched distributor relationships. Target Southeast Asia tire manufacturing in Thailand and Vietnam, where rubber compounding reformulation creates specification openings absent entrenched supplier relationships. Electronics-grade phosphite for connector housings commands the most penetrable premium tier, with 40-60% pricing spreads over industrial grades and fewer qualified competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-tier modular producers with continuous reactor technology and pending automotive certification qualifications. Long-term viability hinges on regulatory compliance infrastructure spanning EPA, REACH, and BIS regimes, favoring targets with validated sub-500 ppm detection capabilities and established lot traceability systems. Watch for EPA Toxic Substances Control Act endocrine disruption findings as the critical inflection signal that would accelerate alternative phosphite architecture qualification and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Feedstock | Gulf Coast and Yangtze River Delta captive supply secures margin insulation against benzene-propylene volatility. |
| Continuous Flow Reactor Deployment | Modular 500-ton capacity increments match volatile automotive order books while tightening quality control. |
| Automotive Certification Investment | Sub-500 ppm free phenol validation unlocks Tier 1 supplier direct agreements bypassing distributor markups. |
| Electronics-Grade Purity Qualification | Connector housing specifications command 40-60% pricing premiums over standard industrial grades. |
| Long-Term Supply Agreement Negotiation | Annual volume contracts with lot traceability replace traditional 15-20% distributor channel structures. |
Study Parameters
Trade databases, chemical industry association publications, and SEC regulatory filings formed the secondary backbone, cross-referenced with customs data on phosphite antioxidant import flows. Primary interviews with polymer plant managers, automotive procurement leads at Tier 1 suppliers, distribution channel partners, and technical R&D directors at stabilizer formulators validated demand assumptions and pricing dynamics. Bottom-up and top-down triangulation reconciled volume estimates from production capacity announcements with consumption patterns across polyolefin processing clusters.
Bottom-up modeling aggregated segment-level consumption across plastics, rubber, coatings, and adhesives applications, while top-down validation checked aggregate figures against regional polymer production statistics. Segmentation dimensions included product purity tier, end-use severity classification, and regional regulatory compliance cluster. CAGRs derived from fitted growth curves incorporating automotive production forecasts, polymer capacity expansion timelines, and regulatory phase-in schedules across the analysis window. Feedstock cost indices and certification investment cycles served as industry-specific forecast inputs.
The model holds under stable regulatory phase-in schedules; deviation in EPA endocrine disruption findings or REACH substance restriction acceleration would shift demand toward alternative antioxidant architectures. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Sodium Citrate Dihydrate Market
Additives
Global Pour Point Depressant Market
Additives
Tackifier Market
Additives
Diamino Stilbene Disulfonic Acid (DASDA) Market
Additives
Surface Modifiers Market
Additives
Lactic Acid Ester Market
Additives
Dispersing Agents Market
Additives
Tire Additives Market
Additives
Low Volatile Organic Compounds Coating Additives Market
Additives
Sodium Caprylate Market
Additives
Refinery Process Additives Market
Additives
Micronized Powder Market
Additives
Global Butyric Acid Derivatives Market
Additives
Oilfield Drilling Fluid Additive Market
Additives
Antimicrobial Additives Market
Additives
Global Scale Inhibitors Market