
 Self-Healing Hydrogels Market | 2026-2036
Self-Healing Hydrogels Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Healing Hydrogels Market Analytics
REACH is expanding the cost-of-entry calculus for hydrogel manufacturers targeting European medical applications. BASF SE leverages its polymer science heritage to sustain leadership in synthetic hydrogel precursors. Johnson & Johnson anchors its position through vertical integration from raw material synthesis to finished wound care products. Evonik Industries AG specializes in high-purity crosslinking chemistries that differentiate its supply relationships with device makers.
Self-healing hydrogels are three-dimensional polymer networks capable of autonomous structural recovery after mechanical damage, typically formed through reversible covalent bonds, ionic crosslinks, or dynamic supramolecular interactions that restore integrity within seconds to hours depending on formulation chemistry. These materials serve primarily as responsive matrices for controlled substance release, tissue scaffolding, and adaptive interfaces in biomedical and industrial systems. Natural product types currently occupy the largest revenue share due to established collagen and alginate supply chains, while bioengineered variants represent the fastest-expanding category as synthetic biology platforms reduce production costs. Soft robotics applications are concentrating margin pools because performance specifications justify premium pricing for strain-recovery and self-sensing functionalities.
The FDA maintains stringent biocompatibility and sterility requirements under ISO 10993 guidelines that govern hydrogel-based wound healing and drug delivery devices entering US commerce. EMA's Medical Device Regulation framework in Europe mandates clinical evidence thresholds that favor manufacturers with established quality management systems and notified body relationships. China's NMPA has accelerated review pathways for innovative biomaterials under its priority review channels, reshaping competitive timelines for multinational entrants. Stakeholders must monitor evolving reimbursement codes for advanced wound care in key markets to align R&D portfolios with payer willingness to cover premium hydrogel therapies.
Market Dynamics
Reversible crosslinking chemistry platforms are compressing product development cycles and forcing incumbent suppliers to rebuild formulation pipelines around autonomous healing kinetics rather than static mechanical properties.
Growth Catalysts
- Wound care protocol modernization:Hospital systems in Germany are integrating self-healing hydrogel dressings into standardized post-surgical recovery pathways, creating pull-through demand for advanced materials.
- ISO 10993 harmonization:Convergent biocompatibility testing frameworks across FDA and EMA jurisdictions are reducing duplicate certification costs for multi-regional suppliers.
- Dynamic supramolecular chemistry:Host-guest interaction platforms enable room-temperature self-healing without external stimuli, opening deployment in temperature-sensitive biological environments.
Market Restraints
- High-purity acrylic monomer supply:Semiconductor industry demand for photoresist-grade acrylates is squeezing hydrogel precursor availability and inflating input costs.
- EMA MDR clinical evidence thresholds:Implantable hydrogel classifications now require prospective human data that extends regulatory timelines beyond synthetic material substitution cycles.
- Silicone elastomer substitution:Mature silicone supply chains and established reimbursement codes for traditional wound dressings create switching friction for novel hydrogel entrants.
Strategic Opportunities
- Soft robotics actuator integration:Convergence of self-healing hydrogels with stretchable electronics is absorbing R&D investment from defense and industrial automation procurement offices.
- China NMPA priority review channels:Accelerated biomaterial approval pathways are compressing competitive entry timelines for innovative crosslinking platforms.
- Veterinary medicine extension:Companion animal surgical applications represent an underpenetrated vertical with lower regulatory barriers and faster clinical validation cycles.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise combining supramolecular design with biocompatibility engineering concentrates in academic institutions rather than industrial R&D centers.
- Notified body capacity constraints:EMA MDR implementation has created bottlenecks in conformity assessment timelines that delay commercial launches regardless of technical readiness.
- Batch-to-batch rheology variance:Dynamic crosslinking kinetics introduce manufacturing control complexities that exceed legacy quality management system capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Healing Hydrogels Market |
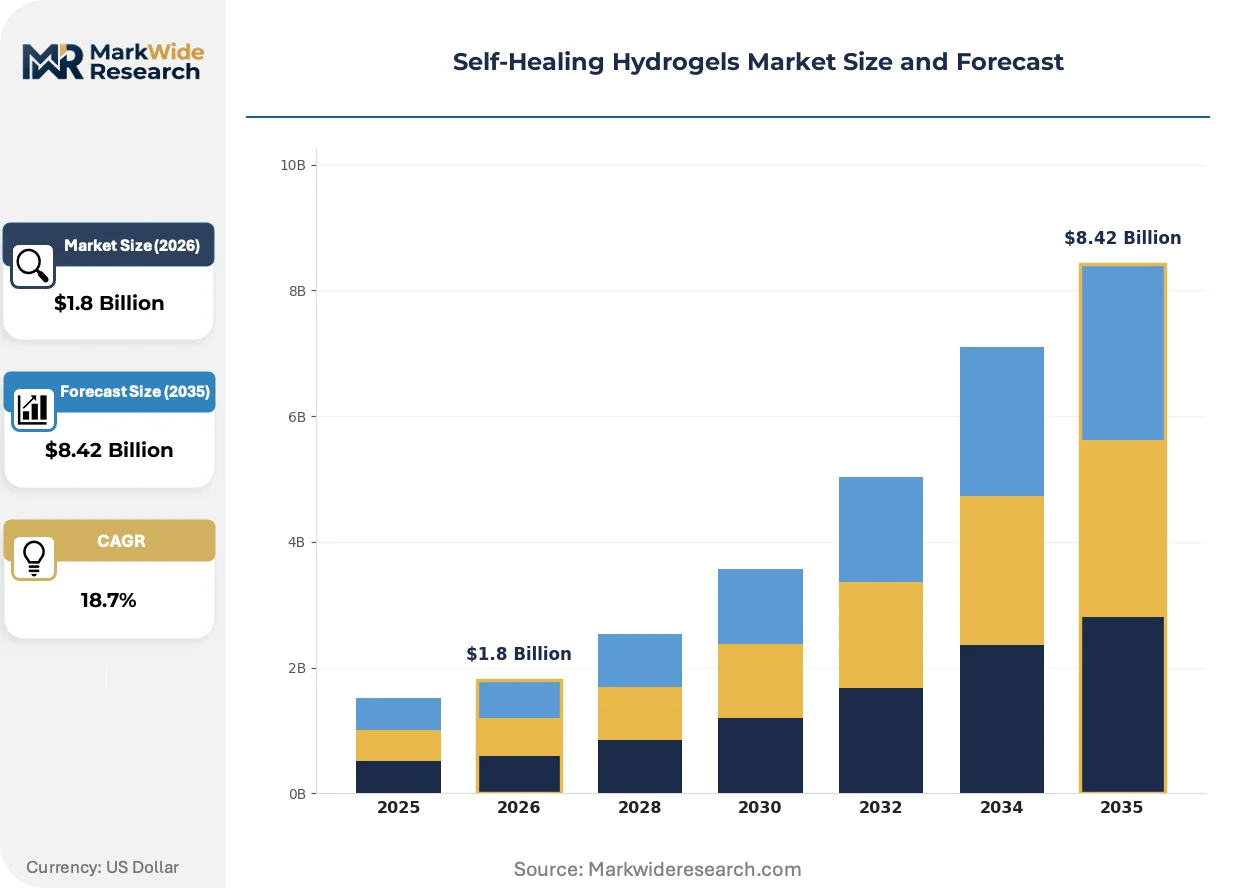
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Hybrid, Bioengineered End User: Medical, Cosmetic, Agricultural, Industrial Technology: 3D Bioprinting, Sol-Gel Process, Crosslinking, Electrospinning Application: Wound Healing, Drug Delivery, Tissue Engineering, Soft Robotics |
| Companies Covered | Johnson & Johnson, 3M Company, Cardinal Health, BASF SE, Evonik Industries AG, Advanced Medical Solutions Group PLC, Coloplast, DSM Biomedical, Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Healing Hydrogels Market Evolving Landscape
Formulation science is pivoting from passive moisture retention to active mechanical responsiveness, with reversible bond architectures enabling entirely new device categories that adapt to physiological stress cycles.
Schiff-base and boronate ester dynamic covalent networks are absorbing research investment from orthopedic and ophthalmic device manufacturers seeking materials that withstand repetitive strain without permanent deformation. Knee implant coating applications are advancing fastest, with several European notified bodies now accepting fatigue-testing protocols that incorporate self-healing recovery metrics. The structural consequence is compression of traditional static-hydrogel market positions in load-bearing applications.
REACH substance restriction expansions are forcing reformulation of conventional crosslinking agents, with ECHA candidate list updates targeting specific boron-containing compounds prevalent in self-healing hydrogel synthesis. Industrial consequence includes accelerated migration toward bio-orthogonal click chemistry platforms that avoid regulatory scrutiny. Medical device suppliers with pre-validated alternative crosslinker portfolios are capturing notified body attention and compressing competitor submission timelines.
Hospital procurement committees are consolidating vendor relationships around full-spectrum wound care portfolios rather than standalone advanced dressings, bundling self-healing hydrogels with negative pressure therapy and antimicrobial silver systems. This concentration is displacing single-product suppliers and rewarding manufacturers with integrated device platforms. Germany's university hospital networks are most advanced in this consolidation, with centralized purchasing bodies demanding outcome guarantees that tie material performance to reduced readmission metrics.
Self-Healing Hydrogels Market Segmentation
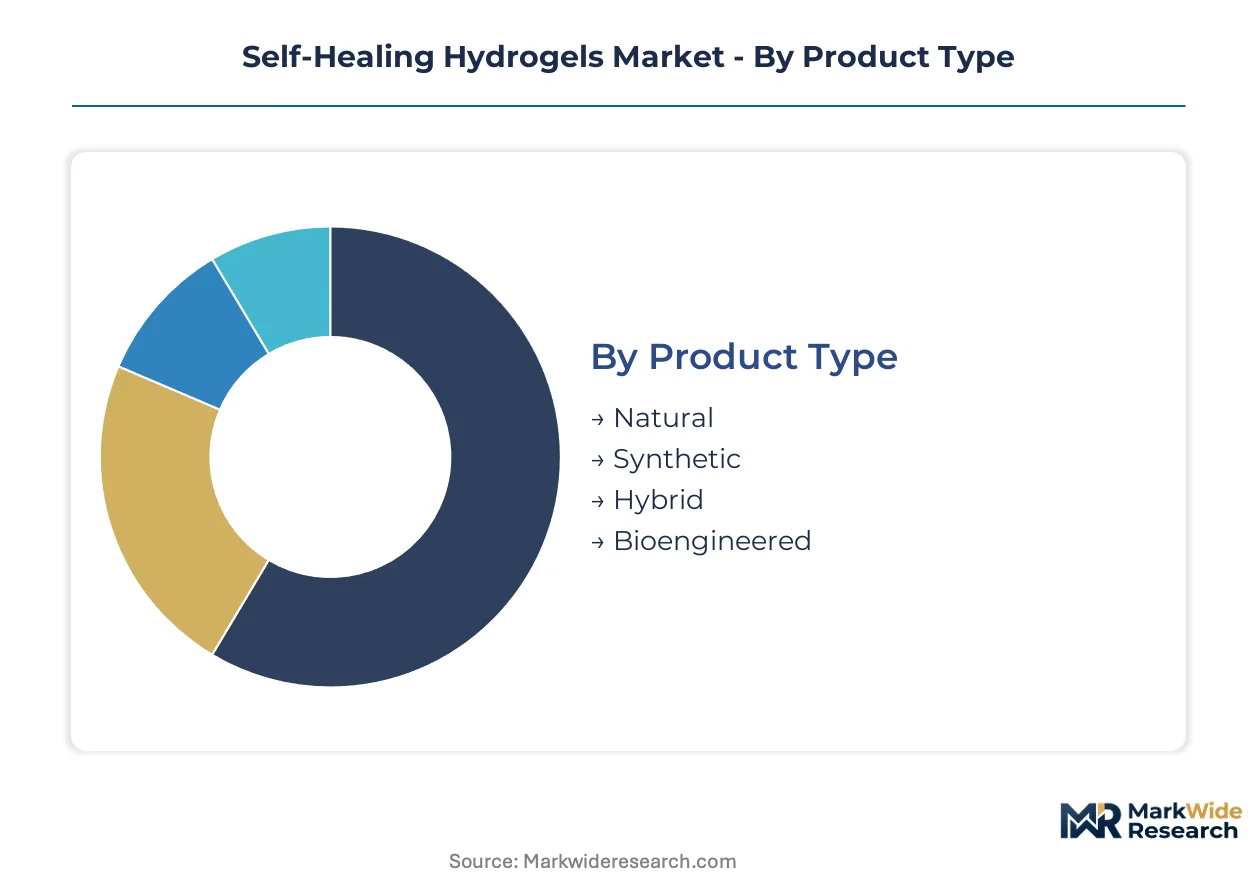
Self-healing hydrogels span heterogeneous technical specifications and regulatory pathways that fragment competitive positioning across value chains. Segmentation clarity determines which formulation platforms align with specific certification burdens and end-use margin pools.
Product Type:
EMA MDR Class III implantable classifications apply differentially across product categories, with natural and bioengineered variants facing distinct biocompatibility evidence requirements versus synthetic platforms.
- Natural:Collagen and alginate-based networks leverage established supply chains from marine and mammalian sources. Hospital procurement in Germany concentrates demand here for post-surgical dressings where clinical familiarity reduces adoption friction.
- Synthetic:Acrylic and polyethylene glycol architectures deliver tunable mechanical properties through controlled polymerization. Semiconductor industry competition for photoresist-grade acrylates is constraining precursor availability and inflating input costs for manufacturers dependent on petrochemical feedstocks.
- Hybrid:Combines natural biocompatibility with synthetic tunability through interpenetrating network designs.
- Bioengineered:Recombinant protein and synthetic biology platforms enable custom peptide sequences with autonomous healing kinetics.
Leading the category by volume: Natural. Growing fastest: Bioengineered.
End User:
Cost tier stratification separates premium medical applications from volume-driven industrial segments, with reimbursement codes determining viable pricing floors.
- Medical:FDA ISO 10993 and EMA MDR frameworks govern wound healing, drug delivery, and implantable devices. Germany's university hospital networks are consolidating vendor relationships around full-spectrum portfolios that bundle hydrogels with negative pressure therapy systems.
- Cosmetic:Dermal filler and skincare applications operate under lighter regulatory burdens with faster formulation turnover.
- Agricultural:Soil moisture retention and controlled-release fertilizer matrices compete on cost against established polymer alternatives.
- Industrial:Sealant and coating applications prioritize mechanical recovery specifications over biocompatibility.
Dominating revenue contribution: Medical. Expanding most quickly: Cosmetic.
Technology:
Manufacturing scalability varies dramatically across process platforms, with some methods requiring capital-intensive equipment that favors integrated producers.
- 3D Bioprinting:Layer-by-layer deposition enables patient-specific scaffold geometries with embedded vascular channels. Research investment from defense procurement offices is accelerating convergence with stretchable electronics for soft robotics actuators.
- Sol-Gel Process:Room-temperature synthesis routes suit temperature-sensitive biological environments and reduce energy costs.
- Crosslinking:Dynamic covalent and supramolecular bond architectures determine autonomous healing kinetics and batch-to-batch rheology consistency.
- Electrospinning:Produces fibrous hydrogel matrices with high surface-area-to-volume ratios for rapid fluid absorption.
Widest deployment currently: Crosslinking. Steepest expansion trajectory: 3D Bioprinting.
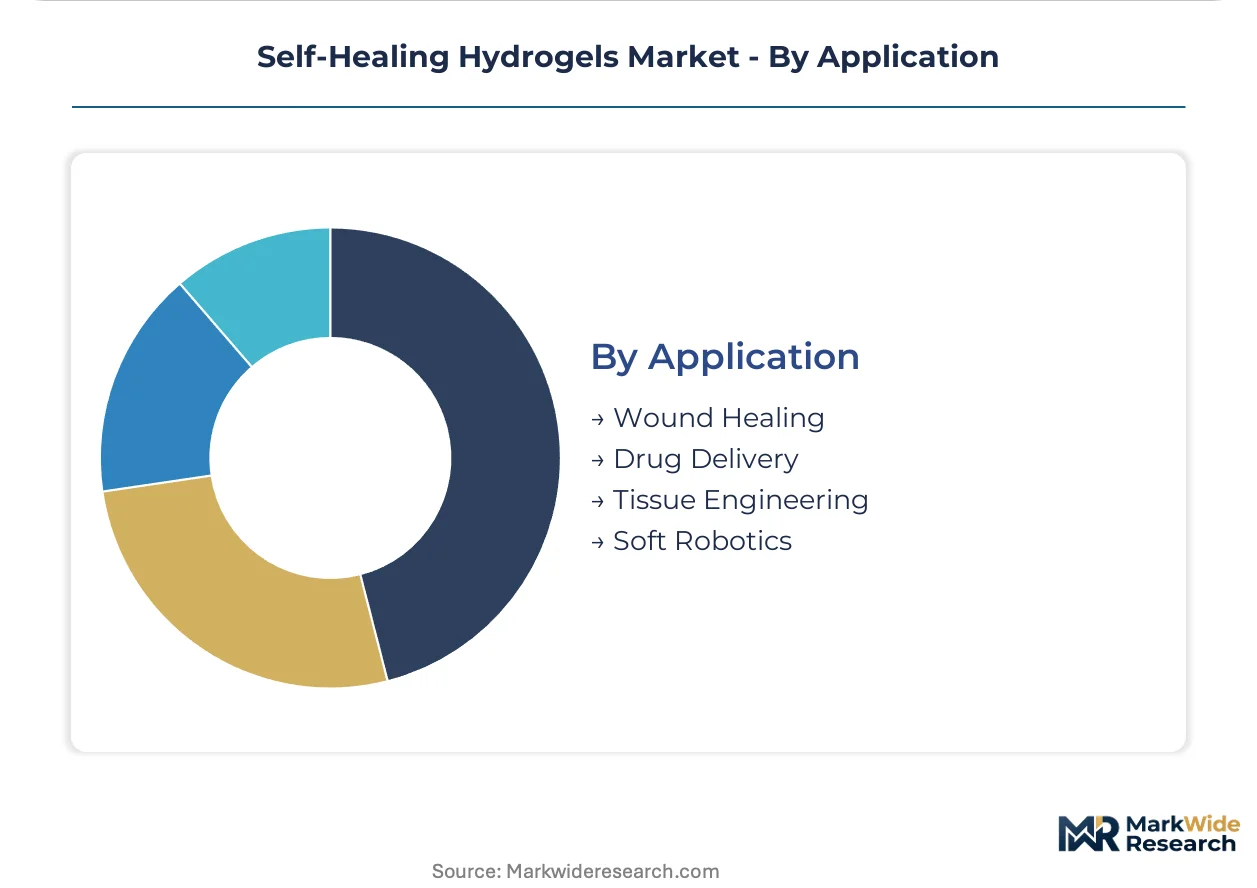
Application:
Customer type fragmentation separates acute care settings with outcome-based procurement from research-stage segments with project-based funding.
- Wound Healing:Post-surgical and chronic ulcer dressings integrate into standardized recovery pathways. Hospital systems in Germany are demanding performance guarantees tied to reduced readmission metrics.
- Drug Delivery:Responsive matrices enable controlled release kinetics that adapt to physiological conditions.
- Tissue Engineering:Scaffolds for cartilage, bone, and organ regeneration require extended biocompatibility validation timelines.
- Soft Robotics:Strain-recovery and self-sensing functionalities command premium pricing from defense and industrial automation sectors.
Capturing largest revenue share: Wound Healing. Gaining share fastest: Soft Robotics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's MedTech corridor operates as a tax-advantaged concentration zone where university hospital networks and polymer research institutes cluster within regulatory reach of EMA headquarters.
Germany
University hospital procurement committees in Berlin and Munich bundle self-healing hydrogels with negative pressure therapy systems under outcome-based contracts tied to readmission metrics. EMA MDR implementation has tightened biocompatibility evidence thresholds for implantable classifications. The Baden-Württemberg polymer science belt anchors BASF SE and Evonik Industries AG manufacturing footprints serving device makers across the Rhine-Ruhr medical technology corridor.
United States
FDA ISO 10993 guidelines govern wound healing and drug delivery devices entering US commerce, with 510(k) pathways absorbing reformulated crosslinking chemistries that avoid REACH-restricted boron compounds. Massachusetts and California host the largest concentration of 3D bioprinting startups converging hydrogels with stretchable electronics for defense procurement. The NIH accelerates tissue engineering validation through its National Institute of Biomedical Imaging and Bioengineering grant programs.
China
NMPA priority review channels compress approval timelines for innovative biomaterials, reshaping competitive entry for multinational hydrogel suppliers targeting Shanghai and Beijing hospital systems. The Yangtze River Delta concentration of synthetic biology platforms reduces production costs for recombinant protein hydrogels. Shenzhen's soft robotics industrial park absorbs R&D investment from automation procurement offices seeking strain-recovery functionalities.
Japan
METI funding for advanced wound care materials supports domestic hydrogel development at Osaka and Nagoya medical device clusters. PMDA harmonization with FDA biocompatibility frameworks reduces duplicate certification burdens for suppliers serving both markets. The Kansai region's polymer engineering heritage sustains specialist manufacturers targeting orthopedic coating applications with fatigue-testing protocols incorporating self-healing recovery metrics.
Switzerland
Swissmedic's notified body relationships attract manufacturers seeking streamlined CE marking pathways for Class III implantable hydrogels. The Basel pharmaceutical cluster drives demand for drug delivery matrices with controlled release kinetics. Zurich's materials science institutes partner with industrial automation firms developing soft robotics actuators that command premium pricing for autonomous healing specifications.
Self-Healing Hydrogels Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation platforms, with market structure tiering by vertical scope and regulatory validation depth. Tier-one positions concentrate among suppliers with captive polymer precursor production and established notified body relationships. Three archetypes dominate: integrated healthcare conglomerates with wound care portfolios, specialty chemical suppliers with crosslinking expertise, and device-focused manufacturers with hospital procurement access. Competitive moves center on backward integration into high-purity monomer supply and strategic partnerships with 3D bioprinting platform developers.
Among diversified healthcare conglomerates, Johnson & Johnson anchors a position spanning raw material synthesis through finished wound care products. BASF SE represents the specialty chemical archetype with polymer science heritage in synthetic hydrogel precursors. Evonik Industries AG exemplifies the high-purity crosslinking specialist tier, differentiating through supply relationships with device makers seeking EMA MDR-compliant formulations.
| Leading Market Players |
|---|
| Johnson & Johnson |
| 3M Company |
| Cardinal Health |
| BASF SE |
| Evonik Industries AG |
| Advanced Medical Solutions Group PLC |
| Coloplast |
| DSM Biomedical |
| Smith & Nephew |
| Others |
Value Network & Pricing Analysis
Photoresist-grade acrylate spot pricing cascades through hydrogel precursor supply chains into three-tier pricing stratification across premium medical-grade, standard industrial-grade, and economy agricultural-grade tiers. Germany's hospital procurement committees leverage volume concentration to extract performance guarantees that compress margins for suppliers lacking captive monomer production.
Pricing Analysis
Lead-time premiums reward suppliers with qualified notified body relationships and validated crosslinker portfolios, while spot inventory discounts attract price-sensitive agricultural buyers. Price differentiation hinges on EMA MDR certification tier and volume scale, with Class III implantable classifications commanding substantial premiums over cosmetic-grade alternatives. Pricing pressure stems from semiconductor industry competition for high-purity acrylic monomers, squeezing hydrogel manufacturer margins. Agricultural end-users exhibit highest price sensitivity, while soft robotics defense contractors demonstrate lowest sensitivity due to performance-specification premiums.
Supply Chain Analysis
ISO 10993 and REACH qualification requirements gate supplier entry, concentrating upstream supply among Germany, China, and the United States for polymer precursor manufacturing. Raw material dependencies center on photoresist-grade acrylates, recombinant protein feedstocks, and boron-containing crosslinking agents facing ECHA restriction pressure. Single-source vulnerability for high-purity monomers from semiconductor-qualified suppliers poses structural risk. Distribution runs through medical device OEMs and hospital procurement committees in Germany's university hospital networks, with direct-to-researcher channels serving 3D bioprinting platform developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The self-healing hydrogels sector sits at a technology-transition inflection as dynamic supramolecular chemistry displaces static crosslinking platforms. Reversible bond architectures are compressing legacy formulation positions in load-bearing medical applications.
For Market Incumbents: Anchor market position through backward integration into high-purity monomer supply chains and accelerated migration toward bio-orthogonal click chemistry platforms that preempt REACH restrictions. Defend against silicone elastomer substitution by embedding self-healing hydrogels into full-spectrum wound care portfolios with negative pressure therapy bundling. Prioritize notified body relationship investment to compress conformity assessment timelines. For New Entrants and Emerging Players: Launch via veterinary medicine distribution partnerships that bypass EMA MDR clinical evidence thresholds and accelerate revenue generation. Target China's NMPA priority review channels for recombinant protein hydrogels, where synthetic biology cost advantages concentrate. Penetrate soft robotics actuator segments through defense procurement relationships that justify premium pricing for strain-recovery specifications. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty crosslinking chemistry specialists with pre-validated alternative portfolios in Germany's Baden-Württemberg polymer belt. Long-term viability hinges on formulation platforms combining biocompatibility engineering with supramolecular design expertise. Watch for batch-to-batch rheology variance resolution as the signal indicating manufacturing scalability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive acrylate production insulates margins from semiconductor demand competition. |
| Bio-Orthogonal Click Chemistry Migration | Preemptive reformulation avoids ECHA boron compound restrictions and accelerates CE marking. |
| Hospital System Partnership Consolidation | Bundled wound care portfolios with outcome guarantees secure procurement committee preference. |
| 3D Bioprinting Platform Convergence | Integration with stretchable electronics opens defense soft robotics procurement channels. |
| NMPA Priority Review Channel Entry | Accelerated biomaterial approval compresses competitive timelines in Shanghai hospital systems. |
Research Methodology
Document review covered EMA MDR implementation guidance, FDA ISO 10993 biocompatibility frameworks, and REACH substance restriction updates, complemented by interviews with polymer chemists at German university research institutes, biomedical engineers at notified bodies, hospital procurement managers in Berlin and Munich, and regulatory affairs leads at medical device OEMs. Secondary sources included ECHA candidate list publications, NMPA priority review pathway documentation, and customs trade data for hydrogel precursor imports. Bottom-up formulation platform demand estimates were triangulated against top-down medical device market sizing.
Cross-reference between historical crosslinking chemistry adoption curves and expert panel input on supramolecular platform readiness shaped the analytical framework across the analysis window. Segmentation dimensions modeled included product type (natural, synthetic, hybrid, bioengineered), end user (medical, cosmetic, agricultural, industrial), technology (3D bioprinting, sol-gel, crosslinking, electrospinning), and application (wound healing, drug delivery, tissue engineering, soft robotics). CAGRs were derived from elasticity-adjusted demand projections incorporating reimbursement code evolution and regulatory timeline compression.
REACH substance list expansion, NMPA review pathway acceleration, and semiconductor industry demand surges for photoresist-grade acrylates are the dominant revision risks warranting forecast reassessment. Forecasts reflect assumptions on crosslinking chemistry migration timelines and notified body capacity normalization. A model refresh is warranted upon material change in EMA MDR clinical evidence threshold enforcement or batch-to-batch rheology control technology breakthrough.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Global Biomaterials Market
Biomaterials
Chitosan-Based Biomaterials Market
Biomaterials
Atelocollagen Market
Biomaterials
Europe Collagen Market
Biomaterials
Biomimetic Materials Market
Biomaterials
Bone Substitutes Market
Biomaterials
Global Bioactive Materials Market
Biomaterials
Hydrogel Face Mask Market
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Chitosan Films Market
Biomaterials
Heparin Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Global Medical Grade Collagen Market
Biomaterials
Spine Surgery Gels Market
Biomaterials
Global Collagen and HA Based Biomaterial Market