

Emulsifiers In Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
Emulsifiers In Personal Care Market Insights
The skin care vertical is repositioning emulsifier demand toward high-performance, sensorial formulations that stabilize active ingredients across varied pH ranges. BASF SE leverages its integrated petrochemical and biotechnology platforms to supply both synthetic and bio-based emulsifier portfolios. Evonik Industries differentiates through silicone-organic hybrid emulsifiers targeting premium anti-aging serums. Croda International anchors its position with lipid-based emulsifiers derived from botanical sources.
Emulsifiers in personal care are surface-active agents that reduce interfacial tension between immiscible phases, typically functioning at concentrations of one to ten percent to create stable oil-in-water or water-in-oil dispersions with controlled rheology and skin feel. Natural Derived emulsifiers command expanding volume as formulators replace PEG-based surfactants to meet clean-label requirements, while non-ionic variants sustain dominant share due to broad compatibility across acidic and alkaline systems. Synthetic emulsifiers retain cost advantages in mass-market lotions and bath products where margin compression limits ingredient spending.
The EU REACH regulation restricts certain ethoxylated surfactants, while the FDA governs cosmetic ingredient safety through voluntary reporting systems and color additive certifications in the United States. SEPPIC navigates these frameworks with RSPO-certified emulsifiers, and Gattefossé specializes in pharmaceutical-grade lipid excipients that satisfy both cosmetic and dermatological standards. Stakeholders must monitor evolving biodegradability mandates and patchwork state-level disclosure laws that fragment compliance requirements across North American and European supply chains.
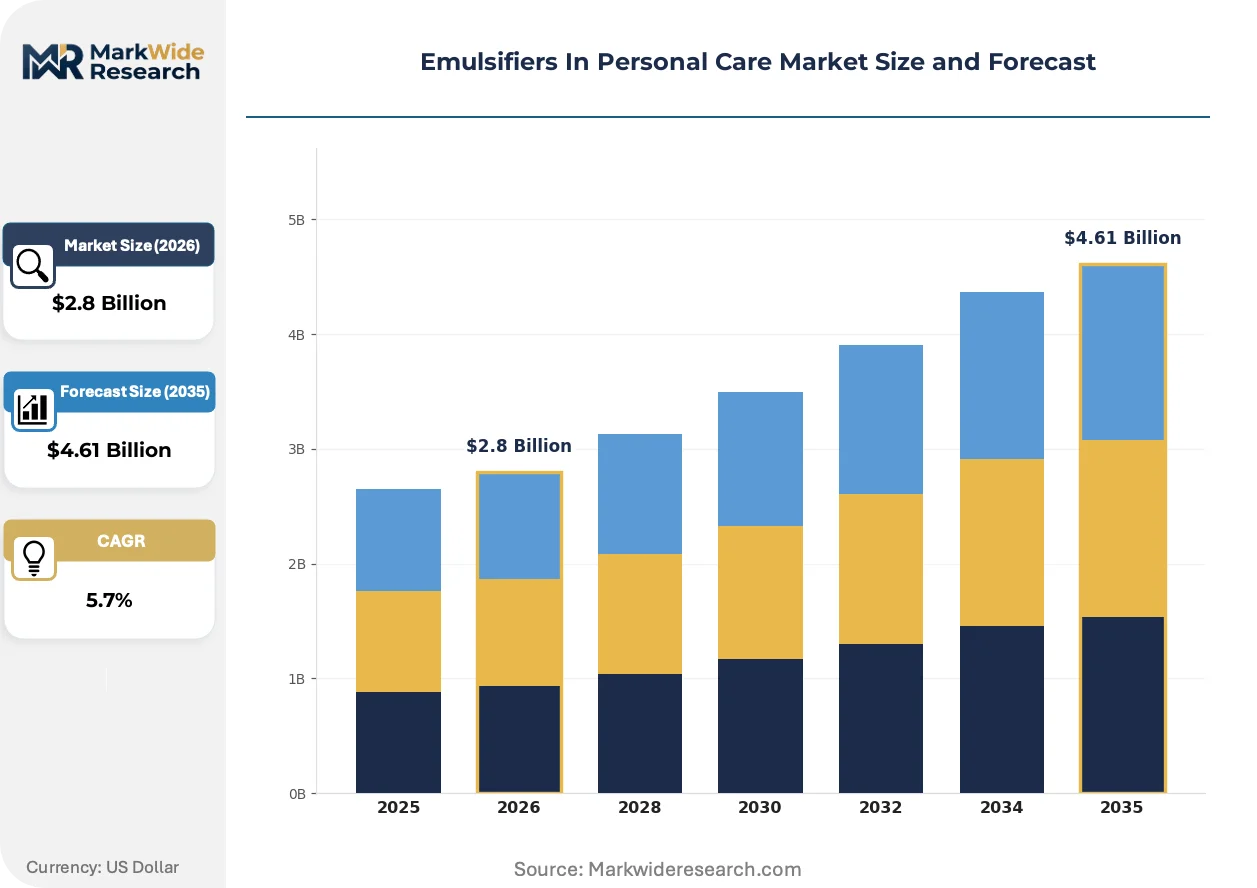
Market Dynamics
Clean-label reformulation pressure from European consumers and tightening biodegradability mandates under EU REACH are forcing personal care manufacturers to requalify entire emulsifier supply chains, compressing procurement timelines and elevating bio-based certification requirements.
Growth Catalysts
- EU REACH ethoxylated surfactant restrictions:Formulators accelerate substitution of PEG-based emulsifiers with plant-derived alternatives to maintain market access across Germany, France, and the Netherlands.
- Active ingredient stabilization demand:Skin care brands require emulsifiers that maintain efficacy of retinoids and vitamin C across acidic pH ranges, expanding specialty chemical procurement.
- Ludwigshafen-Frankfurt supply cluster:Concentrated specialty chemical production in these German hubs reduces logistics costs and technical service response times for European personal care manufacturers.
Market Restraints
- Botanical lipid input cost volatility:Weather-dependent supply of shea butter and jojoba oil creates margin pressure on natural-derived emulsifier producers.
- Petrochemical feedstock concentration:Synthetic emulsifier supply chains remain tethered to refinery output in the US Gulf Coast and Middle East, exposing buyers to energy price swings.
- Biodegradability testing timelines:OECD 301B and 301F aquatic toxicity protocols extend new ingredient qualification by 18-24 months, delaying product launches.
Strategic Opportunities
- Pharmaceutical-grade lipid excipient convergence:Cosmetic and dermatological formulation standards are merging, enabling suppliers to serve dual end-uses with single SKUs.
- Silicone-organic hybrid emulsifier white space:Premium anti-aging serum brands seek sensorial performance without pure silicone regulatory baggage.
- RSPO-certified mass-market penetration:Palm-derived emulsifiers with segregated supply chain documentation command price premiums in clean-label bath and body products.
Industry Challenges
- Formulation chemist scarcity:Personal care manufacturers compete with pharmaceutical and food sectors for talent capable of navigating complex emulsion stability and regulatory documentation.
- Legacy PEG-based inventory stranding:Brands holding multi-year synthetic emulsifier contracts face write-downs as clean-label commitments accelerate ingredient obsolescence.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emulsifiers In Personal Care Market Trends and Innovations
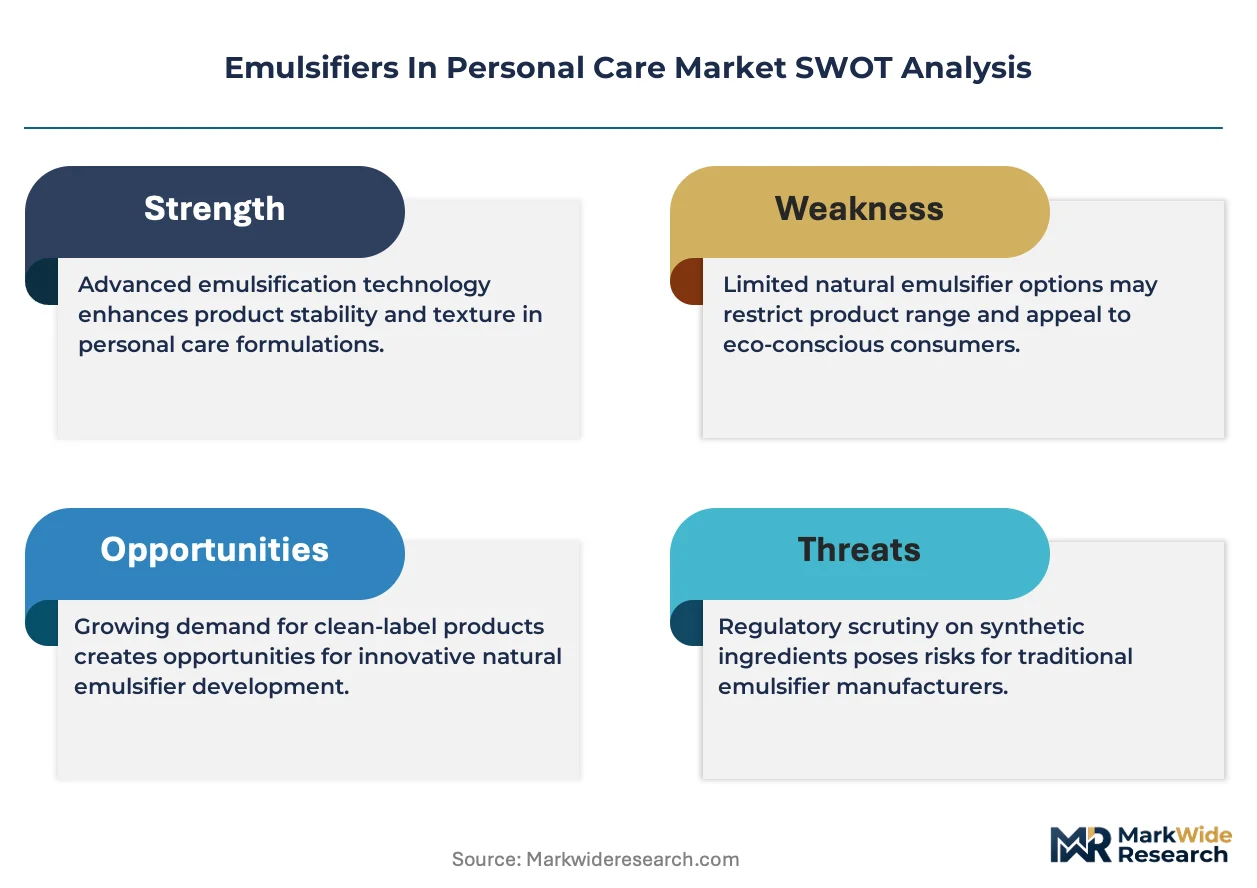
Biotechnology-derived emulsifiers and hybrid silicone-organic architectures are displacing conventional petrochemical surfactants, while regulatory fragmentation across North American state disclosure laws and European biodegradability mandates complicates global formulation strategies.
Enzymatic esterification of plant lipids is consolidating technical and commercial viability for bio-based emulsifiers. Specialty chemical producers in Germany and the Netherlands scale enzymatic processes to replace solvent-based synthesis. Skin care formulators adopt these ingredients at accelerating rates to satisfy RSPO and COSMOS certification requirements. The technology is consolidating cost parity with synthetic alternatives in high-volume lotion applications.
REACH Annex XVII restrictions on certain ethoxylated surfactants are tightening compliance scope for personal care manufacturers selling into the European Economic Area. ECHA substance evaluation processes now explicitly screen emulsifiers for aquatic persistence and endocrine disruption potential. Mid-sized contract manufacturers in Italy and Spain face disproportionate reformulation burdens due to limited in-house toxicology resources.
Beauty brands are unbundling ingredient sourcing from finished good manufacturing, creating direct procurement relationships with specialty chemical suppliers. Traditional toll manufacturers lose intermediation value as skin care brands conduct their own emulsifier qualification and stability testing. This pattern concentrates most visibly in France and the United Kingdom, where direct-to-consumer beauty brands maintain internal formulation capabilities and bypass conventional supply tiers.
Emulsifiers In Personal Care Market Segmentation
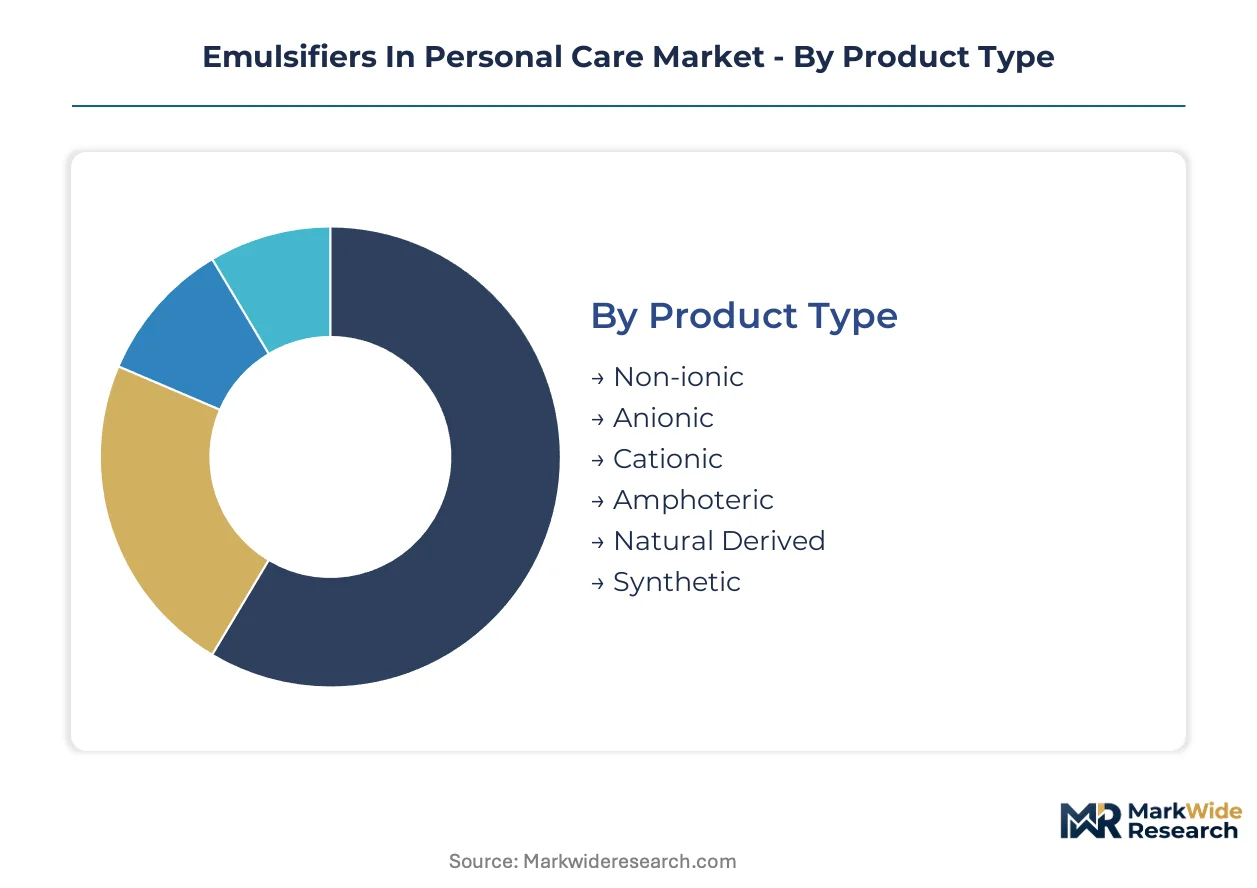
Emulsifier procurement strategies diverge sharply across segment boundaries, with certification requirements and formulation complexity dictating supplier selection criteria. Manufacturers optimize inventory by mapping specific emulsifier chemistries to end-use performance standards and regulatory exposure.
Product Type:
RSPO and COSMOS certifications impose differentiated compliance burdens across emulsifier chemistries, with natural-derived variants facing the most extensive documentation requirements.
- Non-ionic:Polyglyceryl esters and sorbitan derivatives deliver broad pH stability from 3 to 11, making them indispensable for retinol and vitamin C formulations in German skin care manufacturing. Their compatibility with both ionic and non-ionic actives sustains procurement dominance despite higher unit costs versus anionic alternatives.
- Natural Derived:Lecithin, saponins, and plant-based glycerides require batch-level traceability documentation for EU REACH compliance, with enzymatic esterification processes now achieving cost parity in high-volume lotion applications. French clean-label brands prioritize these ingredients for sensorial positioning in premium facial care.
- Synthetic:Petrochemical-based ethoxylates and fatty acid esters carry REACH Annex XVII restrictions on certain ethoxylated surfactants, limiting market access for legacy formulations.
- Anionic:Sulfosuccinates and alkyl ether sulfates excel in foaming applications but face pH compatibility constraints in acidic active delivery systems.
- Cationic:Quaternary ammonium compounds provide conditioning benefits in hair care rinse-off products with specific regulatory thresholds for leave-on applications.
- Amphoteric:Betaine derivatives offer mildness profiles suitable for baby care and sensitive skin formulations with reduced irritation potential.
Non-ionic emulsifiers sit at the top of the volume ranking, with natural derived variants climbing the fastest.
Application:
Margin structures and technical service intensity vary dramatically across personal care applications, with skin care commanding premium pricing for stability expertise.
- Skin Care:Anti-aging serums and moisturizers require emulsifiers that maintain active ingredient efficacy across temperature cycling and oxidative stress, driving specialty chemical procurement in Ludwigshafen and Frankfurt production clusters. Formulators specify low-HLB systems for water-in-oil architectures in overnight repair products.
- Sun Care:UV filter compatibility and photostabilization demands concentrate procurement among suppliers with inorganic-organic hybrid expertise, particularly for benzophenone-free formulations meeting Hawaii and Palau reef-safe mandates.
- Hair Care:Conditioning emulsifiers balance deposition efficiency with rinse-off performance in shampoo and treatment applications.
- Oral Care:Flavor compatibility and foaming control dominate emulsifier selection for toothpaste and mouthwash formulations.
- Makeup:Color dispersion and wear longevity requirements drive silicone-organic hybrid adoption in foundation and concealer products.
- Bath Products:Cost-optimized synthetic emulsifiers sustain mass-market positioning where clean-label premiums face consumer price resistance.
Skin care generates the highest value per kilogram, though sun care exhibits the steepest expansion trajectory on regulatory reformulation cycles.
End User:
Direct procurement relationships are restructuring traditional supply tiers, with formulation capability concentration determining intermediation value.
- Personal Care Manufacturers:Integrated beauty brands in France and the United Kingdom conduct independent emulsifier qualification and stability testing, bypassing toll manufacturers to secure supply chain transparency. Internal toxicology resources enable rapid response to ECHA substance evaluation updates.
- Contract Manufacturers:Mid-sized Italian and Spanish operators face disproportionate reformulation burdens due to limited in-house regulatory expertise, creating vulnerability to REACH compliance timeline compression.
- Online Retailers:Direct-to-consumer brands with lean organizational structures rely on pre-qualified ingredient libraries from specialty chemical distributors.
- Professional Salons:Back-bar product specifications prioritize performance over certification documentation in treatment-grade formulations.
- Retailers:Private label programs demand cost-engineered emulsifier systems with basic stability guarantees.
- Drugstores:Mass-market distribution channels emphasize inventory turnover and shelf-life predictability in procurement criteria.
Personal care manufacturers command the largest procurement volumes, while online retailers are gaining share fastest on direct-to-consumer brand proliferation.
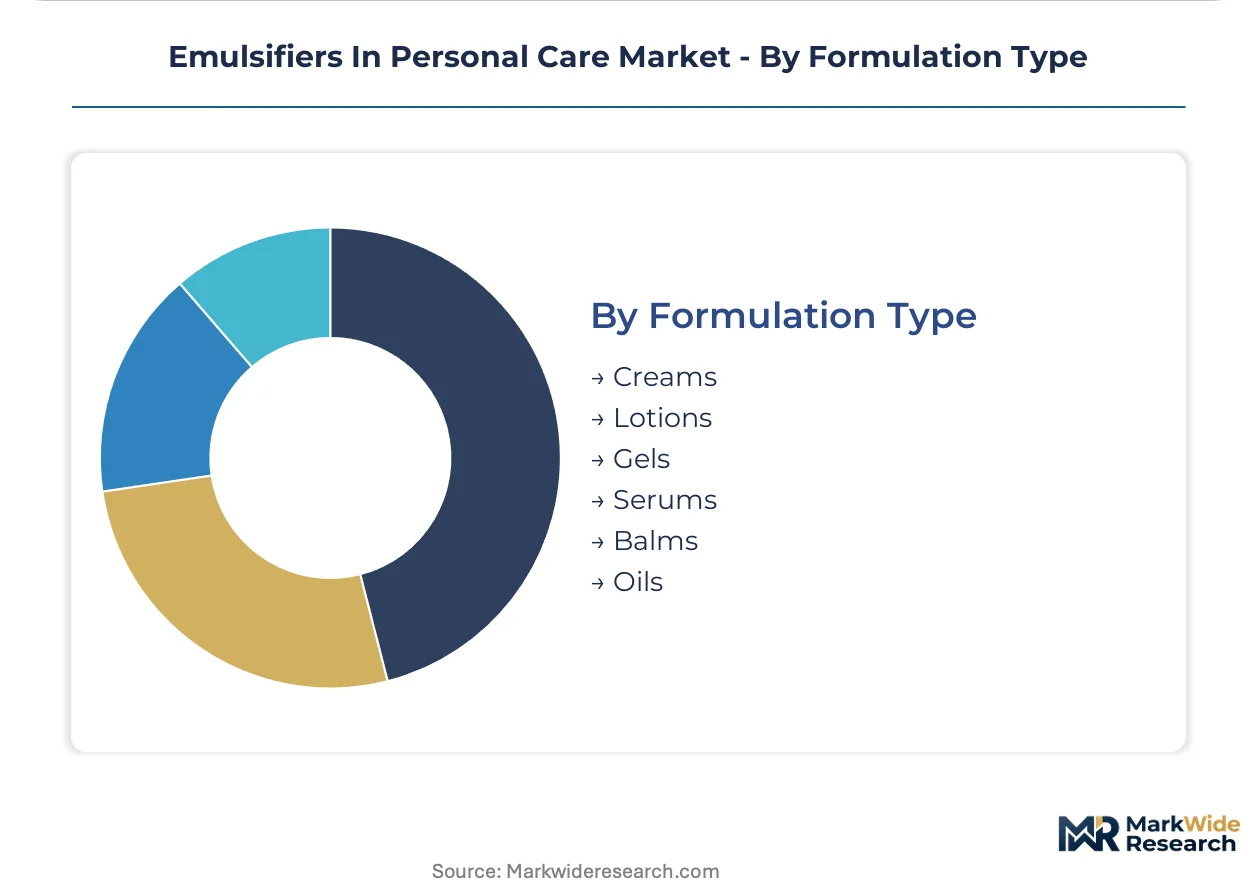
Formulation Type:
Rheology requirements and skin feel specifications create distinct emulsifier performance envelopes across delivery formats.
- Serums:Lightweight, fast-absorbing textures demand low-viscosity emulsifier systems with exceptional spreadability, driving silicone-organic hybrid adoption in premium anti-aging lines targeting sensorial differentiation without pure silicone regulatory exposure.
- Creams:Structural integrity across temperature ranges requires robust network-forming emulsifiers with crystallization control for jar and tube packaging formats.
- Lotions:Pumpable viscosity specifications favor liquid crystal emulsifier systems with shear-thinning behavior.
- Gels:Clear or translucent aesthetics constrain emulsifier selection to specific refractive index matching and low-turbidity systems.
- Balms:Anhydrous or low-water content architectures utilize water-in-oil emulsifiers with high internal phase ratio capability.
- Oils:Cleansing and treatment oils employ self-emulsifying systems for rinse-off transformation upon water contact.
Creams maintain volume leadership in absolute terms, with serums expanding most quickly on premium skin care brand proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping emulsifier production geography as manufacturers relocate to jurisdictions with streamlined REACH compliance pathways and established specialty chemical infrastructure. Cost-of-compliance gaps between European and Asian regulatory frameworks are accelerating investment in enzymatic production facilities outside traditional Ludwigshafen-Frankfurt clusters.
Germany
ECHA substance evaluation protocols drive reformulation demand among skin care manufacturers seeking to maintain European Economic Area market access. REACH Annex XVII restrictions on ethoxylated surfactants concentrate technical service investment in Ludwigshafen and Frankfurt production hubs. Specialty chemical clusters in these cities supply BASF SE and Evonik Industries with integrated petrochemical and biotechnology platforms for dual-portfolio emulsifier production.
United States
FDA voluntary cosmetic ingredient reporting systems create lower compliance barriers than European equivalents, attracting clean-label brand headquarters to California and New York. State-level disclosure laws in California and Washington fragment formulation standardization across domestic supply chains. Gulf Coast petrochemical infrastructure sustains synthetic emulsifier cost advantages for mass-market bath product manufacturers.
France
ANSM dermatological standards merge with cosmetic formulation requirements, enabling pharmaceutical-grade lipid excipient suppliers to serve dual end-use markets. Direct-to-consumer beauty brands in Paris and Lyon conduct independent emulsifier qualification, bypassing traditional toll manufacturing tiers. Gattefossé anchors lipid-based emulsifier production for premium facial care applications.
Netherlands
Rotterdam port logistics reduce feedstock costs for enzymatic esterification facilities scaling bio-based emulsifier output. Dutch specialty chemical producers achieve cost parity with synthetic alternatives in high-volume lotion applications. SEPPIC leverages RSPO-certified supply chains to serve clean-label procurement requirements across German and French brand portfolios.
United Kingdom
Post-Brexit regulatory divergence from EU REACH creates parallel compliance documentation burdens for manufacturers serving both markets. London-based direct-to-consumer brands maintain internal formulation capabilities and establish direct procurement relationships with specialty chemical distributors. Croda International anchors botanical lipid emulsifier supply for premium anti-aging serum formulations.
Emulsifiers In Personal Care Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical conglomerates commanding premium-tier skin care procurement while toll manufacturers serve cost-optimized bath and body applications. The vendor base concentrates around three strategic archetypes: diversified petrochemical-biotechnology hybrids, lipid-specialist botanical suppliers, and silicone-organic hybrid innovators. Competitive positioning hardens through M&A activity targeting enzymatic production capabilities and strategic partnerships bridging pharmaceutical-grade certification with cosmetic formulation standards.
Among German-integrated chemical conglomerates, BASF SE and Evonik Industries occupy positions spanning synthetic and bio-based emulsifier portfolios. BASF SE exemplifies the petrochemical-biotechnology hybrid archetype through its Ludwigshafen production integration. Evonik Industries sits within the silicone-organic hybrid specialization tier targeting sensorial performance requirements. Croda International anchors the botanical lipid specialist position with UK-originated supply chain architecture. These three companies represent distinct competitive vectors rather than overlapping market contestation.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| Evonik Industries |
| Clariant |
| Croda International |
| Ashland |
| Solvay |
| SEPPIC |
| Gattefossé |
| Others |
Pricing and Supply Chain Analysis
Shea butter futures volatility cascades through emulsifier supply chains into three-tier pricing structure across premium, standard, and economy levels. REACH compliance documentation costs compress margins for botanical lipid suppliers while petrochemical feedstock arbitrage sustains synthetic emulsifier cost advantages in mass-market bath products.
Pricing Analysis
Distributor margin layers compress as direct-to-consumer beauty brands establish direct procurement relationships with specialty chemical suppliers in Ludwigshafen and Frankfurt. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with RSPO-certified natural derived emulsifiers commanding premiums over synthetic alternatives. Cost compression in standard-tier synthetic emulsifiers is intensifying because Gulf Coast petrochemical output expansion feeds oversupply conditions. Mass-market bath product manufacturers exhibit highest price sensitivity due to thin margin structures, while premium anti-aging serum brands prioritize sensorial performance over unit cost.
Supply Chain Analysis
Returns and reformulation flows concentrate in mid-sized Italian and Spanish contract manufacturers facing legacy PEG-based inventory stranding from REACH Annex XVII restrictions. Supply concentrates in Germany, the Netherlands, and France, with Rotterdam port logistics reducing feedstock costs for enzymatic esterification facilities. Raw material dependencies rest on shea butter from West Africa, jojoba oil from Argentina and Israel, and palm-derived lipids from Southeast Asia. Single-source vulnerability in enzymatic catalyst supply creates qualification bottlenecks extending new ingredient timelines. Distribution runs through specialty chemical distributors serving direct-to-consumer brands with pre-qualified ingredient libraries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds on regulatory tightening, with ECHA substance evaluation protocols explicitly screening emulsifiers for aquatic persistence and endocrine disruption potential to drive sustained reformulation demand.
For Market Incumbents: Hedge against botanical input cost volatility through backward integration into enzymatic production capabilities in the Netherlands and Germany. Secure captive supply of RSPO-certified palm derivatives to defend margin position as clean-label procurement accelerates. Diversify synthetic-bio hybrid portfolios to maintain access across both mass-market and premium tier formulations.
For New Entrants and Emerging Players: Capture white space in silicone-organic hybrid emulsifiers targeting premium anti-aging serums where sensorial performance requirements outpace incumbent innovation cycles. Penetrate the sun care reformulation wave driven by Hawaii and Palau reef-safe mandates through benzophenone-free UV filter compatibility expertise. Deploy direct technical service models bypassing traditional distributor layers to accelerate qualification timelines.
For Investors and Strategic Acquirers: Asymmetric upside sits with enzymatic esterification specialists achieving cost parity with synthetic alternatives in high-volume lotion applications. Long-term viability favors suppliers bridging pharmaceutical-grade lipid excipient certification with cosmetic formulation standards. Monitor ECHA substance evaluation update cadence as inflection indicator for accelerated substitution demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Production Scale-Up | SEPPIC and Dutch specialty chemical producers achieve cost parity with synthetic emulsifiers in lotion applications. |
| RSPO Supply Chain Certification | Segregated documentation commands price premiums in clean-label bath and body procurement. |
| Silicone-Organic Hybrid R&D | Evonik Industries targets sensorial performance without pure silicone regulatory exposure. |
| Direct-to-Brand Technical Service | French and UK direct-to-consumer brands bypass toll manufacturers for supply chain transparency. |
| Pharmaceutical-Grade Excipient Convergence | Gattefossé and ANSM standards enable dual-market serving of cosmetic and dermatological formulations. |
Research Methodology
Bottom-up personal care formulation modeling reconciled against top-down specialty chemical production tracking forms the analytical core of this study. Primary interviews with technical R&D directors at skin care manufacturers, procurement leads at contract manufacturers, regulatory affairs specialists navigating ECHA protocols, and distribution channel partners in Germany and France combined with secondary validation from REACH Annex XVII filings, ECHA substance evaluation databases, RSPO supply chain documentation, and customs trade data. Bottom-up and top-down triangulation reconciles emulsifier volume flows against end-use brand procurement patterns.
Input-output matrices map emulsifier chemistry grades to application-specific performance requirements across the projection horizon. Segmentation dimensions modeled include product type chemistry, skin care versus sun care versus hair care application, personal care manufacturer versus contract manufacturer end user, and serum versus cream versus lotion formulation type. CAGRs derive from regression analysis of historical procurement volumes against regulatory milestone timing and enzymatic process cost curves. Forecast inputs incorporate REACH compliance timeline compression and clean-label brand proliferation rates.
Underlying measurement precision varies by segment; synthetic emulsifiers carry tighter precision than natural derived variants due to standardized petrochemical feedstock pricing. Forecasts reflect assumptions on regulatory enforcement consistency and enzymatic scale-up cost trajectories. Practitioners should monitor ECHA substance evaluation update frequency and shea butter futures volatility for early signals of forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.