
 Lecithin and Phospholipids Market | 2026-2036
Lecithin and Phospholipids Market Size, Share, and Industry Trends Forecast 2026-2036
Lecithin and Phospholipids Market Analysis
ISO 22000 certification is rotating as the gating qualification for lecithin suppliers serving pharmaceutical-grade contracts. Cargill, Incorporated leverages its integrated oilseed crush network across multiple continents to secure raw material access. Lipoid GmbH specializes in high-purity phosphatidylcholine for injectable drug formulations, anchoring its position in medical nutrition.
Lecithin and phospholipids comprise amphiphilic lipid mixtures extracted from oilseeds or egg yolk, containing 15-25% phosphatidylcholine by weight in standard soy grades, functioning primarily as natural emulsifiers and cell membrane structural analogues. Soy lecithin occupies the dominant volume position due to established crushing infrastructure, though sunflower lecithin captures expanding share among allergen-free and non-GMO product lines. Phosphatidylcholine concentrates in pharmaceutical applications command premium positioning within the value chain.
EFSA in Europe, FDA in the United States, and FSSAI in India enforce divergent purity thresholds for food-grade versus pharmaceutical-grade phospholipids, fragmenting compliance costs across export destinations. REACH registration requirements in Europe constrain small-scale importers of modified lecithin derivatives. Stakeholders must monitor evolving novel food designations for emerging plant sources before committing extraction capacity.
Market Dynamics
Pharmaceutical-grade phospholipid supply chains are bifurcating as ISO 22000 certification becomes mandatory for sterile injectable formulations, forcing processors to choose between commodity food-grade volumes and high-purity medical contracts with divergent capital requirements.
Growth Catalysts
- EFSA novel food pathway:Accelerated approvals for sunflower-derived lecithin variants are displacing soy alternatives in allergen-sensitive formulations across European nutraceutical channels.
- Liposomal encapsulation:Drug delivery platforms utilizing phosphatidylcholine concentrates are expanding oncology and vaccine adjuvant applications through enhanced bioavailability.
- Germany's lipid processing corridor:Concentrated technical expertise in specialized fractionation is attracting multinational procurement offices seeking high-purity phospholipid streams.
Market Restraints
- Soy crush concentration:Over 70% of raw lecithin feedstock originates from Argentina and Brazil oilseed infrastructure, exposing buyers to South American climate volatility and export policy swings.
- REACH registration burden:European chemical registration requirements for modified lecithin derivatives impose six-figure compliance costs that exclude small-scale importers from modified-grade segments.
- Synthetic surfactant substitution:Polysorbates and PEGylated alternatives compete in cost-sensitive emulsification applications where natural-origin claims carry limited pricing power.
Strategic Opportunities
- India's pharmaceutical expansion:CDSCO manufacturing license reforms are attracting liposomal API producers seeking phospholipid supply partnerships for domestic oncology formulation.
- Cell-cultured meat:Phospholipid-based growth media components represent emerging demand from cultivated protein startups requiring serum-free alternatives.
- EU Green Deal bioeconomy incentives:Novel extraction technologies from agricultural waste streams qualify for subsidized pilot scale-up under circular economy funding mechanisms.
Industry Challenges
- Phosphatidylchrome purification talent scarcity:Chromatographic separation expertise for injectable-grade concentrates remains concentrated among German and Swiss technical specialists, constraining capacity expansion.
- Dual certification timelines:Simultaneous FDA drug master file and EMA CEP submissions for pharmaceutical-grade phospholipids extend qualification cycles beyond 24 months.
- Legacy emulsifier integration:Reformulation projects replacing synthetic surfactants with natural lecithin require extensive stability testing that delays product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lecithin and Phospholipids Market |
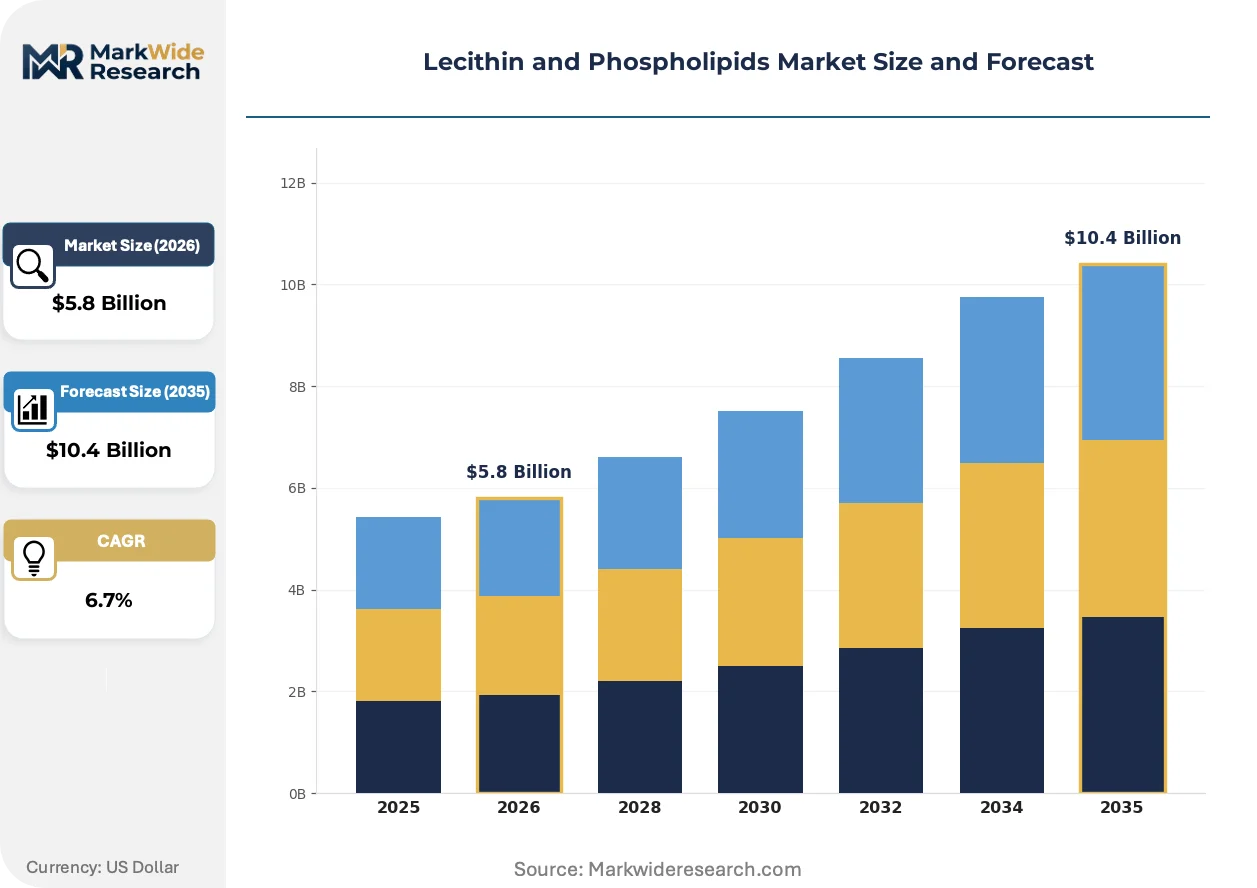
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Lecithin, Egg Lecithin, Sunflower Lecithin, Phosphatidylcholine Application: Food & Beverage, Pharmaceuticals, Cosmetics, Animal Feed Form: Liquid, Powder, Granules, Emulsifier End User: Food Manufacturers, Nutraceutical Companies, Personal Care Brands, Animal Health |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Bunge Limited, Lecico GmbH, Lipoid GmbH, Stern-Wywiol Gruppe GmbH & Co. KG, DuPont de Nemours, Inc., American Lecithin Company, Wilmar International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lecithin and Phospholipids Market Emerging Trajectories
Continuous processing technologies and precision fractionation methods are compressing batch cycles while regulatory divergence between pharmaceutical and food-grade standards is fragmenting supplier qualification pathways across major import markets.
Supercritical CO2 extraction systems for phospholipid purification are miniaturizing from industrial-scale installations to modular skid-mounted units. Mid-size nutraceutical contract manufacturers in the Netherlands and Switzerland are adopting these compact systems to bypass toll-processing dependencies. This distributed processing architecture is compressing lead times for custom phosphatidylcholine ratios while reducing working capital tied to inventory.
REACH registration deadlines for lecithin derivatives are tightening purity documentation requirements for modified grades entering European customs zones. Processors must now submit full toxicological dossiers for hydroxylated or acetylated variants previously imported under food-grade harmonized codes. German customs authorities are rejecting shipments lacking valid registration numbers, redirecting trade flows toward Swiss and UK entry points with transitional arrangements.
Direct procurement relationships between pharmaceutical formulators and specialized fractionators are displacing traditional distributor intermediaries in high-purity segments. Large-scale liposomal drug developers in Massachusetts and Basel now negotiate annual offtake agreements directly with German phospholipid refiners, bypassing regional chemical distributors. This channel compression is most visible in North American oncology API supply chains where batch traceability requirements exceed distributor technical capabilities.
Lecithin and Phospholipids Market Segmentation
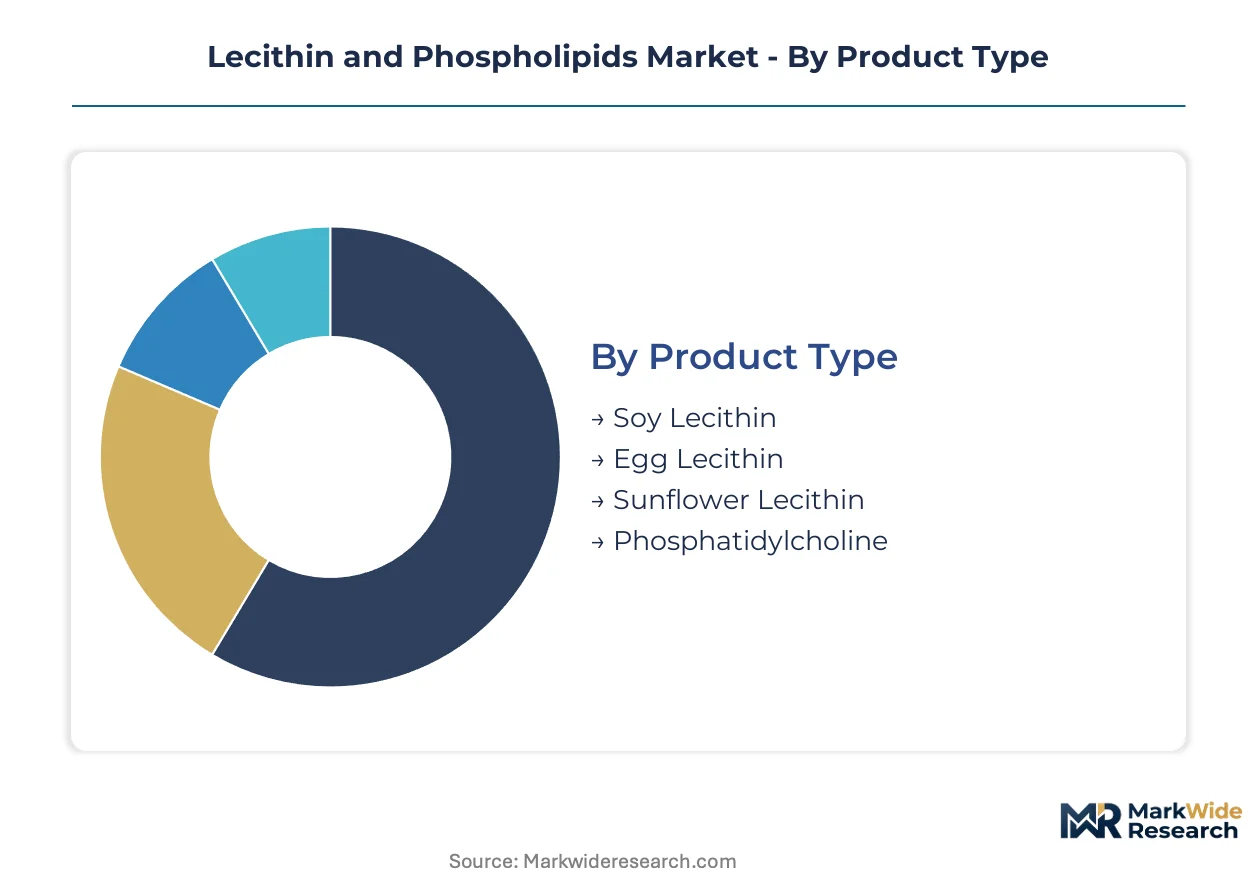
Margin pools in the lecithin and phospholipids market fragment sharply across certification grades and application purity requirements. Pharmaceutical-grade concentrates command premium positioning while food-grade volumes compete on crushing efficiency and logistics scale.
Product Type:
Premium pricing concentrates in high-purity phosphatidylcholine isolates for sterile injectable applications, while commodity soy lecithin generates volume throughput through established oilseed infrastructure.
- Soy Lecithin:Standard grades contain 15-25% phosphatidylcholine by weight and serve as the baseline emulsifier across mass-market food manufacturing. Argentina and Brazil crushing infrastructure supplies over 70% of raw feedstock, exposing procurement to South American climate volatility and export policy swings.
- Phosphatidylcholine:Chromatographic purification yields concentrates exceeding 90% purity for liposomal drug delivery platforms in oncology and vaccine adjuvant formulations. German fractionators anchor technical expertise for sterile injectable grades, constraining capacity expansion due to scarce chromatographic talent.
- Sunflower Lecithin:Non-GMO and allergen-free positioning captures expanding share in European nutraceutical channels following EFSA novel food approvals.
- Egg Lecithin:Yolk-derived phospholipids retain niche demand in cell culture media and specialized pharmaceutical formulations requiring defined fatty acid profiles.
Soy lecithin holds installed capacity. Sunflower lecithin is rotating up the share rankings.
Application:
Volume concentration diverges from value concentration as food-grade emulsification absorbs tonnage while pharmaceutical encapsulation absorbs margin.
- Pharmaceuticals:Liposomal delivery systems utilizing phosphatidylcholine concentrates are expanding through enhanced bioavailability in oncology APIs. CDSCO manufacturing license reforms in India are attracting liposomal producers seeking domestic phospholipid supply partnerships.
- Food & Beverage:Natural emulsifier demand spans chocolate confections, bakery, and dairy alternatives where clean-label positioning commands formulation priority. EFSA novel food pathways for sunflower variants are displacing soy alternatives in allergen-sensitive European product lines.
- Cosmetics:Phospholipid-based liposomes serve as skin penetration enhancers in premium personal care formulations.
- Animal Feed:Nutritional emulsifiers support lipid digestion efficiency in poultry and aquaculture feed rations.
Food and beverage holds installed capacity. Pharmaceuticals is climbing the fastest on value contribution.
Form:
Processing intensity and handling economics separate liquid commodity flows from dried formats requiring additional energy and capital input.
- Liquid:Unprocessed crude lecithin flows directly from oilseed crushing operations into bulk food manufacturing with minimal downstream investment. Supercritical CO2 extraction systems are miniaturizing to modular skid-mounted units, compressing lead times for custom phosphatidylcholine ratios.
- Powder:Spray-dried and blended formats serve nutraceutical capsule manufacturing and dry-mix food applications requiring extended shelf stability.
- Granules:Low-dust handling properties suit automated dosing systems in large-scale bakery and confectionery operations.
- Emulsifier:Pre-hydrated and compounded preparations reduce formulation complexity for cosmetics and specialized pharmaceutical applications.
Liquid holds installed capacity. Powder is gaining share fastest in nutraceutical channels.
End User:
Procurement sophistication bifurcates between commodity buyers optimizing logistics cost and pharmaceutical formulators demanding batch traceability exceeding distributor technical capabilities.
- Nutraceutical Companies:Liposomal supplement manufacturers are expanding phospholipid procurement for enhanced bioavailability delivery systems. Direct annual offtake agreements with German refiners are displacing traditional distributor intermediaries in high-purity segments.
- Food Manufacturers:Mass-market emulsifier procurement prioritizes crushing proximity and freight economics over functional differentiation.
- Personal Care Brands:Premium cosmetic formulators specify phospholipid ratios for lamellar phase stability in skin care emulsions.
- Animal Health:Feed compounders integrate nutritional emulsifiers into species-specific premix formulations for digestion optimization.
Food manufacturers hold installed capacity. Nutraceutical companies is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade buyers concentrate procurement authority in Germany's specialized lipid processing corridor, while food-grade volumes flow through crushing-adjacent logistics hubs in Argentina and Brazil. Nutraceutical formulators in India and Switzerland are establishing direct refiner relationships that bypass traditional distribution channels.
Germany
Injectable-grade phosphatidylcholine demand from Massachusetts and Basel-based drug developers drives annual offtake agreements with specialized fractionators. EMA centralized procedure approvals for sterile liposomal formulations mandate ISO 22000 certification that only German refiners consistently maintain. The Rhine-Main corridor hosts chromatographic purification specialists whose technical expertise constrains European capacity expansion.
United States
Liposomal oncology API producers in Massachusetts negotiate direct supply contracts for high-purity phospholipid streams. FDA drug master file submissions for pharmaceutical-grade concentrates extend qualification timelines beyond twenty-four months. The Northeast pharmaceutical manufacturing belt absorbs premium-priced phosphatidylcholine isolates for vaccine adjuvant applications.
India
CDSCO manufacturing license reforms attract domestic liposomal formulation producers seeking phospholipid supply partnerships. FSSAI purity thresholds for food-grade lecithin diverge from pharmaceutical-grade requirements, fragmenting import compliance costs. Maharashtra's pharmaceutical formulation corridor is emerging as a procurement hub for oncology API developers.
Argentina
Soy crush infrastructure supplies over seventy percent of raw lecithin feedstock to global emulsifier markets. Export policy swings and climate volatility expose buyers to supply disruption risks. The Pampas grain belt anchors crushing capacity that feeds commodity-grade liquid lecithin into bulk food manufacturing channels.
Switzerland
Nutraceutical contract manufacturers adopt modular supercritical CO2 extraction systems to bypass toll-processing dependencies. Swissmedic transitional arrangements for REACH-registered modified lecithin derivatives redirect trade flows from German customs entry points. Basel's pharmaceutical cluster maintains direct procurement relationships with German phospholipid refiners for batch-traceable injectable grades.
Lecithin and Phospholipids Market Vendor Landscape
Player mix skews toward integrated oilseed processors with captive crushing infrastructure and specialized German fractionators serving pharmaceutical channels. The market structure bifurcates between commodity food-grade volumes competing on logistics scale and premium medical-grade concentrates commanding certification-based pricing. Three archetypes dominate: multinational agribusinesses with backward integration into oilseed supply, European technical specialists with chromatographic purification capabilities, and Asian trading houses with regional distribution density. Competitive moves center on direct procurement relationship formation with pharmaceutical formulators and modular extraction technology adoption by mid-size nutraceutical processors.
Among integrated agribusinesses, Cargill, Incorporated and Archer Daniels Midland Company exemplify the scale-driven archetype with oilseed crush networks spanning multiple continents. Lipoid GmbH occupies a position within the specialized fractionator tier, anchoring technical expertise for high-purity phosphatidylcholine applications. These three entities represent the competitive spectrum from commodity volume throughput to premium pharmaceutical-grade certification.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Bunge Limited |
| Lecico GmbH |
| Lipoid GmbH |
| Stern-Wywiol Gruppe GmbH & Co. KG |
| DuPont de Nemours, Inc. |
| American Lecithin Company |
| Wilmar International Ltd. |
| Others |
Supply Flow & Price Mechanics
ISO 22000 certification gates both supply qualification and price differentiation simultaneously, creating a bifurcated market where pharmaceutical-grade phosphatidylcholine concentrates command substantial premia over commodity food-grade lecithin streams. Buyers seeking sterile injectable grades face limited supplier pools in Germany's specialized fractionation corridor, while food manufacturers optimize crushing proximity and freight economics.
Pricing Analysis
Cost-plus contracts with vegetable oil indexation dominate raw lecithin procurement from Argentina and Brazil crushing infrastructure. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade levels reflects purity thresholds and certification burdens. Pricing pressure stems from synthetic surfactant substitution in cost-sensitive emulsification applications. Food manufacturers exhibit highest price sensitivity, while oncology API developers absorb premia for batch-traceable injectable grades.
Supply Chain Analysis
Rosario-Buenos Aires port complex throughput governs global commodity lecithin availability, with over seventy percent of raw feedstock originating from Argentina and Brazil oilseed infrastructure. Supply chains draw from soybeans, sunflower seeds, and egg yolk as primary phospholipid sources. Single-source vulnerability concentrates in South American climate volatility and export policy swings. Distribution runs through integrated agribusiness crush networks and specialized German refiners serving pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic surfactant substitution threatens natural lecithin positioning in cost-sensitive applications, forcing incumbents to defend through certification differentiation and high-purity segment concentration.
For Market Incumbents: Fortify chromatographic purification capabilities in Germany's Rhine-Main corridor to anchor sterile injectable grade supply. Deepen backward integration into non-GMO sunflower seed procurement to capture EFSA novel food pathway expansion. Prioritize ISO 22000 certification maintenance as polysorbate competition intensifies in food-grade emulsification.
For New Entrants and Emerging Players: Toll-processing service gaps in mid-size nutraceutical contract manufacturing present entry points for modular supercritical CO2 extraction adoption. Target India's CDSCO reform corridor for liposomal API supply partnerships. Pursue direct procurement relationship formation with Massachusetts and Basel-based drug developers seeking batch-traceable phospholipid streams.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade phosphatidylcholine fractionation as chromatographic talent scarcity constrains capacity expansion. Long-term viability favors specialized German refiners with EMA CEP submission track records. Watch FDA drug master file approval velocity as inflection indicator for premium segment demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Chromatographic Capacity Expansion | German fractionators anchor sterile injectable supply for Massachusetts oncology developers. |
| Non-GMO Sunflower Sourcing | EFSA novel food approvals accelerate allergen-free lecithin substitution across European nutraceutical channels. |
| Modular Extraction Technology Adoption | Mid-size Dutch and Swiss processors bypass toll-processing dependencies with skid-mounted supercritical CO2 systems. |
| Direct Procurement Relationship Formation | Liposomal drug developers in Basel negotiate annual offtake agreements bypassing regional chemical distributors. |
| REACH Registration Compliance | Modified lecithin derivatives require six-figure toxicological dossiers for European customs clearance. |
Methodological Framework
A standing panel of phospholipid refinery technical directors, nutraceutical contract manufacturing procurement leads, and oncology API formulation scientists provided ongoing calibration across primary interview rounds. Secondary validation drew from EFSA novel food registers, FDA drug master file databases, CDSCO manufacturing license records, and oilseed crush capacity reports from Argentina and Brazil. Bottom-up volume modeling triangulated against top-down value estimates from import customs data and pharmaceutical excipient pricing benchmarks.
Consistency checks validated projections against external oilseed processing capacity announcements and liposomal drug pipeline advancement disclosures. Segmentation dimensions spanned product grade tier, application purity requirement, form factor, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion timelines. Forecast inputs incorporated EMA centralized procedure approval rates and REACH registration completion patterns for modified lecithin derivatives.
Underlying assumptions cover sustained EFSA novel food pathway velocity for sunflower variants, with deviation risk concentrated in South American climate disruption and synthetic surfactant substitution acceleration. Forecasts reflect documented demand elasticity parameters and supply-side capacity constraints. Practitioners should keep alternative scenarios live as CDSCO reform implementation and EU Green Deal bioeconomy funding allocation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Sodium Benzoate Market
Additives
FD and C Lakes Market
Additives
Performance Minerals Additives Market
Additives
Global Metal Scavenging Agents Market
Additives
Guanylic Acid Market
Additives
Friction Modifier Additives Market
Additives
Pectin Market
Additives
Organic Dispersants Market
Additives
Global Scale Inhibitors Market
Additives
Anti-Slip Additives Market
Additives
Grinding Aids Market
Additives
Glycol Acetate Market
Additives
Sodium Citrate Anhydrous Market
Additives
Asia Pacific Silage Additives Market
Additives
Plastics Modifiers Market
Additives
Thallium Acetate Market