
 Global Battery Coating Market | 2026-2036
Global Battery Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Global Battery Coating Market Intelligence
Expertise in polymer chemistry and electrochemical engineering is reorganizing the competitive landscape, favoring material science specialists over general chemical suppliers. Arkema S.A. leverages its portfolio in high-performance polymers for advanced separator coatings. Solvay S.A. specializes in electrolyte additives and binder solutions that enhance battery performance. Meanwhile, BASF differentiates with a comprehensive range of cathode and anode materials, positioning itself as a key supplier to cell manufacturers.
Battery coatings are functional layers applied to internal components like electrodes and separators within a lithium-ion battery cell. These materials, often applied as thin films measured in microns, are critical for improving thermal stability, preventing internal short circuits, and extending the overall cycle life. While polymer coatings represent the foundational product type, ceramic coatings are experiencing rapid adoption for high-performance electric vehicles. The energy storage systems application also demands coatings that prioritize long-term durability and operational safety.
Regulatory frameworks directly influence material formulation and market access for coating suppliers. The EU's REACH regulation and its comprehensive Battery Regulation mandate stringent chemical safety, performance, and sustainability reporting. Concurrently, China’s GB standards for battery safety and US EPA rules governing new chemical substances dictate material selection for manufacturers targeting these markets. Navigating these divergent regional compliance requirements remains a central strategic challenge for all suppliers.
Market Dynamics
The market's central dynamic is the tension between the accelerated pace of electric vehicle battery innovation and the increasing stringency of global safety regulations. This forces material suppliers to develop coatings that simultaneously enhance electrochemical performance and meet divergent regional mandates for thermal stability.
Growth Catalysts
- EV Performance Mandates:Demand for longer range and faster charging in electric vehicles necessitates advanced separator and electrode coatings that improve thermal management and prevent degradation, directly fueling material science innovation.
- EU Battery Regulation:This comprehensive framework imposes strict lifecycle, safety, and performance criteria, compelling manufacturers to adopt higher-grade coatings that can satisfy its rigorous testing and reporting requirements.
- Manufacturing Hub Concentration:The clustering of battery production in South Korea and China creates intense, localized demand for coating materials, streamlining supply chains and accelerating adoption cycles for new formulations.
Market Restraints
- Raw Material Volatility:The pricing and supply instability of key inputs for ceramic coatings, such as high-purity alumina, create significant cost pressures and margin uncertainty for coating formulators.
- Processing Complexity:Achieving uniform, defect-free coating layers at the micron scale remains a significant technical hurdle, with inconsistencies impacting battery yield, performance, and safety.
- Divergent Regulatory Standards:Navigating conflicting chemical registration requirements between frameworks like the EU's REACH and the US EPA's TSCA creates compliance burdens and can delay market entry for new materials.
Strategic Opportunities
- Solid-State Battery Development:The emergence of solid-state battery architectures opens a new frontier for specialized interface coatings designed to manage dendrite growth and ensure ionic conductivity between solid components.
- Domestic Supply Chain Incentives:Policies like the US Inflation Reduction Act (IRA) create powerful financial incentives for establishing domestic production of battery components, including coated separators and electrodes.
- Advanced Material Discovery:The application of artificial intelligence and machine learning platforms to screen novel polymer and ceramic compositions presents an opportunity to rapidly develop next-generation coatings with superior properties.
Industry Challenges
- Specialized Talent Scarcity:A shortage of chemical engineers and material scientists with dual expertise in polymer chemistry and electrochemistry constrains R&D capacity and innovation across the industry.
- Lack of Performance Standardization:The absence of globally harmonized test protocols for coating performance makes direct comparison between supplier materials difficult for battery manufacturers, slowing qualification times.
- Capital-Intensive Production:The high cost of precision coating machinery and cleanroom environments required for high-quality production represents a significant capital barrier for new entrants and smaller suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Battery Coating Market |
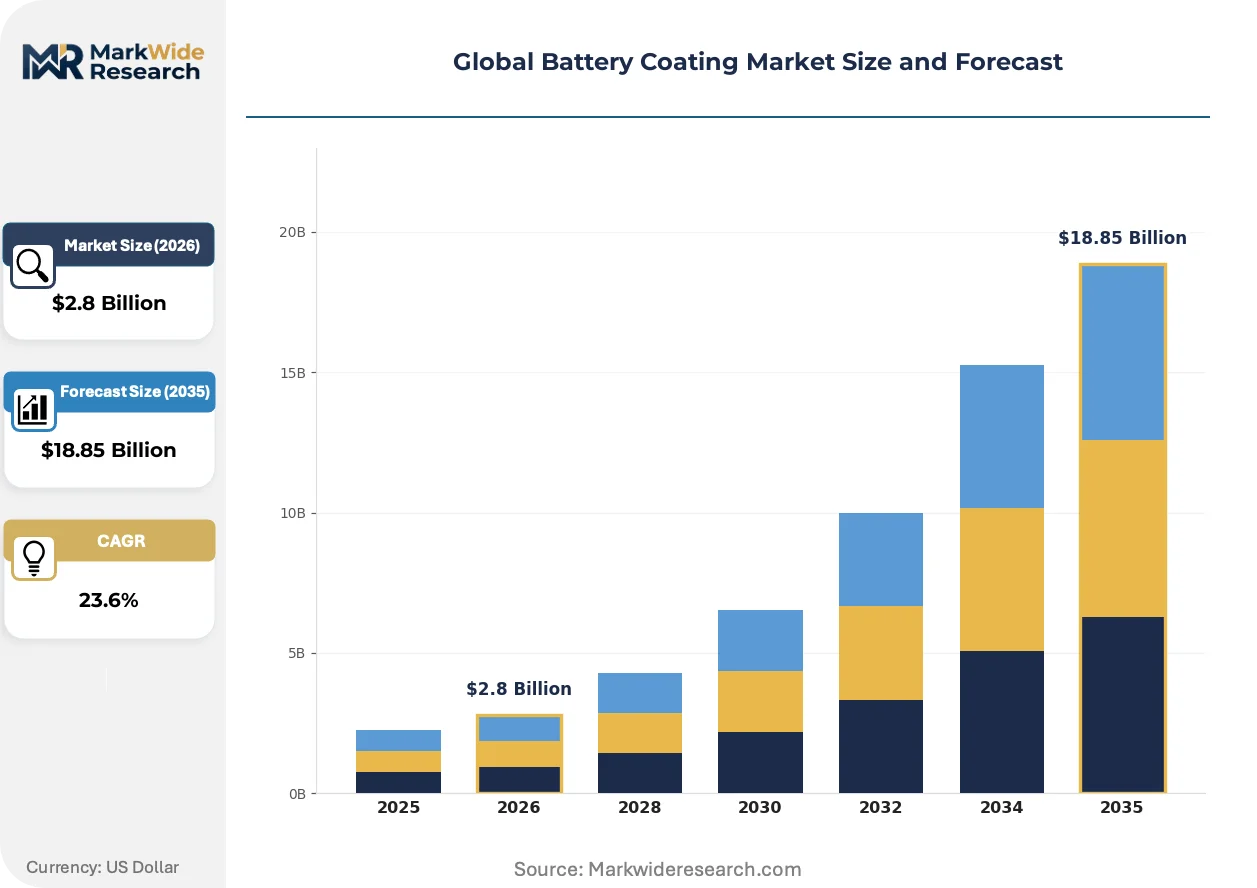
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $18.85 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Coatings, Ceramic Coatings, Metal Oxide Coatings, Carbon-Based Coatings Technology: Spray Coating, Dip Coating, Chemical Vapor Deposition, Electrophoretic Deposition Application: Electric Vehicles, Consumer Electronics, Energy Storage Systems, Aerospace Equipment End User: Battery Manufacturers, Electronics OEMs, Renewable Energy Companies, Electric Mobility Providers |
| Companies Covered | Arkema S.A., Solvay S.A., Asahi Kasei Corporation, Ube Corporation, PPG Industries Inc., BASF, Axalta Coating Systems LLC, SK Innovation Co., Ltd., Targray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Battery Coating Market Strategic Shifts & Innovations
Material science advancements are transforming coatings from passive protective layers into active components that directly influence battery cell performance and safety. This shift is creating a clear separation between suppliers offering commoditized materials and those developing highly functional, specialized formulations.
Advanced functional coatings, such as self-healing polymers and ionically conductive ceramic layers, provide active electrochemical benefits beyond simple insulation. High-performance electric vehicle manufacturers and grid-scale energy storage operators are rapidly adopting these materials to maximize cycle life and safety. This trend is bifurcating the market, creating a premium segment for performance-driven applications while a separate, cost-focused segment serves standard consumer electronics.
China’s GB standards for battery safety have become a major force in material selection for all global suppliers. These regulations mandate stringent thermal runaway prevention tests, compelling cell manufacturers to incorporate more robust coatings, particularly ceramic-coated separators, to pass certification. This requirement affects all battery and EV producers targeting the Chinese market, effectively setting a new baseline for thermal management material performance.
A notable behavioral shift sees battery cell manufacturers moving from sourcing discrete materials to qualifying integrated electrode and separator sub-assemblies. This change disrupts the traditional sales channel where coating suppliers sold directly to component makers. The new model favors material specialists who can co-develop and pre-apply coatings in partnership with cell producers, a trend most prominent in South Korea's highly integrated battery ecosystem.
Global Battery Coating Market Segmentation
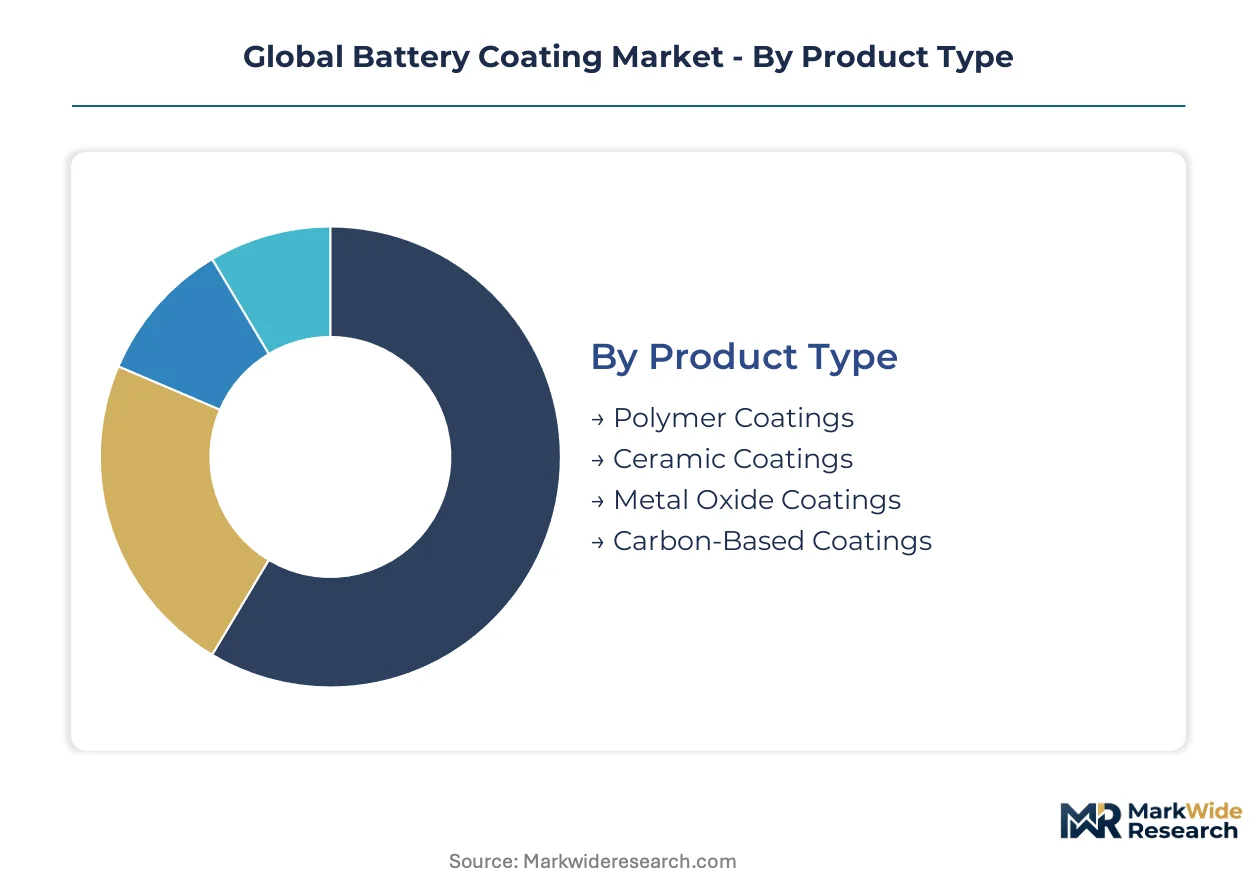
The Global Battery Coating Market segments across diverse product types, application methods, end-use industries, and user categories. Understanding these distinctions is critical for material suppliers and battery manufacturers to align their strategies with specific market demands and regulatory landscapes.
Product Type:
Product type segmentation reveals how different coating materials are adopted across various regions, often driven by local manufacturing capabilities and performance requirements.
- Ceramic Coatings:These advanced formulations, often comprising alumina or zirconia, enhance thermal stability and prevent internal short circuits within high-performance batteries. Demand is heavily concentrating in electric vehicle manufacturing hubs in South Korea and China, driven by stringent safety standards and the need for extended range.
- Polymer Coatings:As foundational protective layers, polymer coatings, such as PVDF or polyimide, provide electrical insulation and mechanical integrity to battery components. Their widespread application across all battery types ensures a consistent demand from global electronics and automotive producers.
- Metal Oxide Coatings:Applied to electrode surfaces, metal oxide coatings improve electrochemical stability and reduce unwanted side reactions. These materials are gaining traction in specialized applications requiring enhanced cycle life and power density.
- Carbon-Based Coatings:Utilizing materials like graphene or carbon nanotubes, these coatings enhance conductivity and improve electrode integrity. They are primarily explored for next-generation battery designs and high-power applications.
Polymer Coatings holds the largest share; momentum sits with Ceramic Coatings.
Technology:
Different coating technologies are selected based on the required precision, throughput, and material compatibility, directly impacting production efficiency and cost structures.
- Spray Coating:This widely adopted method applies a fine mist of coating material onto battery components, offering versatility across various substrates and geometries. It provides a cost-effective solution for large-scale production of standard battery cells.
- Electrophoretic Deposition:This precision technique uses an electric field to deposit uniformly thin and dense coating layers on complex shapes, crucial for high-performance and miniaturized battery designs. Its ability to create highly controlled films is valued by advanced battery developers.
- Dip Coating:A simple and scalable method where components are immersed in a coating solution, dip coating is suitable for applying uniform films to larger battery parts. This technique finds common use in less complex coating applications.
- Chemical Vapor Deposition:This process forms thin films by reacting gaseous precursors on the substrate surface, enabling superior adhesion and material purity. CVD is employed for specialized, high-integrity coatings in niche applications.
The precision and control offered by Electrophoretic Deposition are gaining importance, while Spray Coating remains essential for high-volume manufacturing.
Application:
The application segment delineates where battery coatings provide critical functional benefits, influencing material specifications and regulatory compliance requirements.
- Electric Vehicles:Coatings in EVs are essential for improving thermal management, preventing dendrite formation, and extending battery life, directly impacting vehicle safety and performance. The EU Battery Regulation and China’s GB standards drive stringent material selection for these applications.
- Energy Storage Systems:For grid-scale and residential energy storage, coatings prioritize long-term durability, operational safety, and cycle stability to ensure reliable power delivery. These systems demand robust materials that can withstand extended periods of charge and discharge.
- Consumer Electronics:Coatings for smartphones, laptops, and wearables focus on miniaturization, safety, and energy density to meet the compact design and performance expectations of portable devices. Material choices balance cost-effectiveness with performance.
- Aerospace Equipment:In aerospace, battery coatings must meet extreme safety standards, low weight requirements, and high-performance demands for critical systems. This application segment requires highly specialized and rigorously tested materials.
Electric Vehicles represents a rapidly expanding demand segment, while Energy Storage Systems are crucial for grid stability.
End User:
End-user categories highlight the primary purchasers and integrators of battery coating materials, shaping supply chain dynamics and partnership opportunities.
- Battery Manufacturers:These entities directly integrate coating materials into their cell production lines, requiring materials that meet their specific electrochemical and manufacturing process needs. They frequently co-develop custom coating solutions with material specialists.
- Electric Mobility Providers:This group, encompassing EV manufacturers and other electric transport companies, influences coating demand through their battery performance and safety specifications. Their procurement patterns often favor integrated sub-assemblies.
- Electronics OEMs:Original Equipment Manufacturers in consumer electronics seek coatings that enable smaller, safer, and longer-lasting batteries for their devices. Their focus is on high-volume, cost-effective solutions.
- Renewable Energy Companies:These companies utilize battery coatings within large-scale energy storage systems for solar and wind power integration. They prioritize coatings that offer durability and safety for long-term grid applications.
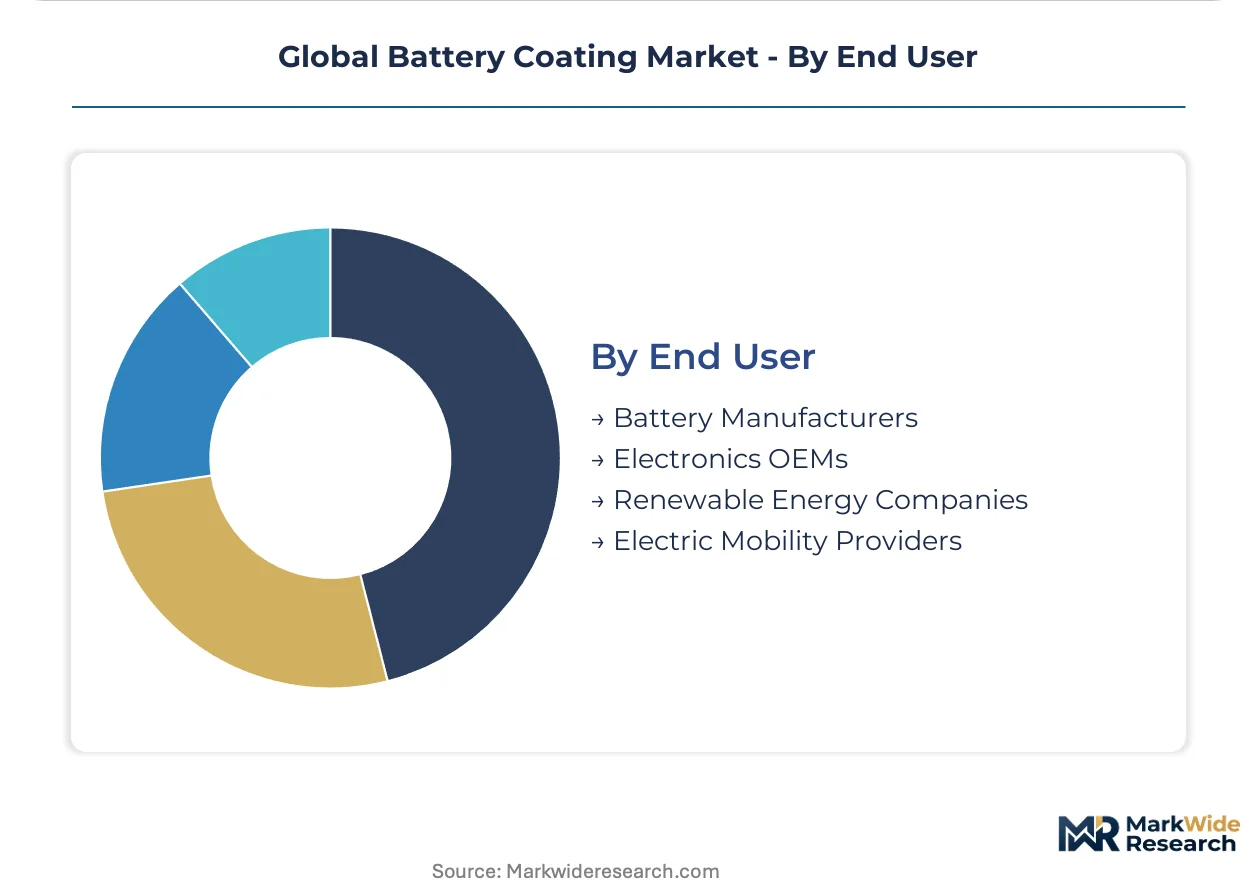
Battery Manufacturers are central to material procurement, with Electric Mobility Providers driving significant innovation in coating requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China’s GB standards for battery safety significantly influence material selection for global suppliers. These regulations, alongside the EU Battery Regulation, compel manufacturers to adopt higher-grade coatings for performance. Demand concentrates in key manufacturing hubs, driving localized material innovation and supply chain efficiency.
China
Demand for advanced coatings in China stems from its massive EV production and grid-scale energy storage projects. The GB standards for battery safety mandate robust thermal runaway prevention, driving ceramic coating adoption. Major battery manufacturing clusters in the Yangtze River Delta and Pearl River Delta rapidly integrate these advanced materials.
South Korea
South Korea's leadership in lithium-ion battery manufacturing fuels demand for high-performance separator and electrode coatings. The country's Ministry of Trade, Industry and Energy (MOTIE) supports R&D initiatives for next-generation battery materials. Integrated battery ecosystems in cities like Cheonan and Cheongju co-develop and qualify novel coating solutions.
Germany
Germany's automotive industry demands superior battery coatings to meet stringent performance and safety requirements for electric vehicles. The EU Battery Regulation imposes strict lifecycle and sustainability criteria, impacting material formulation. Battery gigafactories in Brandenburg and Lower Saxony require advanced thermal management solutions.
United States
United States EV production, supported by incentives from the Inflation Reduction Act (IRA), drives significant demand for advanced battery coatings. The Environmental Protection Agency (EPA) rules for new chemical substances dictate material selection and market access. Manufacturing facilities in states like Michigan and Georgia are scaling up coating integration for domestic battery production.
Global Battery Coating Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the global battery coating market. The market structure exhibits a tiered approach, with specialized material science firms at the premium end and general chemical suppliers offering cost-effective solutions. Strategic archetypes include high-performance polymer specialists, electrolyte additive providers, and integrated cathode/anode material suppliers. Dominant competitive moves involve portfolio diversification into advanced materials and strategic partnerships with cell manufacturers.
Specialists in advanced material science exemplify innovation within this sector, with Arkema S.A. leveraging its high-performance polymer portfolio for advanced separator coatings. This approach focuses on enhancing battery safety and longevity through specialized formulations. Solvay S.A. occupies a position as a key provider of electrolyte additives and binder solutions, which are critical for improving overall battery performance and cycle life. Meanwhile, BASF anchors the market with its comprehensive range of cathode and anode materials, positioning itself as a strategic supplier to cell manufacturers seeking integrated solutions.
| Leading Market Players |
|---|
| Arkema S.A. |
| Solvay S.A. |
| Asahi Kasei Corporation |
| Ube Corporation |
| PPG Industries Inc. |
| BASF |
| Axalta Coating Systems LLC |
| SK Innovation Co., Ltd. |
| Targray |
| Others |
Cost & Logistics Intelligence
Ceramic coating adoption, displacing traditional polymer layers for high-performance applications, simultaneously reshapes global supply geography and pricing economics for battery materials. This shift elevates the value of specialized material science expertise over commodity chemical production.
Pricing Analysis
Geographic price spreads exist for battery coatings, with premium formulations commanding higher prices in regions with stringent performance mandates like Europe and the US. Pricing operates on a hybrid model, combining contract-based long-term offtake agreements for base materials with value-based pricing for advanced, certified ceramic and specialized polymer coatings. Quality grade and certification level, especially adherence to EU Battery Regulation standards, are primary differentiation drivers. Pricing pressure stems from raw material volatility for inputs like high-purity alumina. Consumer electronics manufacturers exhibit the highest price sensitivity, while electric vehicle and energy storage system integrators prioritize performance and safety.
Supply Chain Analysis
Inventory levels and lead times for advanced battery coatings are tightening due to concentrated demand from manufacturing hubs. The supply chain for specialized battery coatings concentrates in South Korea, China, and increasingly, the United States. It draws heavily from key inputs such as high-purity alumina for ceramic coatings and specialized polymers like PVDF. Raw material volatility, particularly for critical minerals and advanced chemical precursors, represents a significant structural risk. Distribution runs through direct sales channels to battery manufacturers, with a growing trend toward integrated sub-assemblies co-developed between material specialists and cell producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a service-attach opportunity, with specialized material qualification and co-development services expanding faster than the underlying coating material volume.
For Market Incumbents: Fortify core intellectual property in advanced material formulations, particularly for ceramic and next-generation polymer coatings, to counter threats from emerging material science startups. Invest in localized production capacity in regions like the United States and Europe to mitigate geopolitical supply chain risks and meet domestic content requirements. Deepen partnerships with leading battery cell manufacturers to co-develop integrated sub-assemblies, securing long-term supply contracts and influencing future material specifications.
For New Entrants and Emerging Players: Expertise in applying AI/ML for novel polymer and ceramic compositions represents a service-layer gap where incumbents under-serve. Target niche applications requiring extreme performance, such as aerospace equipment or solid-state battery interfaces, which are less cost-sensitive and demand highly specialized solutions. A focused go-to-market angle involves offering rapid prototyping and customization services, leveraging agile R&D to address specific battery manufacturer challenges.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized material science firms with strong R&D pipelines and established relationships with Tier 1 battery manufacturers. Evaluate targets based on their intellectual property portfolio in advanced functional coatings and their ability to navigate complex global regulatory frameworks like the EU Battery Regulation. The signal to watch is the successful commercialization of interface coatings for solid-state battery architectures, indicating readiness for the next generation of battery technology.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Ceramic Coating R&D | Enhances thermal stability and safety, meeting stringent EV performance mandates and regulatory requirements. |
| Localized Production Capacity Expansion | Mitigates supply chain risks and qualifies for domestic content incentives under policies like the US IRA. |
| Strategic Partnerships with Cell Manufacturers | Secures long-term demand and co-develops integrated solutions, accelerating market adoption for new materials. |
| AI/ML-Driven Material Discovery | Accelerates the development of next-generation coatings with superior properties for high-performance applications. |
| Certification for EU Battery Regulation | Ensures market access and establishes a competitive advantage in the European electric vehicle sector. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary insights were gathered through in-depth conversations with material scientists, battery engineers, procurement leads at battery manufacturing firms, and regulatory experts across key geographies. This qualitative data was then cross-referenced with comprehensive secondary sources including industry reports, patent databases, company financial disclosures, and regulatory filings from the US EPA, China's GB standards, and the EU Battery Regulation. A robust bottom-up and top-down triangulation approach ensured data accuracy and consistency.
The forecast framework integrates historical market performance with projected growth across the analysis window, utilizing a sophisticated quantitative model. Segmentation dimensions modeled include product type (ceramic, polymer), application (EV, energy storage), end-user (battery manufacturers, electric mobility providers), and key geographic markets. Compound Annual Growth Rates (CAGRs) were derived by analyzing historical trends, anticipated technological advancements, and expert consensus on future market trajectories. Industry-specific forecast inputs include electric vehicle production forecasts and grid-scale energy storage deployment targets.
Forecasts assume regulatory continuity in the EU, China, and the US; material policy shifts would require re-modeling. The analysis reflects assumptions regarding raw material availability and the pace of technological adoption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Europe Powder Coatings Market
Coatings
Europe Anti-Friction Coatings Market
Coatings
Hard Coating Market
Coatings
Shipping Container Coatings Market
Coatings
Global Mirror Coatings Market
Coatings
Water Based Enamel Market
Coatings
Global Radiation Cured Coatings Market
Coatings
Europe Waterborne Polyurethane Coatings Market
Coatings
Japan Architectural Coatings Market
Coatings
Asia-Pacific Floor Coatings Market
Coatings
Global Abrasion Resistant Coatings Market
Coatings
Global Diamond Coatings Market
Coatings
Global Polytetrafluoroethylene (PTFE) Coatings Market
Coatings
Epoxy Surface Coatings Market
Coatings
Superhydrophobic Coatings Market
Coatings
Bio-Fouling Prevention Coatings Market