

Tamarind Gum Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Tamarind Gum Derivatives Market Insights
Asset-light toll manufacturing and contract processing arrangements is tilting competitive dynamics toward regional processors with flexible capacity. JD Gums & Chemicals leverages backward integration into tamarind seed sourcing to sustain margin control across volatile raw material cycles. Lucid Colloids anchors its position through specialized hydrocolloid blending capabilities that serve pharmaceutical formulation clients with exacting viscosity specifications. Indian Hydrocolloids competes on geographic dominance within Gujarat's tamarind belt, where proximity to seed collection networks reduces logistics costs.
Tamarind gum derivatives comprise refined polysaccharides extracted from Tamarindus indica seeds, primarily composed of xyloglucan with molecular weights ranging from 50,000 to 600,000 Da, functioning as cold-water-soluble thickeners and stabilizers across food, pharmaceutical, and industrial applications. The extraction process involves dehulling, milling, and aqueous or alkali isolation to yield powders with controlled particle size and hydration rates. Tamarind Seed Polysaccharide leads product type value pools due to premium pricing in ophthalmic and sustained-release drug delivery systems, while Tamarind Kernel Powder dominates volume through textile sizing and adhesive applications where cost efficiency outweighs refined performance. Pharmaceutical Formulations represents the fastest-growing application segment as manufacturers substitute synthetic excipients with plant-derived alternatives to meet clean-label and biocompatibility requirements.
India's FSSAI mandates labeling disclosures for hydrocolloid sources in packaged foods, directly influencing processor certification investments and customer qualification timelines. The EU REACH framework and EFSA novel food ingredient pathways govern market access for tamarind-derived additives entering European cosmetic and food channels, creating compliance barriers for uncertified exporters. ISO and JIS standards for hydrocolloid purity and microbiological limits shape contract specifications between Indian suppliers and Japanese pharmaceutical buyers. Stakeholders must monitor evolving clean-label definitions across import jurisdictions and assess captive seed supply security before committing to capacity expansion.
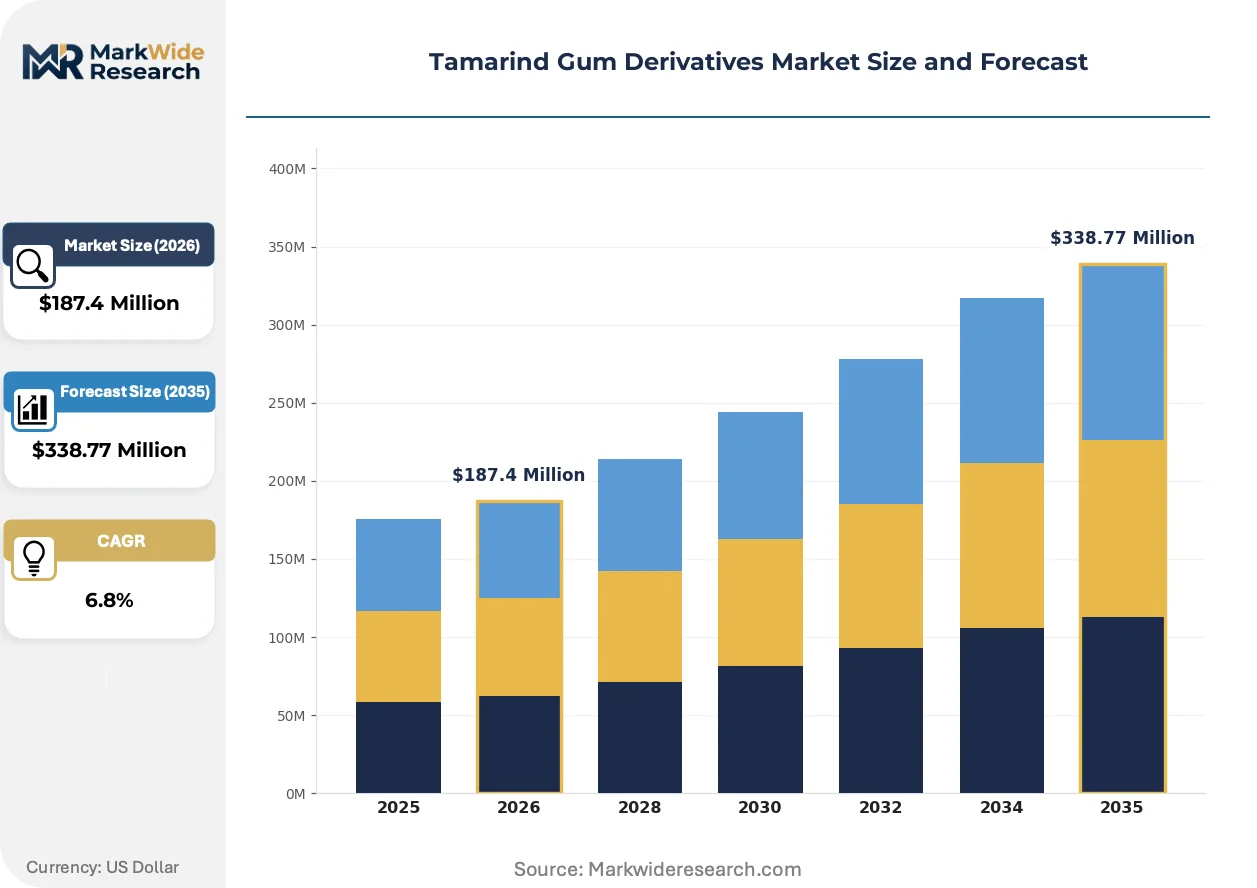
Market Dynamics
Clean-label formulation mandates from FSSAI and EFSA are compressing qualification timelines for tamarind gum processors while raw material sourcing concentrates in Gujarat and Rajasthan seed collection networks.
Growth Catalysts
- EFSA Novel Food Pathways:European regulatory approval for tamarind-derived additives opens cosmetic and pharmaceutical channels previously blocked to uncertified exporters.
- Ophthalmic Drug Delivery:Sustained-release formulation demand pulls refined tamarind seed polysaccharide into premium excipient applications.
- Gujarat-Rajasthan Cultivation Clusters:Proximity between tamarind seed collection networks and processing infrastructure reduces logistics friction for regional gum manufacturers.
Market Restraints
- Seed Price Volatility:Tamarind kernel supply fluctuates with monsoon-dependent agricultural yields across western India.
- REACH Registration Burden:ECHA compliance costs for small-batch hydrocolloid exporters create asymmetric barriers versus synthetic thickener competitors.
- Xanthan Gum Substitution:Established microbial polysaccharide alternatives dominate cost-sensitive textile sizing applications.
Strategic Opportunities
- Japanese Pharmaceutical Channels:JIS-standard hydrocolloid procurement from Indian suppliers remains underpenetrated relative to European sourcing.
- Cell-Cultured Meat Stabilization:Plant-derived hydrocolloid demand in alternative protein formulations creates application white space.
- PLI Scheme Incentives:India's production-linked incentive framework for specialty chemicals rewards domestic gum derivative capacity expansion.
Industry Challenges
- ISO 22000 Certification Timelines:Food safety management system audits delay customer qualification for export-oriented processors.
- Alkali Extraction Process Integration:Legacy aqueous isolation equipment requires capital retrofitting to meet pharmaceutical-grade purity specifications.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tamarind Gum Derivatives Market Trends and Innovations
Formulation science is converging with regulatory compliance requirements to reshape how tamarind gum derivatives qualify for premium pharmaceutical and clean-label food applications.
Enzymatic refinement protocols for tamarind seed polysaccharide is hybridizing molecular weight distribution control with cold-water solubility enhancement. Ophthalmic formulation houses in Japan and Germany are adopting these modified hydrocolloids for sustained-release matrices. The technology is compressing synthetic excipient dependence in ocular drug delivery systems.
REACH registration deadlines for polymer additives are forcing Indian exporters to consolidate batch testing documentation ahead of ECHA compliance windows. Small-volume hydrocolloid specialists face disproportionate cost absorption relative to multi-product chemical distributors. Pharmaceutical-grade tamarind derivatives entering EU cosmetic channels bear the heaviest documentation burden.
Long-term supply agreements with seed collection cooperatives are replacing spot-market procurement for processors seeking FSSAI clean-label certification. Gujarat-based manufacturers are locking in backward sourcing arrangements to satisfy customer traceability requirements. This pattern is most visible among exporters targeting Japanese pharmaceutical buyers with JIS-standard purity specifications.
Tamarind Gum Derivatives Market Segmentation
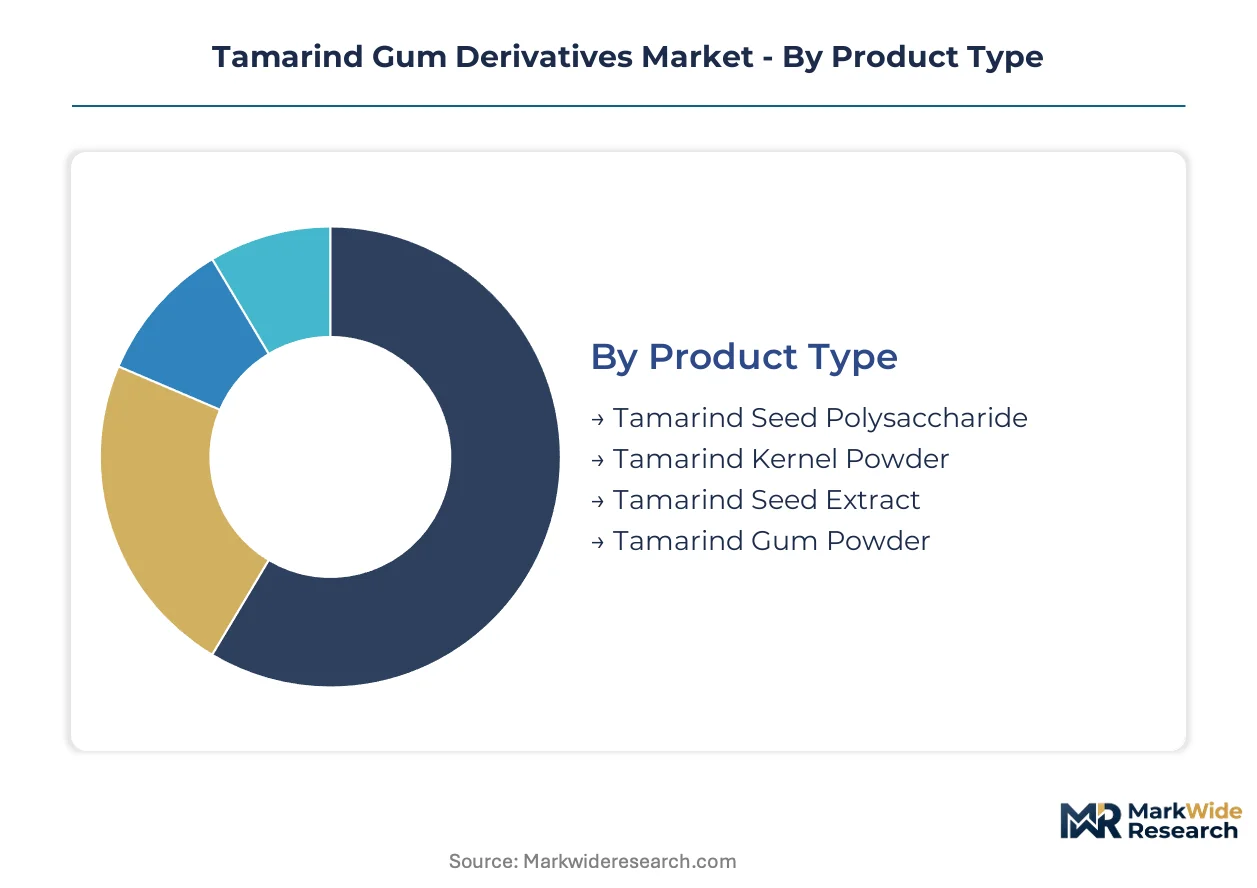
Tamarind gum derivatives fragment across purity grades and application specifications that dictate customer qualification timelines. Pharmaceutical-grade polysaccharides demand multi-year certification cycles, while industrial kernel powder turns over in quarterly procurement rhythms.
Product Type:
Refinement intensity separates segments by production cycle length, from same-day kernel milling to month-long polysaccharide isolation protocols.
- Tamarind Seed Polysaccharide:Refined xyloglucan with molecular weights between 50,000 and 600,000 Da enables cold-water solubility for ophthalmic drug delivery matrices. German and Japanese pharmaceutical formulators specify this grade for sustained-release excipient applications where EMA and PMDA biocompatibility standards apply.
- Tamarind Kernel Powder:Coarsely milled seed meal with residual protein and fiber content serves textile sizing and adhesive manufacturing. Gujarat-based textile mills in Surat and Ahmedabad consume this volume-grade material where cost efficiency outweighs refined performance specifications.
- Tamarind Seed Extract:Partially purified intermediate grade bridges food and cosmetic applications with moderate viscosity control.
- Tamarind Gum Powder:Standardized thickening agent for FSSAI-regulated packaged foods requiring clean-label hydrocolloid disclosure.
Tamarind Kernel Powder dominates installed base. Tamarind Seed Polysaccharide is where expansion concentrates.
Application:
Regulatory burden stratifies segments, with pharmaceutical channels imposing REACH and EMA documentation costs that food and textile applications avoid.
- Pharmaceutical Formulations:Ophthalmic and sustained-release drug delivery systems substitute plant-derived excipients for synthetic alternatives. EMA novel food pathways and PMDA master file submissions govern market access for Indian suppliers targeting European and Japanese buyers.
- Food & Beverage:Clean-label thickening and stabilizing functions in packaged foods, beverages, and dairy alternatives. FSSAI mandates source disclosure for hydrocolloid additives, compressing qualification timelines for Gujarat processors seeking domestic certification.
- Textile Printing:Sizing agent for cotton and synthetic yarn processing where xanthan gum competes on cost.
- Cosmetic Preparation:Natural rheology modifier for skin and hair care formulations under EU cosmetic regulation scrutiny.
- Adhesives:Binder component in paper and wood glue manufacturing with price-sensitive procurement patterns.
Food & Beverage anchors volume consumption. Pharmaceutical Formulations is climbing the fastest as synthetic excipient substitution accelerates.
End User Industry:
Customer scale separates segments, from multinational pharmaceutical qualification programs to fragmented textile mill spot purchasing.
- Pharmaceutical Companies:Formulation houses in Germany, Japan, and Switzerland specify JIS-standard and EP-grade polysaccharides for ocular and controlled-release applications. CDSCO and EMA regulatory convergence shapes supplier selection criteria for Indian exporters.
- Food Processing Units:Domestic and export-oriented packaged food manufacturers across Maharashtra and Karnataka drive FSSAI-compliant hydrocolloid procurement.
- Personal Care Manufacturers:Cosmetic formulators seeking REACH-registered natural thickeners for EU market access.
- Textile Manufacturers:Surat and Tiruppur cluster mills consuming kernel powder for warp sizing operations.
Food Processing Units command aggregate volume. Pharmaceutical Companies is where margin expansion concentrates.
Distribution Channel:
Relationship intensity varies by channel, from multi-year direct supply agreements to transactional wholesale spot markets.
- Direct Sales:Long-term contracts between Gujarat processors and Japanese pharmaceutical buyers with JIS-standard audit requirements. ECHA REACH documentation transfers directly from manufacturer to importer, reducing compliance friction.
- Distributors:Regional agents aggregating fragmented textile and food industry demand across western India.
- Online Retailers:Small-volume cosmetic and specialty food ingredient procurement with limited regulatory documentation.
- Wholesale Suppliers:Commodity kernel powder trading through Ahmedabad and Rajkot agricultural markets.
Direct Sales dominates pharmaceutical-grade value capture. Distributors is where mid-market expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for specialty chemicals is accelerating domestic gum derivative capacity expansion. FSSAI clean-label mandates compress qualification timelines for regional processors. EFSA novel food pathways govern European market access for tamarind-derived additives.
India
Gujarat and Rajasthan cultivation clusters supply raw material to gum processors concentrated in Ahmedabad and Rajkot. FSSAI mandates source disclosure for hydrocolloid additives in packaged foods. Surat textile mills consume volume-grade kernel powder for warp sizing operations.
Japan
Ophthalmic formulation houses specify JIS-standard polysaccharides for sustained-release matrices. PMDA master file submissions govern market access for Indian suppliers. Tokyo and Osaka pharmaceutical clusters drive premium excipient procurement.
Germany
EMA biocompatibility standards apply to refined tamarind seed polysaccharide for drug delivery systems. REACH registration deadlines force consolidation of batch testing documentation. Frankfurt and Stuttgart formulation houses substitute plant-derived excipients for synthetic alternatives.
United States
FDA oversight applies to pharmaceutical-grade hydrocolloids entering ocular and controlled-release applications. Clean-label food manufacturers seek plant-derived thickeners for packaged goods. New Jersey and California formulation clusters import refined polysaccharides for specialty applications.
South Korea
MFDS pharmaceutical regulations shape supplier selection criteria for excipient procurement. Cosmetic formulators seek natural rheology modifiers for skin and hair care products. Seoul and Busan manufacturing clusters represent underpenetrated channels relative to European sourcing.
Tamarind Gum Derivatives Market Competitive Landscape
On the supply side, the industry is fragmented across regional processors with flexible capacity and specialized hydrocolloid blenders serving exacting specifications. Three archetypes dominate: backward-integrated seed processors controlling raw material cycles, specialized blenders anchoring pharmaceutical relationships, and geographic concentrators exploiting proximity to cultivation clusters. Competitive moves concentrate on long-term supply agreements with seed collection cooperatives and enzymatic refinement protocol adoption.
Among India-based processors, JD Gums & Chemicals exemplifies backward-integrated archetypes through captive seed sourcing arrangements. Lucid Colloids occupies a position within the specialized blending tier, while Indian Hydrocolloids represents geographic concentration advantages within Gujarat's tamarind belt. These three anchors illustrate how competitive positioning stratifies across raw material control, technical capability, and logistics optimization rather than scale alone.
| Leading Market Players |
|---|
| JD Gums & Chemicals |
| Chemtotal Labs |
| Wonyoung Industrial |
| Adachi Group |
| Lucid Colloids |
| Indian Hydrocolloids |
| Socius Ingredients |
| Meckoni Impex |
| Altrafine Gums |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in pharmaceutical-grade polysaccharide refining is compressing supplier margins while amplifying pricing power for certified processors serving EMA and PMDA channels. Gujarat-based manufacturers face divergent incentives: expand alkali extraction capacity for premium grades or retreat to volume kernel powder sales.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and industrial-grade tamarind derivatives. Three-tier pricing structure across pharmaceutical, food-grade, and textile applications reflects FSSAI disclosure requirements and REACH registration burdens. Pricing pressure stems from xanthan gum substitution in textile sizing where cost compression dominates procurement criteria. Food processing units exhibit highest price sensitivity due to clean-label mandates without corresponding margin recovery mechanisms.
Supply Chain Analysis
REACH registration requirements for polymer additives limit small-batch hydrocolloid flows into EU cosmetic channels. Raw material sourcing concentrates in Gujarat and Rajasthan cultivation belts, with seed collection networks feeding Ahmedabad and Rajkot processing hubs. Supply chain risk centers on monsoon-dependent agricultural yields creating single-source vulnerability for western Indian tamarind kernels. Distribution runs through direct sales agreements for pharmaceutical grades and wholesale agricultural markets for industrial kernel powder.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Japanese pharmaceutical formulators and German ophthalmic houses as supplier qualification programs consolidate around JIS-standard and EP-grade certifications.
For Market Incumbents: Build regulatory moats through ECHA REACH dossier completion and PMDA master file submissions ahead of compliance windows. JD Gums & Chemicals demonstrates backward integration into seed sourcing as a defensive template against raw material volatility. Lucid Colloids anchors pharmaceutical relationships through enzymatic refinement protocol investments that synthetic excipient competitors cannot replicate. For New Entrants and Emerging Players: Build out toll manufacturing capacity for FSSAI-compliant food-grade hydrocolloids before committing to pharmaceutical-grade alkali extraction infrastructure. South Korean cosmetic formulators seeking natural rheology modifiers represent the most penetrable channel relative to saturated European sourcing. Target cell-cultured meat stabilization applications where plant-derived hydrocolloid demand outpaces established supplier relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade polysaccharide refining as enzymatic protocols replace legacy aqueous extraction. Acquisition targets should display captive seed supply agreements with Gujarat collection cooperatives and existing ISO 22000 certification. Monitor EFSA novel food pathway approval timelines as the signal indicating expanded European market access for certified Indian processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Sourcing | Captive supply from Gujarat collection networks reduces monsoon-driven margin volatility. |
| Enzymatic Refinement Protocol Adoption | Cold-water solubility enhancement opens ophthalmic drug delivery channels in Japan and Germany. |
| REACH Registration Completion | ECHA compliance unlocks EU cosmetic and pharmaceutical channels previously blocked to uncertified exporters. |
| Long-term Supply Agreement with Cooperatives | FSSAI traceability requirements favor processors with locked seed procurement arrangements. |
| Pharmaceutical-Grade Capacity Expansion | Alkali extraction retrofitting captures premium excipient demand from synthetic substitution trends. |
Research Methodology
Initial hypotheses were tested against primary input from gum processing plant managers, pharmaceutical formulation executives, textile procurement leads, and FSSAI regulatory consultants and refined through secondary validation. Customs records from DGFT, FSSAI additive disclosure filings, CDSCO excipient registration databases, and JIS hydrocolloid standards provided triangulation anchors. Bottom-up capacity estimates from Gujarat and Rajasthan processing facilities were cross-checked against top-down demand projections from end-use industries.
Demand-supply balance modeling across the projection horizon incorporated grade tier, end-use industry, and regional regulatory cluster segmentation. CAGRs were derived from installed capacity trajectories and substitution elasticity estimates for synthetic excipients. Forecast inputs included monsoon yield variability for tamarind seed supply and EMA/PMDA approval velocity for novel plant-derived excipients.
Stress conditions across seed price volatility, REACH registration cost absorption, and xanthan gum substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway timelines and clean-label definition stability. Material shifts in EFSA novel food approval criteria or FSSAI hydrocolloid disclosure mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.