
 Drilling Fluid Additives Market | 2026-2036
Drilling Fluid Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Drilling Fluid Additives Market Analysis
REACH compliance is rebalancing the cost-of-entry calculus for European suppliers of drilling fluid additives, compelling substitution of legacy chrome lignosulfonate dispersants with bio-based alternatives. Schlumberger Limited leverages its integrated drilling services platform to bundle specialty chemical packages with directional drilling contracts. Halliburton Company sustains manufacturing scale across its Baroid product line, anchoring supply security for high-temperature high-pressure wells. Baker Hughes Company differentiates through nano-particle fluid systems that reduce formation damage in unconventional reservoirs.
Drilling fluid additives comprise chemically engineered compounds—viscosifiers, fluid loss control agents, surfactants, and weighting materials—dispersed in aqueous, oil-based, or synthetic base fluids to manage downhole pressure, lubricate drill strings, and stabilize wellbores. These formulations typically operate at densities between 8.3 and 22 pounds per gallon and must maintain rheological stability across temperature ranges exceeding 350°F in deep wells. Fluid loss control agents command the thickest margin pools due to their critical role in preventing differential sticking and formation invasion, while viscosifiers represent the most mature segment with commoditized pricing. Offshore drilling applications are outgrowing onshore counterparts as operators push into deeper water with longer lateral sections requiring customized additive packages.
The EPA enforces discharge limitations under the National Pollutant Discharge Elimination System, directly shaping formulation choices for US offshore operations. ECHA's REACH restrictions on chromium and aromatic hydrocarbons are redirecting European procurement toward synthetic base fluids and bio-polymer viscosifiers. Brazil's national petroleum regulator, ANP, mandates local content requirements that influence supply chain configuration for pre-salt development. Stakeholders must monitor the divergence between regional chemical approval frameworks, as compliance in one jurisdiction no longer guarantees market access in another.
Market Dynamics
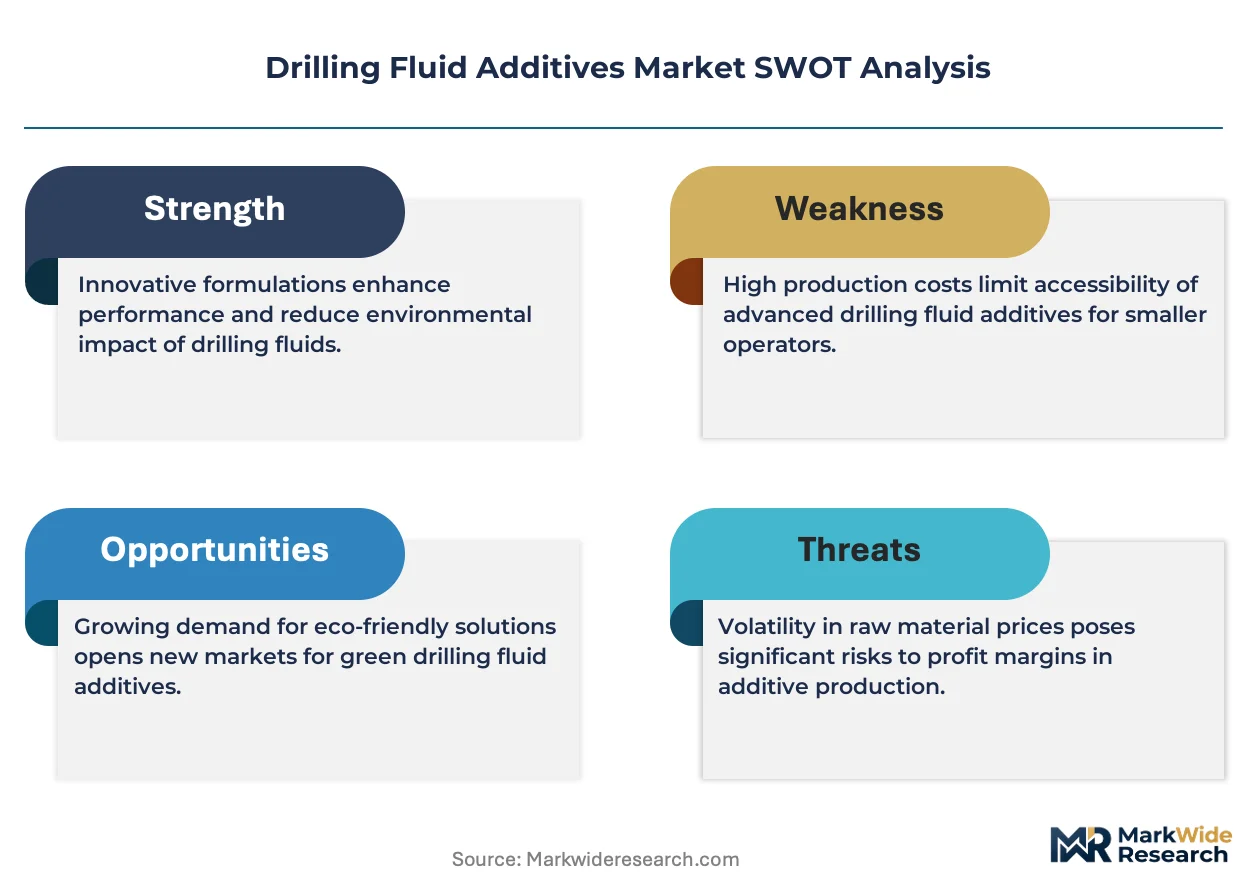
REACH compliance is forcing European suppliers to abandon chrome lignosulfonate dispersants, triggering a wave of bio-polymer substitution that is redrawing raw material procurement networks and reformulation cost structures across the continent.
Growth Catalysts
- Deepwater expansion in Brazil:Petrobras operations in pre-salt basins require high-performance rheology modifiers for ultra-deep wells, sustaining demand for advanced synthetic-based fluid systems.
- EPA discharge standards:Updated National Pollutant Discharge Elimination System limitations for drilling waste are compelling US offshore contractors to upgrade to higher-tier additive packages.
- Synthetic base fluid adoption:Gulf of Mexico and North Sea contractors are migrating from oil-based systems to synthetic alternatives that deliver superior environmental compliance without sacrificing temperature stability.
Market Restraints
- Barite supply concentration:Weighting material sourcing depends heavily on Chinese export quotas and domestic processing capacity, exposing formulators to price volatility and availability risk.
- REACH transition costs:ECHA restrictions on chromium compounds and aromatic hydrocarbons are imposing reformulation expenses that compress margins for legacy product lines.
- Technical performance gaps:Bio-based viscosifiers currently fail to match xanthan gum thermal stability above 300°F, limiting substitution in high-temperature high-pressure applications.
Strategic Opportunities
- West African offshore:Senegal and Mauritania basin development by international operators is creating demand for deepwater-capable fluid systems with local logistics support.
- Geothermal drilling crossover:High-temperature fluid formulations developed for oil and gas are finding application in geothermal well construction, opening adjacent revenue streams.
- EU Green Deal procurement incentives:Public tender preferences for low-carbon drilling services are steering contractor selection toward suppliers with certified bio-based additive portfolios.
Industry Challenges
- Rheology specialist shortage:Formulation chemists capable of tuning non-Newtonian behavior across extreme pressure-temperature windows remain scarce relative to deployment needs.
- Multi-jurisdiction approval timelines:Securing simultaneous acceptance from EPA, ECHA, and ANP for novel chemistries extends product launch cycles by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drilling Fluid Additives Market |
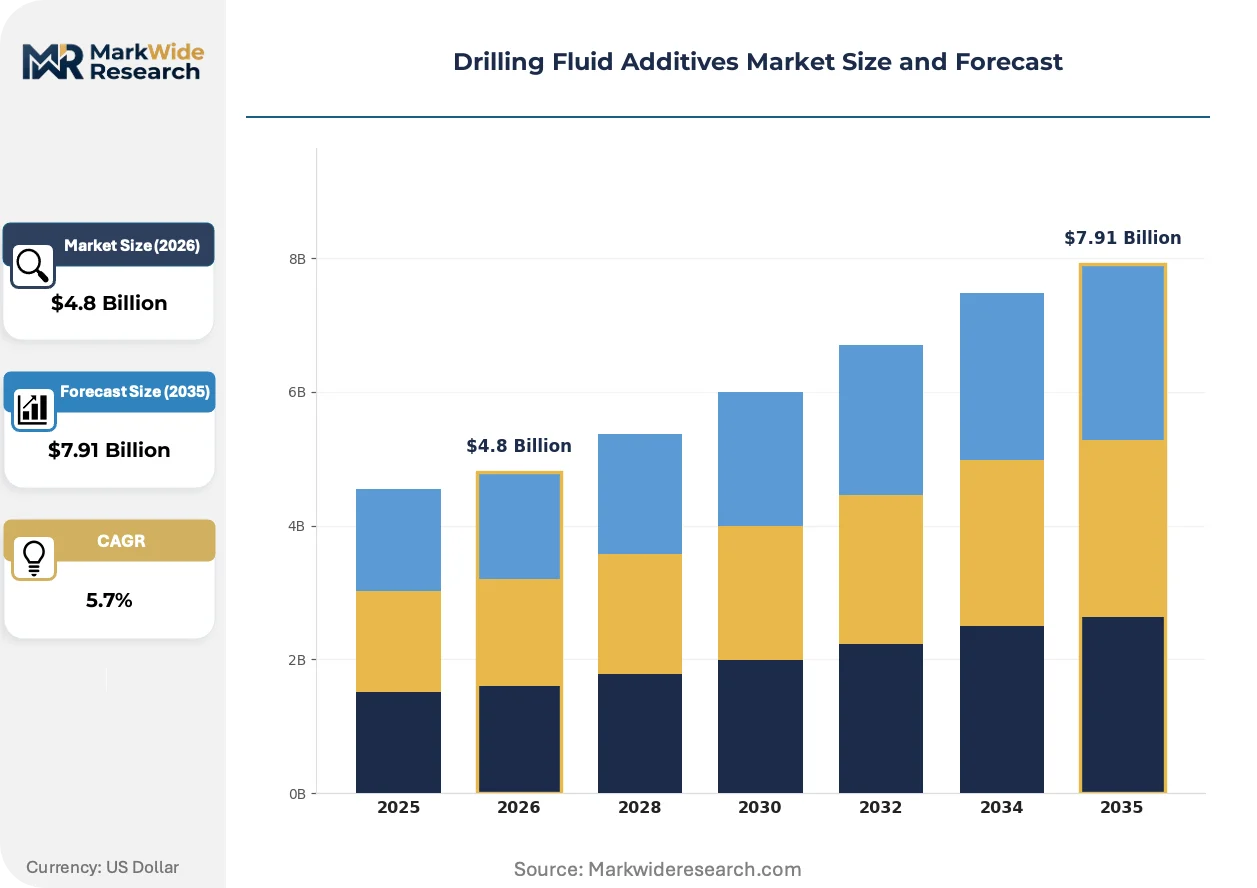
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Viscosifiers, Fluid Loss Control Agents, Viscosifying Agents, Surfactants Application: Onshore Drilling, Offshore Drilling, Workover Operations, Completion Operations End User: Oil & Gas Producers, Drilling Contractors, Geothermal Energy, Mining Companies Delivery Mode: Bulk Supply, Packaged Solutions, Specialty Blends, Custom Formulations |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, BASF SE, Chevron Phillips Chemical Company LLC, Akzo Nobel N.V., Dow Inc., Newpark Resources Inc., Tetra Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drilling Fluid Additives Market Emerging Trajectories
Formulation science is converging with digital well monitoring, enabling real-time additive adjustment that responds to downhole conditions rather than pre-set treatment schedules.
Nano-particle fluid systems are expanding into unconventional reservoir development, where Baker Hughes and specialized chemical suppliers deploy iron oxide and silica nanoparticles to reduce formation damage and improve fracture conductivity. Permian Basin operators are adopting these systems for extended-reach laterals where conventional fluid invasion risks production impairment. The technology is expanding into mid-tier independent producers previously priced out of premium chemistry.
REACH authorization requirements are tightening control over chromium(VI) compounds and polycyclic aromatic hydrocarbons in drilling fluids, forcing European formulators to validate bio-polymer alternatives through extensive downhole testing. The regulation is compressing the viable product portfolio for suppliers serving EU offshore platforms. North Sea contractors are responding by accelerating qualification of synthetic base fluids that eliminate aromatic content while maintaining lubricity performance.
Integrated service contracts are bundling specialty chemicals with directional drilling and logging services, compressing standalone additive procurement. Operators in the Gulf of Mexico and Brazil are consolidating vendor relationships to reduce interface risk and secure volume pricing. This consolidation is most visible among supermajors executing multi-rig campaigns where chemistry consistency across sequential wells outweighs spot-sourcing flexibility.
Drilling Fluid Additives Market Segmentation
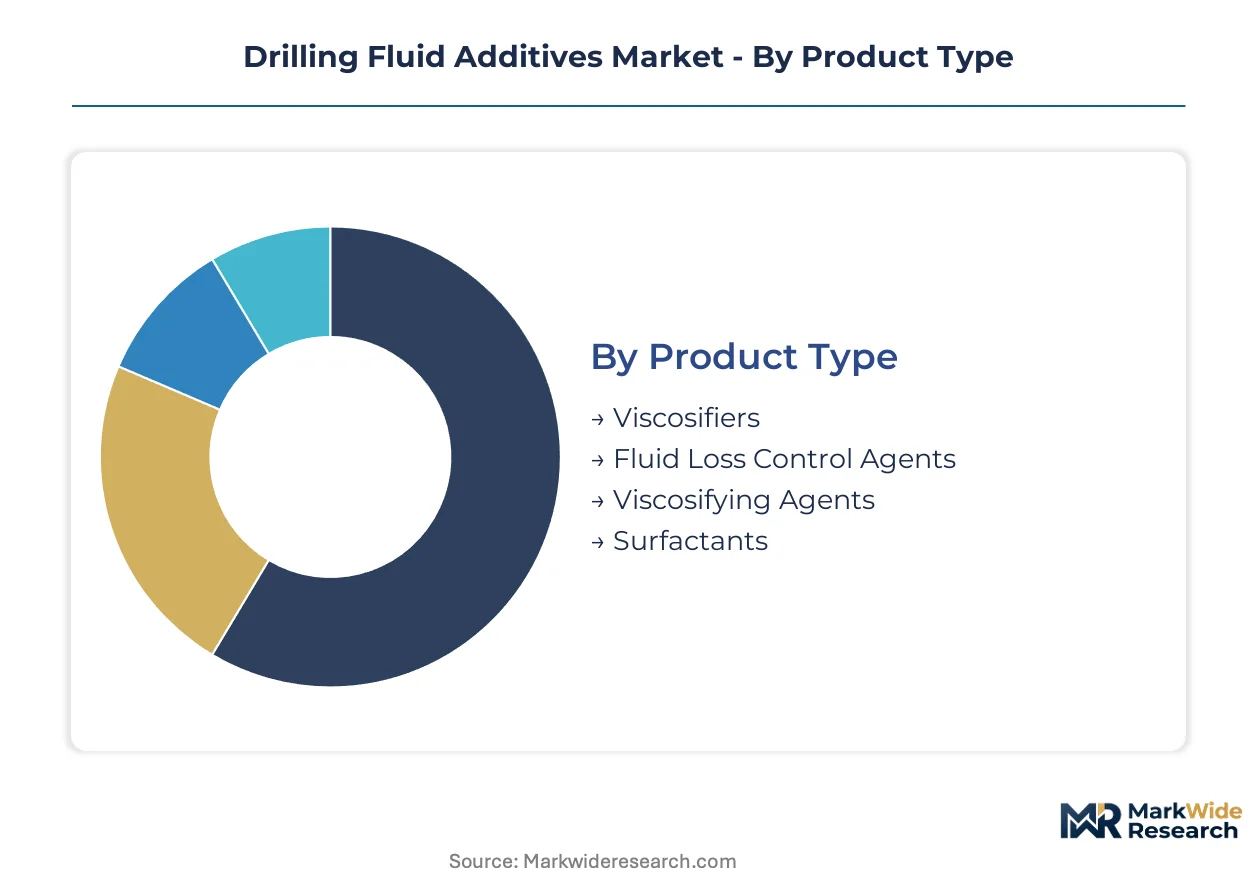
Drilling fluid additives segment along four dimensions that determine procurement patterns and margin capture. Product chemistry dictates performance ceilings in high-pressure high-temperature wells. Application context shapes environmental compliance burdens and logistics complexity.
Product Type:
Reformulation cycles are accelerating as operators replace legacy chemistries with regulatory-compliant alternatives.
- Fluid Loss Control Agents:These polymers and starches form impermeable filter cakes across permeable formations. Demand concentrates in Brazil's pre-salt basins where ultra-deep wells require minimal fluid invasion to protect reservoir productivity. Petrobras specifications for synthetic-based systems are driving premium-grade polymer adoption.
- Viscosifiers:Xanthan gum and guar derivatives dominate rheology management in conventional drilling. Gulf of Mexico contractors are upgrading to thermal-stable variants as laterals extend into hotter sections. The segment faces substitution pressure from bio-polymer alternatives where REACH compliance mandates chemistry changes.
- Viscosifying Agents:Synthetic polymers including PHPA and copolymers provide shear-thinning behavior for directional drilling. Shale inhibition requirements in Permian Basin laterals sustain demand.
- Surfactants:Emulsifiers and wetting agents stabilize oil-based and synthetic fluid systems. North Sea operators prioritize low-toxicity formulations meeting OSPAR discharge standards.
Fluid loss control agents sit at the top of the volume ranking, with viscosifiers climbing the fastest as lateral lengths extend.
Application:
Operational setting determines base fluid selection and environmental scrutiny intensity.
- Offshore Drilling:Deepwater and ultra-deepwater operations require synthetic-based systems with engineered rheology profiles. Gulf of Mexico contractors face EPA NPDES discharge limits that favor biodegradable additives. Brazil's pre-salt development anchors demand for high-density formulations exceeding 18 pounds per gallon.
- Onshore Drilling:Unconventional shale plays in the Permian and Appalachian basins drive consumption of water-based systems with friction reducers. Extended-reach laterals exceeding 15,000 feet demand lubricity packages and torque reducers. Cost pressure from independent producers sustains commodity-grade additive procurement.
- Workover Operations:Well intervention chemistry prioritizes compatibility with existing completion fluids and minimal formation damage. Mature field rehabilitation in the North Sea generates steady demand for filter cake breakers and chelating agents.
- Completion Operations:Gravel pack and frac pack fluid systems require bridging agents and breakers that degrade predictably. Saudi Aramco tight gas developments specify residue-free polymer systems.
Offshore drilling commands the highest per-well additive intensity, with onshore unconventional applications expanding most quickly.
End User:
Customer scale and technical capability shape specification authority and contract structure.
- Oil & Gas Producers:Supermajors and national oil companies set chemistry standards that cascade through drilling contractor supply chains. ExxonMobil and Shell internal specifications for deepwater systems exceed API minimums, forcing additive suppliers into qualification protocols lasting 12-18 months.
- Drilling Contractors:Transocean and Seadrill procure additive packages as part of integrated drilling services. Their buying power concentrates volume with suppliers offering global logistics and technical service networks.
- Geothermal Energy:High-temperature well construction borrows oilfield chemistry for silica scaling control and lost circulation management. Iceland and Kenya developments are adopting modified drilling fluid systems.
- Mining Companies:Large-diameter raise boring and exploration drilling consumes bentonite and polymer systems at lower specification tiers than hydrocarbon applications.
Oil and gas producers anchor procurement value, with geothermal energy gaining share fastest as renewable drilling scales.
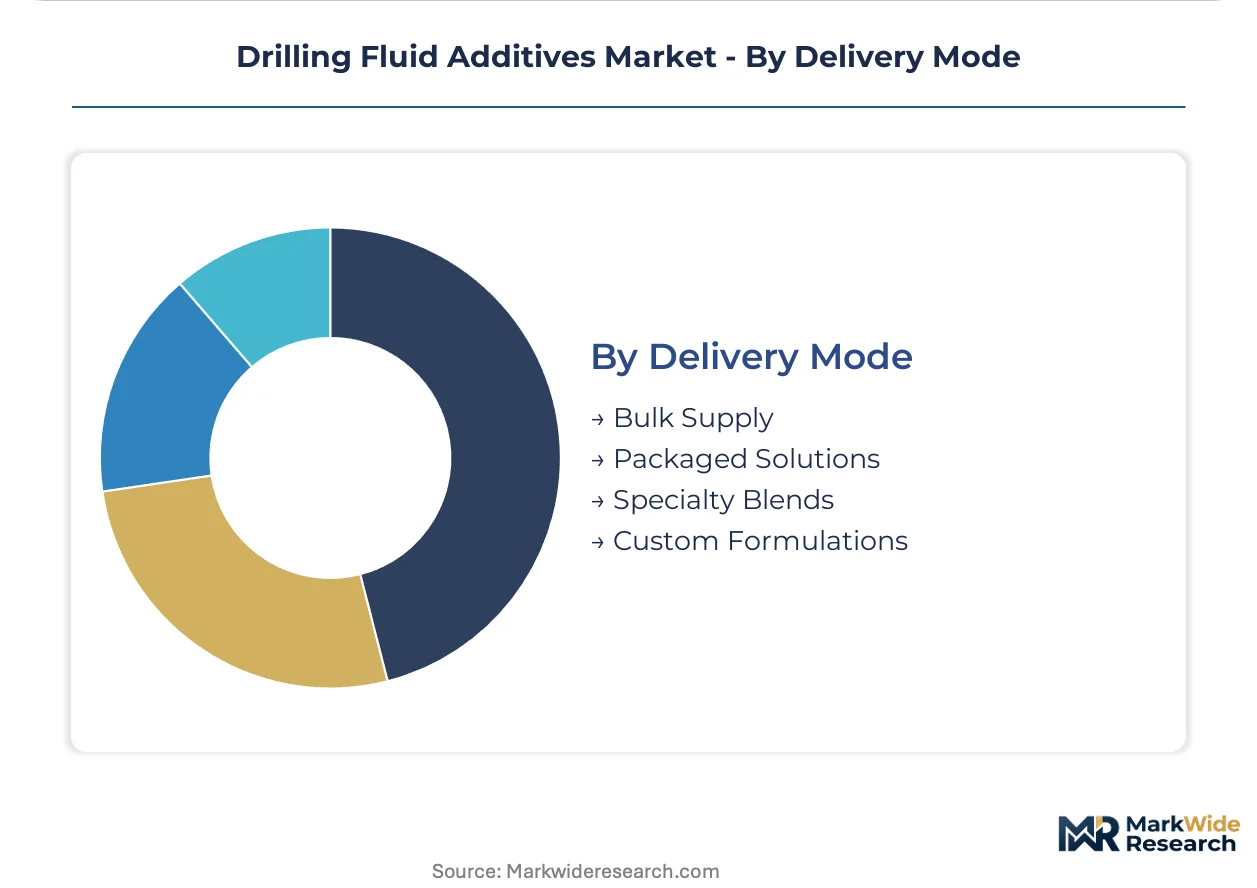
Delivery Mode:
Supply format determines inventory carrying costs and formulation flexibility at the rig site.
- Bulk Supply:Barite and base fluids move through pneumatic delivery systems to offshore platforms and large onshore camps. Chinese export quotas on barite ore concentrate sourcing risk with three major processors controlling seaborne supply.
- Packaged Solutions:Pre-weighed sacks of polymers and specialty additives reduce mixing error and inventory tracking burden. Independent Permian Basin operators favor 50-pound sacks for remote pad drilling.
- Specialty Blends:Pre-mixed lubricant and inhibitor packages save rig time in high-dayrate offshore environments. Baker Hughes and Halliburton deploy proprietary blend skids to contracted rigs.
- Custom Formulations:Engineered systems for HPHT wells or reactive shale formations involve laboratory validation and field trials. ANP local content requirements in Brazil mandate domestic blending for pre-salt contracts.
Bulk supply handles the greatest tonnage, with custom formulations expanding most quickly as well complexity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The drilling fluid additives industry traces its commercial origins to early twentieth-century American oilfield chemistry, when Gulf Coast operators first systematized mud engineering for controlling downhole pressures in the Spindletop era.
United States
Deepwater exploration in the Gulf of Mexico and Permian Basin unconventional development sustain additive demand for synthetic-based systems and extended-reach laterals. The EPA's National Pollutant Discharge Elimination System mandates biodegradable formulations for offshore discharge. Houston anchors the industry's service headquarters, with formulators maintaining blending facilities along the Texas and Louisiana coasts to support offshore logistics.
Brazil
Petrobras pre-salt development in ultra-deepwater basins requires high-density synthetic fluids exceeding eighteen pounds per gallon and specialized rheology modifiers. ANP local content regulations mandate domestic blending and procurement quotas for foreign suppliers. Macaé and Rio de Janeiro host the primary supply chain clusters serving Campos and Santos basin drilling campaigns.
Norway
North Sea maturing fields and new frontier exploration in the Barents Sea sustain demand for environmentally compliant synthetic systems. OSPAR discharge standards and REACH implementation drive substitution of oil-based fluids with low-aromatic alternatives. Stavanger and Bergen concentrate technical service operations for Norwegian and UK continental shelf contracts.
China
Domestic shale gas development in Sichuan and offshore expansion in the South China Sea expand consumption of water-based and synthetic fluid systems. The Ministry of Ecology and Environment tightens drilling waste discharge protocols in sensitive coastal zones. Tianjin and Shanghai host formulation plants serving both domestic operators and export markets across Asia-Pacific.
Saudi Arabia
Aramco tight gas and offshore Red Sea exploration programs specify high-temperature fluid systems for HPHT well construction. The national oil company imposes rigorous qualification protocols that extend supplier onboarding timelines. Dhahran and Jubail Industrial City concentrate manufacturing and technical service capabilities for Middle East drilling campaigns.
Drilling Fluid Additives Market Vendor Landscape
The competitive structure tilts toward integrated oilfield service conglomerates with captive chemical manufacturing capabilities. Three to five global suppliers command the premium tier through bundled drilling services contracts, while regional formulators compete on price for standard additive procurement. The dominant archetypes comprise integrated service providers, standalone specialty chemical manufacturers, and national oil company affiliates. Competitive moves center on vertical integration into base fluid production and strategic partnerships with barite processors to secure weighting material supply.
Within the integrated service tier, Schlumberger Limited, Halliburton Company, and Baker Hughes Company exemplify the bundling model where specialty chemicals anchor comprehensive drilling contracts rather than standalone sales. Schlumberger represents the technology-intensive archetype with laboratory-to-wellbore formulation control. Halliburton occupies a position emphasizing manufacturing scale across established product lines. Baker Hughes sits within the innovation-focused segment through differentiated nano-particle fluid systems. These three entities collectively illustrate how service integration, manufacturing breadth, and technical specialization define competitive positioning in drilling fluid additives.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| BASF SE |
| Chevron Phillips Chemical Company LLC |
| Akzo Nobel N.V. |
| Dow Inc. |
| Newpark Resources Inc. |
| Tetra Technologies Inc. |
| Others |
Supply Flow & Price Mechanics
Barite ore costs cascade from Chinese mining concessions through seaborne logistics into three-tier pricing structures that separate premium synthetic-base fluid systems from commodity water-based formulations. Gulf of Mexico contractors absorb higher per-barrel chemistry expenses to meet EPA discharge mandates, while Permian Basin independents negotiate volume discounts on packaged polymer sacks.
Pricing Analysis
Contract-based long-term offtake dominates procurement for offshore drilling campaigns, with price differentiation anchored in certification grade and volume scale. Premium synthetic systems command substantial uplifts over oil-based alternatives due to REACH-compliant chemistry and thermal stability guarantees. Cost compression in standard-tier viscosifiers is intensifying because bio-polymer substitution erodes xanthan gum pricing power. National oil companies exhibit lowest price sensitivity, while independent Permian operators drive hardest bargain on spot purchases.
Supply Chain Analysis
ANP local-content mandates in Brazil are redirecting foreign suppliers toward domestic blending partnerships and joint-venture manufacturing. Raw material sourcing draws from Chinese barite processors, US Gulf Coast base fluid refiners, and European specialty polymer manufacturers. Single-source vulnerability concentrates in seaborne barite shipments subject to export quota volatility. Distribution runs through Houston and Macaé logistics hubs serving contracted offshore rigs with continuous replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drilling fluid additives function as a regulatory compounder where EPA discharge standard tightening and REACH authorization deadlines continuously reshape formulation demand. Compliance investments create sustainable competitive moats for suppliers with multi-jurisdiction approval capabilities.
For Market Incumbents: Extend synthetic-base fluid qualification pipelines into West African pre-salt basins before competitor laboratory capacity saturates. Deepen backward integration into barite processing through offtake agreements with Chinese ore exporters. Anchor supply security by securing volume commitments from Petrobras and supermajor drilling contractors executing multi-rig campaigns. For New Entrants and Emerging Players: Enter via geothermal drilling crossover applications where oilfield chemistry expertise transfers without established incumbent relationships. Target Kenya and Iceland high-temperature well construction as most penetrable geography. Pursue direct equipment bundling with directional drilling specialists lacking captive chemical manufacturing. For Investors and Strategic Acquirers: Consolidation pressure builds where standalone specialty chemical manufacturers lack integrated service contracts to defend margin capture. Five-to-ten year viability favors suppliers with ANP-approved Brazilian blending facilities and EPA-certified biodegradable portfolios. Watch synthetic-base fluid patent filings as inflection indicator for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barite Processing | Captive ore supply insulates formulators from Chinese export quota volatility. |
| Bio-Polymer R&D Partnership | Joint development with European biotech firms accelerates REACH-compliant viscosifier substitution. |
| Multi-Jurisdiction Regulatory Certification | Simultaneous EPA-ECHA-ANP approval compresses competitor launch timelines by 18-36 months. |
| Geothermal Application Expansion | High-temperature fluid formulations open adjacent revenue in Iceland and Kenya drilling. |
| Integrated Service Contract Bundling | Chemistry-directional drilling packages reduce interface risk for Gulf of Mexico supermajors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drilling fluid formulators, procurement leads at offshore contractors, technical R&D directors at service companies, and regulatory affairs specialists at national oil companies with secondary validation from EPA NPDES filings, ECHA REACH authorization databases, ANP local-content reports, and customs trade data on barite ore shipments. Bottom-up well-count modeling and top-down chemical consumption estimates were triangulated against disclosed supplier revenue segments.
Segment-weighting applied product type, application context, and end-user scale dimensions across the modeling period, with CAGRs derived from elasticity-adjusted drilling activity projections and per-well additive intensity curves. Synthetic-base fluid adoption rates, bio-polymer substitution timelines, and deepwater rig deployment schedules served as industry-specific forecast inputs.
Inputs from regulatory filing databases and contractor procurement disclosures were available through the study window; gaps in real-time inventory positioning data introduce uncertainty bands around short-term pricing trajectory assumptions. Forecasts reflect documented elasticity parameters and scenario-weighted regulatory implementation schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global UV Absorbers Market
Additives
Global Sodium Acetate Market
Additives
Fuel Additives Market
Additives
Agrochemicals Additives Market
Additives
Sodium Metabisulfite Market
Additives
Combustion Clean-Up Additives for High-Mileage Fleets Market
Additives
Biofuel Additives Market
Additives
Global Pour Point Depressant Market
Additives
Fluoropolymer Additives Market
Additives
Printing Ink Additives Market
Additives
Alkyl Acetates Market
Additives
Marine Fuel Additives Market
Additives
Europe Anti-Caking Market
Additives
Sodium Citrate Dihydrate Market
Additives
Glycol Acetate Market
Additives
Propyl Gallate Market