
 Asia-Pacific Concrete Admixtures Market | 2026-2036
Asia-Pacific Concrete Admixtures Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Concrete Admixtures Market Outlook
High-performance grade specifications for marine and seismic-zone concrete is redrawing competitive priorities across the Asia-Pacific. BASF SE leverages its R&D intensity in polycarboxylate ether superplasticizers to anchor premium positioning in Japan and Australia. Sika AG sustains manufacturing scale advantages through integrated supply chains in China and Southeast Asia. Sobute New Materials competes on cost-engineered formulations tailored to domestic infrastructure tenders.
Concrete admixtures encompass chemical additives—typically dosed at one to five percent by weight of cement—that modify fresh or hardened concrete properties through controlled hydration kinetics, air entrainment, or rheological adjustment. Water-reducing admixtures dominate volume flows across the region, reflecting their indispensability in high-strength mix designs for vertical construction and transportation infrastructure. Infrastructure development applications represent the fastest-expanding demand pool, driven by tunnel, bridge, and rail investments in Indonesia, Vietnam, and the Philippines where extended workability and accelerated strength gain carry premium value. Liquid formulations lead form-level consumption due to metering precision and batching-plant compatibility, though powder variants retain share in remote job sites with limited storage.
China's SAMR enforces GB standards governing chloride content and compatibility testing, while India's BIS mandates IS 9103 certification for chemical admixtures used in government-funded projects. Japan's METI promotes JIS-compliant low-carbon concrete through building code incentives that reward embodied-carbon reductions. Australia's NCC and state-level environmental regulations in New South Wales and Victoria are tightening disclosure requirements for construction chemical sourcing. Stakeholders must monitor evolving carbon-border adjustments and green procurement criteria that will increasingly determine specification eligibility in public tenders across the region.
Market Dynamics
China's dual carbon goals and tightening GB standards are compressing the viable formulation window for conventional admixtures, forcing suppliers to requalify entire product portfolios for low-carbon certification eligibility.
Growth Catalysts
- Marine-grade specification expansion:Indonesia's port modernization and Vietnam's coastal highway program are mandating sulfate-resistant formulations with extended workability windows.
- Smart city infrastructure deployment:India's National Infrastructure Pipeline is channeling procurement toward self-compacting concrete admixtures for dense urban vertical construction.
- Japan's METI low-carbon building incentives:JIS-compliant embodied-carbon thresholds are rewarding specification of recycled-content and bio-based plasticizers in public tenders.
Market Restraints
- Naphtha and ethylene oxide feedstock volatility:Polycarboxylate ether precursor costs fluctuate with regional petrochemical pricing, compressing margin stability for formulation specialists.
- China supply concentration:Over half of regional superplasticizer active ingredient capacity clusters in Shandong and Jiangsu provinces, creating geographic vulnerability.
- Chloride compatibility testing delays:SAMR's GB/T 8077 enforcement timeline extends product registration cycles by four to six months.
Strategic Opportunities
- Philippines rail and tunnel buildout:The "Build Better More" program's underground metro lines require accelerators and retarders with 12-hour workability control.
- Australia's NCC embodied-carbon disclosure rules:New South Wales and Victoria procurement guidelines are creating first-mover advantage for Environmental Product Declaration-certified suppliers.
- Digital dosing system integration:IoT-enabled batching plant retrofits in South Korea and Taiwan are opening specification channels for precision-metered liquid formulations.
Industry Challenges
- Rheology technician shortage:Formulation labs across Southeast Asia lack sufficient trained personnel for complex polycarboxylate molecular weight customization.
- Cross-border formulation registration:Each ASEAN member maintains distinct admixture testing protocols, fragmenting product standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Concrete Admixtures Market |
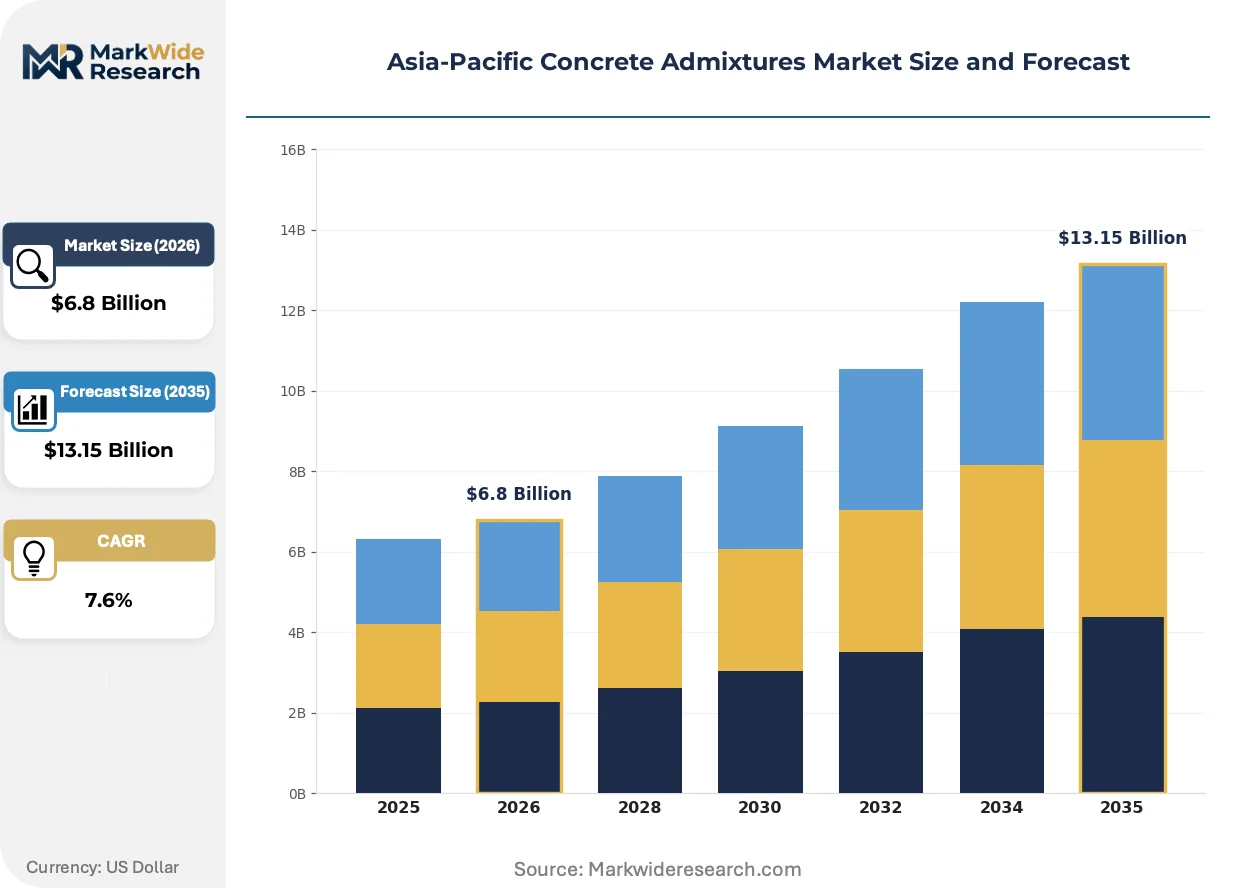
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Reducing Admixtures, Retarding Admixtures, Accelerating Admixtures, Air-Entraining Admixtures Application: Residential Construction, Commercial Construction, Infrastructure Development, Industrial Construction Form: Liquid, Powder, Granular, Paste End User: Contractors, Builders, Construction Companies, Civil Engineers |
| Companies Covered | BASF SE, Sika AG, GCP Applied Technologies, MAPEI S.p.A., Fosroc International Limited, Master Builders Solutions, RPM International, Kao Corporation, Sobute New Materials Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Concrete Admixtures Market Strategic Shifts
Admixture chemistry is pivoting from universal performance claims toward application-specific certification bundles that align with national green building codes and infrastructure procurement mandates.
Polycarboxylate ether comb polymer architecture is fragmenting into niche variants optimized for specific cement chemistries and supplementary cementitious material blends. Indonesian precast producers and Australian high-rise contractors are adopting these tailored grades faster than commodity formulations. The result is compressing the addressable market for standardized PCE products while expanding premium formulation services.
China's SAMR is tightening GB 8076 enforcement for chloride ion content and freeze-thaw compatibility, eliminating marginally compliant imports from regional supply chains. India's BIS is synchronizing IS 9103 testing protocols with these stricter benchmarks. Japanese and Australian specification engineers are now prioritizing suppliers with dual GB/JIS or GB/AS certification coverage.
Specification authority is migrating from contractor procurement offices to EPC engineering teams with direct accountability for embodied-carbon targets. Design-build contracts in Vietnam and the Philippines now embed admixture selection into early-stage mix design optimization rather than late-stage cost engineering. South Korea's Green Building Certification System is accelerating this shift through carbon-budget compliance requirements.
Asia-Pacific Concrete Admixtures Market Segmentation
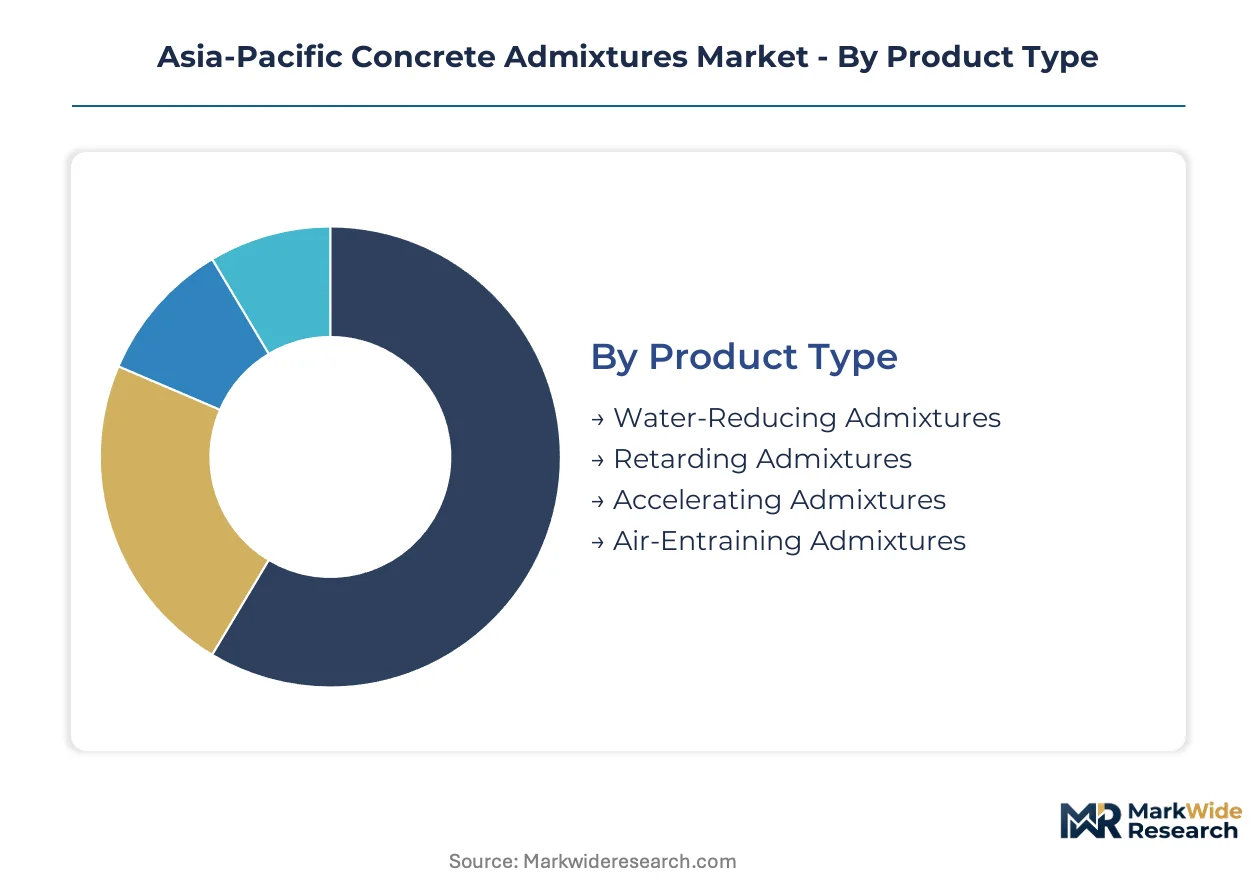
Segmentation in the Asia-Pacific concrete admixtures market reveals how regulatory frameworks and project specifications reshape procurement patterns across distinct product categories and application contexts. Understanding these divides clarifies where formulation investments concentrate and which customer segments command pricing power.
Product Type:
GB standards in China, IS 9103 in India, and JIS certification in Japan each impose distinct performance thresholds that favor certain chemistries over others in national procurement channels.
- Water-Reducing Admixtures:Polycarboxylate ether superplasticizers dominate high-strength mix designs for vertical construction and transportation infrastructure across the region. China's Shandong and Jiangsu provinces host over half of regional superplasticizer active ingredient capacity, creating supply concentration that shapes pricing dynamics for these formulations.
- Retarding Admixtures:Extended workability windows prove indispensable for Indonesia's port modernization and Vietnam's coastal highway programs where sulfate-resistant specifications mandate precise hydration control. Tropical climates and long-distance concrete transport amplify demand for these chemistries in Southeast Asian mega-projects.
- Accelerating Admixtures:Cold-weather construction and rapid formwork turnover in Japan's urban renewal projects sustain steady procurement of these formulations.
- Air-Entraining Admixtures:Freeze-thaw durability requirements under GB/T 8077 and comparable standards support consistent specification in northern China and mountainous regions.
Water-reducing admixtures handle the majority of throughput; accelerating admixtures are expanding most quickly on share as cold-climate and rapid-cure applications multiply.
Application:
Cost tier differentiation separates specification-grade projects with embodied-carbon compliance requirements from commodity construction where price sensitivity dominates procurement decisions.
- Infrastructure Development:Tunnel, bridge, and rail investments in Indonesia, Vietnam, and the Philippines generate premium demand for extended workability and accelerated strength gain. India's National Infrastructure Pipeline channels procurement toward self-compacting concrete admixtures for dense urban vertical construction, with western and southern states showing the most acute demand concentration.
- Commercial Construction:High-rise developments in Australia and South Korea require precision-metered liquid formulations compatible with IoT-enabled batching plant systems. New South Wales and Victoria procurement guidelines now mandate Environmental Product Declaration certification, creating first-mover advantage for compliant suppliers in this segment.
- Residential Construction:Volume-driven demand across India's urban corridors and Southeast Asian secondary cities favors cost-engineered formulations with standardized performance claims.
- Industrial Construction:Marine-grade and seismic-zone specifications in Japan and Australia command specialized formulation services rather than commodity products.
Infrastructure development generates the steepest expansion trajectory; residential construction maintains the largest absolute volume base.
Form:
Supply chain configuration favors liquid formulations where batching plant density supports precision metering, while powder variants retain relevance in remote job sites with limited storage infrastructure.
- Liquid:Metering precision and batching-plant compatibility make this the default choice for urban construction across China, Japan, and South Korea. IoT-enabled retrofits in Taiwan and South Korea are opening specification channels for precision-metered systems that integrate directly with plant control architecture.
- Powder:Remote job sites in the Philippines and Indonesian archipelago construction rely on powder variants where liquid storage and handling present logistical constraints.
- Granular:Niche applications in precast concrete production favor controlled dissolution rates that granular forms provide.
- Paste:Specialized repair and retrofit applications in Japan's aging infrastructure maintenance sector sustain limited but consistent demand.
Liquid formulations command the dominant share of form-level consumption; powder variants are climbing fastest as remote infrastructure buildouts accelerate.
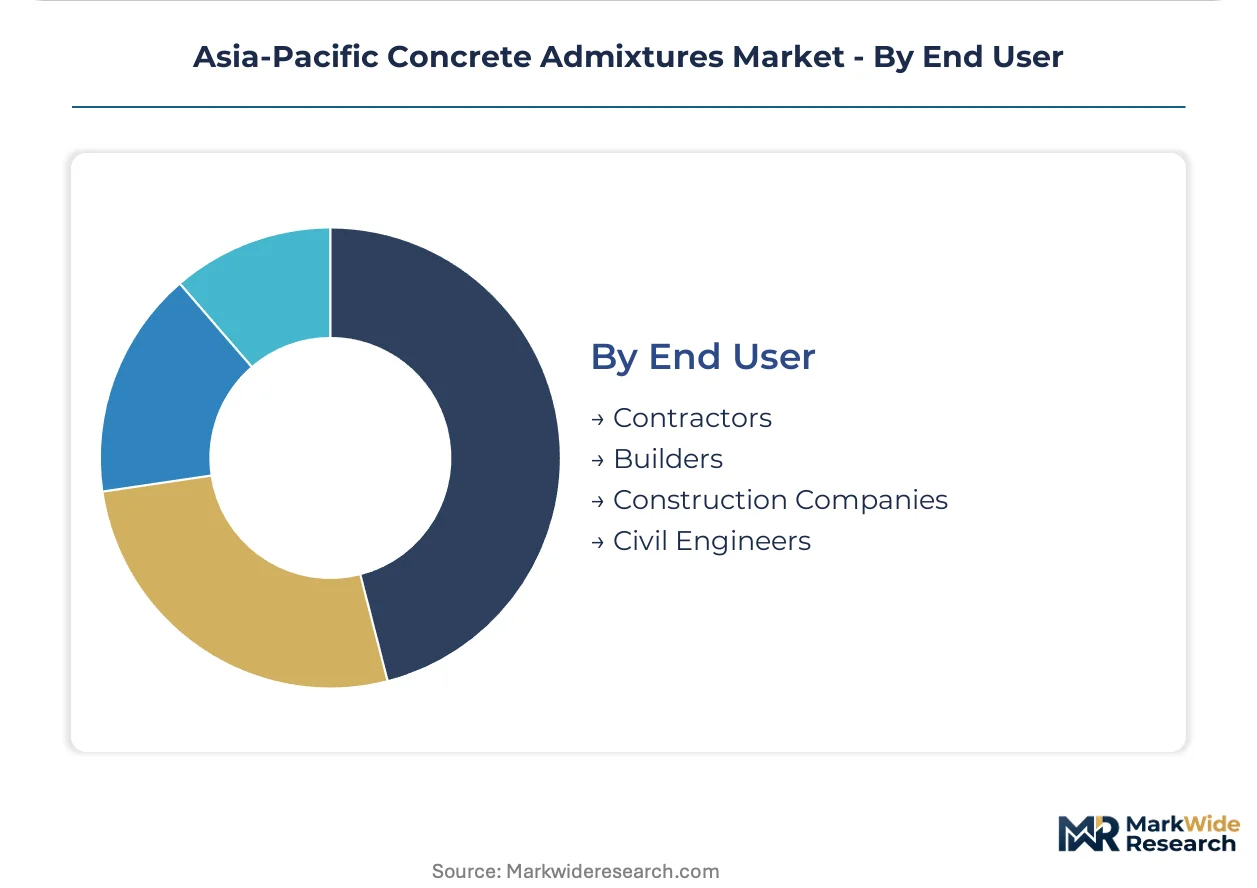
End User:
Customer type determines whether admixture selection occurs during early-stage mix design optimization or late-stage cost engineering, with significant margin implications for suppliers.
- Construction Companies:Large integrated firms with in-house engineering capabilities increasingly embed admixture selection into carbon-budget compliance frameworks. South Korea's Green Building Certification System accelerates this shift through mandatory embodied-carbon accounting.
- Civil Engineers:Specification authority migration toward EPC engineering teams with direct accountability for embodied-carbon targets elevates engineer influence over procurement decisions in Vietnam and Philippines design-build contracts.
- Contractors:Price-sensitive procurement in India's state-level infrastructure tenders favors cost-engineered formulations from domestic suppliers with BIS certification.
- Builders:Smaller-scale residential and commercial projects typically defer to contractor recommendations with limited independent specification authority.
Construction companies represent the largest demand pool by volume; civil engineers are gaining specification influence fastest as carbon-accounting requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports polycarboxylate ether superplasticizer active ingredients to Southeast Asian batching plants and precast facilities across Indonesia, Vietnam, and the Philippines. This trade corridor shapes formulation availability and pricing benchmarks throughout the region.
China
Shandong and Jiangsu provinces concentrate over half of regional superplasticizer capacity, supplying domestic mega-projects and export markets. SAMR enforces GB 8076 standards for chloride content and freeze-thaw compatibility, eliminating marginally compliant imports. The Yangtze River Delta industrial corridor drives premium demand for low-carbon certified formulations aligned with dual carbon goals.
India
Western and southern states generate acute demand concentration from urban corridor development and smart city investments under the National Infrastructure Pipeline. BIS mandates IS 9103 certification for chemical admixtures in government-funded projects. Maharashtra and Gujarat host the densest batching plant networks serving Mumbai-Ahmedabad industrial freight corridors.
Japan
METI promotes JIS-compliant low-carbon concrete through building code incentives rewarding embodied-carbon reductions. Kanto and Kansai regions sustain procurement of cold-weather accelerators for urban renewal projects. Tokyo-Osaka engineering consultancies increasingly embed admixture selection into early-stage carbon-budget compliance frameworks.
Indonesia
Port modernization and coastal highway programs mandate sulfate-resistant formulations with extended workability windows. The "Build Better More" program's underground metro lines in Jakarta require accelerators and retarders with 12-hour workability control. Java-based precast producers are adopting tailored polycarboxylate grades faster than commodity formulations.
Australia
New South Wales and Victoria procurement guidelines mandate Environmental Product Declaration certification, creating first-mover advantage for compliant suppliers. NCC embodied-carbon disclosure rules tighten construction chemical sourcing requirements. Sydney and Melbourne high-rise developments drive demand for precision-metered liquid formulations compatible with IoT-enabled batching systems.
Asia-Pacific Concrete Admixtures Market Competitive Environment
Listed leaders compete with private specialists across certification coverage and formulation customization capabilities. The market structure tiers between multinational chemical conglomerates with integrated R&D pipelines and domestic specialists competing on cost-engineered tenders. Three archetypes dominate: premium innovators with dual-certification portfolios, scale-driven manufacturers with captive supply chains, and regional specialists with localized formulation services. Competitive moves center on strategic partnerships for digital dosing integration and portfolio diversification into low-carbon certified product lines.
Among European-headquartered innovators, BASF SE and Sika AG exemplify the premium-tier archetype through polycarboxylate ether R&D intensity and integrated supply chain positioning. Sobute New Materials Co., Ltd. occupies the domestic specialist tier with cost-engineered formulations tailored to China's infrastructure tender environment. These three represent the competitive spectrum from multinational certification coverage to localized cost optimization.
| Leading Market Players |
|---|
| BASF SE |
| Sika AG |
| GCP Applied Technologies |
| MAPEI S.p.A. |
| Fosroc International Limited |
| Master Builders Solutions |
| RPM International |
| Kao Corporation |
| Sobute New Materials Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between polycarboxylate ether superplasticizer producers and Indonesian precast manufacturers lock in both feedstock access and price visibility across volatile naphtha and ethylene oxide cycles. China's SAMR certification timelines compress supplier margins while securing batching plant loyalty through guaranteed GB 8076-compliant supply.
Pricing Analysis
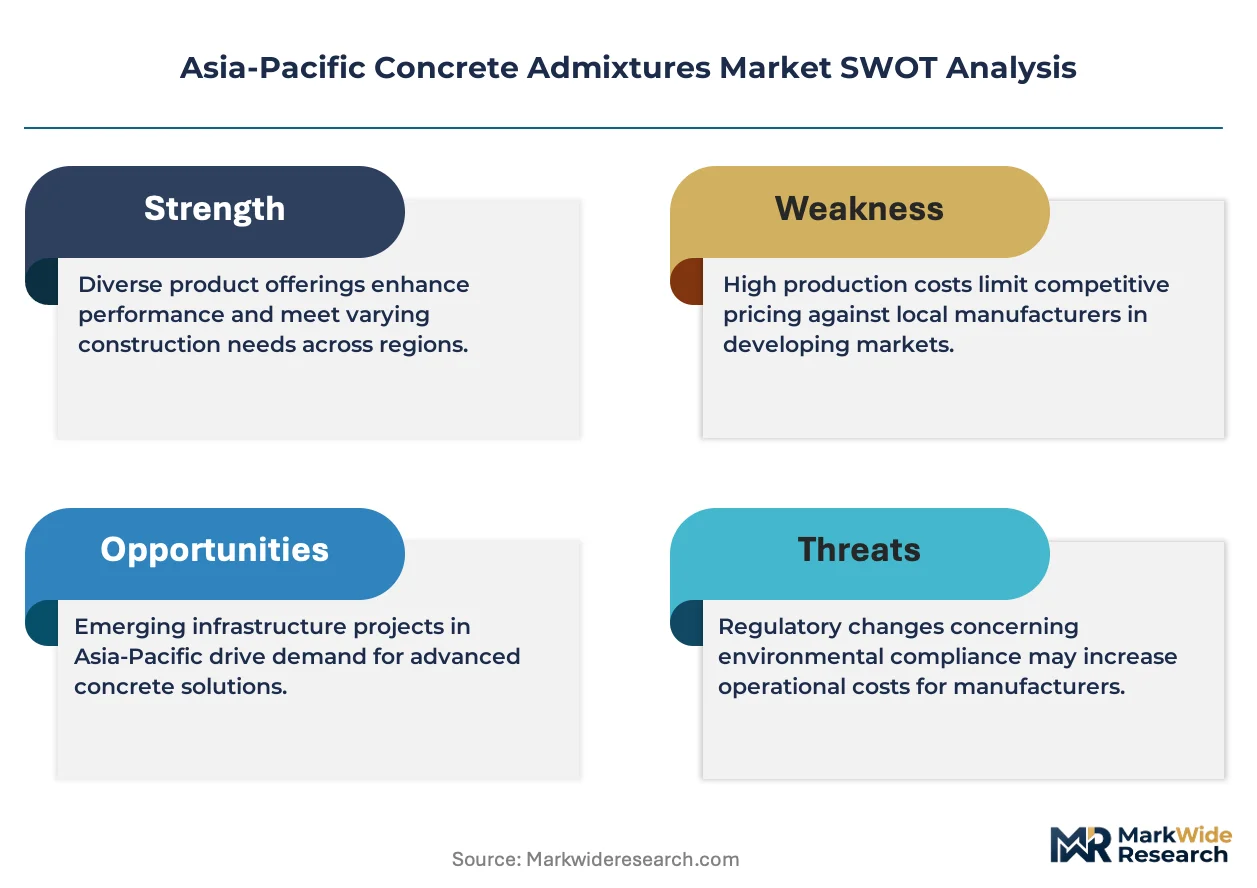
Next-generation low-carbon certified formulations command a 15-20% premium over conventional GB-compliant grades, while commodity polycarboxylate ethers face persistent cost compression from Shandong-based capacity expansions. Three-tier pricing structure across premium JIS-certified, standard GB-compliant, and economy IS 9103 tiers separates specification-grade infrastructure projects from residential volume plays. Pricing pressure stems from feedstock volatility in regional petrochemical markets, with Indian state-level tenders showing the highest buyer price sensitivity and Australian EPD-mandated projects the lowest.
Supply Chain Analysis
Port congestion along the Shanghai-Singapore trade lane elevates inbound logistics costs for polycarboxylate ether active ingredients sourced from Jiangsu province to Southeast Asian batching plants. Supply concentrates in China's Shandong and Jiangsu provinces, South Korea's Yeosu petrochemical complex, and Japan's Kawasaki industrial corridor, with raw material dependencies on ethylene oxide, methoxy polyethylene glycol, and acrylic acid derivatives. Single-source vulnerability from Shandong's dominance creates geographic concentration risk. Distribution runs through integrated chemical distributors serving batching plant networks, with direct mill supply agreements gaining share in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific concrete admixtures represent a high-growth disruption as China's dual carbon goals and Japan's METI low-carbon building incentives requalify entire formulation portfolios toward embodied-carbon compliance.
For Market Incumbents: Fortify certification coverage across GB/JIS/AS tier intersections to defend specification authority against emerging domestic specialists. Backward integration into ethylene oxide precursors in Shandong or Jiangsu mitigates feedstock volatility exposure. Priority investment in digital dosing system partnerships with South Korean and Taiwanese batching plant operators locks in precision-metered liquid formulation channels. For New Entrants and Emerging Players: Differentiate on application-specific polycarboxylate ether comb polymer architectures tailored to Indonesian precast and Australian high-rise vertical construction. The Philippines' "Build Better More" underground metro program offers the most penetrable white-space for 12-hour workability control formulations. Go-to-market through EPC engineering consultancies in Vietnam and Philippines embeds admixture selection into early-stage carbon-budget compliance frameworks. For Investors and Strategic Acquirers: Regional specialists with localized formulation services and dual-certification capabilities present the most attractive acquisition archetype for premium positioning. Long-term viability hinges on portfolio exposure to low-carbon certified product lines and digital dosing integration partnerships. Watch for carbon-border adjustment announcements from Australian and Japanese regulators as the critical inflection signal for specification eligibility shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide Precursors | Captive supply from Shandong petrochemical corridors insulates margin stability against naphtha volatility. |
| Dual-Certification Portfolio Expansion | GB/JIS/AS coverage unlocks specification channels in Japanese METI-incentivized and Australian NCC-mandated projects. |
| Digital Dosing System Partnerships | IoT-enabled batching plant retrofits in South Korea and Taiwan create precision-metered liquid formulation demand. |
| Application-Specific PCE Architecture Development | Tailored comb polymer variants for Indonesian precast and Australian high-rise displace standardized commodity formulations. |
| Environmental Product Declaration Certification | EPD compliance creates first-mover advantage in New South Wales and Victoria procurement guidelines. |
Study Parameters
The analysis maps water-reducing, retarding, accelerating, and air-entraining admixture chemistries, each validated through technical directors at batching plant operators, procurement leads at EPC contractors, formulation lab managers, and regulatory compliance officers. Primary interviews with plant managers at Shandong and Jiangsu superplasticizer facilities, downstream OEM procurement teams at Indonesian precast producers, and distribution channel partners across ASEAN markets combined with secondary validation from customs/trade data, BIS and SAMR regulatory filings, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up volume builds and top-down market sizing triangulated through cross-referencing certification database coverage with batching plant capacity utilization estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including admixture chemistry type, application context across infrastructure and commercial construction, liquid versus powder form factors, and end-user specification authority patterns. CAGRs derived from regression analysis of historical procurement volumes against infrastructure investment pipelines and regulatory compliance timeline shifts. Industry-specific forecast inputs incorporated SAMR GB 8076 enforcement trajectory and METI low-carbon building incentive uptake rates.
Material uncertainties — feedstock price volatility, certification timeline extensions, and carbon-border adjustment implementation — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding infrastructure investment continuity and regulatory compliance pathway stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Tragacanth Market
Additives
Clouding Agents Market
Additives
Global Cement and Concrete Additives Market
Additives
Global Scale Inhibitors Market
Additives
Tocopheryl Acetate Market
Additives
Sorbitan Laurate Market
Additives
Global Anti-Fog Additives Market
Additives
Global Asphalt Additives Market
Additives
Biofuel Additives Market
Additives
Thermal Conductive Additives Market
Additives
Surface Modifiers Market
Additives
Global Coalescing Agent Market
Additives
Alkyl Acetates Market
Additives
Nucleating and Clarifying Agents Market
Additives
Ultraviolet Light Stabilizer Market
Additives
Marine Fuel Additives Market