
 Phthalate Plasticizer Market | 2026-2036
Phthalate Plasticizer Market Size, Share, and Industry Trends Forecast 2026-2036
Phthalate Plasticizer Market Analytics
Aftermarket service revenue for phthalate reformulation consulting is reconfiguring how suppliers capture margin from regulatory transitions. BASF SE leverages its integrated oxo-alcohol feedstock position to sustain cost leadership across European DINP supply. Evonik Industries AG anchors specialty medical-grade DEHP alternatives through its Vestinol product line, while Eastman Chemical Co. competes on non-phthalate flexibility platforms that extend its reach into healthcare tubing applications.
Phthalate plasticizers are ester compounds synthesized from phthalic anhydride and C4-C13 alcohols through esterification, added to polyvinyl chloride to reduce glass transition temperature and enhance processability. DINP dominates volume consumption in automotive wire insulation and interior trim, where heat stability requirements favor its branched C9 alcohol structure. DEHP persists in medical device blood bags and tubing despite regulatory pressure, as healthcare procurement prioritizes material compatibility with existing sterilization protocols. Construction end users channel demand through direct sales arrangements for bulk DOP in flooring and wall covering applications, while distributor networks handle smaller electronics accounts requiring mixed plasticizer blends.
REACH authorization requirements and RoHS substance restrictions in Europe compel reformulation away from classified CMR phthalates in consumer goods and electrical equipment. The US FDA maintains DEHP in approved medical device applications through biocompatibility exemptions, though US EPA chemical action plans signal future scrutiny under TSCA Section 6. China's GB standards and MEE environmental compliance audits enforce emission controls on phthalate manufacturing, reshaping domestic capacity location decisions. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation specialization or unified low-toxicity platforms offer superior returns.
Market Dynamics
REACH authorization timelines and the EU Green Deal's chemical sustainability mandates are forcing rapid portfolio restructuring across European plasticizer supply chains, with DINP and DIDP formulations gaining share against legacy DEHP positions.
Growth Catalysts
- Automotive Interior Specifications:Heat stability requirements in wire insulation and dashboard trim are pulling higher DINP volumes from compounders serving German and Japanese OEM supply chains.
- REACH Authorization Deadlines:The European Chemicals Agency's sunset dates for DEHP are compelling consumer goods manufacturers to validate alternative plasticizer platforms ahead of 2025-2027 phase-outs.
- China's GB Standard Modernization:Domestic MIIT industrial policy is accelerating capacity consolidation around integrated oxo-alcohol producers with compliant emission controls.
Market Restraints
- Feedstock Concentration Risk:C9-C10 alcohol supply clusters along the US Gulf Coast and Rotterdam corridor, exposing DINP producers to naphtha price volatility and force majeure events at integrated crackers.
- Medical Device Lock-In:FDA biocompatibility exemptions for DEHP in blood bags and tubing create regulatory friction against alternative validation, delaying substitution timelines despite REACH pressure.
- Non-Phthalate Substitution Threat:Citrate and adipate esters are capturing healthcare tubing specifications where Eastman Chemical and Lanxess have secured compounder qualification.
Strategic Opportunities
- India's BIS Certification Gap:Domestic cable and flooring manufacturers face 2024-2025 compliance deadlines without qualified local DINP supply, creating import substitution openings for integrated producers.
- Recycled PVC Feedstock Integration:Mechanical recycling of post-consumer automotive trim and construction waste is converging with phthalate reformulation services to create closed-loop compounder relationships.
- Healthcare Tubing Requalification:US EPA TSCA Section 6 scrutiny signals future DEHP restrictions, positioning medical-grade DINP and terephthalate alternatives for procurement specification wins.
Industry Challenges
- Toxicology Data Generation Burden:REACH registration dossiers for alternative plasticizers require extensive mammalian study data, stretching ECHA submission timelines and consuming 18-24 month pre-market investment cycles.
- Compound Blending Complexity:Automotive wire insulation specifications demand precise glass transition temperature control, forcing compounders to maintain multi-plasticizer inventories during reformulation transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phthalate Plasticizer Market |
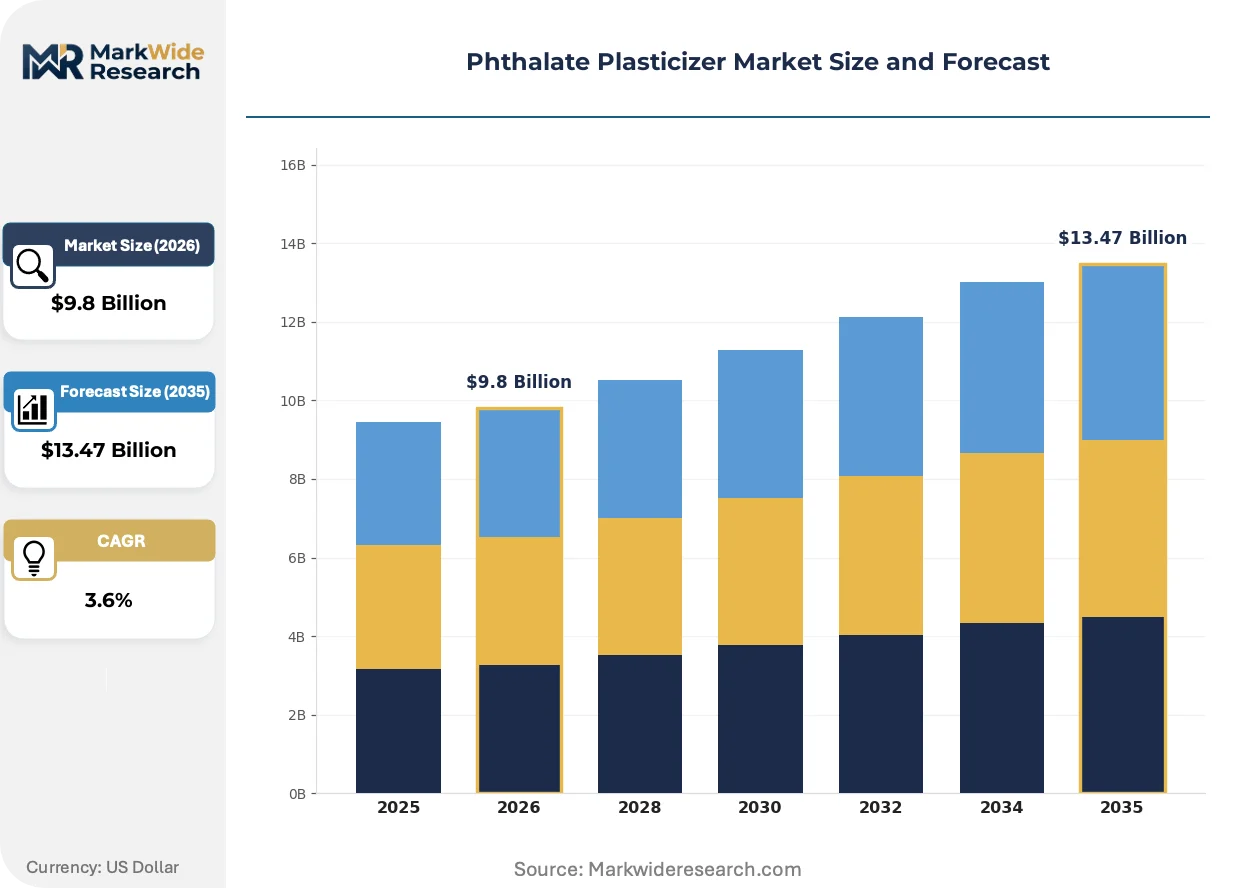
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $13.47 Billion |
| CAGR (2026 – 2036) | 3.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DOP, DINP, DEHP, DBP Application: Medical Devices, Consumer Goods, Automotive Components, Building Materials End User: Construction, Healthcare, Automotive, Electronics Distribution Channel: Direct Sales, Distributors, Online Retail, Resellers |
| Companies Covered | Evonik Industries AG, ADEKA Corp., BASF SE, LG Chem, KLJ Group, Eastman Chemical Co., Nan Ya Plastic Corp., Valtris Specialty Chemicals, Exxon Mobil Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phthalate Plasticizer Market Evolving Landscape
Formulation science is pivoting toward molecular architectures that satisfy both performance specifications and regulatory hazard classification thresholds, with branched-chain esters and bio-based alcohol feedstocks commanding disproportionate R&D allocation.
Enzymatic esterification using immobilized lipase catalysts is rendering obsolete conventional acid-catalyzed batch processes in European specialty plasticizer production. BASF and Evonik pilot facilities in Ludwigshafen and Marl are validating continuous-flow biocatalytic routes that cut energy intensity by half. This technology is rendering obsolete capital-intensive pressure reactors while enabling product-specific carbon footprint certification for automotive OEM sustainability scorecards.
The EU Green Deal's Chemicals Strategy for Sustainability is extending hazard classification criteria to include endocrine disruption and persistence, compressing the acceptable substance pool for consumer-facing applications. ECHA's 2024-2027 rolling action plan targets additional ortho-phthalates for restriction proposal, forcing compounders to pre-validate replacement chemistries. German electrical equipment manufacturers are responding with accelerated RoHS compliance testing for DINP and DIDP in cable sheathing ahead of anticipated substance listing.
Automotive OEMs are consolidating plasticizer procurement around qualified compounder networks with integrated formulation and regulatory documentation capabilities. Tier-1 suppliers such as Aptiv and Lear are displacing spot-market resin purchases with multi-year toll compounding agreements that bundle REACH compliance data. This concentration is most visible in Germany's Rhineland automotive cluster, where wire harness producers now source exclusively from three DINP-qualified compounders with captive laboratory testing infrastructure.
Phthalate Plasticizer Market Segmentation
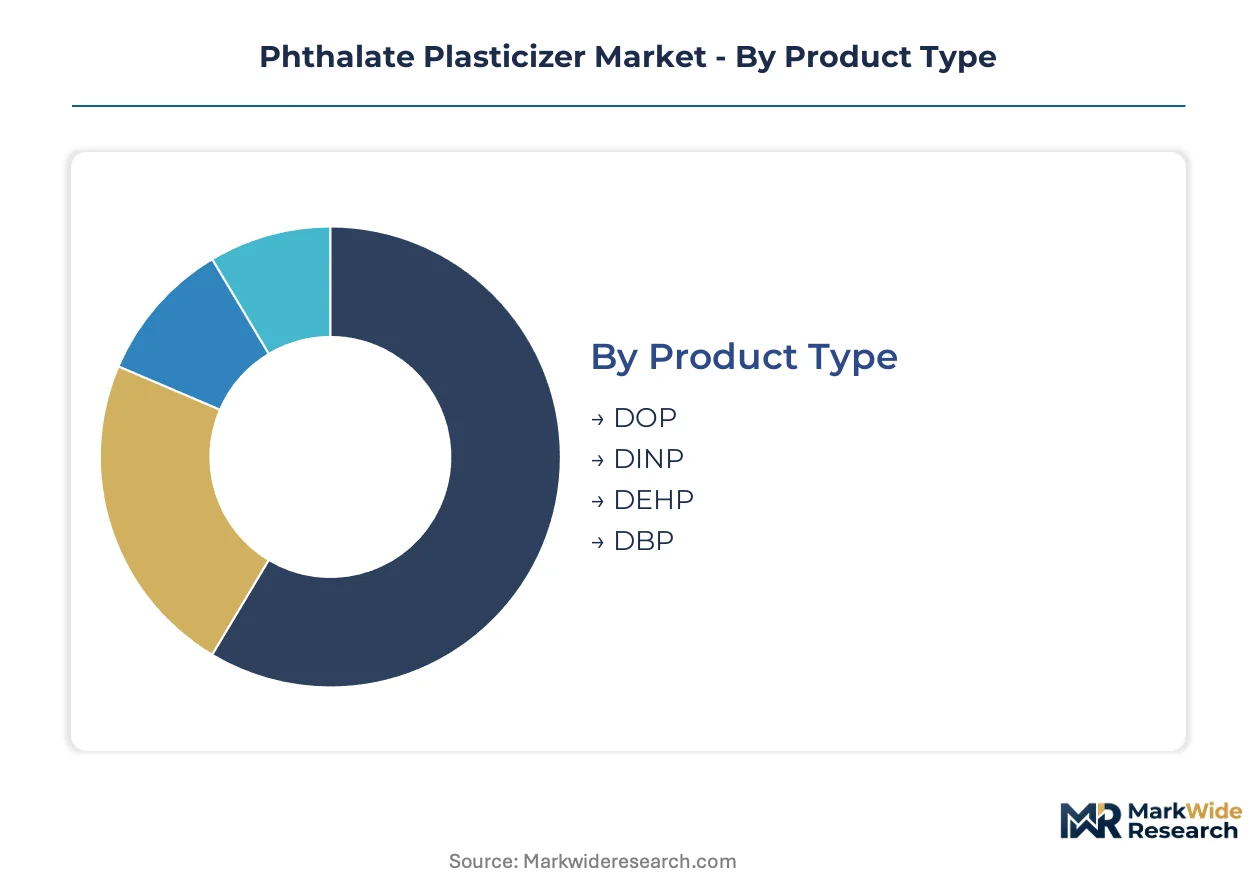
Segmentation in phthalate plasticizers reveals how formulation specifications, regulatory hazard classifications, and procurement channel economics partition value capture across the supply chain. Understanding these divides exposes where integrated producers command premium positioning versus where distributor networks absorb margin compression.
Product Type:
DINP and DOP turn inventory fastest through automotive and construction offtake, while DEHP and DBP face elongated replacement cycles tied to medical device requalification and REACH sunset timelines.
- DINP:Branched C9 ester structure delivers superior heat stability for wire insulation and dashboard trim specifications. German and Japanese automotive OEMs concentrate procurement through qualified compounder networks in Stuttgart and Nagoya, with REACH authorization deadlines accelerating substitution from legacy chemistries.
- DOP:Straight-chain C8 formulation offers cost-optimized plasticization for flooring and wall covering applications. Chinese construction demand absorbs volumes through direct mill arrangements, though GB standard modernization is compressing emission-tolerant capacity.
- DEHP:Dominates medical device blood bags and tubing where FDA biocompatibility exemptions sustain procurement despite ECHA restriction pressure.
- DBP:Lower molecular weight C4 ester serves niche adhesive and cellulose nitrate applications with limited volume traction.
DOP anchors the volume base while DINP gains share at the steepest rate.
Application:
Cost tier stratification separates medical-grade qualification investments from commodity construction offtake, with automotive specifications occupying a mid-tier premium position.
- Automotive Components:Wire harness insulation and interior trim demand precise glass transition temperature control through DINP-dominant formulations. Tier-1 suppliers in Germany's Rhineland cluster source exclusively through three qualified compounders with captive laboratory infrastructure.
- Medical Devices:Blood bags, IV tubing, and dialysis equipment maintain DEHP dependency due to sterilization protocol compatibility and FDA exemption pathways. US healthcare procurement prioritizes material consistency over substitution despite REACH pressure.
- Building Materials:PVC flooring and wall coverings channel bulk DOP demand through direct sales arrangements with integrated construction chemical distributors.
- Consumer Goods:Toys and food contact applications face the most restrictive phthalate limits, driving reformulation toward non-phthalate alternatives.
Building Materials anchors the volume base while Automotive Components climbs the fastest.
End User:
Customer-type concentration determines whether producers capture margin through technical service bundling or compete on spot-market price.
- Construction:Flooring and cable manufacturers procure bulk DOP and DINP through direct sales with volume-tiered pricing. China's MIIT industrial policy is consolidating demand around integrated oxo-alcohol producers with compliant emission controls.
- Healthcare:Medical device manufacturers require extensive toxicology documentation and batch certification, sustaining premium positioning for qualified DINP and terephthalate alternatives.
- Automotive:OEM consolidation around toll compounding agreements bundles REACH compliance data with resin supply.
- Electronics:RoHS substance restrictions and smaller order quantities push demand through distributor networks handling mixed plasticizer blends.
Construction anchors the volume base while Healthcare expands most quickly.
Distribution Channel:
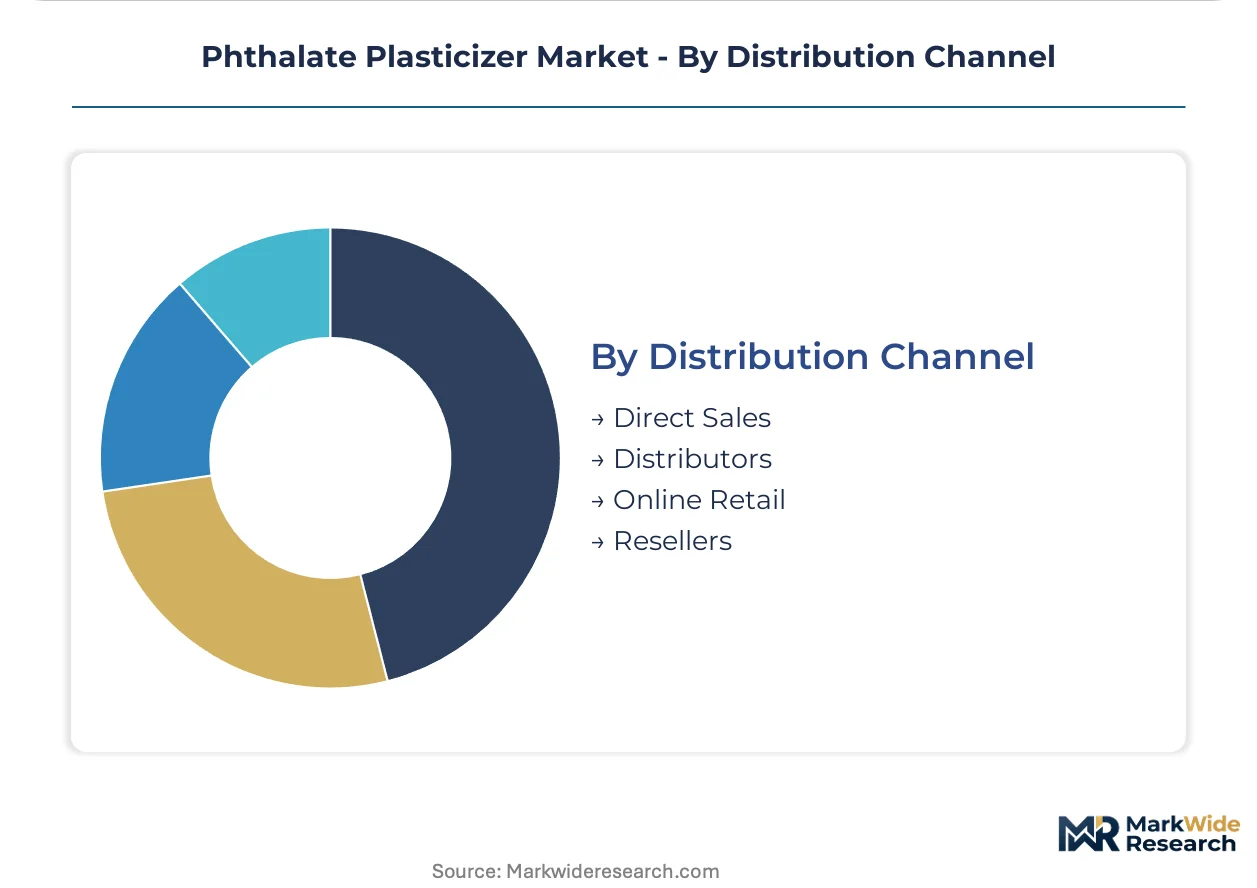
Supply concentration geography dictates channel economics, with Rotterdam and US Gulf Coast feedstock clusters favoring direct mill sales while fragmented Asian demand sustains distributor intermediation.
- Direct Sales:Integrated producers with captive oxo-alcohol capacity serve automotive and construction accounts through long-term offtake agreements. BASF's Ludwigshafen complex anchors European DINP supply with backward integration into C9-C10 alcohol feedstock.
- Distributors:Regional chemical distributors handle smaller electronics and consumer goods accounts requiring mixed-blend formulation services and regulatory documentation support.
- Resellers:Secondary market participants aggregate spot volumes for price-sensitive construction applications with limited technical service requirements.
- Online Retail:Minimal traction in bulk industrial chemicals; limited to specialty small-batch laboratory reagents.
Direct Sales anchors the volume base while Distributors gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's construction sector exhibit extreme price elasticity, absorbing DOP volumes through direct mill arrangements, while German automotive OEMs prioritize heat-stability qualification over cost, creating a bifurcated demand landscape that rewards regional specialization.
China
MIIT industrial policy consolidates phthalate capacity around integrated oxo-alcohol producers with MEE-compliant emission controls. GB standard modernization enforces stricter manufacturing audits, eliminating smaller emitters. The Yangtze River Delta hosts the densest cluster of DINP-qualified compounders serving automotive wire harness exports.
Germany
REACH authorization deadlines for DEHP accelerate reformulation validation across consumer goods and electrical equipment. ECHA's rolling action plan targets additional ortho-phthalates through 2027. The Rhineland automotive cluster concentrates procurement through three DINP-qualified compounders with captive laboratory infrastructure.
United States
FDA biocompatibility exemptions sustain DEHP procurement in blood bags and dialysis tubing despite EPA TSCA Section 6 scrutiny signals. US Gulf Coast C9-C10 alcohol supply exposes DINP producers to naphtha price volatility. Houston-area crackers anchor feedstock integration for domestic plasticizer production.
India
BIS certification deadlines for 2024-2025 strand domestic cable and flooring manufacturers without qualified local DINP supply. CDSCO medical device regulations lag REACH alignment, preserving reformulation timelines. Maharashtra's industrial corridor attracts import substitution investments from integrated oxo-alcohol producers.
Japan
METI chemical management policies align with EU hazard classification trends, pressuring consumer-facing applications toward verified alternatives. JIS standards for automotive wire insulation specify precise glass transition temperature ranges. The Nagoya-Toyota supply chain demands DINP formulations with documented REACH compliance data.
Phthalate Plasticizer Market Competitive Landscape
Integrated petrochemical majors and specialty chemical houses split the market between feedstock-anchored volume positions and qualification-driven premium tiers. The structure concentrates around three strategic archetypes: backward-integrated producers with captive oxo-alcohol supply, compounder-facing specialists bundling regulatory documentation, and diversified chemical conglomerates cross-selling plasticizers from broader portfolios. Dominant competitive moves include capacity consolidation around compliant emission controls and toll compounding agreements that bundle REACH compliance data with resin supply.
Within the integrated producer tier, BASF SE and Evonik Industries AG exemplify divergent strategic positioning. BASF anchors European DINP supply through its Ludwigshafen complex with upstream control over C9-C10 alcohol feedstock. Evonik occupies a specialty position through its Vestinol product line, serving medical-grade qualification requirements. Eastman Chemical Co. represents the non-phthalate competitive threat, capturing healthcare tubing specifications with terephthalate alternatives that compounders are pre-validating ahead of anticipated DEHP restrictions.
| Leading Market Players |
|---|
| Evonik Industries AG |
| ADEKA Corp. |
| BASF SE |
| LG Chem |
| KLJ Group |
| Eastman Chemical Co. |
| Nan Ya Plastic Corp. |
| Valtris Specialty Chemicals |
| Exxon Mobil Corp. |
| Others |
Value Network & Pricing Analysis
Overcapacity in China's Yangtze River Delta phthalate corridor is compressing spot DOP margins while simultaneously forcing integrated producers toward long-term toll compounding agreements that bundle regulatory documentation with resin supply.
Pricing Analysis
Aftermarket reformulation consulting revenue now drives lifetime value capture as REACH sunset deadlines accelerate. Three-tier pricing structure across medical-grade certification, automotive-qualified, and commodity construction tiers separates DINP formulations by toxicology dossier depth. Cost compression in standard-grade DOP is intensifying because Chinese MIIT consolidation is eliminating emission-tolerant capacity. Construction buyers in China exhibit extreme price elasticity, while German automotive OEMs prioritize heat-stability qualification over cost.
Supply Chain Analysis
Toll compounding concentration in Germany's Rhineland cluster and China's Yangtze River Delta holds the majority of qualified DINP formulation capacity. Feedstock supply draws from US Gulf Coast and Rotterdam corridor C9-C10 alcohol production, with naphtha price volatility exposing margin structures. Single-source vulnerability at integrated crackers creates force majeure risk for automotive wire harness supply chains. Distribution runs through direct mill arrangements for bulk construction offtake and qualified compounder networks for automotive specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment—specifically REACH authorization timelines and FDA biocompatibility exemption pathways—creates switching costs that protect incumbent positions.
For Market Incumbents: Entrench through backward integration into C9-C10 oxo-alcohol feedstock and captive laboratory infrastructure for REACH compliance documentation. Non-phthalate substitution from Eastman Chemical's terephthalate platforms and citrate ester competitors threatens medical tubing specifications. Capacity consolidation around MEE-compliant emission controls in China anchors cost leadership against fragmented domestic rivals.
For New Entrants and Emerging Players: India's BIS certification gap for 2024-2025 cable and flooring compliance deadlines offers import substitution openings without qualified local DINP supply. CDSCO medical device regulations lag REACH alignment, preserving extended reformulation timelines for DEHP alternatives. Target toll compounding partnerships with Maharashtra industrial corridor manufacturers as the go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across enzymatic esterification pilot facilities as biocatalytic routes displace pressure reactor investments. Long-term viability favors producers with integrated oxo-alcohol positions and qualified compounder networks over spot-market commodity players. Acquisition targets should demonstrate REACH registration dossier completion and automotive OEM qualification. Monitor ECHA rolling action plan announcements for ortho-phthalate restriction proposals as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oxo-Alcohol Feedstock | BASF's Ludwigshafen complex demonstrates how captive C9-C10 supply anchors DINP cost leadership. |
| REACH Compliance Documentation Bundling | Toll compounding agreements with German Tier-1 suppliers lock in multi-year automotive wire harness contracts. |
| Enzymatic Esterification Scale-Up | Continuous-flow biocatalytic routes at Evonik's Marl facility cut energy intensity for sustainability scorecards. |
| Medical-Grade Alternative Qualification | Vestinol product line investments position for FDA exemption erosion and healthcare tubing requalification. |
| India Import Substitution Capacity | Maharashtra industrial corridor investments capture BIS certification gap before domestic supply qualifies. |
Research Methodology
Cross-validation between primary interviews with plant managers at integrated oxo-alcohol producers and secondary validation through customs/trade data and SEC 10-K filings anchors the qualitative findings. Conversations with procurement leads at downstream automotive OEMs, distribution channel partners, and technical R&D directors at compounders informed formulation transition timelines. Bottom-up segmentation modeling triangulated against top-down capacity assessments from Cefic and ACC reports produced convergent volume estimates.
Calibration against historical REACH authorization implementation rates and automotive specification change cycles shaped the projection framework across the analysis window. Segmentation dimensions modeled include plasticizer grade tier, end-use industry, and regional production hub compliance status. CAGRs derived from elasticity-adjusted demand curves incorporating naphtha feedstock price correlation and regulatory substitution elasticity. Industry-specific inputs included ECHA restriction proposal timelines and MIIT capacity consolidation announcements.
Practitioners should monitor ECHA rolling action plan updates, FDA TSCA Section 6 scrutiny signals, and Chinese MEE audit enforcement patterns for early signals of forecast revision. Forecasts reflect documented assumptions regarding REACH sunset implementation rates and automotive OEM qualification timelines. Quarterly review of regulatory proposal dockets and feedstock price volatility indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Gasoline Additives Market
Additives
Epoxy Type Stabilizers Market
Additives
Feedstuff Additives Market
Additives
Lead Stearate Market
Additives
Diamino Stilbene Disulfonic Acid (DASDA) Market
Additives
Anti-Creasing Agent Market
Additives
Fluoropolymer Additives Market
Additives
Global Pour Point Depressant Market
Additives
Oxygen Scavengers Market
Additives
Carboxymethylcellulose (CMC) Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
Canada Water Enhancer Market
Additives
Conditioning Agent Market
Additives
Encapsulated Citric Acid Market
Additives
Global Flame Retardant Masterbatches Market
Additives
Surface Modifiers Market