
 Enzyme Stabilizer Market | 2026-2036
Enzyme Stabilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Enzyme Stabilizer Market Analytics
Pharmaceutical-grade specification tiers are rotating toward higher-purity stabilizer requirements as biologics manufacturers tighten excipient standards. Thermo Fisher Scientific leverages its diagnostic-grade supply chain to dominate lyophilized formulation segments. MilliporeSigma anchors its position through R&D intensity in custom stabilizer blends for cell-culture applications. Evonik Industries differentiates via specialty polymer coatings that extend enzyme half-life in aqueous environments.
Enzyme stabilizers are chemical or biological additives that preserve catalytic activity by shielding protein structures from thermal denaturation, oxidation, and proteolytic degradation, typically functioning through preferential exclusion mechanisms or direct binding to hydrophobic pockets. Their primary industrial purpose centers on maintaining enzymatic performance during storage, transport, and processing across temperature-variable supply chains. Liquid formulations occupy the largest volume share due to ease of incorporation into continuous food and fuel-ethanol processes, while lyophilized formats command premium positioning in diagnostics and biopharmaceutical cold-chain logistics where reconstitution stability determines assay reliability. Tablet and capsule stabilizer formats remain niche, concentrated in point-of-use healthcare and field-deployed research kits where portability outweighs unit cost.
REACH registration requirements in Europe and FDA Type II drug master file standards in the United States are elevating documentation burdens for stabilizer suppliers seeking pharmaceutical market access, effectively filtering out uncertified regional producers. India's CDSCO and BIS are converging on harmonized excipient purity norms that parallel IPEC guidelines, accelerating formal qualification programs among domestic manufacturers. ISO 9001 and ISO 13485 certifications have become baseline procurement filters for biotechnology end users sourcing stabilizers for GMP-regulated workflows. Stakeholders must monitor evolving dual-use export controls on stabilizer precursors and position their qualification investments ahead of regulatory divergence between major pharmaceutical manufacturing clusters.
Market Dynamics
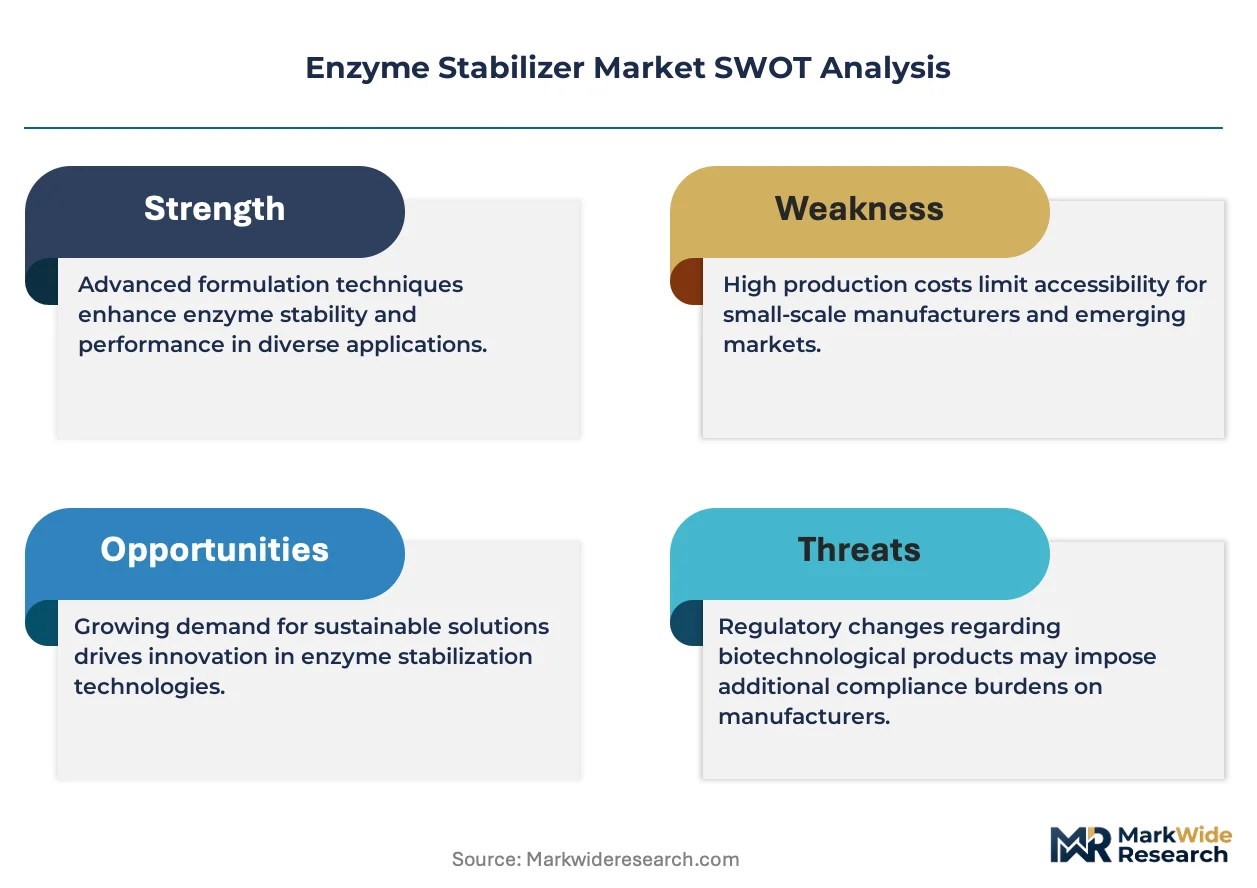
Pharmaceutical-grade purity mandates are compressing supplier margins while filtering uncertified producers from REACH-regulated and FDA-monitored procurement channels. Biologics manufacturers now demand excipient documentation that exceeds historical food-grade thresholds.
Growth Catalysts
- Biologics manufacturing expansion:Cell-culture and monoclonal antibody production lines in India and Germany are consuming custom stabilizer blends at volumes that justify dedicated production facilities.
- REACH registration deadlines:ECHA's 2023-2025 substance evaluation waves are forcing reformulation toward compliant chemistries, creating replacement demand for certified suppliers.
- Cold-chain diagnostics growth:Lyophilized assay kits for point-of-care testing require stabilizers that maintain enzyme activity through freeze-thaw cycles and tropical storage conditions.
Market Restraints
- Specialty polymer input costs:Evonik's proprietary coating chemistries rely on acrylate monomers whose pricing tracks volatile petrochemical feedstock indices.
- Supplier concentration in German chemical clusters:Three-quarters of pharmaceutical-grade stabilizer precursor synthesis occurs within 200 kilometers of Ludwigshafen, creating geographic risk exposure.
- Protease substitution threat:Engineered thermostable enzymes from directed evolution programs reduce exogenous stabilizer dependence in high-temperature industrial processes.
Strategic Opportunities
- CDSCO harmonization pathway:India's convergence with IPEC excipient guidelines creates first-mover advantage for suppliers completing formal qualification ahead of domestic competitors.
- Continuous bioprocessing adoption:Perfusion cell-culture systems require real-time stabilizer dosing that liquid formulation formats can deliver more precisely than lyophilized alternatives.
- Direct-to-biotech distribution:E-commerce platforms for research-grade reagents are disintermediating traditional distributor networks for sub-kilogram stabilizer orders.
Industry Challenges
- ISO 13485 certification timelines:Medical device-grade stabilizer qualification requires 18-24 month audit cycles that delay revenue recognition for new market entrants.
- Formulation scientist scarcity:Protein biochemistry expertise sufficient to design stabilizer-enzyme compatibility matrices commands premium compensation in Boston and Basel labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enzyme Stabilizer Market |
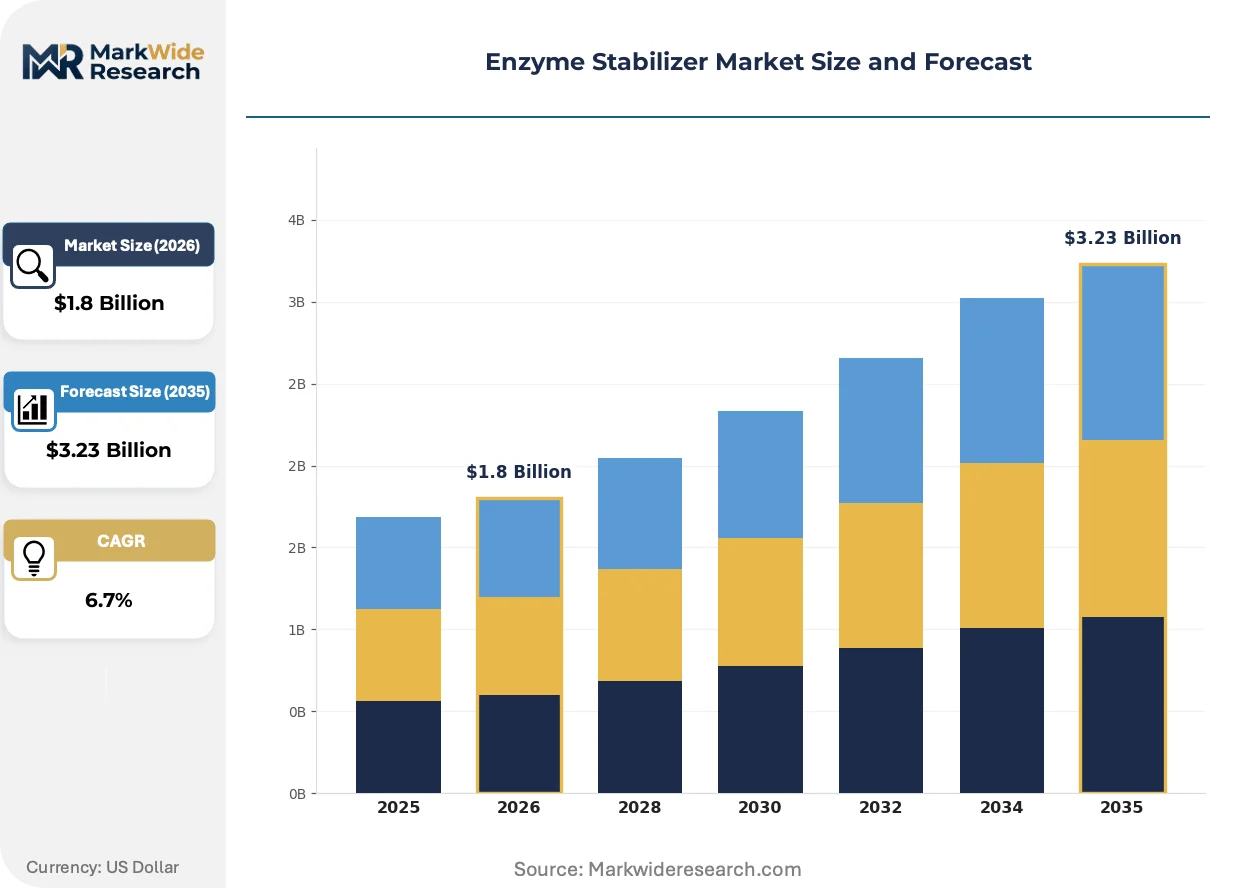
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Tablet, Capsules Application: Food Processing, Pharmaceuticals, Biofuels, Diagnostics End User: Food Industry, Healthcare, Biotechnology, Research Labs Formulation: Granular, Suspensions, Solutions, Lyophilized |
| Companies Covered | Thermo Fisher Scientific, MilliporeSigma, Archer Daniels Midland, Sun Chemical, Roche Custom Biotech, BASF Nutrition, Evonik Industries, Meihua Group, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enzyme Stabilizer Market Evolving Landscape
Trehalose-based stabilizer systems are displacing traditional polyol chemistries across temperature-sensitive biologics applications. Regulatory documentation burdens and manufacturing process intensification are simultaneously reshaping supplier selection criteria.
Sugar-derived glass-forming stabilizers, particularly trehalose and sucrose blends, are supplanting conventional polyol formulations in lyophilized biopharmaceutical applications. Contract manufacturing organizations in Switzerland and Massachusetts are adopting these chemistries for monoclonal antibody formulations. The shift is compressing demand for sorbitol and mannitol in high-value segments while elevating trehalose purification capacity as a strategic constraint.
EMA's revised Annex 1 guidelines on sterile manufacturing are mandating endotoxin testing protocols that extend stabilizer release timelines by 30-45 days. Manufacturers supplying fill-finish operations must now document pyrogen control across raw material sourcing, synthesis, and packaging stages. German and Irish pharmaceutical clusters are responding by qualifying dual-source stabilizer suppliers to mitigate batch-release uncertainty.
Consolidated procurement by multi-site biologics manufacturers is displacing site-specific ordering through integrated supply agreements that span R&D, clinical, and commercial phases. Thermo Fisher Scientific and MilliporeSigma are capturing these contracts through diagnostic-grade supply chain credentials that regional competitors cannot replicate. The concentration is most visible in Cambridge, Massachusetts and South San Francisco, where venture-backed biotechs prioritize vendor redundancy over unit cost minimization.
Enzyme Stabilizer Market Segmentation
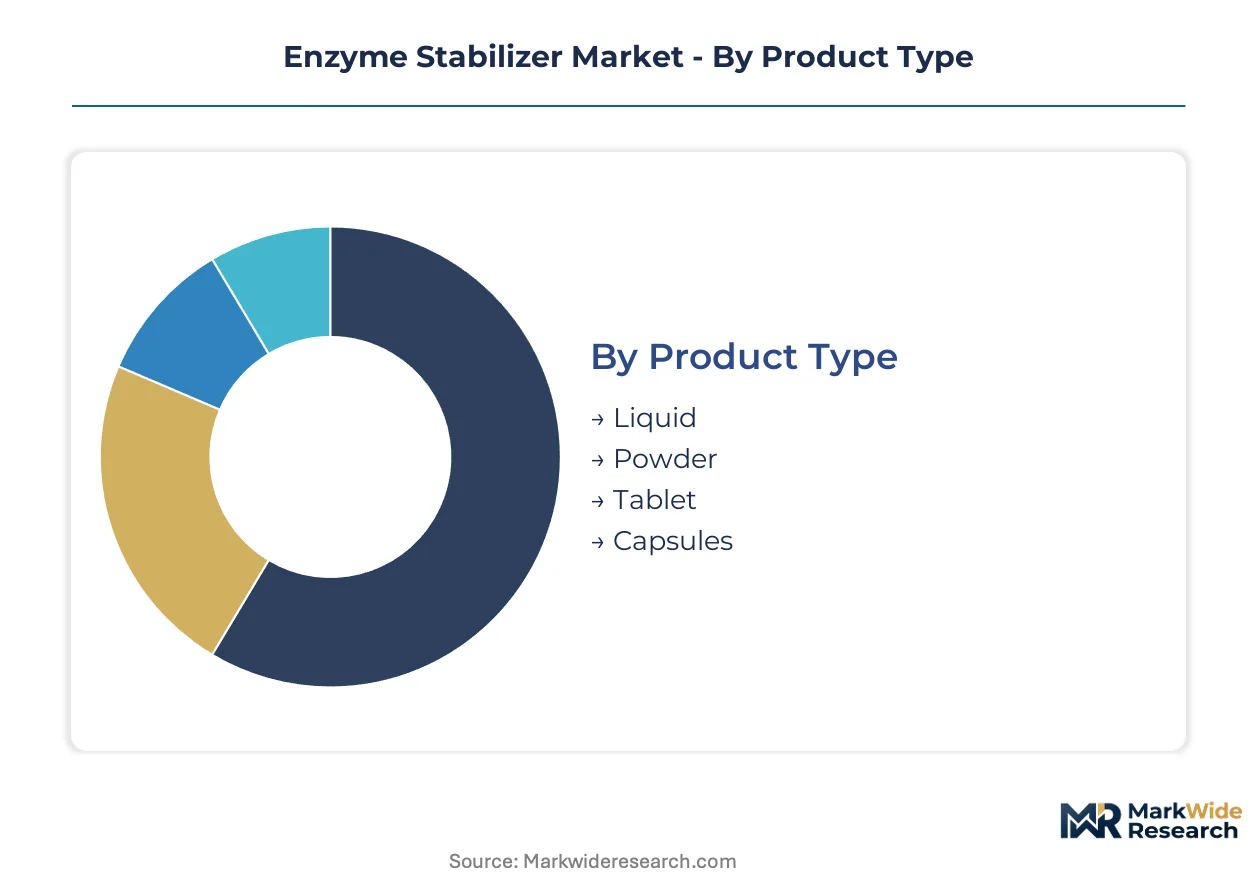
Enzyme stabilizer procurement patterns diverge sharply across formulation formats and end-use specifications, with substitution pressure from engineered thermostable enzymes reshaping investment priorities in high-temperature industrial segments. Understanding these fault lines enables suppliers to allocate qualification resources toward defensible revenue pools.
Product Type:
Liquid stabilizers face the most acute substitution threat from next-generation enzyme engineering, while solid formats maintain structural demand from cold-chain logistics constraints.
- Liquid:Aqueous solutions of polyols, salts, and surfactants enable continuous dosing into fermentation and fuel-ethanol processes. Food manufacturers in India and Germany consume bulk volumes for starch hydrolysis operations, though directed-evolution thermostable amylases are eroding stabilizer dependence in high-temperature jet-cooking applications.
- Powder:Spray-dried formulations of trehalose, maltodextrin, and buffering salts serve lyophilization feedstocks for biopharmaceutical manufacturing. Swiss and Massachusetts contract development organizations specify powder grades with endotoxin documentation for monoclonal antibody excipient blends.
- Tablet:Compressed stabilizer matrices containing disintegrants and binders target field-deployed diagnostic kits. Military and point-of-care healthcare procurement in Saudi Arabia and the UAE drives niche volume for tropical stability requirements.
- Capsules:Gelatin or HPMC shells encasing stabilizer blends for research laboratory aliquoting. Academic institutions in Boston and Basel purchase gram-scale quantities for protein crystallography workflows.
Liquid stabilizers retain volume leadership; lyophilized-compatible powder formats hold the steepest expansion curve.
Application:
Margin structures stratify across application tiers, with pharmaceutical-grade documentation burdens filtering suppliers from high-value segments while commodity food processing tolerates broader qualification standards.
- Food Processing:Stabilizer systems for amylases, proteases, and lipases in baking, brewing, and dairy applications. Indian food manufacturers under FSSAI oversight are expanding trehalose adoption for extended shelf-life enzyme premixes.
- Pharmaceuticals:Excipient-grade stabilizers for biologics formulations requiring FDA Type II drug master files and EMA sterile manufacturing compliance. Fill-finish operations in Ireland and Germany now mandate 30-45 day extended endotoxin release testing.
- Biofuels:Cellulase and amylase stabilizers for simultaneous saccharification and fermentation in fuel-ethanol production. Brazilian ANVISA-regulated mills and US EPA-monitored corn-ethanol facilities drive cost-sensitive procurement.
- Diagnostics:Lyophilized assay stabilizers maintaining enzyme activity through freeze-thaw cycles and ambient shipping. CDSCO-harmonized Indian manufacturers are qualifying domestic suppliers for export to tropical African markets.
Food processing commands absolute volume; pharmaceutical applications generate the highest unit margins and qualification barriers.
End User:
Customer sophistication tiers separate specification-driven biotechnology procurement from price-elastic food industry purchasing, with research labs occupying an intermediate volatility position.
- Food Industry:Large-scale enzyme users in baking, dairy, and beverage manufacturing prioritizing cost-per-activity metrics over purity documentation. Indian PLI scheme beneficiaries are localizing stabilizer sourcing for import substitution.
- Healthcare:Hospital and clinical laboratory networks requiring stabilizers for diagnostic reagent manufacturing. US HIPAA-compliant procurement channels favor vendors with ISO 13485 medical device certification.
- Biotechnology:Cell-culture and monoclonal antibody producers demanding custom stabilizer blends with batch-specific CoA documentation. Cambridge, Massachusetts and South San Francisco venture-backed biotechs prioritize supplier redundancy.
- Research Labs:Academic and government institutions purchasing sub-kilogram quantities through e-commerce reagent platforms. Thermo Fisher Scientific and MilliporeSigma dominate this channel through diagnostic-grade supply chain credentials.
The food industry anchors procurement volume; biotechnology end users are expanding most quickly on biologics manufacturing capacity builds.
Formulation:
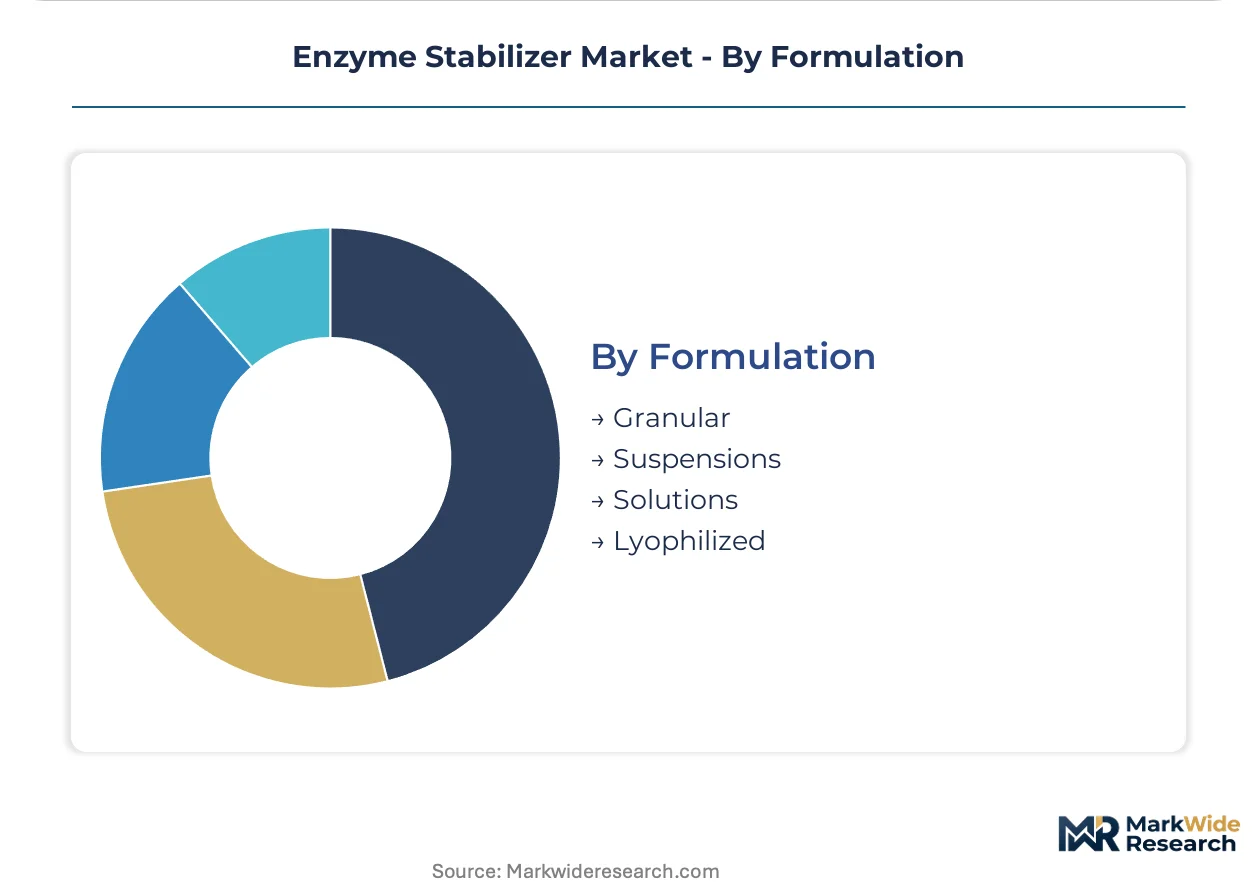
Physical form factors determine supply chain compatibility, with aqueous formats aligning to continuous processing and dried formats serving batch lyophilization workflows.
- Granular:Free-flowing agglomerated particles for bulk handling in food and feed enzyme premixes. German chemical clusters near Ludwigshafen concentrate precursor synthesis for this format.
- Suspensions:Colloidal stabilizer dispersions in non-aqueous vehicles for hydrophobic enzyme protection. Biofuel applications in Brazil favor suspensions for cellulase stabilization in high-solids fermentation.
- Solutions:Fully dissolved aqueous stabilizer systems for direct injection into bioreactors. Perfusion cell-culture adoption in Switzerland and Massachusetts is accelerating real-time dosing demand.
- Lyophilized:Vacuum-dried cakes requiring reconstitution for cold-chain diagnostics and biopharmaceuticals. EMA Annex 1 revisions are extending release timelines, prompting dual-source qualification strategies.
Solutions retain volume leadership on continuous processing adoption; lyophilized formats command premium positioning with the steepest specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade stabilizer precursor synthesis clusters within 200 kilometers of Ludwigshafen, Germany, creating geographic concentration risk. India and Switzerland are emerging as alternative qualification hubs for biologics manufacturing.
United States
FDA Type II drug master file standards and HIPAA-compliant procurement channels favor ISO 13485-certified suppliers. Greater Boston and South San Francisco biotech clusters prioritize vendor redundancy over unit cost minimization for monoclonal antibody stabilizer sourcing.
Germany
EMA Annex 1 sterile manufacturing revisions mandate 30-45 day extended endotoxin release testing for fill-finish operations. The Ludwigshafen chemical corridor anchors three-quarters of pharmaceutical-grade precursor synthesis, prompting Irish and German clusters to qualify dual-source suppliers.
India
CDSCO harmonization with IPEC excipient guidelines and PLI scheme import substitution are accelerating domestic qualification programs. Maharashtra and Gujarat pharmaceutical contract manufacturers are expanding local procurement of stabilization chemistries for export to tropical African markets.
Switzerland
Swissmedic oversight and contract manufacturing organization concentration in Basel and Zürich drive demand for trehalose-based lyophilization feedstocks. Swiss CMOs are adopting sugar-derived glass-forming stabilizers for monoclonal antibody formulations ahead of EMA compliance deadlines.
Brazil
ANVISA-regulated fuel-ethanol mills and cost-sensitive biofuel procurement favor suspension-format cellulase stabilizers for high-solids fermentation. São Paulo state processors are balancing acrylate monomer cost volatility against continuous saccharification efficiency requirements.
Enzyme Stabilizer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Diagnostic-grade supply chain credentials separate premium-tier suppliers from commodity food-grade competitors. Three archetypes dominate: integrated life science conglomerates with regulatory documentation depth, specialty chemical manufacturers with polymer coating expertise, and agricultural processors with feedstock cost advantages. Strategic moves concentrate on dual-source qualification partnerships and trehalose purification capacity expansion.
Within the integrated life science tier, Thermo Fisher Scientific and MilliporeSigma occupy positions anchored by diagnostic-grade supply chain infrastructure. Evonik Industries exemplifies the specialty polymer archetype through aqueous coating chemistries. Among agricultural-originated suppliers, Archer Daniels Midland and Cargill represent cost-leadership positioning in food-grade volume segments. Meihua Group anchors Chinese-origin fermentation-derived stabilizer supply. Roche Custom Biotech and BASF Nutrition sit within European pharmaceutical-nutrition hybrid positioning.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| MilliporeSigma |
| Archer Daniels Midland |
| Sun Chemical |
| Roche Custom Biotech |
| BASF Nutrition |
| Evonik Industries |
| Meihua Group |
| Cargill |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day endotoxin release timelines for pharmaceutical-grade stabilizers concentrate pricing power with certified suppliers near Ludwigshafen, while food-grade buyers in India negotiate on spot-market polyol terms. This lead-time differential separates premium biopharmaceutical procurement from cost-driven food processing channels.
Pricing Analysis
REACH registration and FDA Type II drug master file standards dictate the pricing tier structure across pharmaceutical, food-grade, and research-laboratory segments. Three-tier pricing separates GMP-certified excipient grades from technical-grade industrial formulations and commodity food-processing volumes. Price differentiation hinges on endotoxin documentation depth and ISO 13485 certification status. Cost compression in food-grade liquid stabilizers is intensifying because Brazilian and Indian fuel-ethanol mills prioritize cost-per-activity metrics over purity thresholds. Biotechnology end users in Massachusetts and Basel exhibit the lowest price sensitivity, while biofuel processors in São Paulo state anchor the elasticity spectrum.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes shapes inbound logistics costs for trehalose raw material sourced from Chinese fermentation facilities. Pharmaceutical-grade precursor synthesis concentrates in Germany, Switzerland, and Ireland, while food-grade polyol production feeds from Indian and Brazilian agricultural processors. Supply chains draw from acrylate monomer petrochemical streams, sugar-derived fermentation feedstocks, and specialty salt precursors. Single-source vulnerability concentrates in the Ludwigshafen chemical corridor, where three-quarters of high-purity stabilizer synthesis occurs within a two-hundred-kilometer radius. Distribution runs through integrated life science distributors for sub-kilogram research orders and direct-to-manufacturer contracts for bulk pharmaceutical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The enzyme stabilizer market tracks a cyclical recovery anchored to biologics manufacturing capacity expansion in India and Germany. Contract manufacturing organization buildouts are restocking excipient inventories after destocking phases in prior periods.
For Market Incumbents: Consolidate trehalose purification capacity and dual-source qualification partnerships to defend against endotoxin testing timeline extensions under EMA Annex 1 revisions. Deepen backward integration into sugar-derived fermentation feedstocks to buffer acrylate monomer cost volatility. Lock in integrated supply agreements with Cambridge and South San Francisco biotech clusters before regional competitors complete CDSCO harmonization programs.
For New Entrants and Emerging Players: Differentiate on CDSCO-fast-tracked excipient qualification for Indian pharmaceutical contract manufacturers exporting to tropical African markets. Target lyophilized diagnostic stabilizers for point-of-care healthcare procurement in Saudi Arabia and the UAE, where military and tropical stability requirements sustain niche premium positioning. Pursue direct-to-biotech e-commerce distribution for research-laboratory gram-scale orders, disintermediating traditional distributor networks.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because regulatory documentation burdens are filtering uncertified regional producers from REACH-regulated and FDA-monitored procurement channels. Acquisition candidates include mid-cap stabilizer blenders with existing ISO 13485 credentials and trehalose purification assets. Monitor ECHA substance evaluation wave completion rates as the inflection signal for replacement demand velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Trehalose Purification Capacity Expansion | Addresses sugar-derived glass-forming stabilizer demand from Swiss and Massachusetts monoclonal antibody formulators. |
| CDSCO Harmonization Qualification Program | Captures first-mover advantage ahead of domestic Indian competitors in pharmaceutical contract manufacturing. |
| Dual-Source Supplier Partnership | Mitigates batch-release uncertainty from EMA Annex 1 endotoxin testing timeline extensions in Irish and German clusters. |
| Direct-to-Biotech E-Commerce Platform | Disintermediates traditional distributor networks for sub-kilogram research-grade stabilizer orders in Boston and Basel. |
| Backward Integration into Fermentation Feedstocks | Reduces exposure to volatile petrochemical acrylate monomer pricing in specialty polymer coating chemistries. |
Research Methodology
A standing panel of biopharmaceutical formulation scientists, food processing procurement leads, contract manufacturing organization supply chain directors, and diagnostic reagent quality managers provided ongoing calibration across primary interview rounds. Secondary validation drew from EMA Annex 1 guidance documents, FDA Type II drug master file repositories, CDSCO excipient notification records, and IPEC certification databases. Bottom-up segment sizing triangulated against top-down industry spend estimates from chemical trade associations and biotechnology capital expenditure disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled formulation format, application tier, end-user sophistication, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from elasticity-adjusted demand curves and capacity buildout timelines. Forecast inputs incorporated perfusion cell-culture adoption rates, directed-evolution thermostable enzyme substitution thresholds, and trehalose purification capacity expansion announcements.
The analysis sits within stated boundaries; outcomes outside sustained biologics manufacturing investment, stable petrochemical feedstock pricing, and regulatory harmonization trajectories would require recalibration. Forecasts reflect documented assumptions regarding endotoxin testing timeline stability, REACH registration completion rates, and CDSCO enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Anti-Slip Additives Market
Additives
Middle East Feed Additives Market
Additives
Japan Sodium Reduction Ingredient Market
Additives
Sorbitan Esters Market
Additives
Hydrogen Peroxide Chemical Indicator Market
Additives
Lauroyl Methyl Glucamide Market
Additives
Germany Sodium Reduction Ingredient Market
Additives
Gelatin Peptones Market
Additives
Disodium Guanylate Market
Additives
United States Betaine Market
Additives
Spain Anti Caking Market
Additives
Binder Excipients Market
Additives
Rheological Additives Market
Additives
Engine Oil Additive Market
Additives
Tire Additives Market
Additives
Octane Improver Fuel Additives Market