
 Europe Pigments Market | 2026-2036
Europe Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pigments Market Insights
Specialty pigment formulation revenue is fragmenting across regional compounders and multinational suppliers. BASF SE leverages integrated azo pigment complexes to sustain pricing power in automotive refinish channels. Clariant AG anchors its position through phthalocyanine blue leadership in packaging inks. LANXESS competes via chromium oxide green specialization for high-temperature industrial coatings.
Pigments are finely ground insoluble particles, typically 0.1 to 10 micrometers in diameter, that impart color through selective light absorption and scattering; titanium dioxide dominates opacity engineering while organic chromophores deliver saturated hues in plastics and printing applications. Inorganic pigments command the largest volume pool across European construction materials, yet specialty pigments capture disproportionate margins in automotive and electronics applications where heat stability and regulatory compliance justify premium positioning. Powder formulations lead industrial uptake, though liquid dispersions are gaining share in waterborne coating systems where mill-base integration reduces volatile organic compound emissions.
REACH registration requirements and the EU Green Deal carbon border adjustments constrain import access for non-compliant Asian suppliers while redirecting domestic capacity toward lower-toxicity chemistries. ECHA substance evaluation protocols and the F-Gas Regulation indirectly shape pigment demand by accelerating coating reformulation cycles across member states. Stakeholders must monitor regulatory divergence between EU harmonized standards and emerging national eco-label schemes that could fragment procurement specifications across the continent.
Market Dynamics
REACH substance evaluation protocols and EU Green Deal carbon border adjustments are redirecting procurement toward compliant domestic suppliers while accelerating formulation cycles across automotive and packaging coatings.
Growth Catalysts
- Automotive Coatings Reformulation:German and French OEMs are expanding procurement of high-performance organic pigments to meet EU Green Deal decarbonization mandates for vehicle lifecycle emissions.
- ECHA Substance Evaluation:REACH compliance requirements are constraining import access for non-compliant Asian suppliers, creating protected demand pools for European compounders with registered portfolios.
- Bio-based Feedstock Transition:Southern European formulation houses are redirecting investment toward specialty pigment portfolios derived from renewable feedstocks to capture sustainability premiums in consumer packaging.
Market Restraints
- Titanium Dioxide Feedstock Volatility:Ilmenite and rutile concentrate prices fluctuate with Chinese mining output controls, compressing margins for sulfate-process TiO2 producers in Spain and Italy.
- Chromium Compound Restrictions:ECHA authorization requirements for chromium(VI) pigments are forcing industrial coatings formulators to qualify alternative heat-stable inorganics at elevated technical cost.
- Substitution by Effect Pigments:Automotive designers in Stuttgart and Turin are specifying interference pigments and aluminum flakes to achieve color-shifting effects without traditional organic chromophores.
Strategic Opportunities
- Polish and Czech Industrial Coatings:Underpenetrated Central European manufacturing corridors offer expansion paths for pigment dispersion facilities serving automotive component suppliers.
- Waterborne Coating Integration:Liquid pigment dispersions are capturing share in Benelux architectural coatings where mill-base integration reduces volatile organic compound emissions and accelerates production cycles.
- CSRD-Driven Disclosure Requirements:Corporate Sustainability Reporting Directive mandates are creating service revenue streams for pigment suppliers offering certified carbon footprint data and supply chain traceability documentation.
Industry Challenges
- Color Chemist Talent Scarcity:Formulation expertise in azo complex stabilization and phthalocyanine synthesis is concentrating at retiring specialists in Basel and Ludwigshafen, constraining R&D throughput at mid-tier compounders.
- Multi-Jurisdictional Certification Timelines:Pigment producers must synchronize EU REACH registrations with emerging national eco-label schemes in France, Germany, and Italy that fragment procurement specifications.
- Legacy Equipment Retrofit Costs:Southern European powder pigment facilities face capital intensity in converting spray-drying operations to meet F-Gas Regulation thermal efficiency standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pigments Market |
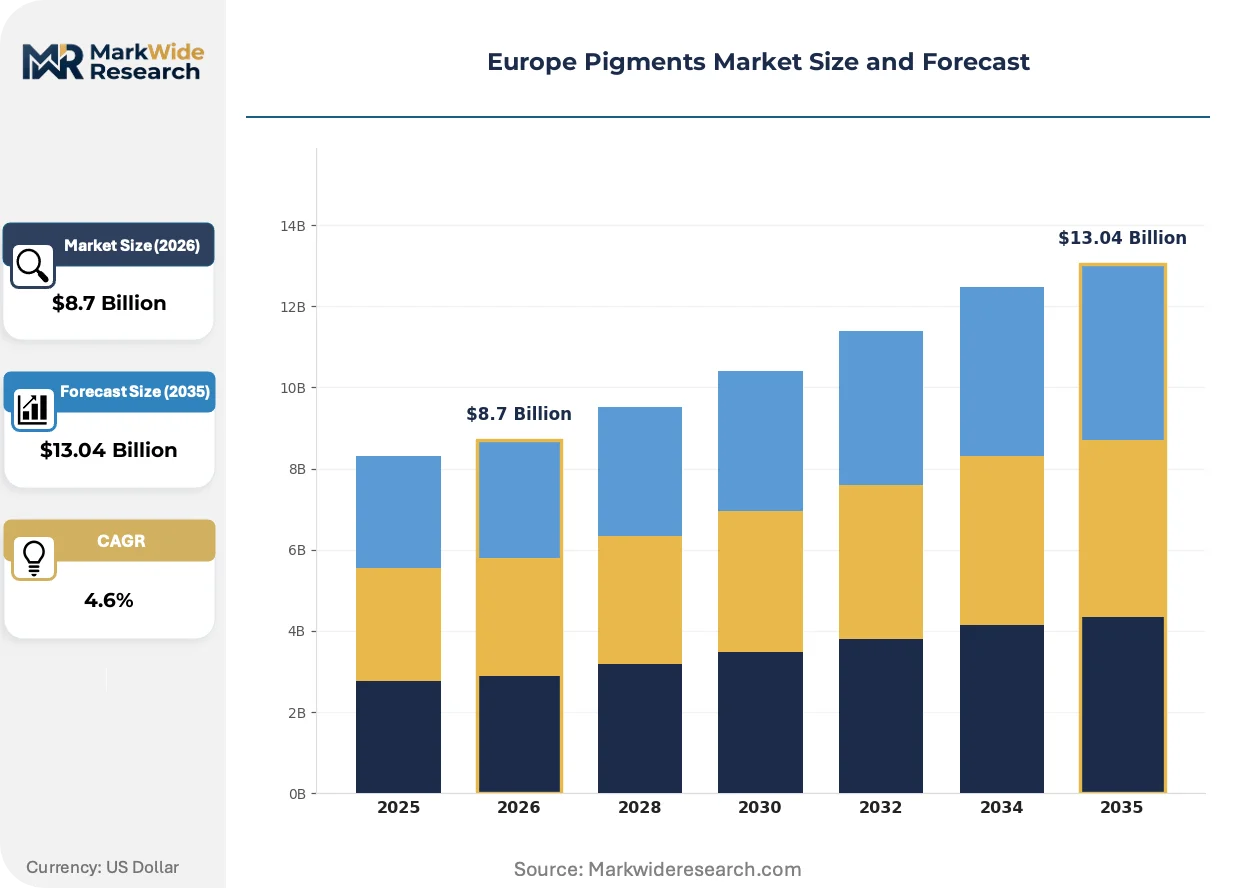
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Pigments, Inorganic Pigments, Specialty Pigments, Color Additives Application: Coatings, Plastics, Inks, Construction Materials End User: Automotive, Consumer Goods, Packaging, Construction Form: Powder, Liquid, Granular, Paste |
| Companies Covered | BASF SE, Clariant AG, DIC Corporation, LANXESS, Heubach GmbH, Huntsman Corporation, Merck KGaA, The Chemours Company, Cabot Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pigments Market Trends and Innovations
Formulation chemistry is pivoting toward lower-toxicity alternatives as regulatory pressure intensifies, while dispersion technology evolves to serve waterborne coating architectures.
High-performance organic pigments are migrating from solvent-borne automotive refinish systems into waterborne basecoat formulations. German OEM collision repair networks are adopting these dispersions to maintain color matching precision while meeting volatile organic compound limits. This technology is migrating from premium vehicle segments into mass-market platforms as compliance deadlines tighten.
ECHA authorization procedures under REACH are compressing the commercial lifespan of legacy heavy-metal pigments in industrial applications. The F-Gas Regulation indirectly accelerates this transition by mandating coating reformulation for heat-exchange equipment manufacturers. Southern European construction coatings producers are most affected, with Italian and Spanish formulators accelerating qualification of bismuth vanadate and complex inorganic color pigments as replacements.
Specification behavior among coatings procurement departments is fragmenting as sustainability credentials displace pure cost optimization in supplier selection. Automotive tier-one suppliers in France and Germany now require carbon footprint documentation alongside technical datasheets, compressing vendor qualification cycles. This pattern is most visible in Stuttgart and Munich, where BMW and Mercedes-Benz supply chain audits prioritize pigment traceability from mine to mill.
Europe Pigments Market Segmentation
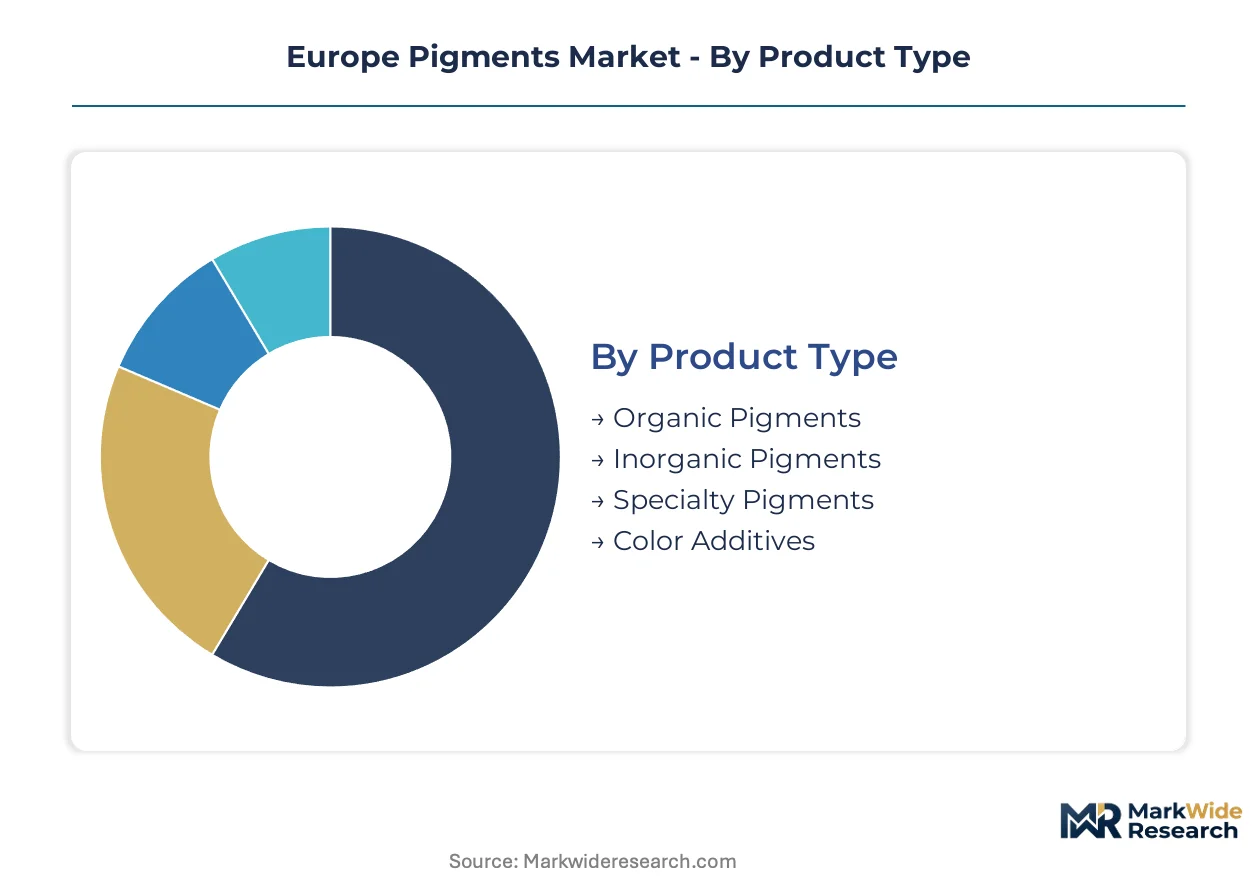
Pigment procurement specifications diverge sharply across European end-use verticals. Formulators in Germany's automotive supply chain demand heat-stable dispersions with full REACH traceability, while Italian construction material producers prioritize cost-engineered powder grades for cement coloration.
Product Type:
After-sales technical support intensity varies dramatically across pigment chemistries, with specialty grades requiring dedicated color-matching laboratories and organic azo complexes demanding regulatory compliance documentation.
- Organic Pigments:Carbon-based chromophores including azo and phthalocyanine structures deliver saturated hues with lower density than mineral alternatives. German automotive refinish networks in Stuttgart and Munich specify these for waterborne basecoat systems under EU VOC limits.
- Inorganic Pigments:Metal oxide and salt-based colorants engineered from titanium dioxide, iron oxide, and chromium compounds dominate construction volume. Spanish cement producers and Italian terrazzo manufacturers absorb the bulk of sulfate-process TiO2 output despite feedstock price volatility from Chinese ilmenite controls.
- Specialty Pigments:High-performance grades with engineered particle morphology for heat stability and lightfastness command technical service investment.
- Color Additives:Pre-dispersed concentrates and masterbatch formulations reduce compounding complexity for mid-tier plastics processors.
Inorganic pigments hold the largest share; momentum sits with specialty pigments as automotive electrification accelerates thermal management coating specifications.
Application:
Application-driven cost tiers separate commodity volume plays from premium formulation services, with coatings commanding the highest technical support overhead.
- Coatings:Architectural, automotive, and industrial liquid and powder systems absorb pigment value through dispersion quality and weathering performance. French OEM collision repair channels and Benelux architectural formulators drive specification toward liquid dispersions that integrate directly into waterborne mill-bases.
- Plastics:Polymer matrix integration demands thermal stability above 280°C for engineering resins used in under-hood automotive components. Bavarian and Czech injection molders specify phthalocyanine blues and complex inorganic color pigments for dashboard and exterior trim applications.
- Inks:Flexographic and gravure printing systems for flexible packaging require low-migration formulations compliant with EU food contact regulations.
- Construction Materials:Concrete, mortar, and roofing granule coloration consumes iron oxide reds and synthetic blacks in bulk quantities.
Coatings generates the highest value per kilogram; plastics is climbing fastest as electric vehicle lightweighting multiplies polymer content per vehicle.
End User:
Customer-type maturity levels determine procurement sophistication, with automotive buyers imposing the most stringent qualification protocols.
- Automotive:OEM and tier-one supplier specifications cascade through refinish, OEM coatings, and interior plastics. Mercedes-Benz and BMW supply chain audits in Germany now require carbon footprint documentation alongside color tolerance data.
- Consumer Goods:Appliance, electronics, and furniture manufacturers balance aesthetics with regulatory compliance for skin-contact and food-adjacent applications.
- Packaging:Brand owners in France and Italy drive demand for bio-based and low-migration ink systems ahead of EU Single-Use Plastics Directive implementation.
- Construction:Ready-mix concrete and prefabricated element producers prioritize price stability and batch-to-batch consistency over technical innovation.
Automotive commands premium positioning; packaging is expanding most quickly as sustainability credentials reshape supplier selection criteria.
Form:
Supply concentration patterns favor powder production in Southern Europe while liquid dispersion capacity clusters near Benelux coating manufacturing corridors.
- Powder:Dry pigment crystals and spray-dried granules serve plastics compounding and powder coating applications. Italian and Spanish facilities dominate European powder capacity though F-Gas Regulation thermal efficiency standards are forcing capital-intensive dryer retrofits.
- Liquid:Aqueous and solvent-based dispersions with controlled particle size distribution enable direct mill-base integration. Dutch and Belgian architectural coating producers are converting spray lines to liquid systems that cut VOC emissions and accelerate color change cycles.
- Granular:Dust-free handling forms for automated dosing in high-volume construction material plants.
- Paste:High-solids concentrates for specialized ink and coatings applications requiring precise viscosity control.
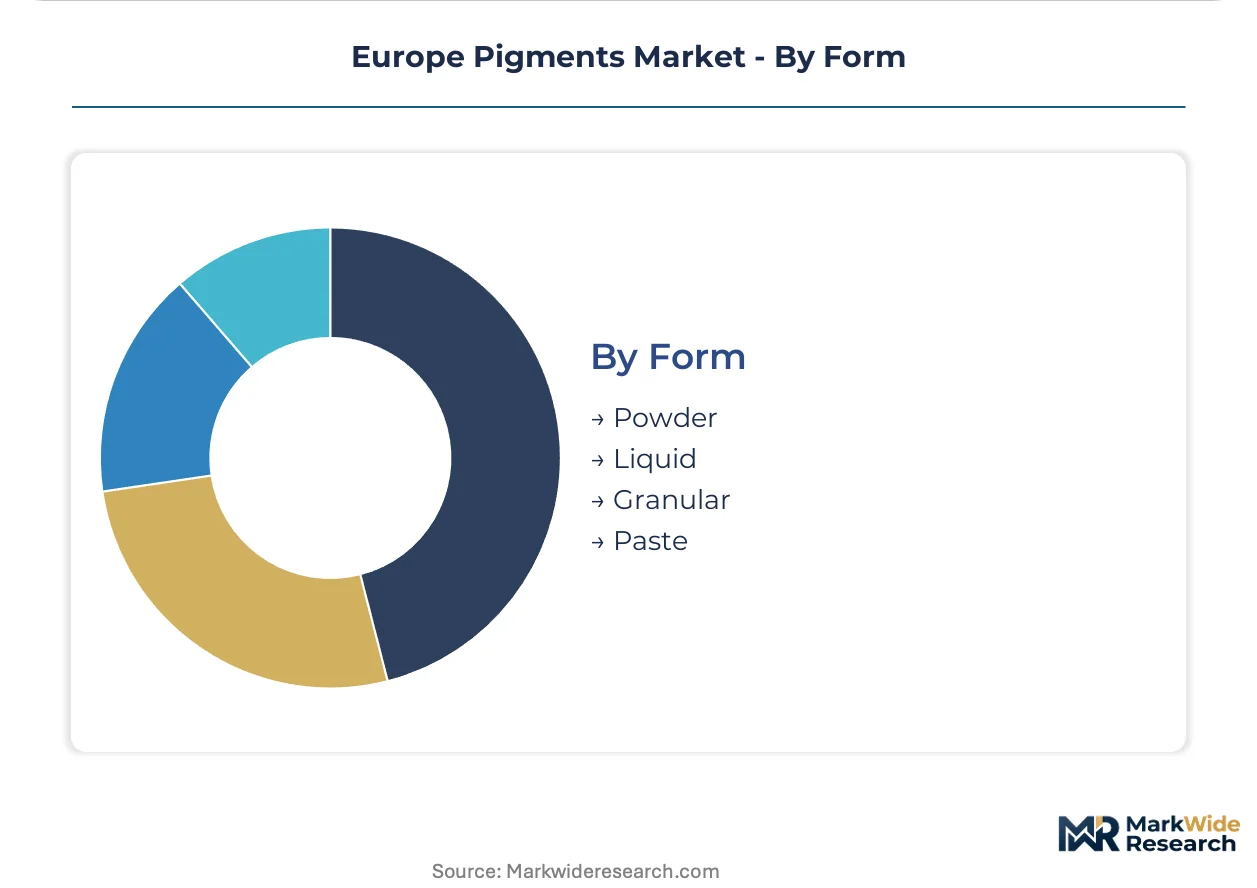
Powder retains volume leadership; liquid is gaining share fastest as waterborne coating conversion accelerates across German and French automotive networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive formulators consume high-performance organic pigments for waterborne refinish systems, while Italian and Spanish construction material producers absorb bulk inorganic grades for cement coloration, creating a bifurcated consumption mix across the continent.
Germany
Stuttgart and Munich automotive clusters drive specification of phthalocyanine blues and complex inorganic color pigments for electric vehicle thermal management coatings. REACH registration requirements under ECHA protocols constrain import access for non-compliant suppliers, protecting domestic compounders with registered portfolios. BASF SE and LANXESS anchor pigment production in Ludwigshafen and Leverkusen, serving Mercedes-Benz and BMW supply chain audits that now mandate carbon footprint documentation.
France
French OEM collision repair networks in Paris and Lyon are converting to liquid pigment dispersions for waterborne basecoat systems under EU VOC limits. The EU Green Deal carbon border adjustments redirect procurement toward compliant domestic suppliers with full supply chain traceability. Packaging ink formulators in the Hauts-de-France region qualify low-migration organic pigments ahead of EU Single-Use Plastics Directive implementation.
Italy
Italian terrazzo manufacturers and cement producers in Lombardy and Veneto absorb sulfate-process TiO2 output despite feedstock price volatility from Chinese ilmenite controls. ECHA authorization requirements for chromium(VI) pigments force industrial coatings formulators to qualify bismuth vanadate replacements at elevated technical cost. Southern European formulation houses redirect investment toward specialty pigment portfolios derived from renewable feedstocks.
Spain
Spanish construction material plants in Catalonia and Andalusia prioritize cost-engineered iron oxide reds and synthetic blacks for concrete coloration. F-Gas Regulation thermal efficiency standards force capital-intensive retrofits of spray-drying operations at powder pigment facilities. The country's national chemical regulator enforces REACH compliance timelines that synchronize with emerging national eco-label schemes fragmenting procurement specifications.
Netherlands
Dutch architectural coating producers in the Randstad convert spray lines to liquid pigment dispersions that cut VOC emissions and accelerate color change cycles. Benelux manufacturing corridors offer expansion paths for pigment dispersion facilities serving automotive component suppliers. CSRD-driven disclosure requirements create service revenue streams for suppliers offering certified carbon footprint data and supply chain traceability documentation.
Europe Pigments Market Competitive Landscape
Capability concentration sits with integrated azo and phthalocyanine specialists; scale advantage sits with diversified chemical conglomerates with captive titanium dioxide feedstock access. The vendor base separates into three strategic archetypes: multinational integrated producers, regional formulation houses, and niche specialty compounders. Dominant competitive moves include backward integration into ilmenite and rutile concentrate sourcing, and geographic expansion into underpenetrated Central European industrial corridors.
Among Germany-based chemical conglomerates, BASF SE and LANXESS exemplify the integrated producer archetype with positions across organic and inorganic pigment chemistries. Swiss specialty chemical player Clariant AG occupies a position within the high-performance organic segment, particularly in packaging ink applications. These three entities anchor the competitive structure, with regional European compounders and Asian suppliers contesting volume segments where regulatory compliance barriers are lower.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| DIC Corporation |
| LANXESS |
| Heubach GmbH |
| Huntsman Corporation |
| Merck KGaA |
| The Chemours Company |
| Cabot Corporation |
| Others |
Pricing and Supply Chain Analysis
REACH registration chokepoints determine both tier spreads and supply chain configuration across European pigment procurement. ECHA substance evaluation protocols compress margins for non-compliant Asian suppliers while protecting premium positioning for registered domestic compounders serving automotive OEMs.
Pricing Analysis
Long-term offtake contracts dominate procurement between German automotive OEMs and domestic azo pigment specialists, insulating BASF and LANXESS from ilmenite spot volatility. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered specialty grades from unregistered commodity imports and construction-grade iron oxides. Cost compression in sulfate-process TiO2 is intensifying because Chinese mining output controls squeeze Spanish and Italian producers. Construction material buyers in Southern Europe exhibit highest price sensitivity; automotive tier-one suppliers in Stuttgart and Munich prioritize traceability documentation over unit cost.
Supply Chain Analysis
EU Green Deal carbon border adjustments function as de facto export controls, restricting non-compliant pigment flows from Chinese and Indian producers. Feedstock concentration centers on Chinese ilmenite and rutile mining, German phthalocyanine intermediate synthesis, and Finnish titanium dioxide chloride-process output. Supply chain risk rests on single-source vulnerability for high-purity chromium oxide green feedstocks facing ECHA authorization withdrawal. Distribution runs through Benelux liquid dispersion hubs for waterborne coatings and Italian powder facilities serving construction materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's pigments sector sits in early-cycle expansion as electric vehicle thermal management coatings multiply addressable demand for heat-stable organic pigments. Waterborne reformulation mandates across German and French automotive networks accelerate specification upgrades.
For Market Incumbents: Harden azo and phthalocyanine formulation capabilities against substitution by interference pigments in Stuttgart design studios. Deepen backward integration into ilmenite sourcing to offset Chinese concentrate volatility compressing sulfate-process margins. Anchor Ludwigshafen and Leverkusen capacity with dedicated color-matching laboratories serving Mercedes-Benz and BMW supply chain audits. For New Entrants and Emerging Players: Build out liquid dispersion facilities in Polish and Czech industrial corridors serving underpenetrated automotive component suppliers. Target waterborne coating integration in Benelux architectural markets where mill-base compatibility reduces VOC compliance costs. Lead with CSRD-certified carbon footprint documentation to displace mid-tier compounders lacking traceability infrastructure. For Investors and Strategic Acquirers: ECHA authorization timelines for chromium(VI) replacements reshape the acquisition landscape toward bismuth vanadate and complex inorganic color pigment specialists. Five-to-ten year viability favors regional compounders with registered portfolios and captive dispersion technology. Watch for REACH substance evaluation acceleration as the inflection signal forcing portfolio consolidation among legacy heavy-metal pigment producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ilmenite Sourcing | Captive rutile concentrate supply insulates German TiO2 producers from Chinese export quota volatility. |
| Waterborne Dispersion Capacity Expansion | Liquid pigment facilities in Randstad corridor capture Benelux architectural coating conversion demand. |
| REACH Registration Portfolio Acquisition | Registered azo complexes command protected pricing in automotive refinish channels facing ECHA scrutiny. |
| Bio-based Feedstock Qualification | Renewable-derived specialty pigments capture sustainability premiums in French and Italian packaging markets. |
| CSRD Traceability Service Launch | Certified carbon footprint documentation opens service revenue from BMW and Mercedes-Benz supply chain audits. |
Research Methodology
Initial hypotheses were tested against primary input from automotive coating procurement managers, pigment plant technical directors, ECHA regulatory affairs specialists, and construction materials buyers, then refined against secondary validation. Data synthesis drew from customs trade records, Cefic chemical industry reports, SEC 10-K filings of listed pigment producers, and EU REACH registration databases. Bottom-up volume modeling across end-use applications triangulated with top-down value estimates from production capacity assessments.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeling across pigment chemistry type, application vertical, and regional production hub. CAGRs derived from compound growth trajectory analysis of historical consumption patterns and projected formulation cycle acceleration. Forecast inputs incorporated electric vehicle production ramp schedules and EU Green Deal carbon border adjustment implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Chinese TiO2 producers would shift outcomes. Material shifts in ECHA substance evaluation acceleration or F-Gas Regulation thermal efficiency standard tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Acid Dyes Market
Dyes and Pigments
Thermochromic Labels Market
Dyes and Pigments
Indigo Carmine Market
Dyes and Pigments
Natural Colorants Market
Dyes and Pigments
Thermochromic Pigments Market
Dyes and Pigments
Organic Pigment Dispersions Market
Dyes and Pigments
Azo Pigments Market
Dyes and Pigments
Chlorophyll Color Market
Dyes and Pigments
Acid Orange Market
Dyes and Pigments
Polymer Colorant Market
Dyes and Pigments
Cadmium Pigments Market
Dyes and Pigments
High Performance Organic Pigments Market
Dyes and Pigments
Bismuth Vanadate Pigment Market
Dyes and Pigments
Fluorescent Brightening Agents Market
Dyes and Pigments
Metal Complex Dyes Market
Dyes and Pigments
Phthalocyanine Blue Market