
 Potassium Nitrate Market | 2026-2036
Potassium Nitrate Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Nitrate Market Intelligence
Specialty glass manufacturing is consolidating its share of potassium nitrate offtake as solar energy expansion drives demand for optical-grade material. Haifa Group leverages its vertical integration from raw brine to refined crystals to sustain cost leadership in premium grades. SQM competes through its Atacama Desert nitrate deposits, while ICL Group Ltd. anchors Mediterranean supply with Dead Sea-derived production.
Potassium nitrate is an inorganic salt with the chemical formula KNO3, typically produced through fractional crystallization of nitrate-rich brines or chemical synthesis, and functions primarily as an oxidizer, fertilizer nutrient, and food preservative. Granular product types dominate agricultural channels due to ease of mechanical spreading, while powder grades command margin pools in pharmaceutical and pyrotechnic applications where particle size precision governs performance. Food preservation demand tracks regulatory thresholds for cured meat applications, with solution formats gaining traction in industrial water treatment processes.
EPA standards in the United States limit nitrate discharge from fertilizer production facilities, while REACH registration in Europe mandates full toxicological dossiers for import authorization. ISO 9001 certification governs pharmaceutical-grade manufacturing protocols, creating compliance barriers for unqualified entrants. Stakeholders must monitor evolving fertilizer subsidy regimes and decarbonization mandates that threaten brine-evaporation energy costs.
Market Dynamics
Specialty glass manufacturers are capturing potassium nitrate offtake as solar energy deployment accelerates demand for optical-grade material with ultra-low iron content. This demand rotation is compressing traditional agricultural margins while rewarding producers with crystallization precision capabilities.
Growth Catalysts
- Solar glass specification tightening:Photovoltaic panel producers in China and Germany now mandate sub-50 ppm iron content in melt batches, pulling premium-grade potassium nitrate into optical supply chains.
- REACH impurity threshold reductions:ECHA's 2024 amendment to food-grade registration dossiers is forcing impurity elimination investments that upgrade byproduct streams into saleable technical grades.
- Dead Sea brine processing infrastructure:Israel's integrated evaporation-crystallization complexes maintain cost advantages in high-purity output that Asian chemical synthesis routes struggle to match.
Market Restraints
- Natural gas price volatility:Brine evaporation and thermal crystallization stages depend on natural gas input costs that fluctuate with European supply disruptions.
- Supply concentration in evaporite deposits:Chilean caliche and Israeli Dead Sea operations control over 70% of primary nitrate feedstock, creating single-source vulnerability.
- Sodium nitrate substitution in agricultural blends:Compound fertilizer formulators in Brazil and India are substituting sodium nitrate where potassium specificity is not agronomically critical.
Strategic Opportunities
- Underpenetrated Southeast Asian glassmaking:Vietnam and Indonesia lack domestic optical-grade supply, creating import substitution potential for integrated producers with logistics scale.
- Pharmaceutical-grade certification expansion:USP and EP compliance for excipient applications opens margin pools in tablet disintegration and osmotic pump technologies.
- EU Green Deal carbon border adjustments:Solar glass imports into Europe face embodied carbon tariffs that favor low-carbon nitrate sources with verified Scope 1-2 data.
Industry Challenges
- ISO 9001 pharmaceutical certification timelines:Eighteen-month validation cycles delay market entry for producers upgrading from technical to medical-grade protocols.
- Crystallization engineer scarcity:Fractional crystallization optimization requires expertise in phase diagram manipulation that retiring specialists in Germany and Japan are not replenishing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Nitrate Market |
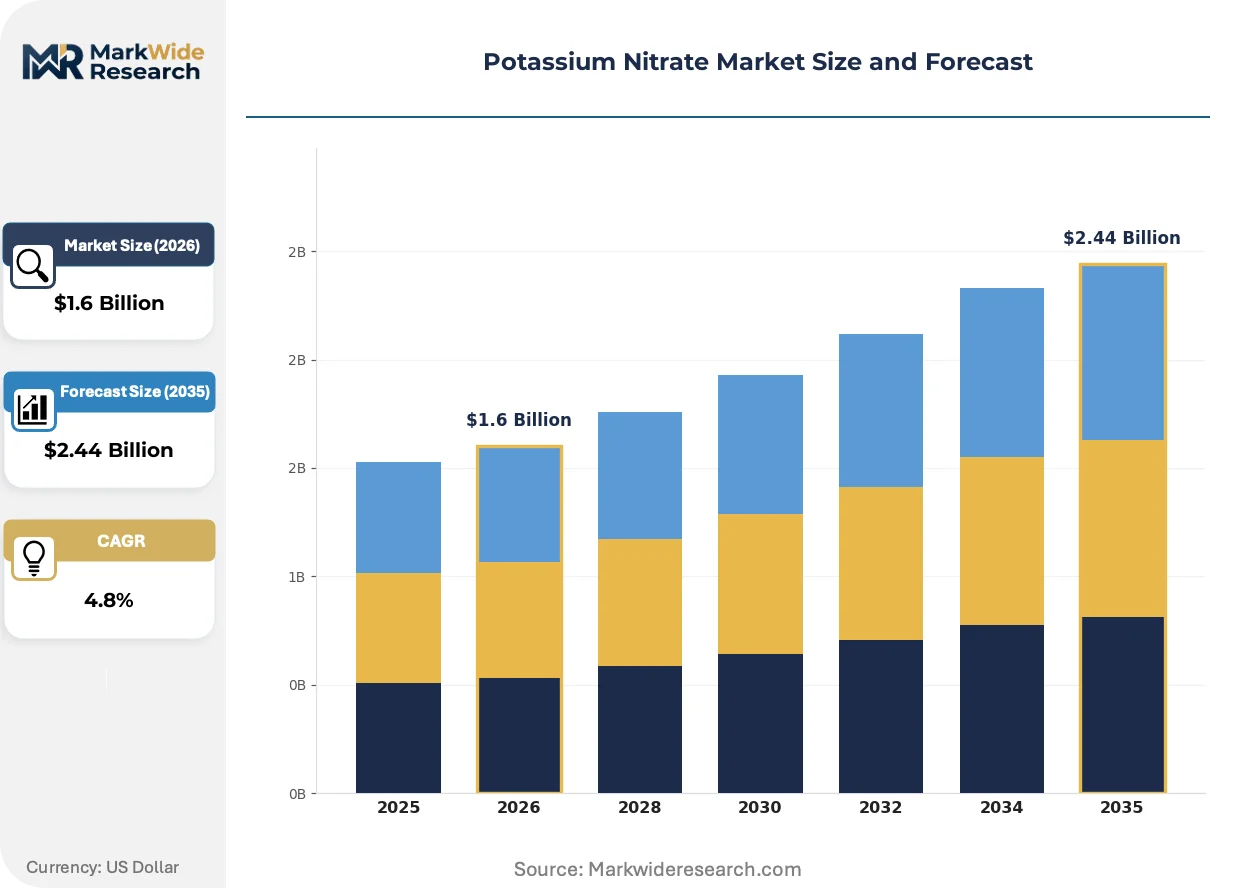
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $2.44 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Solution Application: Agriculture, Food Preservation, Pharmaceuticals, Fertilizers End User: Agricultural Producers, Food Manufacturers, Healthcare Providers, Chemical Industries Distribution Channel: Wholesale, Online Retail, Direct Sales, Distributors |
| Companies Covered | Arab Potash Company, ICL Group Ltd., Haifa Group, AG CHEMI GROUP, American Elements, SQM, Uralchem, Positive Group, Yara International ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Nitrate Market Strategic Shifts & Innovations
Continuous crystallization technology is displacing batch processing in premium-grade production, while regulatory carbon accounting and buyer procurement centralization are rewriting competitive rules. These forces favor capital-intensive players with integrated analytical capabilities.
Membrane filtration pre-concentration is absorbing dissolved solids from dilute brine streams before thermal processing, cutting energy intensity by eliminating early-stage evaporation loads. Solar glass manufacturers in Germany and China are specifying membrane-treated feedstock to meet carbon disclosure requirements. This technology is absorbing market share from conventional multi-effect evaporators in new capacity installations.
REACH registration dossier updates are mandating full substance toxicity profiling for potassium nitrate imports into Europe, extending authorization timelines for non-EU producers. The industrial consequence is a bifurcation between registered suppliers with active dossiers and traders facing import barriers. Food-grade and pharmaceutical segments are consolidating procurement around ECHA-registered sources to avoid supply interruption.
Buyer consortium formation among solar glass manufacturers is consolidating procurement volumes and standardizing quality specifications across tier-one producers in China, Germany, and South Korea. Long-term offtake agreements with fixed purity bands are displacing spot market purchases for optical-grade material. This concentration is most visible in the Yangtze River Delta cluster where panel producers have unified nitrate specifications.
Potassium Nitrate Market Segmentation
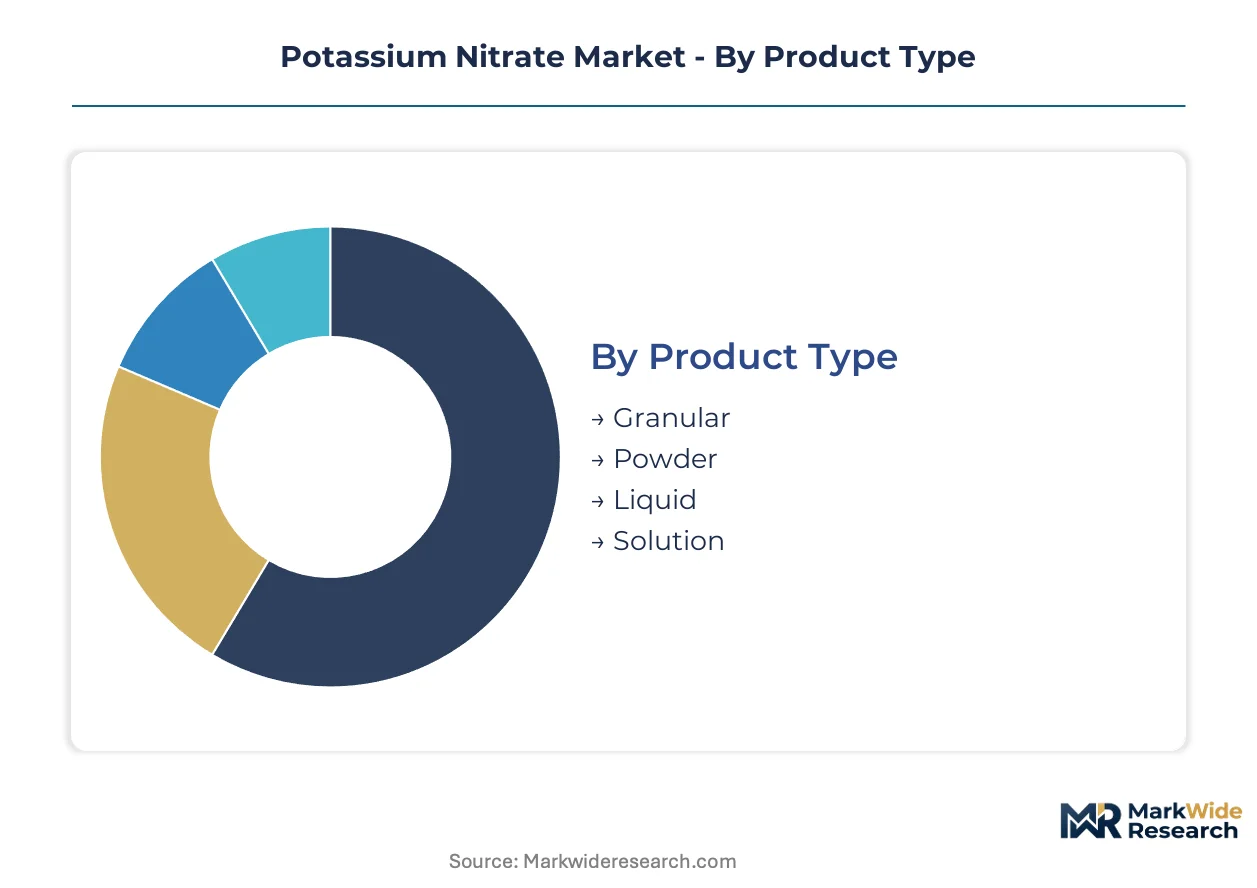
Potassium nitrate segmentation tracks crystallization precision, purity thresholds, and channel economics. Each dimension governs margin capture and regulatory compliance differently across agricultural, optical, and pharmaceutical end-uses.
Product Type:
Crystallization method and particle engineering determine application suitability and pricing tier.
- Granular:Dense crystalline particles ranging 2-4 mm produced through controlled cooling crystallization. Mechanical spreading compatibility concentrates demand in Brazilian and Indian broad-acre agriculture where fertilizer application equipment requires free-flowing material. Natural gas price volatility directly compresses margins for thermal-processed granular output.
- Powder:Fine particulate below 150 microns milled from refined crystal feedstock. Pyrotechnic manufacturers in Germany and pharmaceutical formulators in Switzerland specify narrow particle distribution for oxidizer consistency and tablet disintegration performance. REACH registration mandates for food-contact applications are upgrading technical powder streams into certified grades.
- Liquid:Aqueous solutions at 40-60% concentration by weight, shipped in bulk tanker configurations for industrial water treatment and metal finishing applications. Municipal utilities in the United States specify liquid delivery for continuous dosing systems.
- Solution:Saturated or near-saturated preparations for food brining and specialized agricultural fertigation. Meat processors in Italy and Spain procure solution formats for standardized curing operations.
Mature deployment sits with Granular. Newer deployment is concentrated in Powder.
Application:
End-use specifications diverge sharply on iron content, heavy metal limits, and certification requirements.
- Agriculture:Compound fertilizer blending and direct application as potassium-nitrogen source. Brazilian soybean producers and Israeli greenhouse operators represent volume anchors, though sodium nitrate substitution threatens potassium-specific demand where soil chemistry permits.
- Food Preservation:Cured meat applications governed by FDA and EFSA maximum residue limits. ECHA's updated REACH dossier requirements are forcing impurity elimination investments that upgrade technical material into food-grade streams.
- Pharmaceuticals:Excipient functions in osmotic pump tablets and disintegration aids. USP and EP compliance opens margin pools, though eighteen-month ISO 9001 validation cycles delay producer entry from technical grades.
- Fertilizers:Specialized potassium nitrate-based formulations for chloride-sensitive crops. Premium greenhouse and hydroponic operations in the Netherlands and Spain specify low-chloride material for high-value vegetable production.
Volume concentration remains in Agriculture. Value expansion is climbing the fastest in Pharmaceuticals.
End User:
Procurement sophistication and specification stringency separate customer tiers.
- Agricultural Producers:Large-scale farming operations and cooperative purchasing organizations. Brazilian soybean growers and Israeli desert agriculture operations anchor offtake through long-term supply contracts.
- Food Manufacturers:Industrial meat processors and cured product specialists. Italian charcuterie producers and Spanish ham manufacturers specify solution and powder formats for standardized curing protocols.
- Healthcare Providers:Hospital pharmacies and compounding facilities sourcing pharmaceutical-grade material for specialized formulations. German and Swiss healthcare procurement centralizes around certified excipient suppliers.
- Chemical Industries:Specialty glass manufacturers, pyrotechnic producers, and water treatment operators. Solar panel glass producers in China and Germany now mandate sub-50 ppm iron content, pulling premium-grade material into optical supply chains.
Procurement scale dominates with Agricultural Producers. Specification intensity is expanding most quickly with Chemical Industries.
Distribution Channel:
Channel selection reflects shipment scale, certification documentation requirements, and customer technical service needs.
- Wholesale:Bulk material aggregation for agricultural and industrial volume buyers. Brazilian and Indian fertilizer distributors consolidate procurement through wholesale structures.
- Online Retail:Small-package sales for laboratory, hobbyist, and specialty agricultural users. Limited to technical grades without pharmaceutical or food certification.
- Direct Sales:Producer-to-customer relationships for pharmaceutical and optical-grade material requiring certificate-of-analysis documentation and technical support. Haifa Group and ICL Group leverage direct channels for premium grades.
- Distributors:Regional stocking points for just-in-time delivery to food manufacturers and water treatment operators. European distributors increasingly require ECHA-registered sources to avoid import authorization gaps.
Volume flow runs through Wholesale. Margin capture is concentrating in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in evaporite-rich territories while consumption disperses across agricultural and industrial end-markets. Israel and Chile control primary nitrate feedstock through Dead Sea brine and Atacama caliche deposits. Manufacturing clusters in Germany and China process imported material into optical-grade and pharmaceutical specifications.
Israel
Dead Sea evaporation-crystallization complexes supply high-purity potassium nitrate to European solar glass manufacturers. The national chemical regulator enforces export documentation standards that align with REACH pre-registration requirements. ICL Group's integrated operations near Sodom anchor Mediterranean supply chains with captive brine processing.
Chile
Atacama Desert nitrate caliche deposits feed SQM's production of technical and agricultural grades. The country's mining environmental authority monitors extraction impacts under updated sustainability protocols. Antofagasta region processing facilities export granular material to Brazilian soybean operations and Asian fertilizer blenders.
Germany
Solar glass manufacturers in Saxony and Thuringia specify sub-50 ppm iron content potassium nitrate for photovoltaic panel production. ECHA's 2024 REACH dossier amendments force importers to maintain active substance registrations. The Bitterfeld-Wolfen chemical cluster hosts refining operations that upgrade technical grades to optical specifications.
China
Yangtze River Delta panel producers have consolidated procurement around unified nitrate purity bands through buyer consortium structures. The Ministry of Ecology and Environment tracks embodied carbon in solar glass supply chains under dual carbon policy frameworks. Jiangsu province crystallization plants serve domestic optical-grade demand while competing with Israeli imports on price.
United States
Municipal water treatment operators in Texas and California specify liquid potassium nitrate for continuous dosing systems. EPA discharge limits on fertilizer production facilities constrain domestic manufacturing expansion. The Gulf Coast chemical corridor imports granular material for agricultural distribution through wholesale channels.
Potassium Nitrate Market Key Industry Players
Top-tier vendors anchor premium-grade supply through integrated brine-to-crystal operations, while mid-scale chemical synthesizers compete on agricultural volume. The market structure bifurcates between evaporite-based producers with captive raw material and conversion-dependent processors buying nitrate feedstock. Three archetypes dominate: Dead Sea/Atacama integrated miners, European-Japanese crystallization specialists, and Chinese-Indian synthesis operators. Competitive moves center on backward integration into brine assets and pharmaceutical-grade certification investments.
Among integrated mining operators, ICL Group Ltd. and SQM exemplify the feedstock-anchored archetype with evaporite-based production positions. Haifa Group occupies a position within the premium-grade tier through Israeli vertical operations. These three entities represent the concentration of optical-grade and food-certified supply capacity that Asian synthesis routes struggle to replicate on cost and purity metrics.
| Leading Market Players |
|---|
| Arab Potash Company |
| ICL Group Ltd. |
| Haifa Group |
| AG CHEMI GROUP |
| American Elements |
| SQM |
| Uralchem |
| Positive Group |
| Yara International ASA |
| Others |
Cost & Logistics Intelligence
Buyer consortium consolidation among solar glass manufacturers in China and Germany is forcing crystallization precision upgrades that compress agricultural-grade margins while rewarding producers with membrane filtration capabilities. This procurement centralization around sub-50 ppm iron specifications is bifurcating supply into premium optical channels and commodity fertilizer streams with diverging pricing power.
Pricing Analysis
Short lead-time premiums of 15-25% apply to pharmaceutical-grade orders requiring USP documentation within 30-day windows, while spot inventory of technical-grade granular material trades at discounts to contract offtake. Contract-based long-term agreements dominate optical-grade procurement, with price differentiation driven by certification tier and volume scale. Cost compression in agricultural grades is intensifying because sodium nitrate substitution in Brazilian and Indian compound fertilizers erodes potassium-specific premiums. Agricultural producers remain most price-sensitive, while pharmaceutical formulators in Switzerland and Germany absorb premiums for excipient-grade consistency.
Supply Chain Analysis
Dual-sourcing mandates from European solar glass manufacturers require active REACH dossiers from both Israeli Dead Sea operators and Chilean caliche processors to avoid single-source vulnerability. Supply concentrates in Israel, Chile, and China, with raw material dependencies on nitrate-rich brines, natural gas for thermal crystallization, and membrane filtration equipment. Single-source vulnerability from evaporite deposit concentration creates structural risk, as over 70% of primary feedstock originates from Dead Sea and Atacama operations. Distribution runs through wholesale channels for agricultural volume, while direct sales capture pharmaceutical and optical-grade margins with certificate-of-analysis documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around REACH-registered producers with captive brine assets, as ECHA's impurity threshold reductions force technical-grade operators into costly upgrades or exit. Smaller synthesis-based players lacking integrated evaporation infrastructure face margin compression from both regulatory compliance and natural gas price volatility.
For Market Incumbents: To counter sodium nitrate substitution in agricultural markets, ICL Group and Haifa Group should deepen backward integration into Dead Sea brine processing while expanding pharmaceutical-grade certification capacity. Captive supply of optical-grade feedstock and ISO 9001 validation investments defend premium positioning against Asian synthesis competitors. For New Entrants and Emerging Players: Capture underpenetrated Southeast Asian glassmaking demand in Vietnam and Indonesia through import substitution partnerships with membrane filtration technology providers. White-space exists in pharmaceutical-grade supply to German and Swiss healthcare procurement, with go-to-market traction through distributor relationships requiring ECHA-registered sources. For Investors and Strategic Acquirers: The window for entry favors integrated evaporite miners with active REACH dossiers and verified Scope 1-2 carbon data qualifying for EU Green Deal border adjustments. Acquisition targets include crystallization specialists in Germany and Japan facing engineer succession gaps. Watch for membrane filtration adoption rates in new Chinese capacity as inflection indicator for cost-competitive optical-grade supply expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Assets | Captive Dead Sea or Atacama feedstock locks in cost advantage against synthesis routes. |
| Pharmaceutical-Grade Certification Investment | USP and EP compliance opens 40% margin premiums in excipient applications. |
| Membrane Filtration Technology Adoption | Pre-concentration cuts energy intensity for solar glass carbon disclosure requirements. |
| Long-term Supply Agreement with Solar Glass Consortiums | Fixed purity band contracts displace spot market volatility in Yangtze River Delta procurement. |
| Joint Venture in Southeast Asian Glassmaking | Vietnam and Indonesia lack domestic optical-grade supply, creating import substitution potential. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plant managers at Dead Sea and Atacama processing facilities, procurement leads at German solar glass manufacturers, and distribution channel partners in Brazilian fertilizer markets. ECHA REACH dossiers, EPA discharge permits, and Israeli export documentation standards provided regulatory validation. Bottom-up crystallization capacity estimates triangulated against top-down end-use consumption models across agricultural, optical, and pharmaceutical segments.
Reconciliation of production volume data from evaporite miners, import statistics from customs authorities, and end-use procurement disclosures from solar panel manufacturers shaped the analytical framework. Segmentation dimensions modeled include crystallization precision tier, iron content specification, certification grade, and regional production hub. CAGRs derived from fitted growth curves incorporating natural gas price elasticity, REACH compliance cost trajectories, and solar deployment forecasts. Industry-specific inputs encompassed membrane filtration adoption rates and crystallization engineer availability indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to European natural gas supply disruptions, ECHA impurity threshold amendments, and Chinese solar glass export tariff structures. Deviation in sodium nitrate substitution rates in Brazilian soybean agriculture would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Caprylyl Glycol Market
Additives
Microcrystalline Cellulose (MCC) Market
Additives
Global Zinc Stearate Market
Additives
Global Sodium Acetate Market
Additives
Tragacanth Market
Additives
Tocopheryl Acetate Market
Additives
Oilfield Drilling Fluid Additive Market
Additives
High Performing Matting Agents Market
Additives
Polymeric Plasticizer Market
Additives
Nucleating Agents Market
Additives
Drilling Fluid Additives Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
Global Pour Point Depressant Market
Additives
Benzoates Market
Additives
Global Butyric Acid Derivatives Market
Additives
Plasticizer Alcohols Market