
 Liquid Silage Additive Market | 2026-2036
Liquid Silage Additive Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Silage Additive Market Analytics
Pharmaceutical-grade fermentation stability is reorganizing competitive tiers in liquid silage additives. Chr. Hansen Holding A/S leverages its microbial strain library to dominate high-performance bacterial inoculants. DSM Firmenich anchors European supply through integrated enzyme manufacturing. BASF SE competes on chemical preservervative scale while extending distribution into emerging dairy clusters.
Liquid silage additives comprise aqueous formulations of homofermentative and heterofermentative lactic acid bacteria, cellulolytic enzymes, and organic acids applied at 10^5–10^6 CFU per gram of fresh forage to accelerate pH decline and inhibit clostridial spoilage. Their primary purpose is preserving nutritional value in grass, maize, and legume silage for ruminant feed. Bacterial additives command the largest volume position due to proven efficacy in aerobic stability, while enzymatic additives represent the fastest-expanding margin pool as dairy operations pursue fiber digestibility gains. Concentrated liquid forms retain structural preference among large livestock operations for precision dosing and tank-mix compatibility.
EU Green Deal methane targets and REACH chemical restrictions are reshaping formulation requirements across member states. EFSA feed additive evaluations now mandate strain-specific safety dossiers for bacterial inoculants, elevating R&D barriers. Stakeholders must monitor regulatory divergence between EU harmonized standards and emerging national sustainability certifications that could fragment market access.
Market Dynamics
EU Green Deal methane-reduction mandates are compressing formulation windows for livestock feed preservatives, forcing additive suppliers to demonstrate strain-specific efficacy under tighter EFSA safety dossier requirements while dairy operations seek fermentation stability guarantees.
Growth Catalysts
- EFSA Strain-Specific Dossiers:Harmonized safety documentation across EU member states is accelerating bacterial inoculant standardization and reducing regulatory fragmentation for cross-border suppliers.
- Dairy Farm Consolidation:Large-scale operations in Germany and the Netherlands are demanding precision-dosing liquid formulations compatible with automated feed mixing systems.
- Cellulolytic Enzyme Advances:Fiber digestibility gains from next-generation enzymatic additives are pulling investment away from chemical preservative categories.
Market Restraints
- Lactic Acid Bacteria Supply Concentration:Strain banking and master cell culture production cluster in Denmark and the Netherlands, creating single-source vulnerability for inoculant formulators.
- REACH Chemical Restrictions:Organic acid preservatives face escalating registration costs and use limitations, narrowing formulation flexibility for hybrid products.
- Fermentation Failure Liability:Batch spoilage attribution disputes between additive suppliers and dairy operations are elevating insurance and contractual risk premiums.
Strategic Opportunities
- Polish Dairy Expansion:Underpenetrated large-farm segments in eastern EU member states present first-mover positioning for precision-dosing liquid additive systems.
- Biogas Digestate Integration:Converging anaerobic digestion and silage preservation expertise enables circular-economy service bundling for methane-conscious operations.
- EU Carbon Farming Certification:Emerging soil-carbon crediting frameworks for sustainable feed practices create premium pricing authorization for verified low-emission additive protocols.
Industry Challenges
- Microbial Strain Curators:Scarce expertise in anaerobic bacteria phenotyping and cryopreservation is constraining R&D throughput for novel inoculant development.
- Legacy Feed Mixer Integration:Retrofitting automated dosing hardware into existing farm infrastructure requires site-specific engineering and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Silage Additive Market |
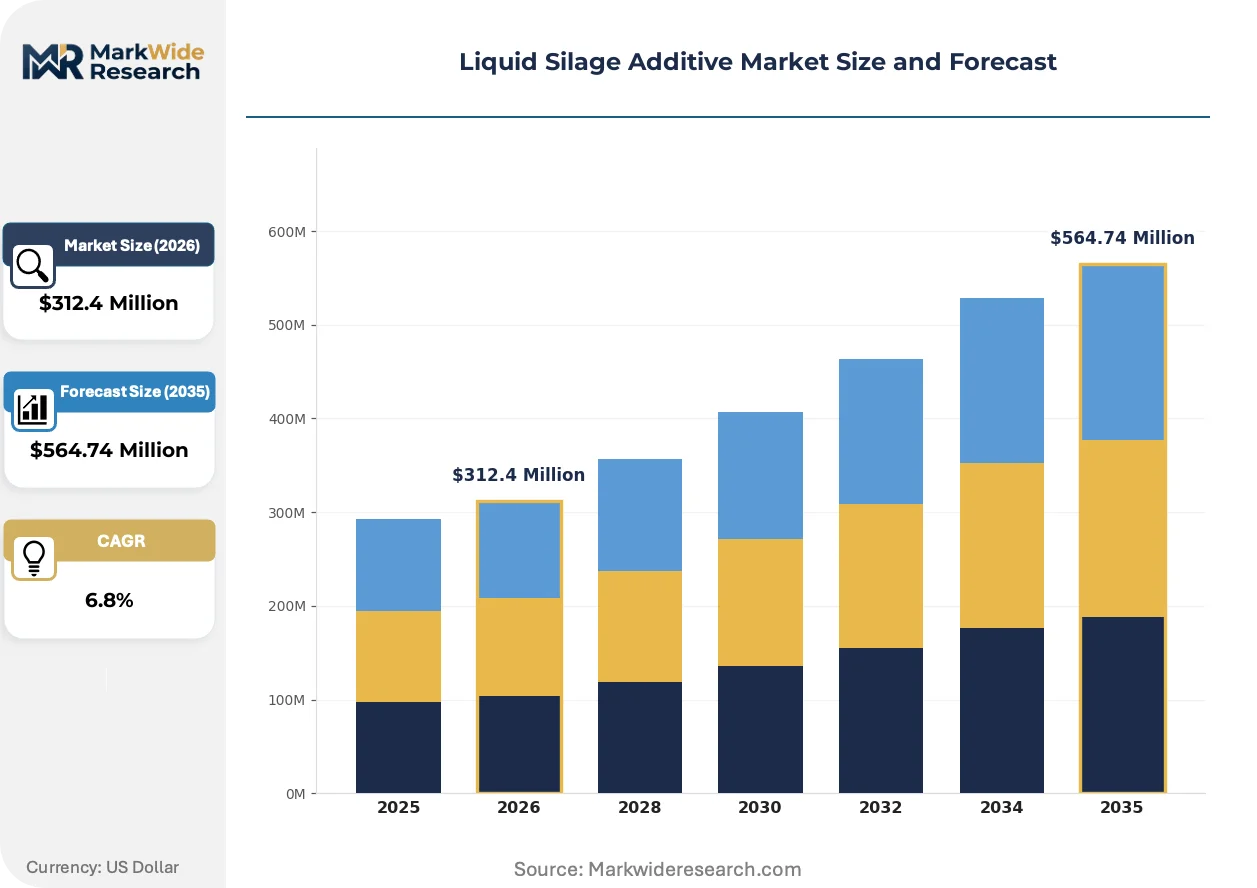
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymatic Additives, Bacterial Additives, Chemical Preservatives, Organic Acids Application: Animal Feed, Dairy Production, Fermentation Processes, Crop Preservation Form: Concentrated Liquid, Ready-to-Use Liquid, Powdered Form, Granular Form End User: Dairy Farms, Livestock Operations, Feed Manufacturers, Agricultural Cooperatives |
| Companies Covered | Chr. Hansen Holding A/S, DSM Firmenich, BASF SE, Corteva Agriscience, Archer Daniels Midland Company, Lallemand Inc., Alltech, Volac International Limited, Kemin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Silage Additive Market Evolving Landscape
Formulation science is pivoting from broad-spectrum chemical preservation toward targeted microbiome modulation, with digital dosing systems and strain-level traceability emerging as the new competitive battlegrounds.
Multi-strain bacterial consortia engineering is miniaturizing the functional complexity previously achieved through chemical additive stacking. Danish research institutes are deploying CRISPR-guided strain optimization to compress development cycles for homofermentative and heterofermentative combinations. Large dairy cooperatives in the Netherlands are piloting these advanced inoculants in 10,000-ton silage pits, with early adopters reporting compressed pH decline curves and reduced aerobic spoilage margins.
REACH Annex XIV authorization timelines for organic acid preservatives are forcing formulation pivots toward exempt biological categories. ECHA's 2024-2026 sunset date cluster for benzoic acid derivatives is accelerating R&D redirection into bacterial and enzymatic alternatives. German feed compounders are pre-registering enzyme-based preservation protocols to secure uninterrupted supply chain continuity ahead of chemical use restrictions.
Precision agriculture contracting is displacing spot-market additive purchases among consolidated dairy operations. Volume-commitment agreements with embedded fermentation performance guarantees are replacing transactional procurement in the Netherlands and northern France. This shift is most visible in Friesland-Campina's supplier qualification program, which mandates real-time dosing telemetry and batch-traceable strain documentation as baseline vendor requirements.
Liquid Silage Additive Market Segmentation
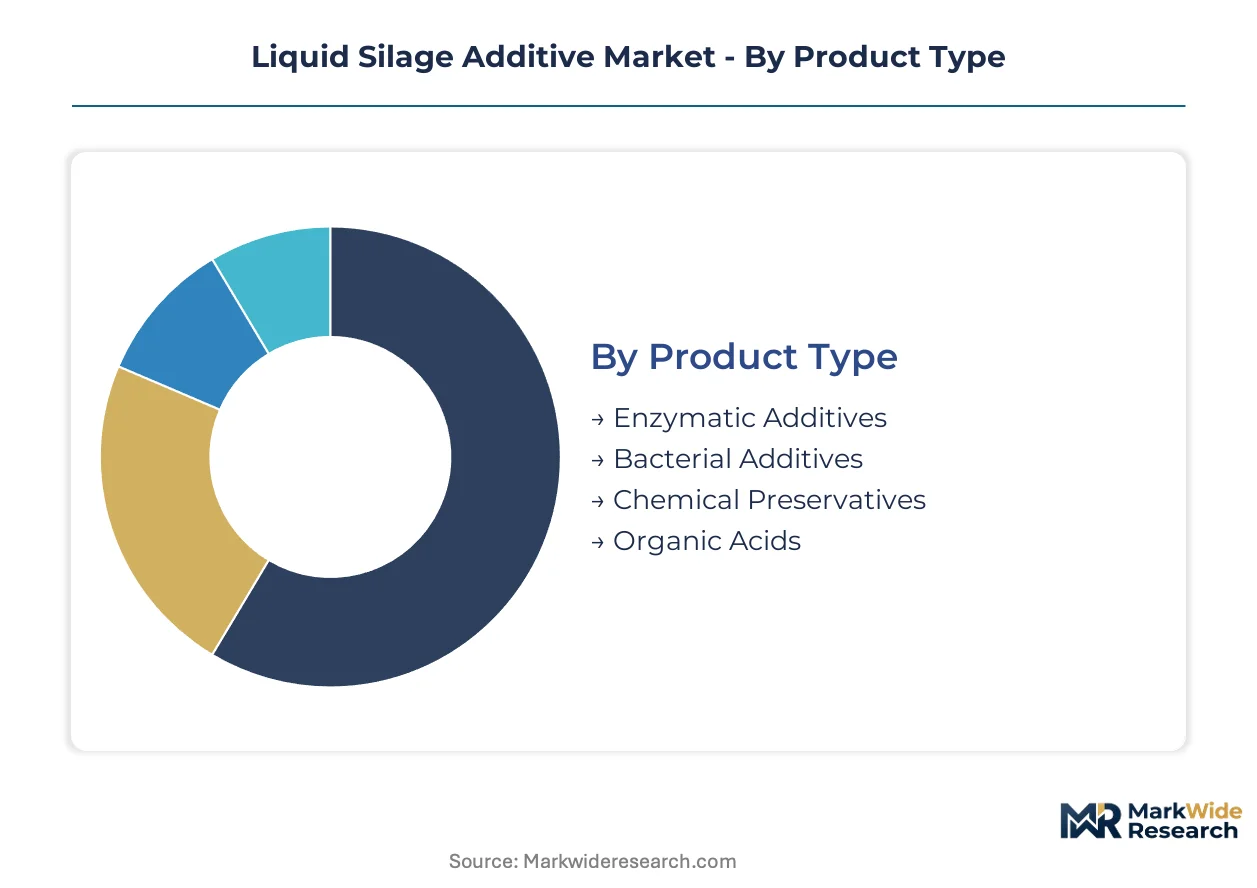
Liquid silage additives serve distinct operational needs across fermentation chemistry, application intensity, and farm-scale infrastructure. Segmentation reveals where formulation investments concentrate and which delivery formats command procurement priority in consolidated dairy operations.
Product Type:
Geographic concentration of demand varies sharply by chemistry: bacterial formulations draw heavily from domestic EU dairy consolidation, while enzymatic additives track export-oriented forage trade corridors.
- Bacterial Additives:Aqueous suspensions of homofermentative and heterofermentative lactic acid bacteria dosed at 10^5–10^6 CFU per gram. German and Dutch mega-farms anchor volume demand as EFSA strain-specific dossiers standardize cross-border supply.
- Enzymatic Additives:Cellulolytic and hemicellulolytic enzyme cocktails targeting fiber digestibility gains. French and Belgian feed compounders drive fastest uptake ahead of REACH chemical sunset dates for organic acid alternatives.
- Chemical Preservatives:Benzoic acid and propionic acid derivatives facing ECHA authorization pressure.
- Organic Acids:Formic and acetic acid blends for rapid pH suppression in wet forage conditions.
Bacterial additives command the established base. The steepest expansion runs through enzymatic formulations.
Application:
Cost tier stratification separates commodity preservation from premium performance guarantees, with fermentation-process applications carrying the highest per-ton additive spend.
- Dairy Production:Precision-dosed bacterial inoculants for high-value milk yield consistency. Netherlands-based cooperatives like Friesland-Campina mandate real-time dosing telemetry and strain traceability, elevating supplier qualification barriers.
- Animal Feed:Broad-spectrum preservation for beef and sheep operations. Polish and Romanian livestock clusters absorb volume formulations with lower per-unit margins but scale-driven procurement.
- Fermentation Processes:Anaerobic digestion co-optimization with biogas operations.
- Crop Preservation:Seasonal grass and legume silage for smallholder cooperatives.
Dairy production anchors premium pricing tiers. Animal feed captures volume scale.
Form:
Supply concentration in concentrated liquid production reflects capital intensity of aseptic fermentation infrastructure, while ready-to-use formats serve fragmented farm segments.
- Concentrated Liquid:High-potency formulations requiring on-farm dilution and automated dosing integration. German equipment manufacturers dominate precision-dispensing hardware pairing, locking in formulation-specification relationships.
- Ready-to-Use Liquid:Pre-diluted solutions for small-to-mid scale operations lacking mixing infrastructure. Eastern EU farm segments in Hungary and Slovakia prefer this format for operational simplicity.
- Powdered Form:Lyophilized bacterial cultures for extended shelf stability.
- Granular Form:Solid carriers for manual application in remote or low-mechanization settings.
Concentrated liquid holds manufacturing scale advantages. Ready-to-use liquid penetrates undermechanized farm segments.
End User:
Customer type determines contract structure: feed manufacturers negotiate multi-year supply agreements, while agricultural cooperatives aggregate spot purchasing into seasonal tenders.
- Feed Manufacturers:Integrated compounders blending silage additives into total mixed rations. DSM Firmenich and BASF SE serve this channel through dedicated technical service teams and formulation co-development.
- Dairy Farms:Direct procurement by consolidated operations with in-house nutritionists. Dutch and Danish farms above 500-head capacity specify strain-level documentation and fermentation performance guarantees.
- Livestock Operations:Beef and sheep specialists with seasonal preservation needs.
- Agricultural Cooperatives:Member-owned purchasing bodies aggregating smallholder demand.
Feed manufacturers lock in supply security through vertical partnerships. Dairy farms drive specification intensity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in liquid silage additives tilt toward intra-EU trade, with Denmark and the Netherlands running persistent surpluses in bacterial strain exports while Germany and France absorb concentrated liquid formulations through cross-border supply chains.
Germany
Dairy farm consolidation in Lower Saxony and Bavaria drives precision-dosing system adoption. EFSA strain-specific dossier requirements filter supplier access, advantaging domestic compounders with regulatory compliance infrastructure. The Münsterland dairy cluster now mandates real-time dosing telemetry as a procurement baseline.
Netherlands
Friesland-Campina's supplier qualification program reshapes procurement toward volume-commitment contracts with fermentation guarantees. EU Green Deal methane targets compress formulation windows for cooperatives above 500-head capacity. Wageningen University research institutes anchor CRISPR-guided strain optimization partnerships.
France
Feed compounders in Brittany and Normandy pivot fastest toward enzymatic alternatives as ECHA REACH sunset dates approach for benzoic acid derivatives. The Grand Ouest dairy basin absorbs pre-registered enzyme protocols to secure supply continuity. ANSM monitoring of feed additive safety elevates documentation burdens for cross-border suppliers.
Poland
Underpenetrated large-farm segments in Masovian and Greater Poland voivodeships attract first-mover positioning for automated dosing systems. National sustainability certifications diverge from EU harmonized standards, fragmenting market access for unprepared suppliers. Poznań-based agricultural cooperatives aggregate spot purchasing into seasonal tenders with growing scale.
Denmark
Strain banking and master cell culture production concentrate in Copenhagen-region biotech corridors, creating supply chokepoints for EU inoculant formulators. Chr. Hansen's microbial library anchors high-performance bacterial additive exports across member states. Danish dairy operations below 200-head capacity still prefer ready-to-use liquid formats over concentrated alternatives.
Liquid Silage Additive Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities and strain documentation depth. Market structure tilts toward oligopoly in bacterial inoculants while enzymatic additives sustain more fragmented entry. Three archetypes dominate: integrated enzyme manufacturers, microbial strain curators, and chemical preservative incumbents pivoting toward biological alternatives. Competitive moves concentrate on backward integration into strain banking and geographic expansion into eastern EU dairy clusters.
Within the microbial strain curator tier, Chr. Hansen Holding A/S and Lallemand Inc. exemplify the R&D-intensive positioning that EFSA dossier requirements now filter for. DSM Firmenich occupies a distinct position bridging enzyme manufacturing with integrated technical service capabilities. Among chemical-origin diversifiers, BASF SE represents the scale-driven pivot toward exempt biological categories as REACH restrictions tighten. These three anchors illustrate how regulatory pressure is compressing the viable competitive set around strain-level documentation and precision-dosing compatibility.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| DSM Firmenich |
| BASF SE |
| Corteva Agriscience |
| Archer Daniels Midland Company |
| Lallemand Inc. |
| Alltech |
| Volac International Limited |
| Kemin Industries |
| Others |
Value Network & Pricing Analysis
Aseptic fermentation capacity utilization above 85% in Danish and Dutch biotech corridors compresses marginal cost curves for bacterial inoculant formulators while elevating price floors for enzymatic alternatives. This scale concentration grants Chr. Hansen and DSM Firmenich pricing power in premium bacterial tiers, whereas smaller compounders absorb margin pressure through ready-to-use liquid formats.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the liquid silage additive market. Premium tiers command certification-grade bacterial formulations with EFSA strain-specific dossiers and embedded fermentation guarantees, while economy tiers serve Polish and Romanian livestock clusters through volume-scaled procurement. Cost compression in enzymatic categories is intensifying because REACH chemical sunset dates accelerate R&D redirection into biological alternatives. Feed manufacturers exhibit lowest price sensitivity due to multi-year supply agreements, whereas agricultural cooperatives aggregating smallholder demand drive hardest bargaining on per-unit costs.
Supply Chain Analysis
Strait of Hormuz transit underwrites organic acid feedstock flows for chemical preservative formulators, though biological additive supply chains bypass this chokepoint entirely. Master cell culture production clusters in Denmark, the Netherlands, and Germany anchor bacterial inoculant supply, drawing from pharmaceutical-grade fermentation infrastructure and cryopreserved strain banks. Raw material dependencies center on glucose feedstocks for bacterial propagation, cellulase enzyme precursors from Trichoderma fermentation, and specialized stabilizer chemistries for aqueous formulations. Single-source vulnerability concentrates in Copenhagen-region strain banking facilities. Distribution runs through integrated feed compounder channels in Germany and France, with direct-to-farm precision-dosing systems gaining share in Dutch mega-farm segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal methane-reduction mandates are compressing formulation windows and elevating regulatory compliance barriers, creating a high-growth disruption opportunity for biological additive suppliers with strain-level documentation capabilities.
For Market Incumbents: Compound defensive positioning through backward integration into cryopreserved strain banking and automated dosing hardware partnerships. Capacity addition in Polish dairy clusters secures first-mover positioning as eastern EU farm consolidation accelerates. EFSA dossier standardization threatens smaller formulators lacking regulatory infrastructure—invest in compliance capabilities to filter competitive access. For New Entrants and Emerging Players: Lead with enzymatic formulation specialization targeting French and Belgian feed compounders ahead of REACH chemical sunset dates. Underpenetrated large-farm segments in Masovian and Greater Poland voivodeships offer the most penetrable geography for precision-dosing liquid systems. A go-to-market angle bundling biogas digestate integration services with silage preservation captures circular-economy procurement preferences. For Investors and Strategic Acquirers: Microbial strain curators with CRISPR-guided optimization partnerships and established EFSA dossier track records represent the highest-conviction acquisition archetype. Long-term viability hinges on regulatory compliance moats deepening over the projection horizon. Watch for divergence between EU harmonized standards and emerging national sustainability certifications as the critical inflection signal for market access fragmentation risk.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Banking Backward Integration | Copenhagen-region biotech corridors anchor captive supply of master cell cultures for EU inoculant formulators. |
| EFSA Dossier Pre-Registration | German feed compounders secure uninterrupted bacterial additive supply ahead of harmonized safety documentation mandates. |
| Precision-Dosing Hardware Partnership | Dutch equipment manufacturers lock in formulation-specification relationships with Friesland-Campina supplier programs. |
| Enzymatic Protocol Pre-Registration | French compounders pivot from benzoic acid derivatives to cellulolytic alternatives before ECHA sunset dates. |
| Biogas Digestate Service Bundling | Danish research institutes enable circular-economy positioning for methane-conscious dairy operations. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with bacterial strain curators, feed compounder procurement leads, dairy farm nutritionists, and EFSA regulatory affairs specialists; and secondary validation through EMA feed additive submission databases, ECHA REACH authorization timelines, EU customs trade data, and SEC filings from listed enzyme manufacturers. Bottom-up triangulation across farm-scale adoption patterns and top-down reconciliation with compounder procurement volumes anchored volume estimates.
Across the analysis window, the forecasting framework modeled segmentation dimensions including fermentation chemistry type, application intensity tier, farm-scale infrastructure category, and regional regulatory cluster alignment. CAGRs derived from curve-fitting historical adoption trajectories against EFSA dossier implementation phases and REACH chemical restriction timelines. Industry-specific inputs incorporated cellulolytic enzyme efficacy trial data and automated dosing system penetration rates in consolidated dairy operations.
Underlying assumptions cover EFSA strain-specific dossier harmonization progress, EU Green Deal methane target enforcement intensity, and REACH Annex XIV authorization adherence, with deviation risk concentrated in regulatory divergence between member state sustainability certifications. Practitioners should keep alternative scenarios live as national low-emission feed protocols and carbon farming certification frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Anti-Foaming Agent Market
Additives
Thallium Acetate Market
Additives
Glyceryl Caprylate Market
Additives
Magnesium Stearate Market
Additives
Cold Flow Improvers Market
Additives
Oxygen Scavengers Market
Additives
Glycyrrhizic Acid Glycosides Market
Additives
Viscosity Reducing Agents Market
Additives
Global Low-Profile Additive Market
Additives
Hydroxypropyl Distarch Phosphate Market
Additives
Glycol Acetate Market
Additives
FD and C Lakes Market
Additives
Sodium Potassium Tartrate Market
Additives
Gasoline Additives Market
Additives
Global PVC Additives Market
Additives
Refining Additives Market