
 Caustic Sulphite Caramel Market | 2026-2036
Caustic Sulphite Caramel Market Size, Share, and Industry Trends Forecast 2026-2036
Caustic Sulphite Caramel Market Analytics
Ingredient customization revenue is fragmenting across liquid, powder, and paste format specialists. Sethness Caramel Color anchors North American supply through backward integration into burnt sugar feedstock refining. Sensient Technologies Corporation competes on pharmaceutical-grade certification, while Nigay SAS dominates European liquid caramel logistics through dedicated tanker fleet operations.
Caustic sulphite caramel denotes a Class IV caramel color produced via ammonium sulphite-assisted heat treatment of carbohydrates, yielding a negatively charged colloidal dispersion with isoelectric points below pH 1.5, primarily employed for stable brown coloration in acidic beverage matrices. The liquid format leads volume due to bulk soft-drink dosing infrastructure, though powder grades capture margin pools in artisanal bakery premix channels where shelf stability and precise batch scaling matter. Food-grade specifications sustain the widest addressable base, while pharmaceutical-grade thresholds concentrate value among CDMO-qualified suppliers serving oral dosage form contracts.
EFSA maintains maximum permissible daily intake thresholds for Class IV caramel colors through its ANS Panel, directly constraining formulation ceilings in EU-labeled products. The FDA's Title 21 CFR 73.85 listing permits caustic sulphite caramel in foods, drugs, and cosmetics, though California Proposition 65 litigation risk around 4-MeI contaminants elevates supplier liability screening. Stakeholders must monitor evolving clean-label retailer specifications that may displace synthetic color classes before regulatory mandates formalize.
Market Dynamics
EFSA's ANS Panel re-evaluation of Class IV caramel safety thresholds is compressing formulation ceilings across EU beverage manufacturing, forcing compounders to re-qualify suppliers against tightening 4-MeI contaminant specifications.
Growth Catalysts
- Cola concentrate standardization:Beverage manufacturers in Germany are consolidating caramel procurement through centralized specification hubs serving pan-European bottling networks.
- FDA Title 21 CFR 73.85:The FDA's broad food-drug-cosmetic listing permits caustic sulphite caramel deployment across acidic matrices without category-specific pre-approval.
- Dark beer coloration demand:European craft brewing revival is pulling liquid caramel volumes through dedicated tanker logistics serving regional malt houses.
Market Restraints
- Burnt sugar feedstock volatility:Backward-integrated suppliers face margin pressure from sucrose price swings tied to Brazilian harvest cycles.
- California Proposition 65 liability:4-MeI litigation exposure elevates supplier screening costs for brands distributing in the US West Coast.
- Clean-label displacement threat:Retailer-driven natural color specifications are preemptively excluding synthetic caramel classes from premium private-label formulations.
Strategic Opportunities
- Pharmaceutical-grade certification:CDMO-qualified suppliers can capture oral dosage form contracts requiring isoelectric point stability below pH 1.5.
- Powder format artisanal channels:Bakery premix manufacturers in France seek shelf-stable grades enabling precise batch scaling without liquid dosing infrastructure.
- EU Green Deal alignment:Caramel producers with renewable energy-process heat integration qualify for preferential supplier status under Scope 3 reduction mandates.
Industry Challenges
- EFSA compliance timeline compression:Accelerated safety re-evaluation schedules strain toxicology documentation resources at mid-tier caramel houses.
- Tanker fleet utilization optimization:Liquid caramel logistics require dedicated stainless-steel transport assets with temperature-controlled discharge systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caustic Sulphite Caramel Market |
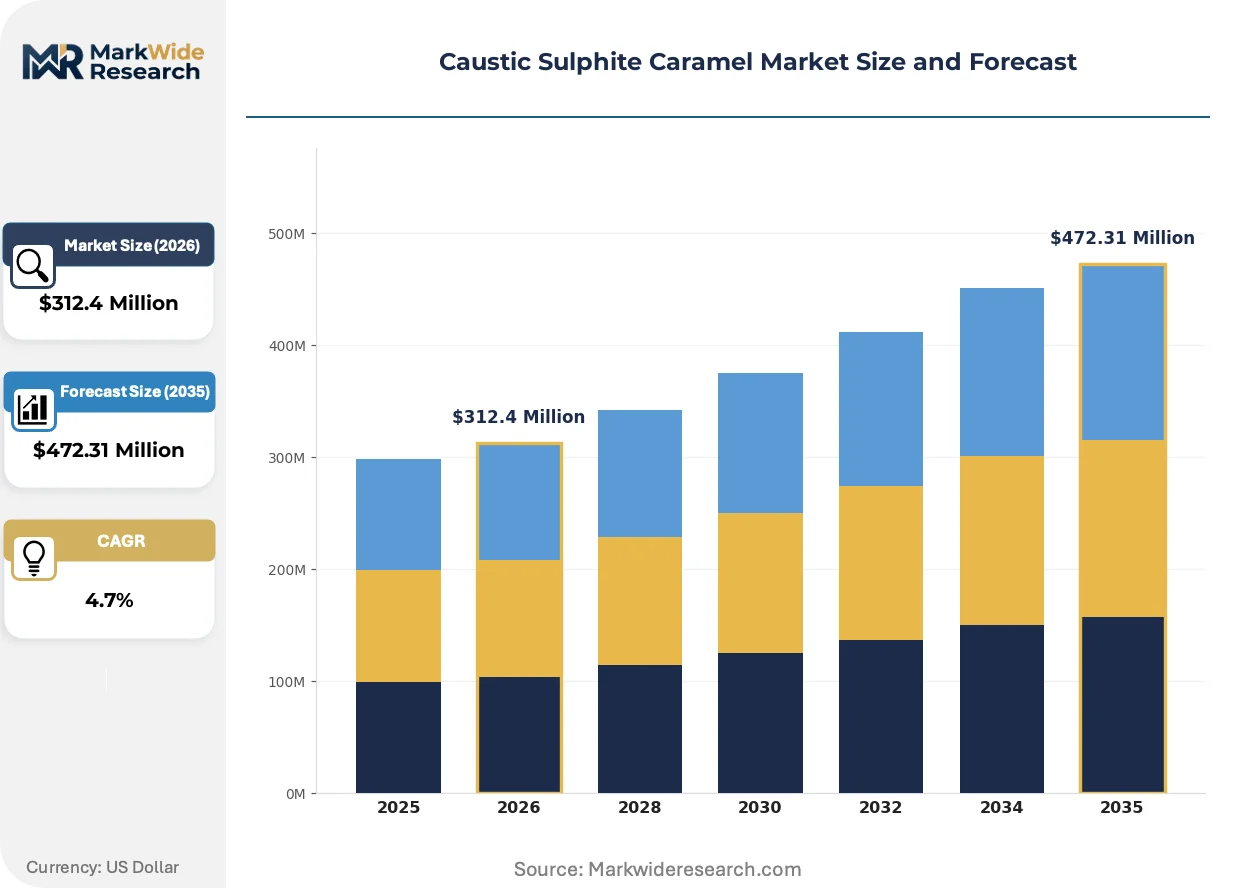
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Paste End Use Industry: Food & Beverage, Bakery, Confectionery, Dairy Packaging Type: Bags, Drums, Tankers, Bottles Grade: Food Grade, Industrial Grade, Pharmaceutical Grade, Technical Grade |
| Companies Covered | Sethness Caramel Color, Mascot Food Colors, Sensient Technologies Corporation, D.D. Williamson & Co., Inc., Aarkay Food Products Ltd., Bakels Worldwide, Goteborgsfood Budapest Ltd., Metarom A.s., Nigay SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caustic Sulphite Caramel Market Evolving Landscape
Process analytical technology is digitizing caramel manufacturing workflows, enabling real-time color consistency monitoring that reduces batch-to-batch variation and accelerates customer qualification cycles.
Spectroscopic in-line monitoring is digitizing quality control across European liquid caramel production facilities. Major beverage compounders in Germany now mandate digital batch records for supplier audit readiness. The technology compresses release timelines from days to hours while building contaminant traceability databases for regulatory defense.
EFSA's ANS Panel maintains maximum permissible daily intake thresholds for Class IV caramel colors through rolling safety re-evaluations. The framework constrains formulation ceilings in EU-labeled soft drinks and alcoholic beverages. German beverage manufacturers are responding by diversifying supplier bases across multiple caramel classes to distribute regulatory risk.
Buyer concentration among multinational beverage compounders is consolidating procurement decisions into centralized technical specification teams. Regional caramel houses now face direct negotiation with global category managers rather than distributed plant-level purchasing. This pattern concentrates most visibly in North American cola manufacturing where three compounders control majority volume allocation.
Caustic Sulphite Caramel Market Segmentation
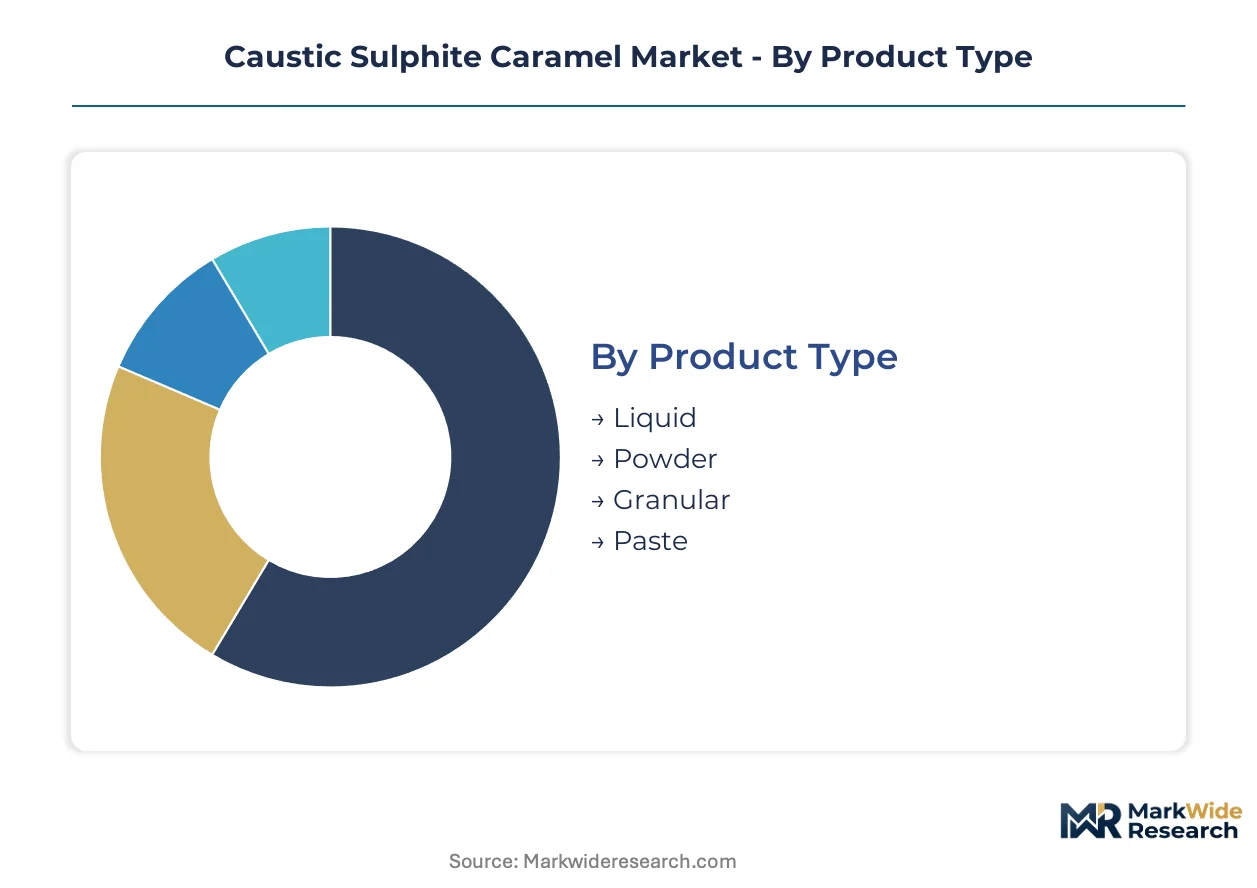
Caustic sulphite caramel procurement cycles vary dramatically across format, application, and specification tiers. Understanding these velocity differentials helps suppliers align inventory models with customer qualification timelines and regulatory documentation burdens.
Product Type:
Liquid formats turn inventory fastest through continuous soft-drink dosing lines, while powder and paste grades sit longer in artisanal channels requiring smaller batch runs.
- Liquid:Dominates bulk beverage manufacturing with negatively charged colloidal dispersions optimized for acidic matrices. German bottling networks drive demand through dedicated tanker logistics serving pan-European compounders. EFSA's tightening 4-MeI thresholds compress release timelines and accelerate batch turnover.
- Powder:Shelf-stable grades enable precise batch scaling in bakery premix channels lacking liquid dosing infrastructure. French artisanal manufacturers favor this format for color consistency across small production runs. California Proposition 65 liability screening extends customer qualification cycles.
- Granular:Intermediate flow properties suit intermediate-scale confectionery operations seeking controlled dissolution rates.
- Paste:High-viscosity grades serve niche dairy applications requiring minimal moisture addition.
Liquid anchors the volume base while powder gains share at the steepest rate.
End Use Industry:
Cost tier stratification separates high-volume beverage contracts from premium artisanal channels where specification tolerance tightens and pricing power concentrates.
- Food & Beverage:Cola concentrate standardization and dark beer coloration pull the majority of Class IV caramel volume. North American bottlers consolidate procurement through centralized technical specification teams. FDA Title 21 CFR 73.85 listing permits broad deployment without category-specific pre-approval.
- Bakery:Artisanal premix manufacturers in France demand powder grades with extended shelf stability for precise color matching across regional product lines. Clean-label retailer specifications are preemptively excluding synthetic caramel classes from premium private-label formulations.
- Confectionery:Mid-tier margin pool where color intensity requirements compete with cost pressure from private-label contract manufacturing.
- Dairy:Niche volume channel with specialized paste format requirements for moisture-sensitive applications.
Food & Beverage commands the revenue base while Bakery climbs the fastest amid clean-label displacement risks elsewhere.
Packaging Type:
Supply concentration shapes logistics economics, with dedicated tanker fleets requiring high utilization thresholds to justify capital deployment against bag and drum alternatives.
- Tankers:Stainless-steel dedicated fleets with temperature-controlled discharge systems serve high-volume liquid caramel contracts. Nigay SAS dominates European logistics through captive transport assets. Fleet utilization optimization strains mid-tier caramel houses lacking scale.
- Drums:Intermediate bulk format bridging tanker-scale and bag-scale procurement for regional beverage compounders.
- Bags:Powder and granular grades move through standard palletized freight with lower capital intensity.
- Bottles:Laboratory and pilot-scale sampling format for customer qualification and R&D color matching.
Tankers capture the margin pool while bags sustain the widest addressable customer base.
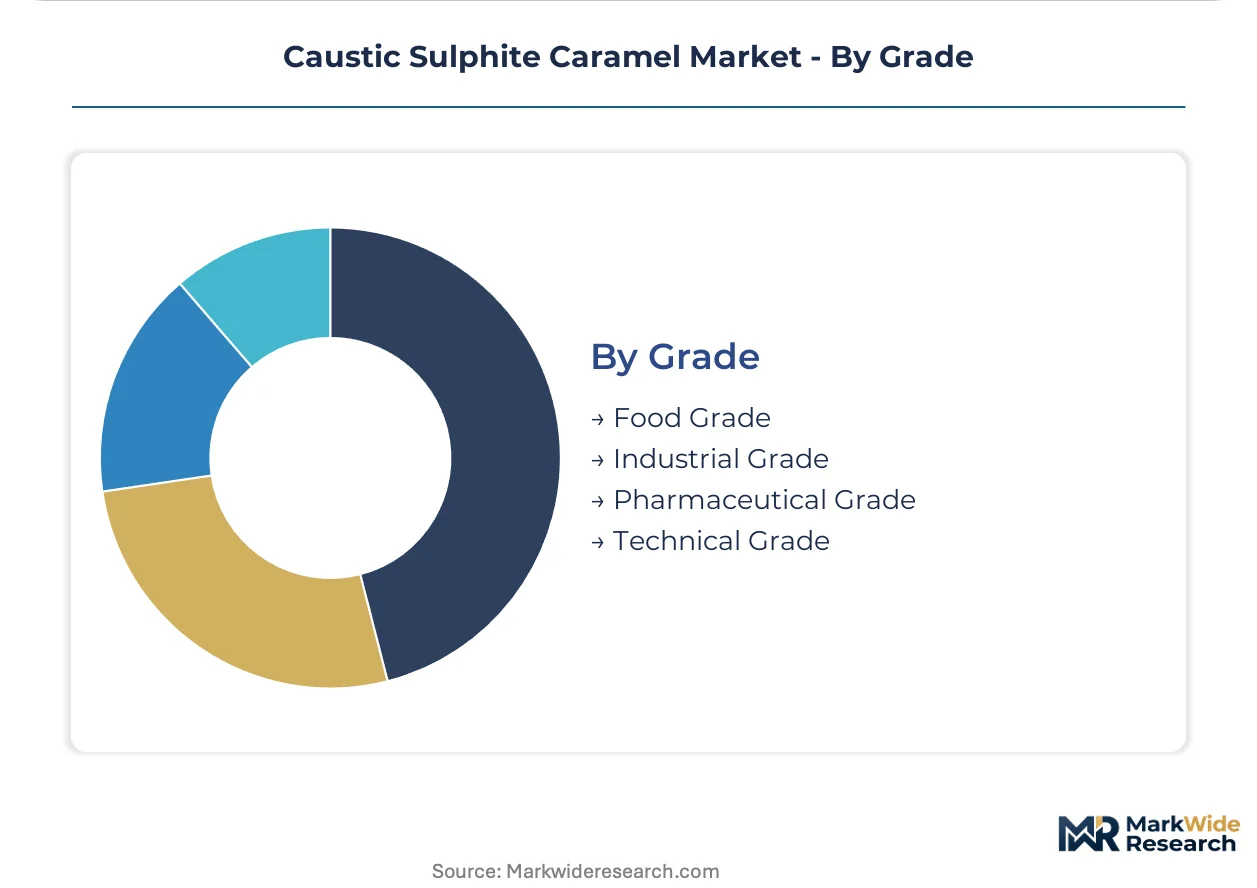
Grade:
Certification tier creates pricing stratification across food, pharmaceutical, and industrial applications, with documentation burden escalating toward CDMO-qualified thresholds.
- Food Grade:Widest addressable base with EFSA ANS Panel maximum permissible daily intake thresholds constraining formulation ceilings. German beverage manufacturers diversify supplier bases across multiple caramel classes to distribute regulatory risk.
- Pharmaceutical Grade:CDMO-qualified suppliers capture oral dosage form contracts requiring isoelectric point stability below pH 1.5. Sensient Technologies Corporation competes on certification depth. Toxicology documentation resources strain mid-tier houses facing accelerated EFSA compliance timelines.
- Industrial Grade:Lower-specification applications with minimal regulatory documentation burden.
- Technical Grade:Non-food applications where color consistency requirements relax.
Food Grade sustains the volume foundation while Pharmaceutical Grade expands most quickly through CDMO contract concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes caustic sulphite caramel primarily for beverage coloration, while France and the United States diverge toward bakery and pharmaceutical applications respectively. This consumption-mix differential shapes supplier qualification criteria and logistics infrastructure investments across major markets.
Germany
Cola concentrate standardization and dark beer coloration pull the majority of European Class IV caramel volume through centralized specification hubs. EFSA's ANS Panel maximum permissible daily intake thresholds constrain formulation ceilings for compounders serving pan-European bottling networks. The Rhineland-Palatinate and Bavaria clusters host dedicated tanker logistics serving major beverage compounders.
United States
Pharmaceutical-grade certification demand concentrates value among CDMO-qualified suppliers serving oral dosage form contracts. FDA Title 21 CFR 73.85 permits broad deployment across food, drug, and cosmetic matrices without category-specific pre-approval. New Jersey and Pennsylvania house the primary pharmaceutical manufacturing corridors where isoelectric point stability below pH 1.5 commands premium positioning.
France
Artisanal bakery premix manufacturers favor powder grades enabling precise batch scaling without liquid dosing infrastructure. Clean-label retailer specifications are preemptively excluding synthetic caramel classes from premium private-label formulations. The Île-de-France and Auvergne-Rhône-Alpes regions concentrate artisanal production facilities requiring extended shelf stability specifications.
India
Food-grade specifications sustain the widest addressable base among regional beverage and confectionery manufacturers. FSSAI color additive regulations govern caramel deployment across processed food categories with evolving documentation requirements. Maharashtra and Gujarat host the primary food processing corridors where mid-tier caramel houses compete on batch-to-batch consistency.
Brazil
Industrial-grade applications dominate volume consumption for lower-specification coloration needs in regional beverage manufacturing. ANVISA pharmaceutical regulations create certification tiering for suppliers targeting oral dosage form opportunities. São Paulo state anchors the primary manufacturing concentration where tanker-scale logistics remain underdeveloped relative to North American benchmarks.
Caustic Sulphite Caramel Market Competitive Landscape
Capability concentration sits with pharmaceutical-certified specialists; scale advantage sits with backward-integrated feedstock controllers. The vendor base separates into three functional tiers: tanker-fleet logistics operators, pharmaceutical-grade certifiers, and regional compounder-integrated producers. Two dominant competitive moves define current positioning—supplier base diversification to distribute EFSA regulatory risk, and captive renewable energy integration to qualify for EU Green Deal preferential procurement status.
Within the North American integrated tier, Sethness Caramel Color exemplifies backward integration into burnt sugar feedstock refining. Sensient Technologies Corporation occupies the pharmaceutical-grade certification vector. Nigay SAS represents the European liquid logistics specialist archetype with dedicated tanker fleet operations serving German beverage compounders.
| Leading Market Players |
|---|
| Sethness Caramel Color |
| Mascot Food Colors |
| Sensient Technologies Corporation |
| D.D. Williamson & Co., Inc. |
| Aarkay Food Products Ltd. |
| Bakels Worldwide |
| Goteborgsfood Budapest Ltd. |
| Metarom A.s. |
| Nigay SAS |
| Others |
Value Network & Pricing Analysis
Rhineland-Palatinate's concentrated caramel production clusters feed directly into German beverage compounders' centralized procurement hubs, translating upstream capacity discipline into downstream price-setting leverage for tanker-scale liquid contracts.
Pricing Analysis
Long-term offtake agreements dominate high-volume beverage contracts, locking in stable unit economics across multi-year supply relationships while spot procurement serves artisanal bakery channels with volatile sucrose-indexed adjustments. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade certifications separates CDMO-qualified suppliers commanding premium positioning from commodity processors facing margin compression. Price differentiation hinges on 4-MeI contaminant documentation depth and EFSA compliance certification status. Food-grade buyers exhibit highest price sensitivity due to clean-label displacement threats, while pharmaceutical-grade purchasers prioritize isoelectric point stability over unit cost.
Supply Chain Analysis
Export-control regimes on ammonium sulphite catalyst technologies constrain capacity transfers to emerging production regions, preserving incumbent advantages in established manufacturing corridors. Supply concentrates in Germany, the United States, and France, with Brazilian industrial-grade capacity expanding through ANVISA-aligned certification investments. Raw material flows draw from Brazilian sucrose harvest cycles, Indian maize starch processing, and North American corn syrup refining. Single-source vulnerability runs through dedicated stainless-steel tanker fleets requiring temperature-controlled discharge infrastructure. Distribution runs through captive logistics networks serving pan-European compounders, with drum and bag formats bridging smaller regional accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among three multinational beverage compounders controlling majority North American cola volume allocation, forcing regional caramel houses into direct negotiation with global category managers rather than distributed plant-level purchasing.
For Market Incumbents: Harden EFSA compliance documentation through accelerated toxicology investment ahead of ANS Panel re-evaluation timelines, while securing renewable energy-process heat integration to qualify for EU Green Deal preferential procurement status. Backward integration into burnt sugar feedstock refining defends margin position against Brazilian sucrose price volatility. Pharmaceutical-grade certification depth anchors CDMO contract retention against Sensient Technologies Corporation's competitive pressure. For New Entrants and Emerging Players: India's Maharashtra and Gujarat food processing corridors present underpenetrated white-space for food-grade powder formats serving mid-tier confectionery manufacturers lacking liquid dosing infrastructure. French artisanal bakery premix channels offer secondary entry through shelf-stable grades enabling precise batch scaling. Target CDMO qualification partnerships as the go-to-market angle for pharmaceutical-grade positioning. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-qualification moat play because EFSA's tightening 4-MeI thresholds and accelerated safety re-evaluation schedules strain toxicology resources at mid-tier caramel houses, creating consolidation pressure among sub-scale operators. Acquisition targets should display captive renewable energy assets and pharmaceutical-grade certification depth. Monitor California Proposition 65 litigation volume as the inflection signal for US West Coast supplier liability escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Refining | Sethness Caramel Color anchors North American supply through captive burnt sugar processing. |
| Pharmaceutical-Grade Certification Investment | CDMO-qualified suppliers capture oral dosage form contracts requiring isoelectric point stability. |
| Renewable Energy-Process Heat Integration | EU Green Deal alignment qualifies producers for preferential supplier status under Scope 3 mandates. |
| Dedicated Tanker Fleet Expansion | Nigay SAS dominates European liquid caramel logistics through captive stainless-steel transport assets. |
| Process Analytical Technology Deployment | Real-time spectroscopic monitoring compresses batch release timelines from days to hours. |
Research Methodology
Desk research of EFSA ANS Panel safety evaluations, FDA Title 21 CFR 73.85 regulatory filings, and FSSAI color additive guidelines preceded structured interviews with caramel plant managers, beverage compounder procurement leads, pharmaceutical CDMO technical directors, and bakery premix manufacturer R&D heads. Secondary validation drew from customs/trade data, SEC 10-K disclosures by listed ingredient suppliers, and European liquid logistics operator fleet registries. Bottom-up volume modeling across format, grade, and end-use segments triangulated against top-down market sizing from regional production cluster analysis.
Assumptions held EFSA maximum permissible daily intake thresholds and FDA listing status constant across the projection horizon, while varying clean-label retailer specification adoption rates and Brazilian sucrose harvest yield scenarios. Segmentation dimensions modeled included product format, certification grade, end-use industry, and packaging type. CAGRs derived from weighted average of historical volume trajectories and forward-looking procurement intent signals from centralized specification hubs. Industry-specific inputs incorporated pharmaceutical oral dosage form pipeline growth and craft brewing revival intensity.
Practitioners should monitor EFSA ANS Panel re-evaluation schedules and California Proposition 65 litigation trends for early signals of regulatory constraint tightening. Forecasts reflect these documented assumptions. Material shifts in clean-label retailer mandate formalization or ammonium sulphite catalyst export-control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Cosmetic Grade Color Additives Market
Additives
United Kingdom Sodium Reduction Ingredient Market
Additives
Fluid Loss Additives Market
Additives
Additives for Floor Coatings Market
Additives
Lubricant Additives Market
Additives
Refinery Process Additives Market
Additives
Sodium Potassium Tartrate Market
Additives
China Feed Additives Market
Additives
Sodium Citrate Dihydrate Market
Additives
Organic Dispersants Market
Additives
Global Rheology Modifiers Market
Additives
Additives for Metalworking Fluids Market
Additives
Ballast Tank Corrosion Inhibitors Market
Additives
Calcium Diglutamate Market
Additives
Silage Additives Market
Additives
Global Sodium Acetate Trihydrate Market