
 Power Sector North America Gas Turbine MRO Market | 2026-2036
Power Sector North America Gas Turbine MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Power Sector North America Gas Turbine MRO Market Insights
North American OEM service networks is broadening maintenance capacity across the United States and Canada to capture aging fleet overhaul cycles. General Electric Company leverages its distributed repair network to anchor long-term utility contracts across the Midwest and Southeast. Siemens Energy AG sustains technology leadership through advanced hot gas path refurbishment capabilities. Mitsubishi Heavy Industries Ltd competes on large-frame gas turbine expertise for combined-cycle installations.
Power Sector North America Gas Turbine MRO encompasses inspection, component refurbishment, and life-extension services for heavy-duty and aeroderivative gas turbines operating above 1,000 degrees Fahrenheit firing temperatures, performed to restore thermal efficiency and emissions compliance. The primary purpose is to extend operational life, reduce heat rate degradation, and maintain grid reliability for baseload and peaking power assets. Maintenance and overhaul services command the largest revenue share due to scheduled inspection intervals driven by fired hours and start-stop cycles. Long-term contracts dominate the contract type landscape as utilities seek predictable lifecycle cost management and guaranteed parts availability.
EPA emissions standards under the Clean Air Act, FERC reliability mandates, and NERC CIP cybersecurity frameworks collectively shape maintenance scope, inspection frequency, and documentation requirements for North American gas turbine operators. Compliance with these regulations directly determines overhaul scheduling, parts traceability protocols, and service provider qualification criteria. Stakeholders must monitor evolving carbon intensity rules and hydrogen co-firing compatibility standards as these will redefine component material specifications and MRO technical scopes.
Market Dynamics
Aging gas turbine fleets across the United States and Canada are compressing overhaul cycles as firing-hour accumulation triggers mandatory hot gas path inspections under EPA emissions compliance frameworks.
Growth Catalysts
- FERC Grid Reliability Mandates:Independent system operators in Texas and the Southeast now require documented turbine availability guarantees, extending contractual MRO coverage periods.
- Hydrogen Co-firing Pilots:Combustion system retrofits for hydrogen blending at combined-cycle plants in Louisiana and California are creating specialized refurbishment demand.
- Gulf Coast Baseload Clustering:Concentrated gas-fired capacity along the Texas-Louisiana corridor generates economies of scale for mobile repair unit deployment.
Market Restraints
- Superalloy Supply Concentration:Single-source dependency on vacuum induction melting capacity in Pennsylvania and Ohio creates input cost volatility for turbine blade casting.
- EPA New Source Review Triggering:Major component replacements risk reclassification as modified sources, imposing additional emissions control retrofits.
- Technical Labor Scarcity:Certified Level III non-destructive testing technicians for phased-array ultrasonic inspection command premium wages exceeding Midwest manufacturing medians.
Strategic Opportunities
- Canadian Cogeneration Expansion:Alberta oil sands thermal facilities and Ontario district heating systems present underpenetrated overhaul demand outside US utility structures.
- Digital Twin Integration:Convergence of physics-based degradation modeling with operational data analytics enables predictive maintenance subscription models.
- Inflation Reduction Act Credits:Clean electricity production incentives for efficient gas plants are accelerating turbine efficiency upgrade commitments.
Industry Challenges
- NERC CIP Cybersecurity Certification:Maintenance documentation systems require segmented network architecture compliance, extending IT integration timelines.
- Legacy Control System Interfacing:1990s-era Mark V and Mark VI turbine control platforms demand specialized protocol translation for modern diagnostic equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Sector North America Gas Turbine MRO Market |
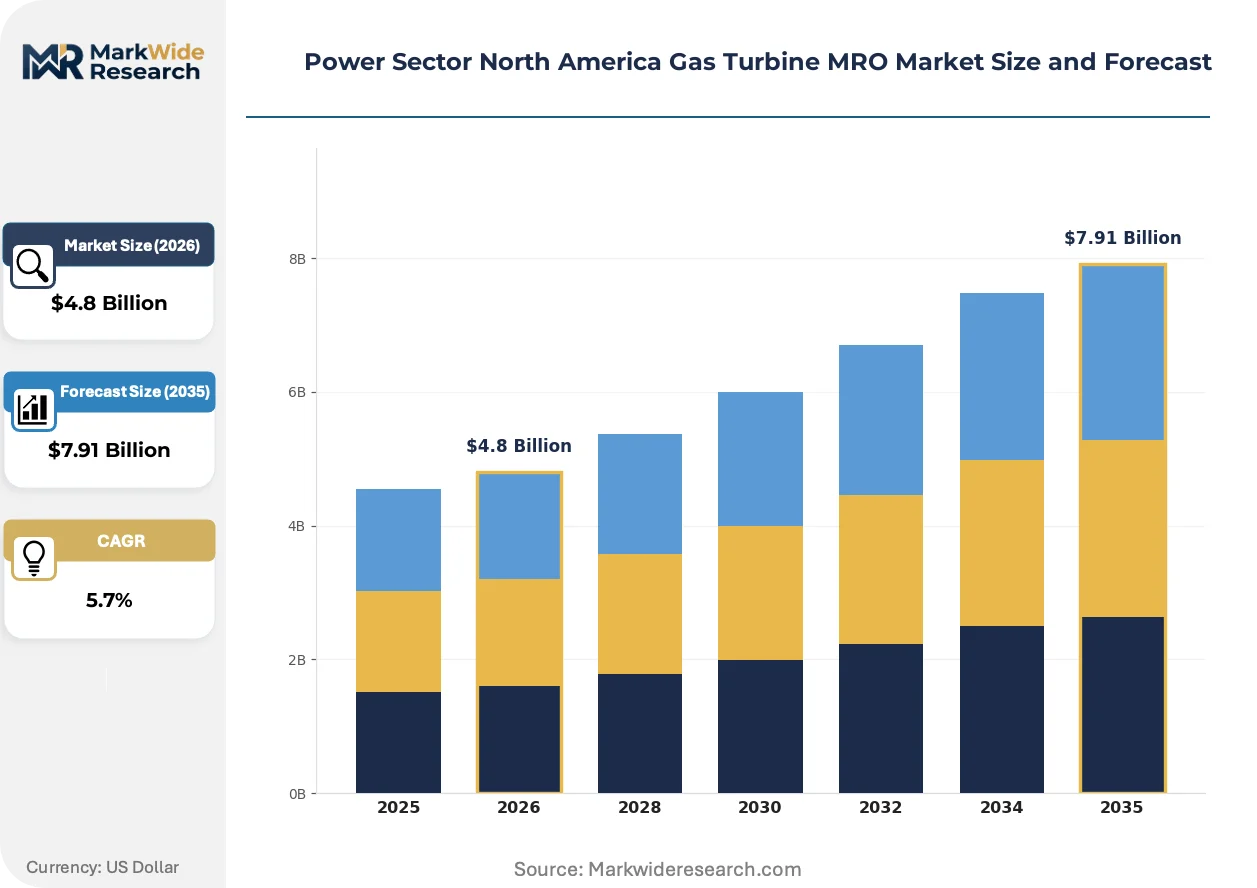
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Repair, Overhaul, Parts Replacement Technology: Combustion, Steam, Hybrid, Fuel Cell End User: Utilities, Industrial Facilities, Power Producers, OEMs Contract Type: Long-Term, Short-Term, Project-Based, Spot Contracts |
| Companies Covered | General Electric Company, Siemens Energy AG, Mitsubishi Heavy Industries Ltd, Fluor Corporation, Power Services Group, Bechtel Corporation, Solar Turbines, Sulzer AG, Mechanical Dynamics & Analysis LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Sector North America Gas Turbine MRO Market Trends and Innovations
Additive manufacturing of nickel-based superalloy turbine components is compressing lead times for blade restoration. Regulatory pressure on NOx emissions is accelerating combustion hardware refresh rates. Buyer consolidation among independent power producers is reshaping contract negotiation leverage.
Cold spray deposition technology is absorbing repair volume previously routed to conventional welding and brazing processes. Midwest utility operators are adopting this solid-state deposition method for compressor blade leading edge restoration. The technology is absorbing market share from traditional weld repair shops by eliminating heat-affected zone cracking risks.
EPA's proposed Good Neighbor Plan ozone transport rule is tightening NOx emission budgets for cross-state power generation. Gas turbine operators in the Ohio River Valley and Mid-Atlantic must now schedule more frequent combustion system inspections. Combined-cycle plants in these regions are responding by pre-purchasing low-NOx burner hardware ahead of enforcement dates.
Long-term service agreements are displacing transactional overhaul procurement among merchant power generators. Texas and PJM market participants now favor fifteen-year fixed-price contracts with guaranteed parts availability. This preference shift is most visible among private equity-backed independent power producers seeking predictable EBITDA profiles.
Power Sector North America Gas Turbine MRO Market Segmentation
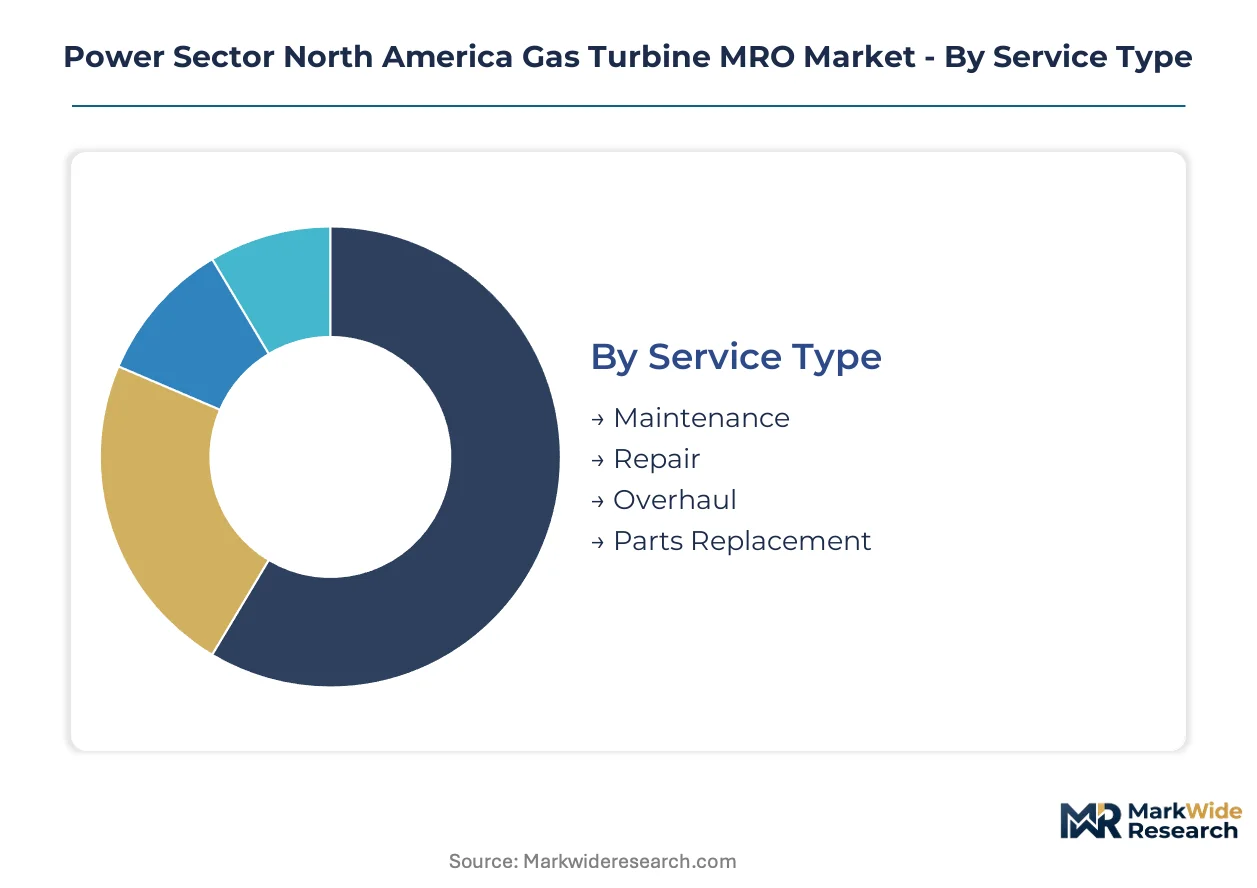
Segmentation in the North American gas turbine MRO market reveals how regulatory compliance burdens, operational intensity, and contract economics fragment service demand across distinct buyer profiles and technical requirements. Understanding these divisions clarifies where EPA emissions enforcement and FERC reliability mandates concentrate procurement leverage.
Service Type:
EPA emissions certification requirements and NERC CIP documentation protocols apply differentially across service categories, with overhaul and parts replacement triggering more stringent traceability obligations than routine maintenance.
- Maintenance:Scheduled inspection intervals driven by fired hours and start-stop cycles dominate procurement volume. Texas and Gulf Coast utilities bundle these services into long-term agreements to satisfy FERC availability guarantees while managing lifecycle costs.
- Repair:Component restoration using cold spray deposition and additive manufacturing is absorbing volume from conventional welding. Midwest operators favor solid-state repair methods to eliminate heat-affected zone cracking in compressor blade leading edge restoration.
- Overhaul:Hot gas path refurbishment requires Level III non-destructive testing certification and EPA emissions compliance documentation.
- Parts Replacement:Superalloy blade casting faces supply concentration risk from Pennsylvania and Ohio vacuum induction melting capacity.
Leading the category by volume: Maintenance. Growing fastest: Repair.
Technology:
Cost tier differentiation separates mature combustion systems from emerging hybrid configurations, with capital intensity and refurbishment frequency determining contract pricing structures.
- Combustion:Heavy-duty and aeroderivative gas turbines operating above 1,000 degrees Fahrenheit firing temperatures require periodic hot gas path inspection. Ohio River Valley plants are pre-purchasing low-NOx burner hardware ahead of EPA Good Neighbor Plan enforcement.
- Steam:Combined-cycle steam turbine sections demand coordinated overhaul scheduling with gas turbine modules.
- Hybrid:Hydrogen co-firing pilots in Louisiana and California are creating specialized combustion system retrofit demand.
- Fuel Cell:Emerging integration with gas turbine bottoming cycles remains nascent in North American utility applications.
Dominating procurement spend: Combustion. Expanding most quickly: Hybrid.
End User:
Customer type determines contract duration preferences and technical specification authority, with independent power producers reshaping negotiation leverage through portfolio consolidation.
- Utilities:Investor-owned utilities in the Midwest and Southeast anchor fifteen-year fixed-price contracts with guaranteed parts availability. General Electric's distributed repair network captures these relationships through long-term service agreements.
- Industrial Facilities:Cogeneration operators in Alberta oil sands and Ontario district heating systems present underpenetrated overhaul demand with distinct procurement timelines.
- Power Producers:Private equity-backed independent power producers favor predictable EBITDA profiles through contractual coverage extensions.
- OEMs:Original equipment manufacturers maintain captive service networks for warranty compliance and technology control.
Commanding largest contract value: Utilities. Gaining share fastest: Power Producers.
Contract Type:
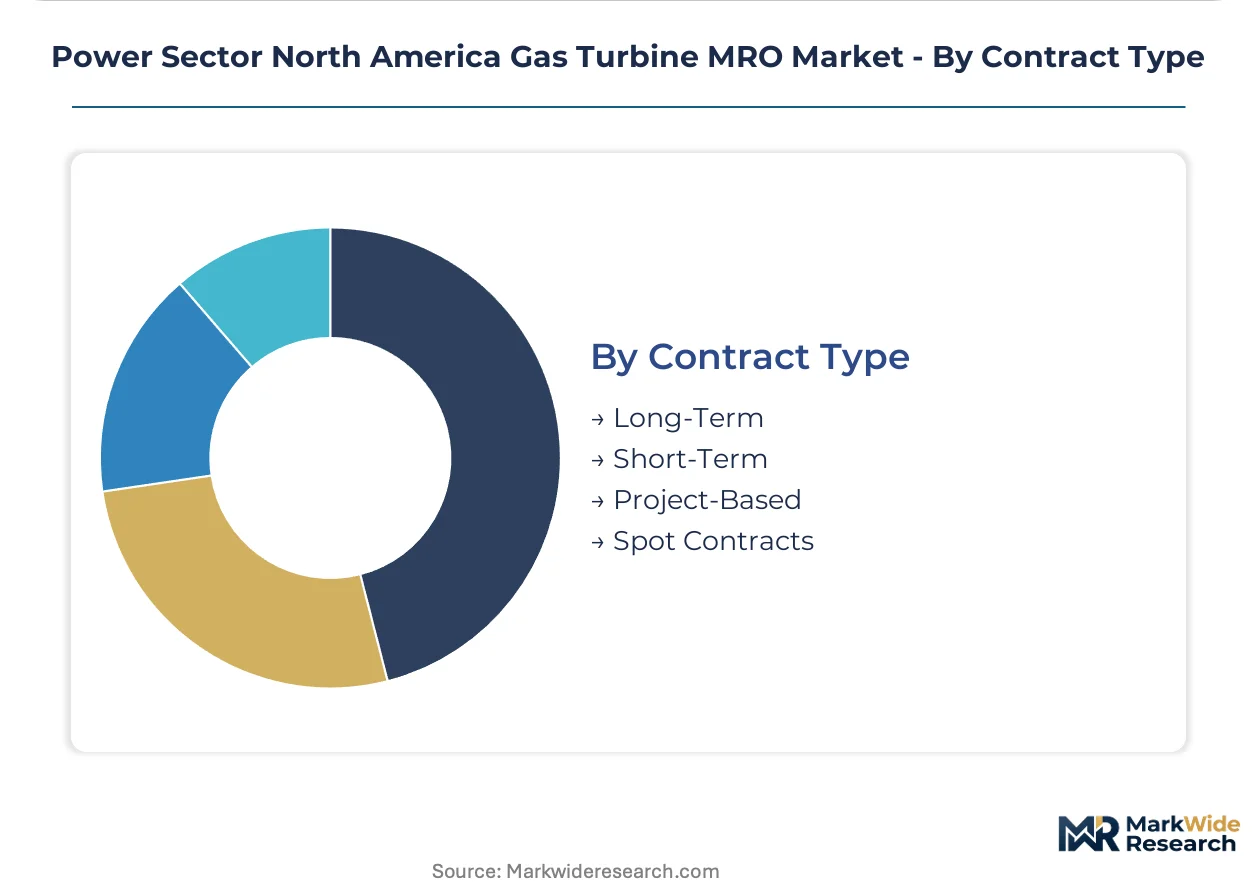
Volume concentration and margin structure vary sharply across contract duration, with long-term agreements displacing transactional procurement among merchant generators seeking cost predictability.
- Long-Term:Fifteen-year fixed-price agreements with guaranteed parts availability now dominate Texas and PJM markets. These contracts incorporate digital twin integration and predictive maintenance subscription models.
- Short-Term:Annual or multi-year agreements serve smaller operators with limited capital commitment capacity.
- Project-Based:Discrete overhaul events for aging fleet hot gas path inspections trigger EPA New Source Review exposure.
- Spot Contracts:Emergency repair procurement commands premium pricing during peak demand periods.
Capturing majority revenue: Long-Term. Steepest expansion trajectory: Project-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pennsylvania and Ohio vacuum induction melting capacity anchors superalloy supply chains for turbine blade casting across North American MRO networks. This metallurgical infrastructure concentrates procurement leverage for hot gas path refurbishment cycles.
United States
Texas and Gulf Coast baseload gas generation clusters compress overhaul intervals as firing-hour accumulation triggers EPA emissions compliance inspections. FERC reliability mandates now require documented turbine availability guarantees from independent system operators. Houston and Corpus Christi host concentrated mobile repair unit deployment serving combined-cycle plants.
Canada
Alberta oil sands thermal facilities and Ontario district heating systems present underpenetrated overhaul demand outside US utility procurement structures. Provincial regulators enforce distinct emissions documentation protocols for cogeneration assets. Calgary and Toronto industrial corridors favor shorter contract durations than American fifteen-year agreements.
Mexico
Natural gas-fired capacity expansion along the US-Mexico border generates cross-border service logistics for turbine maintenance. Comisión Federal de Electricidad procurement frameworks emphasize local content requirements for major overhauls. Monterrey and Tamaulipas industrial zones attract mobile repair units from Texas-based service providers.
Power Sector North America Gas Turbine MRO Market Competitive Landscape
Global majors compete with regional champions across service network density and long-term contract anchoring. The market consolidates around OEM-captive networks and independent service providers with specialized hot gas path capabilities. Three archetypes dominate: full-service OEM integrators, component refurbishment specialists, and mobile repair unit operators. Competitive positioning depends on securing fifteen-year fixed-price agreements and backward integration into superalloy casting capacity.
Among OEM-anchored service networks, General Electric Company, Siemens Energy AG, and Mitsubishi Heavy Industries Ltd exemplify the integrated archetype combining distributed repair infrastructure with technology control. These entities occupy positions defined by warranty compliance authority and proprietary hot gas path refurbishment protocols. Their market presence reflects long-term service agreement penetration rather than transactional procurement capture.
| Leading Market Players |
|---|
| General Electric Company |
| Siemens Energy AG |
| Mitsubishi Heavy Industries Ltd |
| Fluor Corporation |
| Power Services Group |
| Bechtel Corporation |
| Solar Turbines |
| Sulzer AG |
| Mechanical Dynamics & Analysis LLC |
| Others |
Pricing and Supply Chain Analysis
EPA Good Neighbor Plan ozone transport compliance gates both qualified MRO provider networks and premium-tier pricing access for hot gas path refurbishment, as only certified shops with Level III non-destructive testing technicians and documented emissions traceability protocols can bid on Ohio River Valley and Mid-Atlantic utility contracts.
Pricing Analysis
Warranty bundling and long-term service agreement structures separate premium-tier pricing from unbundled transactional overhaul procurement. Fifteen-year fixed-price contracts with guaranteed parts availability command premium positioning among Texas and PJM independent power producers seeking predictable EBITDA profiles, while spot emergency repairs extract maximum pricing leverage during peak demand periods. Price differentiation hinges on NERC CIP cybersecurity certification tier and hot gas path refurbishment technology control. Cost compression in standard-tier maintenance is intensifying as cold spray deposition and additive manufacturing displace conventional welding, eroding legacy repair shop margins. Merchant power generators exhibit highest price sensitivity, while investor-owned utilities anchoring Midwest and Southeast fleets demonstrate lowest sensitivity due to rate-base recovery mechanisms.
Supply Chain Analysis
Superalloy blade casting feedstock rests on vacuum induction melting capacity concentrated in Pennsylvania and Ohio, with nickel-based superalloy ingot supply drawing from domestic specialty metals producers and select European precision foundries. Critical input dependencies include cobalt-chromium alloys, ceramic thermal barrier coatings, and precision-cast turbine vanes. Single-source vulnerability in Pennsylvania-Ohio metallurgical infrastructure creates input cost volatility when capacity constraints emerge. Distribution runs through OEM-captive service networks, independent hot gas path specialists with mobile repair units, and regional component refurbishment shops serving Gulf Coast baseload clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
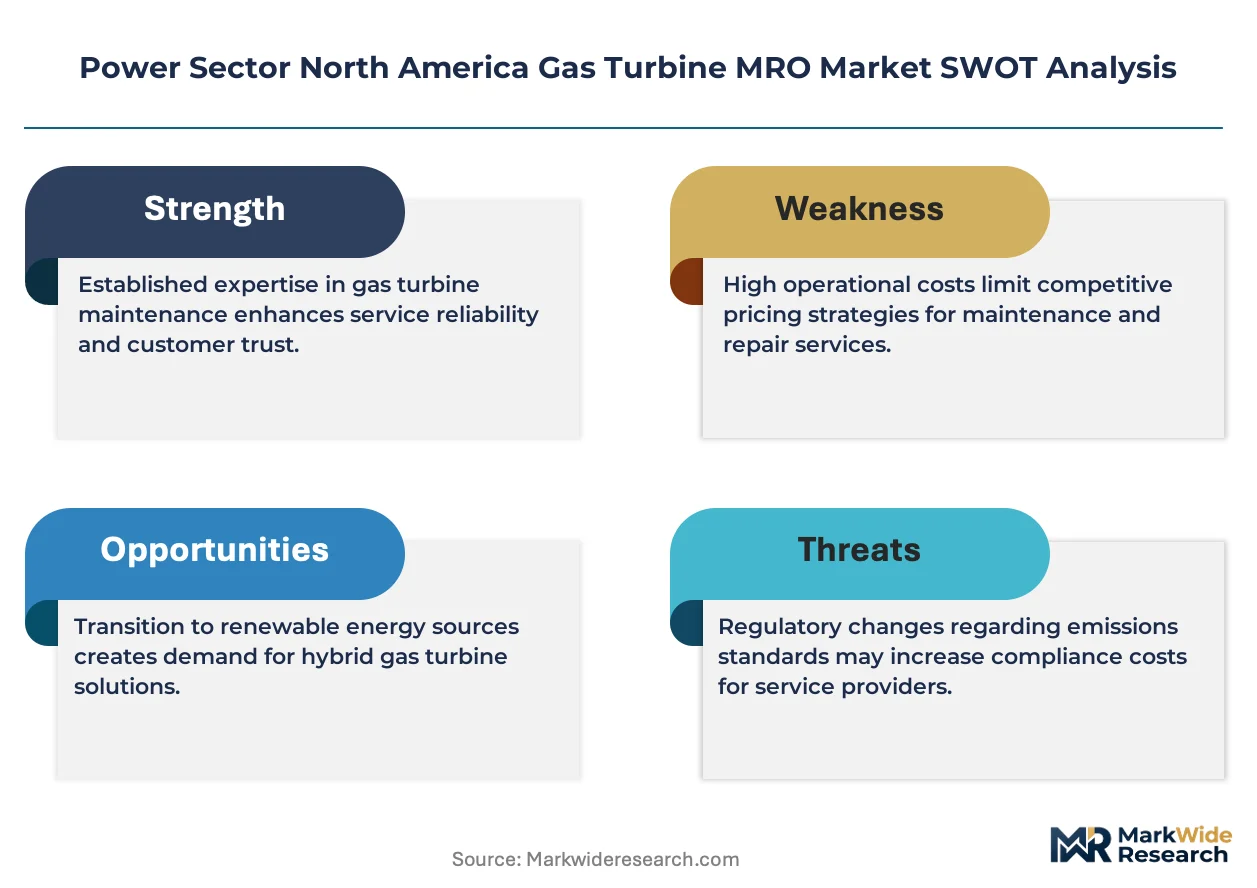
The North American gas turbine MRO sector sits in a technology-transition phase as hydrogen co-firing combustion system retrofits displace legacy natural gas-only configurations, reshaping component material specifications and refurbishment technical scopes.
For Market Incumbents: Anticipate hydrogen compatibility certification requirements by securing backward integration into superalloy casting capacity and pre-positioning low-NOx burner hardware inventories ahead of EPA enforcement timelines. Anchor long-term service agreement renewals through digital twin integration subscriptions that lock in fifteen-year contractual coverage. Defensive positioning requires capturing Alberta oil sands and Ontario district heating cogeneration demand outside traditional US utility procurement structures. For New Entrants and Emerging Players: The premium-to-economy price-point gap in hot gas path refurbishment creates entry space for mobile repair unit operators with cold spray deposition capabilities and Level III non-destructive testing certification. Target Canadian provincial procurement frameworks with shorter contract durations and distinct emissions documentation protocols than American fifteen-year agreements. Penetrate through specialized hydrogen co-firing pilot project support in Louisiana and California combined-cycle installations. For Investors and Strategic Acquirers: FERC-mandated turbine availability guarantee documentation is the leading indicator that long-term service agreement pricing power is consolidating among OEM-anchored networks with distributed repair infrastructure. Five-to-ten year viability favors acquisition of independent hot gas path specialists with backward integration into superalloy casting and NERC CIP cybersecurity-compliant documentation systems. Monitor hydrogen blending percentage mandates in state-level clean energy standards as the critical inflection signal for combustion system retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Casting | Captive vacuum induction melting capacity insulates against Pennsylvania-Ohio supply concentration risk and secures hot gas path refurbishment margins. |
| Hydrogen Co-firing Combustion Retrofit | Louisiana and California pilot projects validate specialized burner hardware demand ahead of broader EPA emissions compliance deadlines. |
| Digital Twin Platform Deployment | Predictive maintenance subscriptions anchored in physics-based degradation modeling convert transactional overhaul procurement to recurring revenue streams. |
| NERC CIP Cybersecurity Certification | Segmented network architecture compliance for maintenance documentation systems qualifies bidders for FERC-mandated availability guarantee contracts. |
| Canadian Cogeneration Market Entry | Alberta oil sands thermal facilities and Ontario district heating systems present underpenetrated overhaul demand with distinct provincial regulatory frameworks. |
Research Methodology
Multi-period observation of fired-hour accumulation patterns, EPA emissions compliance inspection intervals, and long-term service agreement renewal rates anchored the trend analysis, supplemented by interviews with utility planning officers, independent power producer asset managers, EPC contractors, hot gas path refurbishment technicians, and FERC regulatory specialists. Secondary validation drew from EIA power plant databases, FERC filings, EPA Clean Air Act enforcement records, NERC CIP compliance documentation, and OEM service network disclosures. Bottom-up triangulation across individual turbine unit maintenance schedules converged with top-down market sizing through utility capital expenditure tracking and IPP portfolio aggregation.
Segment-weighting across service type, technology, end user, and contract type dimensions structured the analytical framework across the projection horizon. Modeled dimensions included maintenance versus overhaul versus repair service categories, heavy-duty versus aeroderivative versus hybrid combustion configurations, utility versus industrial versus power producer customer archetypes, and long-term versus project-based contract structures. CAGRs derived from regression analysis of historical fired-hour accumulation rates, fleet age distribution curves, and regulatory compliance cost passthrough elasticity. Industry-specific forecast inputs incorporated hydrogen co-firing pilot expansion timelines and superalloy supply capacity utilization rates.
Underlying measurement precision varies by segment; long-term service agreement pricing and utility capital expenditure flows carry tighter precision than spot emergency repair procurement and merchant generator discretionary spend. Forecasts reflect assumptions regarding EPA enforcement intensity, FERC reliability mandate evolution, and superalloy supply chain stability. Hydrogen blending mandate acceleration, vacuum induction melting capacity constraints, and NERC CIP cybersecurity rule revisions constitute the small set of triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Global Power Grid System Market
Power Generation
Captive Power Plant Market
Power Generation
South East Asia Power Market
Power Generation
Global Gas Turbines Market
Power Generation
Tunisia Power Market
Power Generation
Europe Distributed Power Generation Market
Power Generation
Peaking Power Plant Market
Power Generation
Mexico Combined Heat and Power Market
Power Generation
Coal Fired Power Generation Market
Power Generation
Hydrogenerators Market
Power Generation
Power Plant EPC Market
Power Generation
Temporary Power Generation & Power Rental Market
Power Generation
Europe Thermal Power Market
Power Generation
Global Turbines Market
Power Generation
India Gensets Market
Power Generation
Distributed Power Generation Market