
 Oil and Gas Engineering Services Market | 2026-2036
Oil and Gas Engineering Services Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Engineering Services Market Analytics
Saudi Arabia is rewriting capital deployment patterns across the oil and gas engineering services sector with its offshore and onshore megaproject pipeline. Schlumberger leverages its integrated drilling and evaluation portfolio to anchor long-term contracts in the kingdom's offshore fields. Worley competes through its hydrogen and carbon capture engineering specialization, while Saipem sustains heavy-living and subsea installation dominance across Middle Eastern waters.
Oil and gas engineering services encompass the technical planning, design, simulation, and project execution required to develop hydrocarbon reservoirs, transport raw materials, and process refined products across upstream, midstream, and downstream stages. These services rely on 3D modeling, process simulation, and automation systems to optimize field development plans and reduce operational risk. Upstream application segments command the deepest engineering margins due to subsea complexity and frontier exploration demands, while downstream refining services remain mature with replacement-cycle driven procurement. IoT Solutions within the technology dimension represent the fastest-expanding service layer as operators demand real-time asset monitoring.
The EPA enforces methane emissions standards that reshape offshore platform design specifications and flare system engineering across United States waters. API standards and BSEE safety mandates further constrain equipment qualification and contractor certification requirements for Gulf of Mexico operations. Stakeholders must monitor how carbon border adjustments and Scope 3 accounting rules redirect engineering procurement toward low-carbon project configurations.
Market Dynamics
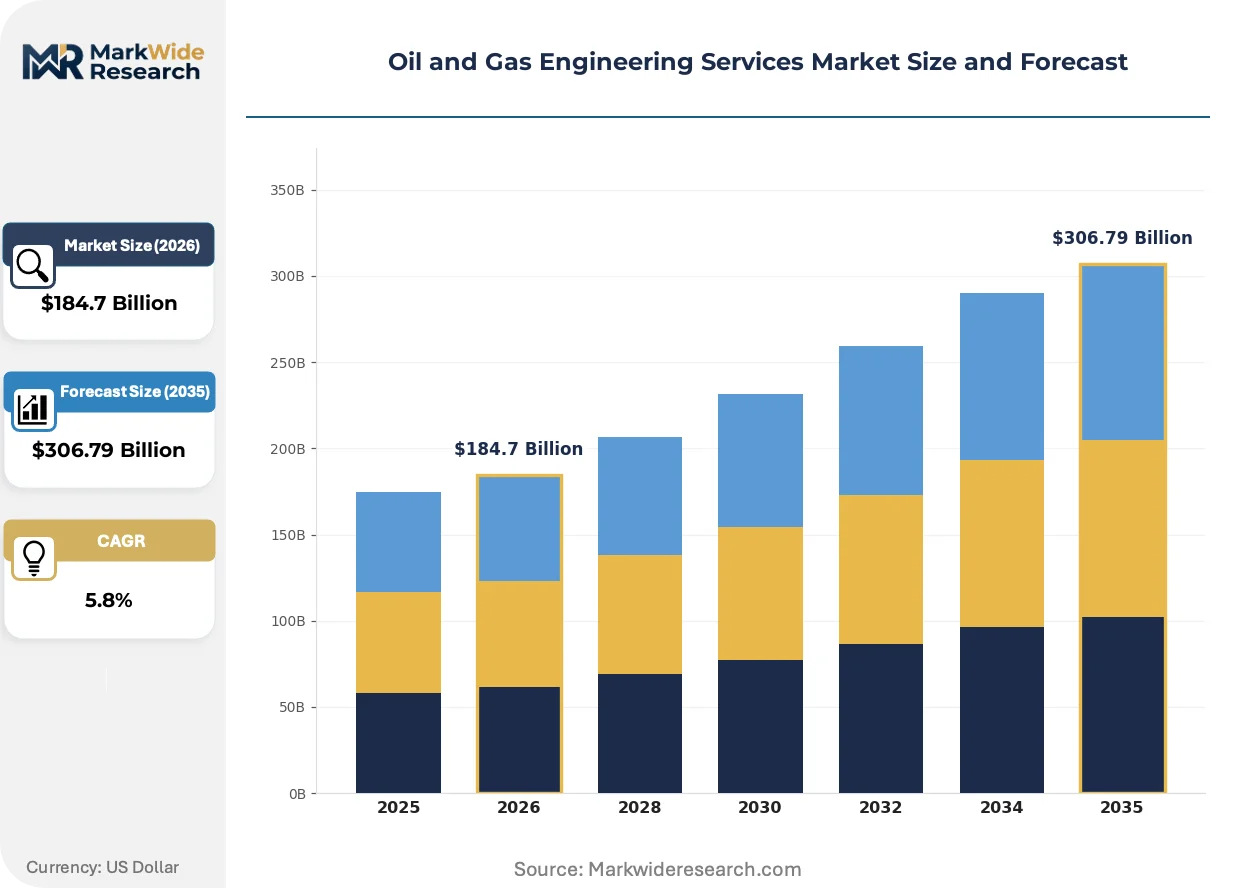
Deepwater exploration economics in Brazil and methane abatement mandates across United States offshore zones are compressing engineering contractor margins while elevating integrated service bundling requirements.
Growth Catalysts
- EPA Methane Emissions Standards:Tightened design specifications for offshore platforms in United States waters are forcing engineering procurement toward flare system upgrades and leak detection retrofits.
- Digital Twin Adoption:Real-time 3D field modeling is reducing operational risk across upstream development planning, with operators demanding IoT-enabled asset monitoring layers.
- Saudi Aramco Megaprojects:Full-cycle engineering capabilities for offshore and onshore developments in Saudi Arabia are concentrating procurement among contractors with integrated drilling and subsea installation portfolios.
Market Restraints
- Specialized Steel and Alloy Input Costs:Subsea pipeline and platform fabrication depends on corrosion-resistant metallurgy subject to volatile commodity pricing and concentrated supplier bases.
- Deepwater Technical Limitations:Pressure-rated equipment for ultra-deep reservoirs beyond 3,000 meters remains qualified through only a handful of global testing facilities.
- BSEE Safety Mandates:Equipment qualification and contractor certification requirements for Gulf of Mexico operations add procedural friction to project timelines.
Strategic Opportunities
- Hydrogen and Carbon Capture Engineering:Specialized process design capabilities for blue hydrogen production and CO2 sequestration infrastructure are opening procurement channels outside traditional hydrocarbon scopes.
- Brazil Deepwater Expansion:Integrated engineering package procurement from pre-salt operators is creating demand for contractors with local content compliance and heavy-living vessel coordination.
- API Standards Convergence:Unified equipment qualification frameworks are reducing certification duplication costs for contractors serving multiple offshore jurisdictions.
Industry Challenges
- Subsea Systems Integration Complexity:Legacy platform control architectures require extensive retrofit engineering to interface with modern digital monitoring and autonomous inspection technologies.
- Specialized Welding and Inspection Talent Scarcity:Hyperbaric welding certification and subsea robotics operation skills face generational replacement gaps across contractor workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Engineering Services Market |
| Market Size in 2026 | $184.7 Billion |
| Market Size in 2035 | $306.79 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Consulting, Project Management, Construction Technology: 3D Modeling, Simulation, Automation, IoT Solutions Application: Upstream, Midstream, Downstream, Refining End User: Exploration Companies, Drilling Contractors, Oil Producers, Service Providers |
| Companies Covered | Schlumberger, Halliburton, Baker Hughes, TechnipFMC, Saipem, Wood Group, KBR, Fluor Corporation, Worley, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Engineering Services Market Evolving Landscape
Automation systems and emissions monitoring technologies are compressing traditional engineering service boundaries, forcing contractors to embed software competencies within hardware-centric project delivery.
Digital twin platforms are hybridizing physics-based reservoir simulation with real-time production data streams. Major offshore operators in Norway and Brazil are deploying these systems for predictive maintenance of subsea trees and manifolds. The technology is hybridizing separate engineering disciplines—process design, mechanical integrity, and control systems—into unified service contracts that displace siloed procurement.
REACH chemical safety regulations in Europe are restricting subsea insulation and coating material formulations used in North Sea developments. Engineering contractors must reformulate corrosion protection specifications and requalify equipment through notified bodies. Subsea installation projects in Norwegian and UK waters face extended material certification timelines as suppliers adapt to substance restriction lists.
Integrated service contracts are displacing discrete engineering procurement across Middle Eastern offshore developments. National oil companies in Saudi Arabia and the UAE are bundling front-end engineering, procurement, and construction management into single-source agreements. This concentration is most visible in shallow-water gas field developments where operators prioritize schedule certainty over multi-vendor competition.
Oil and Gas Engineering Services Market Segmentation
Engineering procurement patterns in hydrocarbon development diverge sharply across service maturity and technical complexity. Contractors must align capability portfolios with segment-specific margin structures and qualification barriers.
Service Type:
Established engineering disciplines anchor revenue stability while integrated delivery models reshape competitive positioning.
- Design:Front-end engineering packages for subsea field architectures command premium pricing due to reservoir simulation complexity and regulatory scrutiny. Brazilian pre-salt operators concentrate procurement here for integrated drilling and production systems.
- Consulting:Technical advisory on methane abatement strategies and carbon capture feasibility is accelerating fastest as EPA standards tighten offshore platform specifications. Specialist firms embed process safety and emissions accounting into traditional reservoir engineering scopes.
- Project Management:EPCM contracting dominates Saudi Aramco megaprojects where schedule certainty overrides multi-vendor competition.
- Construction:Heavy-living vessel coordination and modular fabrication drive procurement in Middle Eastern shallow-water gas developments.
Design retains volume leadership; Consulting holds the steepest expansion curve.
Technology:
Digital capability layering determines contractor differentiation across hardware-centric project delivery.
- 3D Modeling:Real-time field visualization platforms integrate geophysical data with drilling plans, compressing development timelines for deepwater Brazil operators.
- Simulation:Physics-based reservoir modeling predicts production decline and informs facility sizing decisions.
- Automation:Control system engineering for unmanned platforms reduces operational expenditure in North Sea marginal fields.
- IoT Solutions:Sensor networks and edge computing architectures enable predictive maintenance of subsea trees and manifolds. Norwegian operators deploy these systems across offshore assets to minimize intervention vessel callouts.
3D Modeling captures the largest implementation base; IoT Solutions is climbing the fastest as operators demand real-time asset monitoring layers.
Application:
Upstream complexity sustains margin premiums while downstream replacement cycles stabilize procurement volumes.
- Upstream:Subsea engineering for frontier exploration and deepwater development commands the deepest margins due to pressure-rated equipment requirements and limited qualified supplier bases. Brazil's pre-salt layer and Guyana's offshore blocks concentrate demand.
- Midstream:Pipeline integrity engineering and compression station design support baseload transportation infrastructure.
- Downstream:Refinery revamp and capacity debottlenecking follow predictable maintenance schedules.
- Refining:Process unit optimization and emissions control retrofitting respond to carbon border adjustment pressures in European markets.
Upstream dominates value capture; Refining is gaining share fastest through low-carbon reconfiguration mandates.
End User:
Procurement authority fragmentation shapes contract structures and technical specification authority.
- Exploration Companies:Independent operators prioritize front-end engineering for prospect evaluation and farm-out package preparation.
- Drilling Contractors:Rig fleet modernization drives demand for automation integration and digital twin deployment.
- Oil Producers:National oil companies in Saudi Arabia and the UAE bundle full-cycle engineering into single-source agreements, concentrating procurement among integrated service providers.
- Service Providers:Subcontractor engineering support for specialized welding, inspection, and subsea robotics faces generational talent scarcity across certification pipelines.
Oil Producers anchor contract volume; Service Providers are expanding most quickly through niche technical specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized welding and subsea fabrication capacity clusters in the United States, Saudi Arabia, Brazil, Norway, and China. These five markets concentrate engineering procurement for deepwater, unconventional, and megaproject developments.
United States
Deepwater exploration in the Gulf of Mexico and Permian Basin shale development drive engineering demand. EPA methane emissions standards tighten flare system specifications for offshore platforms. Houston anchors the largest concentration of subsea engineering contractors serving Gulf of Mexico operators.
Saudi Arabia
Offshore and onshore megaprojects require full-cycle engineering capabilities from front-end design through construction. SFDA chemical safety mandates influence material specifications for subsea insulation systems. Dhahran and Jubail Industrial City host integrated engineering centers supporting Saudi Aramco's procurement concentration.
Brazil
Pre-salt deepwater exploration creates demand for pressure-rated equipment and heavy-living vessel coordination. ANVISA regulates subsea chemical injection systems used in corrosion management. Rio de Janeiro and Macaé cluster engineering contractors serving Petrobras and international pre-salt operators.
Norway
North Sea marginal field development and unmanned platform automation sustain engineering procurement. REACH chemical safety regulations restrict subsea coating and insulation material formulations. Stavanger and Bergen concentrate digital twin specialists serving Equinor and independent North Sea operators.
China
Offshore gas field development in the South China Sea and shale engineering services expand procurement volumes. MEE environmental standards govern emissions control for offshore platform operations. Shenzhen and Tianjin host fabrication yards supplying subsea equipment for domestic and export markets.
Oil and Gas Engineering Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fabrication and material supply. The market structures around three tiers: integrated service providers bundling design-through-construction, specialized engineering consultancies, and equipment fabricators. Strategic archetypes include full-cycle EPCM contractors, digital capability specialists, and subsea installation heavyweights. Competitive moves center on integrated contract bundling and hydrogen engineering portfolio expansion.
Among integrated service providers, Schlumberger, Saipem, and Worley occupy positions across the upstream engineering spectrum. Schlumberger anchors the digital-physical integration tier through drilling and evaluation capabilities. Saipem exemplifies subsea installation and heavy-living vessel coordination for deepwater developments. Worley sits within the energy transition engineering tier, specializing in hydrogen and carbon capture process design. These three represent the competitive positioning vectors—digital integration, subsea execution, and low-carbon engineering—that define procurement concentration in Saudi Arabian megaprojects and Brazilian pre-salt developments.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Baker Hughes |
| TechnipFMC |
| Saipem |
| Wood Group |
| KBR |
| Fluor Corporation |
| Worley |
| Others |
Value Network & Pricing Analysis
Houston's subsea engineering corridor anchors fabrication capacity for Gulf of Mexico operators, concentrating supplier leverage over pricing terms for corrosion-resistant alloys and pressure-rated equipment. This geographic clustering enables tier-one contractors to extract volume discounts from metallurgical suppliers while passing certification premiums downstream to independent operators.
Pricing Analysis
EPA methane emissions standards dictate the pricing tier structure across offshore platform engineering services. Three-tier pricing structure across premium, standard, and economy levels separates API-certified integrated contractors from regional specialists and commodity fabricators. Price differentiation hinges on BSEE safety certification tier and after-sales service bundling for predictive maintenance systems. Cost compression in the standard tier is intensifying because Brazilian pre-salt operators are consolidating procurement into single-source agreements. Exploration companies exhibit the highest price sensitivity, while Saudi Aramco's megaproject procurement prioritizes schedule certainty over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become critical tools for subsea equipment fabricators managing working capital through 180-day project cycles. Manufacturing clusters in the United States, Saudi Arabia, and China draw from specialized steel mills in Japan and South Korea for corrosion-resistant alloys. The supply chain rests on nickel-based superalloy feedstock and hyperbaric welding consumables subject to concentrated supplier bases. Single-source vulnerability around pressure-testing facilities for ultra-deep equipment creates bottlenecks. Distribution runs through EPCM contractors serving national oil companies with bundled procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oil and gas engineering services are entering a cyclical recovery phase as deepwater exploration economics in Brazil and methane abatement mandates in United States waters drive replacement-cycle procurement. Capital deployment into frontier basins and low-carbon reconfiguration projects sustains contractor backlogs through the projection horizon.
For Market Incumbents: Insulate margin positions by deepening backward integration into specialized welding certification pipelines and captive supply of subsea robotics capabilities. Anchor long-term contracts through digital twin integration that locks operators into proprietary monitoring platforms. Threat substitution from hydrogen engineering specialists requires defensive capability acquisition in carbon capture process design.
For New Entrants and Emerging Players: Establish a beachhead in North Sea marginal field automation where Equinor's unmanned platform rollout creates demand gaps incumbent EPCMs have underinvested in. Target subsea inspection robotics as the most penetrable segment given generational talent scarcity across certified operator pools. Lead with outcome-based contracting that ties fees to intervention vessel reduction metrics rather than capital expenditure markups.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement concentration among Saudi Aramco and Petrobras favors scaled contractors with integrated drilling-through-construction portfolios. Acquisition targets should exhibit hydrogen engineering capabilities or Brazil local content compliance rather than pure fabrication assets. Watch ANP regulatory relaxation on foreign vessel participation as the signal for Brazilian pre-salt contract inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Equinor and Petrobras contracts now mandate real-time 3D field modeling for predictive maintenance. |
| Hydrogen Engineering Capability Buildout | Worley's carbon capture specialization opened Saudi Aramco blue hydrogen procurement channels outside traditional scopes. |
| Brazil Local Content Compliance Investment | ANP requirements force foreign contractors into Macaé fabrication partnerships for pre-salt eligibility. |
| Subsea Robotics Certification Pipeline | Saipem's hyperbaric welding training centers address generational replacement gaps in inspection talent. |
| Integrated EPCM Contract Concentration | Schlumberger's bundled drilling-evaluation-procurement packages displaced discrete service procurement in Middle Eastern megaprojects. |
Research Methodology
A spread of perspectives from EPC project directors, subsea equipment procurement managers, regulatory compliance officers, and digital twin platform engineers converged on the working assumptions shaping this analysis. Primary fieldwork across Houston, Rio de Janeiro, and Dhahran supplemented secondary validation through BSEE safety filings, ANP project development databases, EPA emissions compliance records, and SEC 10-K disclosures from listed engineering contractors. Bottom-up project pipeline enumeration triangulated against top-down national oil company capital expenditure frameworks.
Demand-supply balance modeling across the analysis window segmented procurement by service type, technology layer, application stage, and end-user authority. The framework captured upstream engineering margins against downstream replacement cycles, digital capability premiums against commoditized fabrication, and integrated contract concentration against discrete procurement. CAGRs derived from project sanctioning timelines and operator spending plan trajectories, with specific weighting for Saudi Aramco megaproject phasing and Brazilian pre-salt development schedules.
Stress conditions across alloy price volatility, regulatory tightening velocity, and deepwater technical limitation resolution were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about national oil company procurement consolidation and emissions standard implementation timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Electric Fracking Market
Oil & Gas
Global Seismic Survey Market
Oil & Gas
Asia-Pacific Oilfield Chemicals Market
Oil & Gas
Africa Natural Gas Market
Oil & Gas
Oilwell Completion Tools Market
Oil & Gas
Canada LNG Market
Oil & Gas
Colombia Oil and Gas Downstream Market
Oil & Gas
Aqueous Flare Meter Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
Kazakhstan Oil and Gas Midstream Market
Oil & Gas
Europe Coiled Tubing Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
North America Completion Equipment and Services Market
Oil & Gas
Africa Drilling and Completion Fluids Market
Oil & Gas
Oil and Gas Electrification Market
Oil & Gas
Geothermal Drilling Market