
 Polyester Staple Fiber Market | 2026-2036
Polyester Staple Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Polyester Staple Fiber Market Analysis
Automotive interior applications is consolidating share within polyester staple fiber offtake as OEMs pursue lighter cabin materials and recycled content mandates. Indorama Ventures Public Company Limited leverages its integrated PET resin-to-fiber chain to supply certified recycled grades directly to tier-one seating suppliers. Toray Industries, Inc. anchors its position through advanced polymer modification R&D that improves fiber resilience under thermal cycling. Tongkun Group Co., Ltd. dominates Chinese domestic volume with backward integration into purified terephthalic acid production.
Polyester staple fiber consists of short-length polyethylene terephthalate filaments, typically cut to 32–102 millimeters, produced through melt spinning and staple cutting processes for subsequent carding or air-laid web formation. Its primary commercial purpose centers on providing durable, hydrophobic, and cost-efficient fibrous inputs for yarn spinning and non-woven fabric assembly. Non-woven grades currently lead volume absorption due to surge demand in hygiene disposables and industrial filtration media where loft and liquid retention properties command premium positioning. Carded segments sustain margin pools in apparel basics and home textile applications where fiber length uniformity determines downstream processing efficiency. Dyed specialty fibers represent the fastest-growing product type as brand owners specify solution-dyed alternatives to reduce water-intensive piece-dyeing steps.
REACH substance restrictions and the EU Green Deal carbon border adjustments are reshaping import fiber specifications across European textile and automotive supply chains. China's GB standards and dual carbon goals enforce energy intensity caps on staple fiber melt-spinning operations, compressing capacity at smaller producers. The US EPA industrial emissions framework and state-level extended producer responsibility bills in California and New York are elevating post-consumer recycled content thresholds for synthetic fiber products. Stakeholders must monitor regulatory divergence between jurisdictions to align product certification portfolios with diverging compliance baselines rather than assuming harmonized standards.
Market Dynamics
The polyester staple fiber market faces structural compression from regulatory divergence across major consuming regions, as carbon border adjustments and chemical substance restrictions fragment previously standardized product specifications into jurisdiction-specific compliance tiers.
Growth Catalysts
- EU Green Deal carbon border mechanisms:European automotive OEMs now mandate certified recycled-content fiber for seating applications, pulling premium-grade supply toward verified circular feedstock chains.
- Hygiene disposables expansion:Non-woven absorbency layers in adult incontinence and medical wipes consume increasing volumes of high-loft staple grades, particularly across Southeast Asian converting clusters.
- China's dual carbon enforcement:Energy intensity caps on melt-spinning operations are accelerating consolidation toward integrated producers with captive PTA supply, concentrating compliant capacity.
Market Restraints
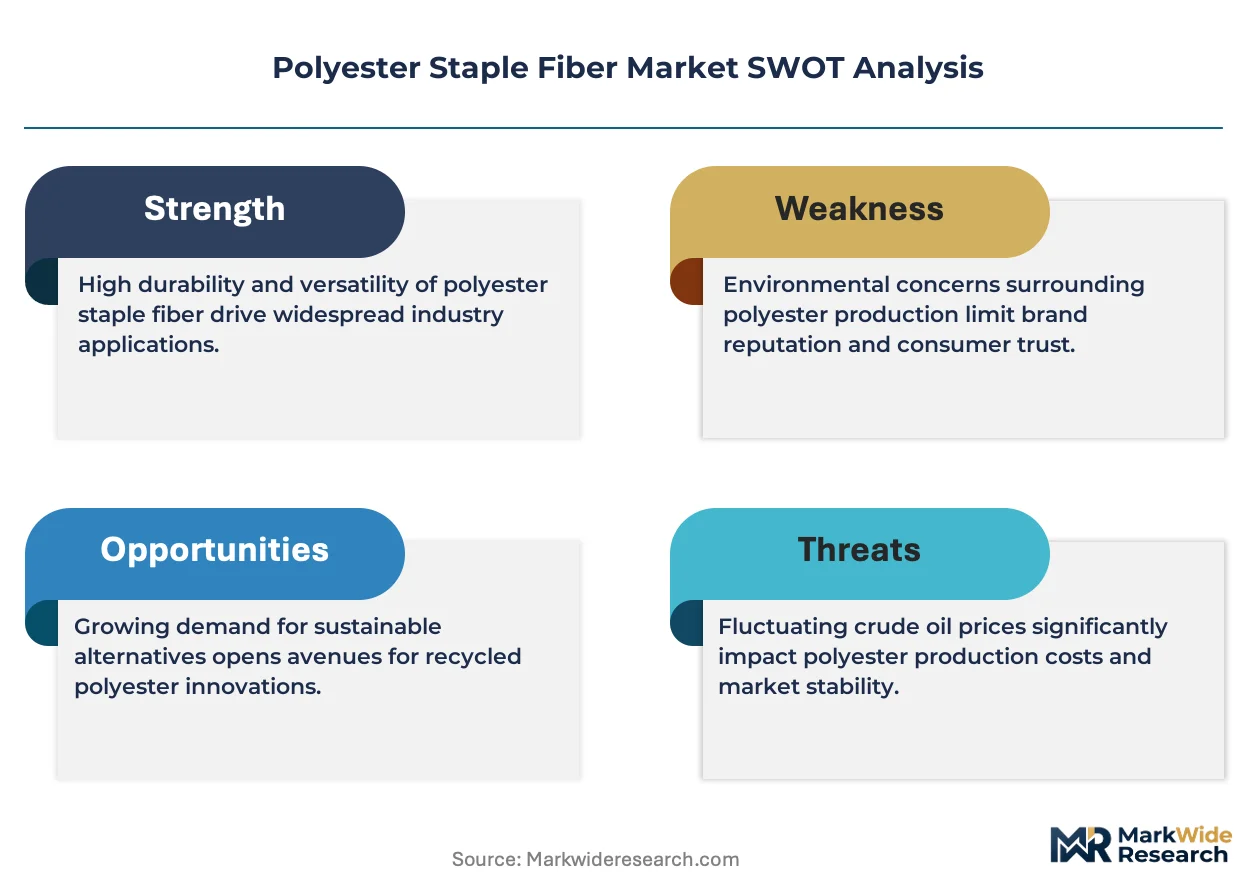
- Purified terephthalic acid price volatility:Crude-linked paraxylene feedstock costs transmit directly into staple fiber margin compression, exposing non-integrated spinners to input cost squeezes.
- Supply concentration in Zhejiang province:Over half of Chinese melt-spinning capacity clusters within a single coastal corridor, creating weather and logistics contingency exposure for global buyers.
- REACH substance restriction timelines:ECHA's rolling SVHC candidate list updates force continuous reformulation of fiber finishes and antistatic coatings, elevating R&D overhead.
Strategic Opportunities
- India's technical textile push:The country's PLI scheme for non-woven geotextiles and filtration media creates localized demand for industrial-grade staple fiber with specific tenacity specifications.
- Solution-dyed specialty migration:Brand owners specify pre-pigmented fiber to eliminate water-intensive piece-dyeing, opening premium positioning for polymer modification capabilities.
- California extended producer responsibility:State-level post-consumer recycled content mandates for synthetic textiles are forcing apparel brands to secure certified recycled fiber supply ahead of compliance deadlines.
Industry Challenges
- Polymer chemist talent scarcity:Melt-spinning process optimization and recycled feedstock contamination control require specialized expertise that regional education pipelines struggle to replenish.
- Multi-jurisdiction certification stacking:Simultaneous pursuit of GRS, OEKO-TEX, and EU Ecolabel approvals extends product launch timelines and fragments quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyester Staple Fiber Market |
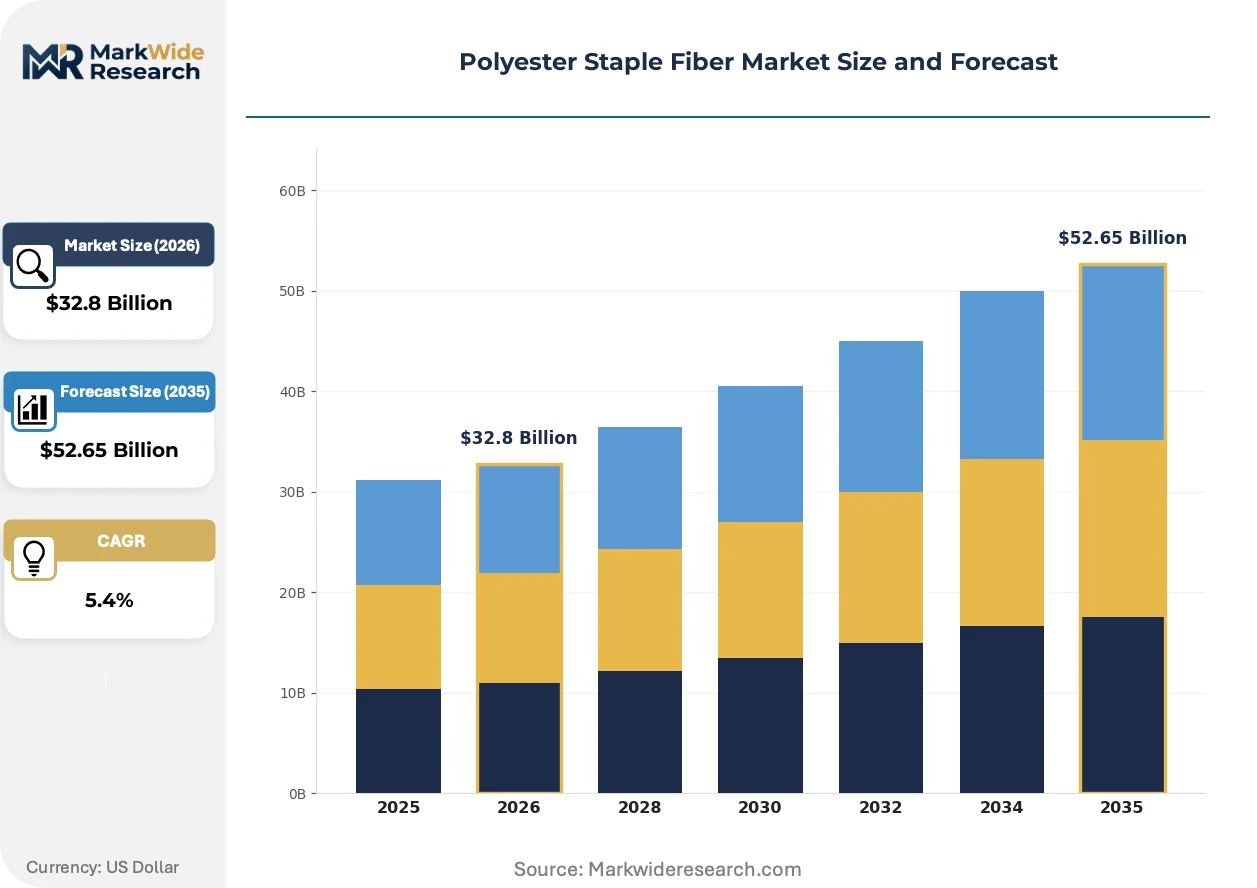
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carded, Combed, Non-woven, Dyed End User: Textiles, Automotive, Home Furnishings, Filtration Application: Clothing, Upholstery, Bedding, Carpets Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Toray Industries, Inc., Far Eastern New Century Corporation, Indorama Ventures Public Company Limited, Tongkun Group Co., Ltd., Zhejiang Hengyi Group Co., Ltd., Reliance Industries Limited, Alpek S.A.B. de C.V., Hengli Group Co., Ltd., Sinopec Yizheng Chemical Fibre Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyester Staple Fiber Market Emerging Trajectories
Active reshaping of this market stems from convergence between chemical recycling infrastructure scale-up and mechanical recycling quality advancement, bifurcating recycled-content supply into two competing technical pathways with distinct cost and performance profiles.
Advanced glycolysis-based chemical recycling is absorbing post-consumer PET waste streams previously rejected by mechanical processors due to contamination or color variance. Automotive seating suppliers in Germany and the US Midwest are qualifying chemically recycled staple fiber for visible interior surfaces at parity with virgin polymer resilience. This technology is absorbing premium pricing spreads that mechanical recyclers previously captured, compressing margins across intermediate reprocessing tiers.
REACH substance restrictions on per- and polyfluoroalkyl substances are forcing reformulation of durable water-repellent fiber finishes by December 2025 enforcement timelines. European outdoor apparel brands are accelerating qualification of silicone-based and hydrocarbon alternative chemistries, shifting specification power toward finish chemical suppliers with ECHA pre-registration dossiers. Technical outerwear segments face the steepest compliance cost escalation, with some brands delaying seasonal launches to secure reformulation validation.
Direct mill-to-brand contracting is displacing traditional trader-mediated fiber procurement in apparel basics, with large retailers establishing multi-year offtake agreements for specified recycled-content percentages. Bangladeshi and Vietnamese garment manufacturers now source staple fiber through brand-mandated supplier lists rather than spot market purchases. This concentration is most visible in US mass-market apparel, where three retailers account for a dominant share of certified recycled fiber contracting volume.
Polyester Staple Fiber Market Segmentation
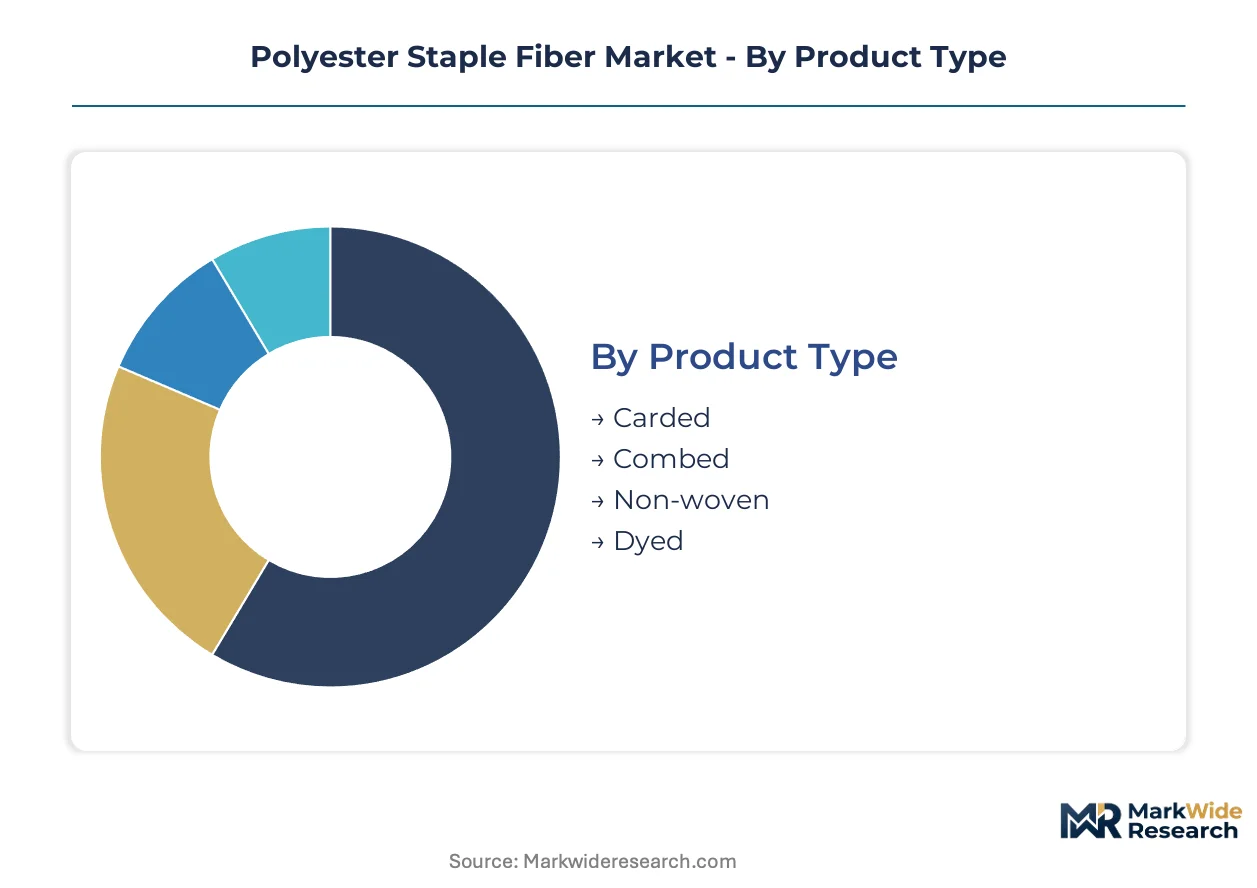
Polyester staple fiber segmentation reflects divergent processing requirements and end-use performance specifications. Buyers select grades based on downstream forming technology, regulatory compliance needs, and finished product durability standards.
Product Type:
Cost tier separates buyers in this category, with premium positioning commanding specialized polymer modification capabilities.
- Non-woven:High-loft staple grades engineered for air-laid and wet-laid web formation deliver superior absorbency and bulk retention. Demand concentrates in Southeast Asian converting clusters for hygiene disposables and medical wipes, driven by adult incontinence product expansion.
- Dyed:Solution-pigmented fiber eliminates water-intensive piece-dyeing through masterbatch integration during melt spinning. European outdoor apparel brands specify these grades to meet EU Green Deal water reduction mandates, with specialty polymer modification commanding premium positioning.
- Carded:Fiber length uniformity of 32–51 millimeters optimizes downstream yarn spinning efficiency for apparel basics.
- Combed:Extended staple lengths of 51–102 millimeters serve premium yarn applications requiring enhanced tensile consistency.
Volume sits with Non-woven; growth tilts toward Dyed.
End User:
Application maturity drives specification divergence, with emerging segments imposing stricter recycled-content verification protocols.
- Automotive:Seating and interior panel applications mandate certified recycled-content fiber under OEM circular material programs. German and US Midwest tier-one suppliers qualify chemically recycled grades for visible cabin surfaces, with thermal cycling resilience specifications tightening polymer modification requirements.
- Filtration:Industrial air and liquid filtration media demand precise denier control and chemical resistance for high-temperature operating environments. Chinese environmental enforcement is expanding flue gas treatment installations, pulling industrial-grade staple into power sector applications.
- Textiles:Yarn spinning for apparel and home textiles remains the foundational volume anchor.
- Home Furnishings:Upholstery and decorative applications prioritize color fastness and abrasion resistance.
Volume sits with Textiles; growth tilts toward Automotive.
Application:
Customer type determines fiber length and finish specifications, with contract manufacturers facing divergent brand-mandated compliance tiers.
- Clothing:Mass-market apparel basics consume high-volume carded staple through direct mill-to-brand contracting. Bangladeshi and Vietnamese garment manufacturers now source through retailer-mandated supplier lists, with California extended producer responsibility bills forcing recycled-content verification.
- Bedding:Quilted products and mattress components require hollow conjugate fiber for thermal insulation and loft retention. Chinese domestic consumption is scaling as urban household formation accelerates demand for synthetic fill alternatives to down.
- Upholstery:Furniture fabric applications emphasize abrasion resistance and flame retardancy compliance.
- Carpets:Bulked continuous filament and staple blends serve residential and commercial flooring installations.
Volume sits with Clothing; growth tilts toward Bedding.
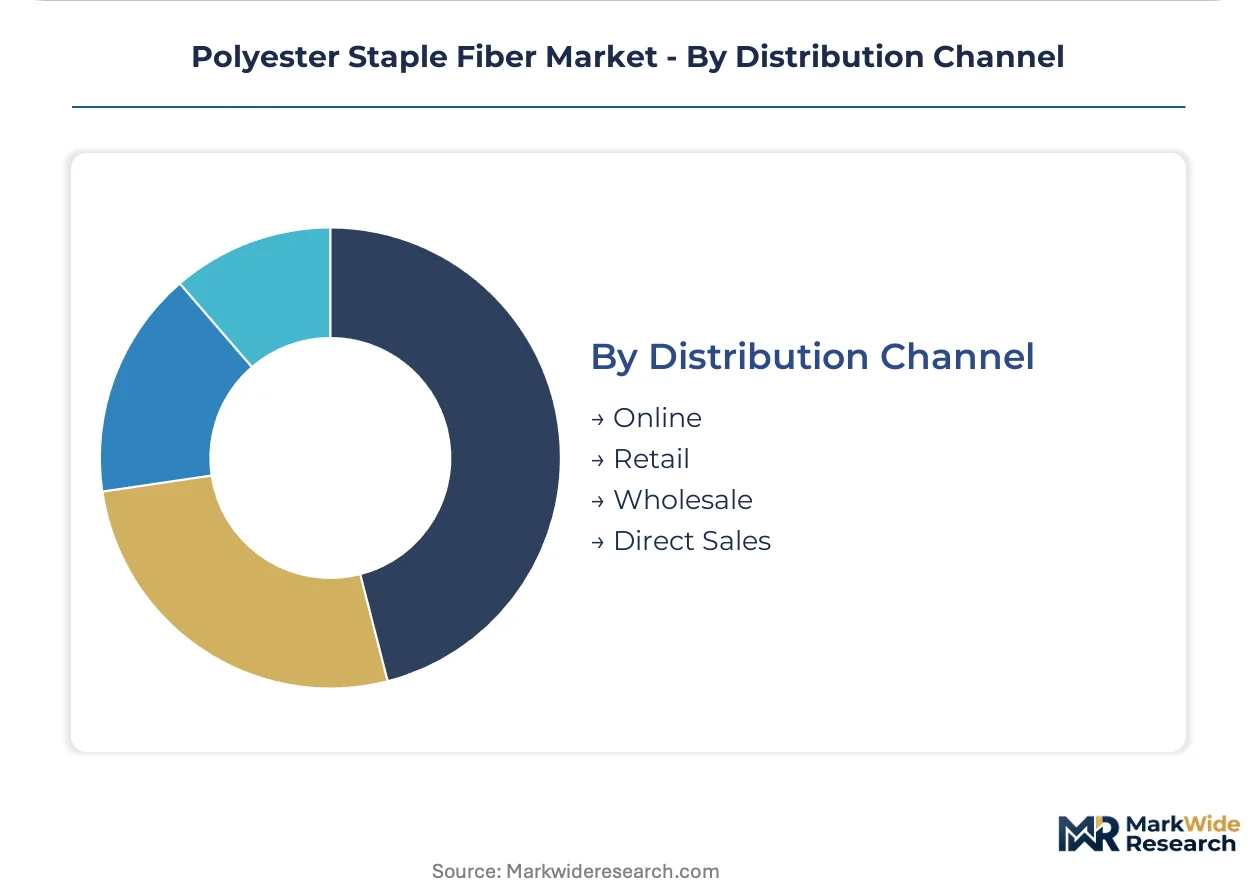
Distribution Channel:
Supply concentration shapes procurement patterns, with integrated producers bypassing intermediary tiers.
- Direct Sales:Captive supply agreements link major spinners to tier-one automotive seating and hygiene product manufacturers. Indorama Ventures and Tongkun Group leverage integrated PET resin-to-fiber chains to supply certified recycled grades without trader intermediation.
- Wholesale:Regional distributors serve mid-scale textile mills and non-woven converters with standardized grade inventories.
- Online:Digital procurement platforms are emerging for spot market transactions and sample qualification.
- Retail:Limited to specialty fiber sales for craft and small-scale manufacturing applications.
Volume sits with Direct Sales; growth tilts toward Wholesale consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in coastal China while consumption spreads across automotive and textile hubs in Germany, the United States, and Southeast Asia. This geographic split creates freight-intensive supply chains and regulatory arbitrage opportunities. Energy intensity caps and carbon border adjustments are reshaping where compliant capacity locates.
China
Domestic textile mills and automotive seating plants absorb the majority of global staple fiber output. GB standards and dual carbon goals enforce energy intensity caps on melt-spinning operations, compressing capacity at smaller producers. Zhejiang province hosts over half of national melt-spinning capacity, with Ningbo and Shaoxing clusters serving both export and domestic hygiene product manufacturers.
Germany
Automotive OEMs in Stuttgart and Munich mandate certified recycled-content fiber for cabin seating applications. ECHA's REACH substance restrictions and EU Green Deal carbon border adjustments force continuous reformulation of fiber finishes and antistatic coatings. The Ruhr industrial corridor hosts specialized chemical recycling facilities supplying chemically recycled grades to tier-one seating suppliers.
United States
Apparel brands and automotive manufacturers drive demand for high-tenacity and recycled-content grades. EPA industrial emissions frameworks and California's extended producer responsibility bills elevate post-consumer recycled content thresholds for synthetic textiles. The US Midwest automotive belt around Detroit qualifies chemically recycled fiber for visible interior surfaces.
India
Technical textile expansion in geotextiles and filtration media creates localized demand for industrial-grade staple fiber. The PLI scheme for non-woven applications incentivizes domestic converting capacity. Gujarat and Maharashtra host emerging melt-spinning operations targeting hygiene disposable and medical wipe segments.
Vietnam
Garment manufacturers serving US and EU brands source staple fiber through retailer-mandated supplier lists. Converting clusters around Ho Chi Minh City process imported fiber into yarn for apparel basics exports. The country's role as a contract manufacturing hub exposes processors to diverging EU and US compliance certification requirements.
Polyester Staple Fiber Market Vendor Landscape
Top-tier vendors anchor integrated PET resin-to-fiber chains, while mid-scale spinners compete on regional logistics and specialized grades. The market structure favors producers with captive purified terephthalic acid supply and certified recycled-content capabilities. Three archetypes dominate: integrated petrochemical conglomerates with backward integration into feedstock, specialized fiber spinners with polymer modification expertise, and regional converters leveraging tariff-advantaged locations. Competitive moves center on chemical recycling infrastructure partnerships and multi-year offtake agreements with automotive OEMs and mass-market retailers.
Within the integrated conglomerate tier, Indorama Ventures Public Company Limited and Tongkun Group Co., Ltd. exemplify scale-driven positioning through captive upstream supply chains. Toray Industries, Inc. occupies a position among polymer modification specialists, anchoring the advanced fiber resilience segment where thermal cycling specifications command premium positioning. These three entities collectively represent the dominant competitive archetypes: feedstock-integrated volume leadership, technical performance differentiation, and regional market concentration.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Far Eastern New Century Corporation |
| Indorama Ventures Public Company Limited |
| Tongkun Group Co., Ltd. |
| Zhejiang Hengyi Group Co., Ltd. |
| Reliance Industries Limited |
| Alpek S.A.B. de C.V. |
| Hengli Group Co., Ltd. |
| Sinopec Yizheng Chemical Fibre Company Limited |
| Others |
Supply Flow & Price Mechanics
Automotive OEM tier-one seating suppliers concentrate procurement power through multi-year offtake agreements, locking in contract-based long-term pricing that compresses spot-market premiums for non-integrated spinners. This buyer consolidation forces smaller melt-spinning operations toward commodity spot sales or distressed inventory liquidation.
Pricing Analysis
Margin tightening in virgin-grade staple reflects crude-linked paraxylene volatility transmitting directly into input cost squeezes. Three-tier pricing structure across GRS-certified recycled, OEKO-TEX standard, and uncertified economy grades separates buyers by compliance tier. Cost-down pressure on mechanical recyclers accelerates because chemical recycling facilities capture premium spreads for automotive-qualified fiber. Mass-market apparel brands exhibit highest price sensitivity, while German automotive seating suppliers accept premiums for thermal cycling resilience.
Supply Chain Analysis
Post-consumer PET bottle collection and glycolysis-based chemical recycling flows are reshaping feedstock sourcing, with European automotive OEMs mandating verified circular chains. Raw material dependencies center on purified terephthalic acid, monoethylene glycol, and post-consumer flake supply. Production concentrates in China, India, and Vietnam, with Zhejiang province hosting over half of global melt-spinning capacity. Single-source vulnerability from this coastal clustering exposes buyers to weather and logistics disruption. Distribution runs through direct mill-to-brand contracting for automotive and hygiene tiers, with wholesale channels serving mid-scale textile converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating rapidly as energy intensity caps under China's dual carbon goals force smaller, non-integrated spinners into distressed exit or acquisition.
For Market Incumbents:Cement feedstock security through backward integration into purified terephthalic acid production or captive chemical recycling partnerships. Scale GRS and OEKO-TEX certification portfolios ahead of EU Green Deal enforcement timelines to defend premium positioning against emerging mechanical recyclers with contamination control gaps.
For New Entrants and Emerging Players:Digital procurement platforms for spot-market fiber qualification offer the lowest-friction entry path. Target India's technical textile segment under PLI scheme incentives for geotextiles and filtration media, where tenacity specifications favor specialized polymer modification capabilities over commodity volume.
For Investors and Strategic Acquirers:The window for entry favors integrated petrochemical conglomerates with captive PTA supply and certified recycled-content pipelines. Mid-scale spinners with polymer modification expertise but lacking upstream integration represent prime acquisition targets. Monitor ECHA SVHC candidate list updates for forced reformulation triggers that elevate R&D overhead and compress margins at undercapitalized finish chemical suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PTA Production | Captive feedstock supply insulates margin compression from paraxylene volatility. |
| Chemical Recycling Partnership | Glycolysis-based facilities qualify fiber for German automotive visible interior specifications. |
| Multi-Year Offtake Agreement | Direct contracting with tier-one seating suppliers locks in volume ahead of EU carbon border adjustments. |
| Solution-Dyed Specialty Migration | Pre-pigmented fiber eliminates water-intensive piece-dyeing for EU Green Deal compliance. |
| Certification Portfolio Expansion | Simultaneous GRS, OEKO-TEX, and EU Ecolabel approvals access diverging jurisdiction requirements. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with melt-spinning plant managers, automotive tier-one procurement leads, hygiene product technical directors, and chemical recycling R&D heads. Bottom-up volume modeling triangulated against top-down industry association aggregates from Cefic, China Chemical Fiber Association, and ACC reports. SEC 10-K disclosures and ECHA pre-registration dossiers provided vendor-level capacity and certification data.
Segmentation granularity modeled product type at grade tier, end-use industry at automotive versus textile versus filtration, and regional production hub at country level across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating automotive lightweighting content per vehicle, hygiene disposable penetration rates, and dual carbon enforcement intensity. Forecast inputs included PTA price correlation coefficients and REACH substance restriction implementation timelines.
The model holds under stable paraxylene feedstock pricing and gradual REACH enforcement; deviation in crude volatility spikes or accelerated SVHC candidate list expansion would shift volume toward chemical recycling pathways. Practitioners should monitor ECHA rolling updates and China GB standard revision announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Rayon Fibers Market
Synthetic Fibers
Global Synthetic Spider Silk Market
Synthetic Fibers
Synthetic Textile Fiber Market
Synthetic Fibers
Fiber Blends Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
Polyester Tire Cord Fabrics Market
Synthetic Fibers
Carbon Fiber Strands Market
Synthetic Fibers
North America High Performance Fibers Market
Synthetic Fibers
High-Strength Polyester Thread Market
Synthetic Fibers
Textile Fibers Market
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
Polyester Fibers Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Melt Spun Fibers Market
Synthetic Fibers
Asia-Pacific Aramid Fiber Market