
 Middle-East and Africa Aramid Fiber Market | 2026-2036
Middle-East and Africa Aramid Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Aramid Fiber Market Foresight
Modular composite panel bundling is recalibrating buyer choice across the Middle-East and Africa aramid fiber market, as procurement teams shift from commodity yarn purchasing to integrated subsystem contracts. DuPont leverages its upstream polymerization capabilities to anchor premium para-aramid supply into Gulf aerospace tier-one programs. Teijin Aramid competes through specialized meta-aramid formulations targeting Saudi electrical infrastructure retrofit cycles. Kolon Industries Inc extends its position via distributor partnerships that control channel access across North African military textile markets.
Aramid fibers are synthetic aromatic polyamides characterized by high tensile strength-to-weight ratios, thermal stability exceeding 400°C decomposition thresholds, and inherent flame resistance without halogenated additives; manufacturers spin para-aramid variants from liquid-crystal p-phenylene terephthalamide solutions to yield rigid molecular chains optimized for ballistic protection and tension-bearing composites. Para-Aramid commands the dominant value share in regional military and aerospace procurement, while Meta-Aramid captures margin pools in electrical insulation and industrial filtration where thermal endurance requirements exceed mechanical load demands. Composites as a form category outpaces textile growth, driven by Gulf state investments in lightweight pressure vessel fabrication for hydrogen and natural gas transport infrastructure.
Saudi Arabia's SFDA enforces personal protective equipment certification aligned with EU MDR technical benchmarks, compelling imported aramid garments to meet dual conformity assessment protocols. UAE's MOHAP and South Africa's national standards body coordinate flame-retardant material specifications for hydrocarbon sector workforce safety, creating regulatory pull for certified meta-aramid textiles. Stakeholders must monitor evolving Gulf Cooperation Council harmonization talks on chemical substance registration, as divergent national implementation timelines risk fragmenting product compliance pathways and locking in country-specific supply arrangements.
Market Dynamics
Modular composite panel bundling is recalibrating buyer choice across the Middle-East and Africa aramid fiber market, as procurement teams shift from commodity yarn purchasing to integrated subsystem contracts. DuPont leverages its upstream polymerization capabilities to anchor premium para-aramid supply into Gulf aerospace tier-one programs. Teijin Aramid competes through specialized meta-aramid formulations targeting Saudi electrical infrastructure retrofit cycles. Kolon Industries Inc extends its position via distributor partnerships that control channel access across North African military textile markets.
Growth Catalysts
- SFDA PPE mandates:Saudi Arabia's personal protective equipment certification aligned with EU MDR technical benchmarks compels imported aramid garments to meet dual conformity assessment protocols, expanding certified product demand.
- Refinery modernization:Saudi Arabia's Eastern Province petrochemical corridor drives bulk para-aramid uptake for protective equipment and filtration systems as downstream chemical expansion accelerates.
- Hydrogen transport infrastructure:Gulf state investments in lightweight pressure vessel fabrication for hydrogen and natural gas transport infrastructure outpace textile growth in the composites form category.
Market Restraints
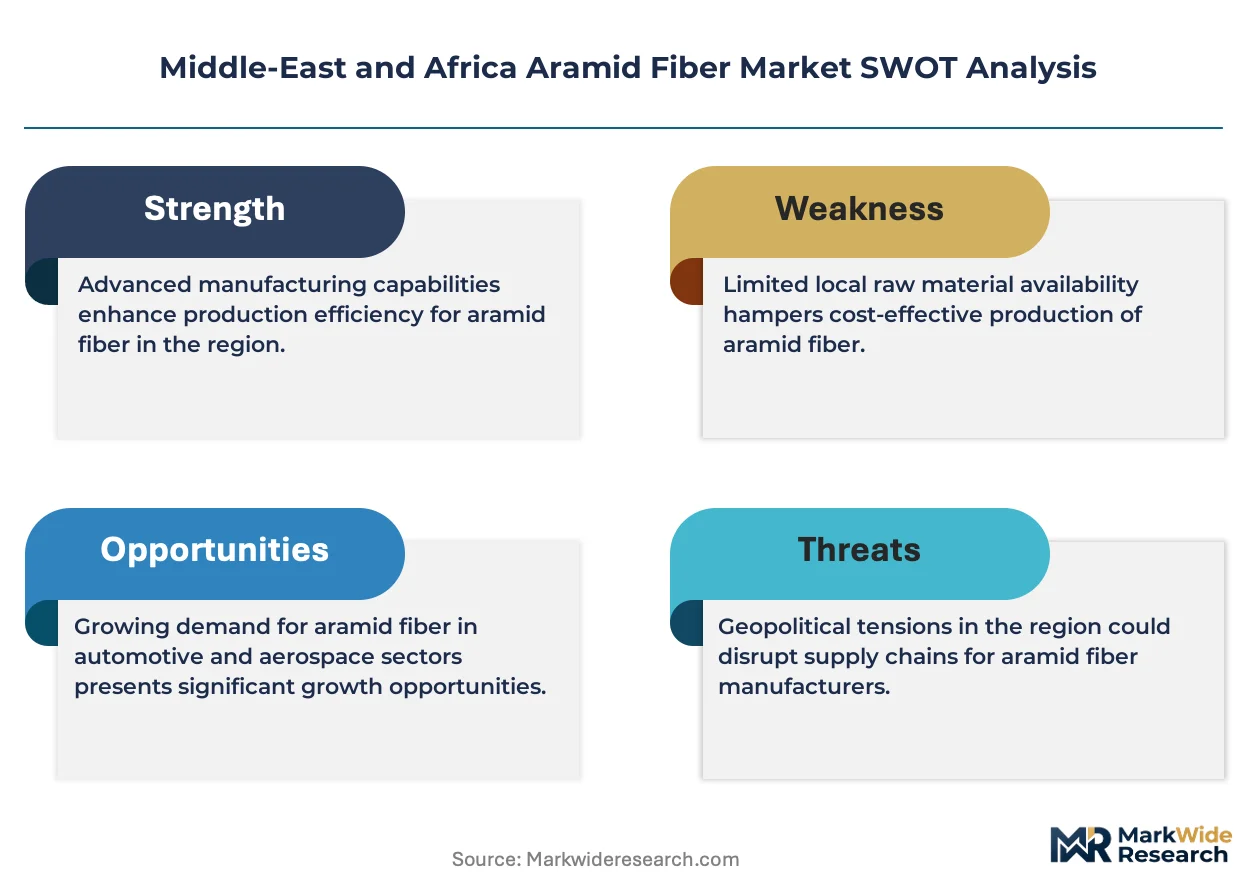
- Acrylonitrile price volatility:Feedstock cost fluctuations for the primary precursor to aramid polymers compress margin predictability for regional converters operating on fixed-price municipal contracts.
- Single-source polymer dependency:Concentrated para-aramid polymer supply from North American and European producers exposes MEA fabricators to extended lead times and currency mismatch risks.
- UHMWPE substitution in ballistics:Ultra-high molecular weight polyethylene fibers capture select military procurement slots where weight reduction outweighs thermal performance requirements.
Strategic Opportunities
- Egyptian military textile modernization:Underpenetrated North African defense procurement channels present first-mover positioning for certified meta-aramid suppliers establishing local finishing partnerships.
- MOHAP-MOHAP coordination:UAE and Saudi flame-retardant material specification harmonization creates regulatory tailwind for dual-certified product platforms spanning both markets.
- Smart textile integration:Convergence of conductive fiber weaving with aramid substrates enables next-generation industrial monitoring garments for Abu Dhabi offshore platform workforces.
Industry Challenges
- Polymerization technician scarcity:Specialized wet-spinning process engineering expertise remains concentrated in European and East Asian training pipelines, constraining regional production scale-up timelines.
- Dual certification complexity:EU MDR and Gulf national standards body parallel assessment requirements extend product approval cycles for protective equipment entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Aramid Fiber Market |
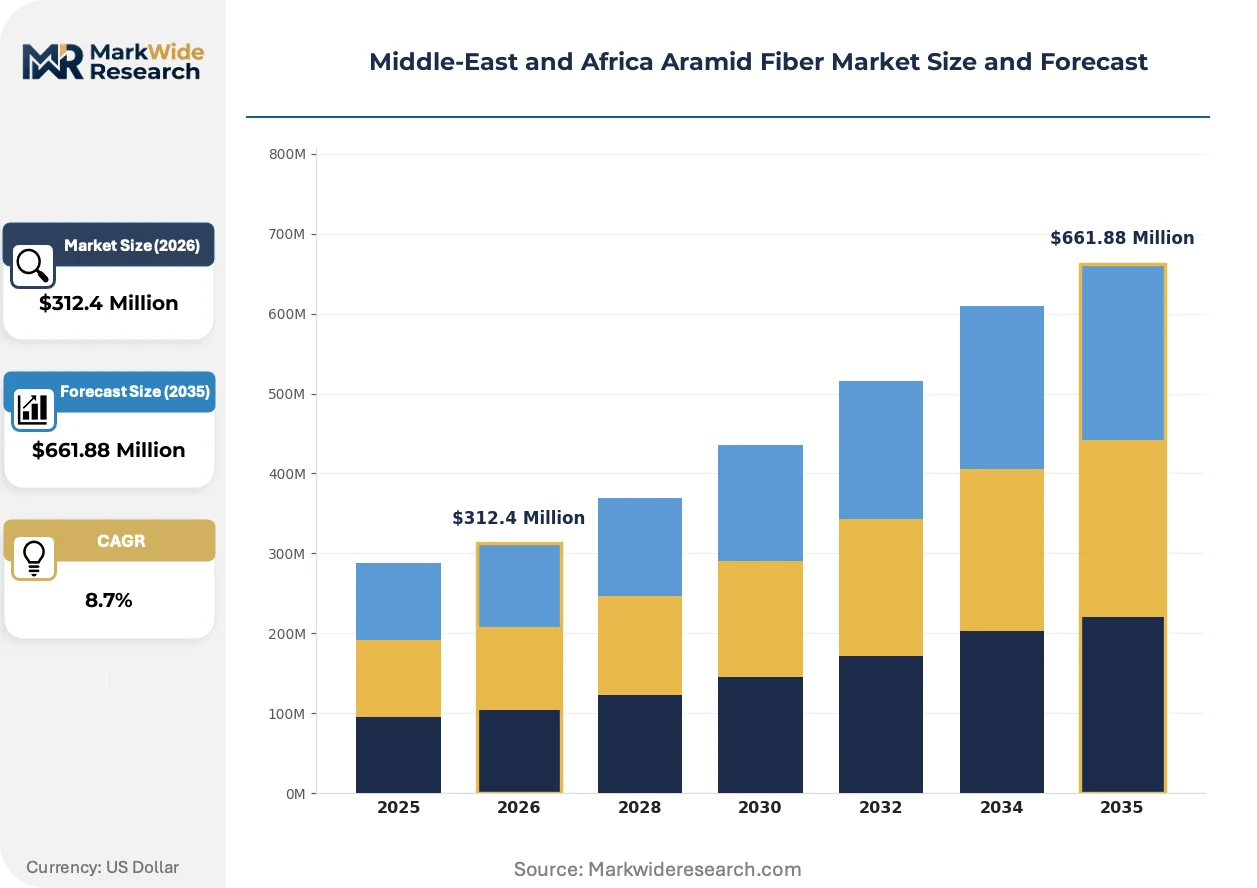
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meta-Aramid, Para-Aramid, Blends, Others End Use Industry: Aerospace, Automotive, Military, Electrical Form: Textiles, Composites, Films, Paper Distribution Channel: Direct, Distributors, Online, Retail |
| Companies Covered | Hyosung, YF International bv, DuPont, Taekwang Industrial, Kermel, Teijin Aramid, Kolon Industries Inc, Huvis Corp, Toray Industries Inc, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Aramid Fiber Market Shifts & Advancements
Aramid fiber processing is pivoting toward integrated composite subsystem supply, compressing traditional yarn-trading margins while elevating technical service capabilities as the primary competitive differentiator across Middle-East and Africa procurement channels.
Multi-axial non-crimp fabric technology is consolidating position in Gulf aerospace manufacturing, replacing hand-layup prepreg methods with automated fiber placement compatibility. Emirates aerostructures suppliers and Saudi Arabian Military Industries tier-one partners are qualifying these engineered fabrics for thermal shielding applications. This consolidation is compressing the supplier base toward polymerization-integrated converters capable of delivering bonded panel assemblies rather than raw reinforcement materials.
MOHAP and South Africa's national standards body coordinate flame-retardant material specifications for hydrocarbon sector workforce safety, creating regulatory pull for certified meta-aramid textiles. Industrial consequence includes mandatory third-party testing for all imported protective garments entering UAE refinery and petrochemical facilities. Saudi Arabia's Eastern Province operators and Abu Dhabi National Oil Company subsidiaries are most affected, responding by pre-qualifying suppliers against dual UAE-Saudi certification benchmarks to streamline cross-border deployment.
Integrated subsystem contracting is displacing commodity yarn purchasing across Gulf Cooperation Council procurement desks, with buyers consolidating spend around composite panel fabricators rather than fiber distributors. DuPont and Teijin Aramid direct sales teams are capturing these consolidated contracts, while traditional regional distributors face margin compression. This pattern is most visible in Saudi Arabia's aerospace tier-one programs and UAE hydrogen transport infrastructure tenders, where technical service integration outweighs unit price in supplier selection criteria.
Middle-East and Africa Aramid Fiber Market Segmentation
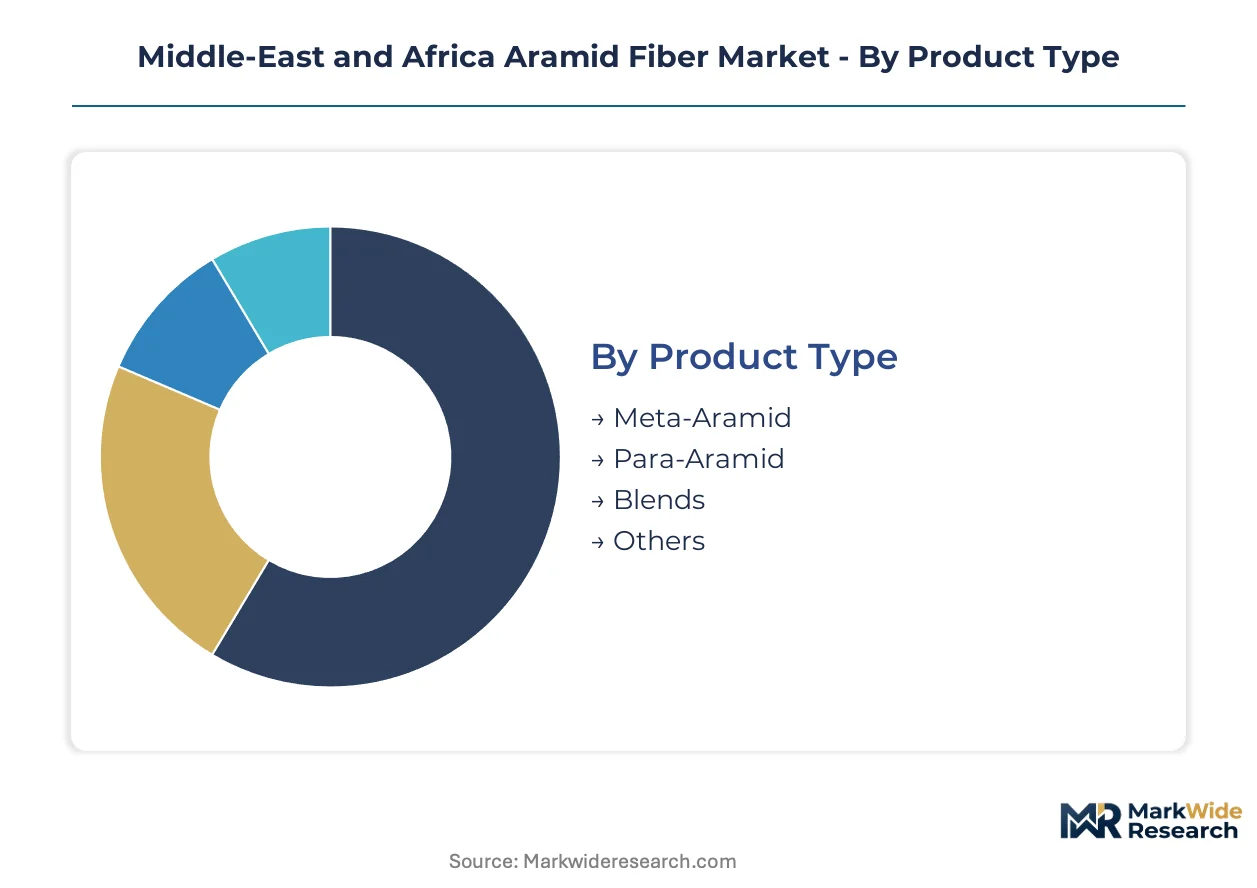
Segmentation in the Middle-East and Africa aramid fiber market reveals divergent certification burdens across product categories. SFDA and MOHAP mandates create tiered compliance costs that reshape competitive positioning within each segment boundary.
Product Type:
Certification requirements fragment sharply across polymer chemistry, with para-aramid facing ballistic-grade testing protocols while meta-aramid navigates electrical insulation standards under Gulf national regulations.
- Para-Aramid:Rigid molecular chains spun from liquid-crystal p-phenylene terephthalamide solutions deliver tensile strength-to-weight ratios exceeding steel. Saudi Arabia's Eastern Province petrochemical corridor drives bulk uptake for refinery protective equipment and filtration systems as downstream chemical expansion accelerates.
- Meta-Aramid:Flexible aromatic polyamide structures withstand thermal decomposition beyond 400°C without halogenated additives. UAE MOHAP flame-retardant mandates for hydrocarbon processing facilities pull certified textile demand through Abu Dhabi National Oil Company supply chains.
- Blends:Hybrid formulations combining aramid with carbon or glass fibers optimize cost-performance for North African military textile procurement.
- Others:Specialty aromatic copolymers address niche aerospace thermal shielding applications in Gulf Cooperation Council tier-one programs.
Leading the category by volume: Para-Aramid. Growing fastest: Meta-Aramid.
End Use Industry:
Application-specific performance thresholds determine polymer selection, with aerospace and military procurement commanding premium grades while electrical infrastructure retrofit cycles favor cost-optimized alternatives.
- Military:Ballistic protection systems require para-aramid composites meeting multi-hit penetration resistance standards. Egyptian defense procurement channels present first-mover positioning for certified suppliers establishing local finishing partnerships.
- Aerospace:Thermal shielding applications in Gulf OEM programs demand polymerization-integrated supply with automated fiber placement compatibility. Emirates aerostructures suppliers and Saudi Arabian Military Industries partners drive multi-axial non-crimp fabric qualification.
- Automotive:Lightweight pressure vessel fabrication for hydrogen transport infrastructure concentrates demand in UAE and Saudi Arabia.
- Electrical:Insulation retrofit cycles in Saudi grid infrastructure favor meta-aramid formulations with established Gulf standards body certification.
Highest margin concentration: Aerospace. Steepest expansion trajectory: Hydrogen transport applications within Automotive.
Form:
Processing depth determines value capture, with raw textiles facing margin compression while bonded composite panel assemblies consolidate procurement spend around technical service capabilities.
- Composites:Integrated subsystem contracts displace commodity yarn purchasing across Gulf Cooperation Council procurement desks. DuPont and Teijin Aramid direct sales teams capture consolidated aerospace and hydrogen infrastructure tenders where technical integration outweighs unit price.
- Textiles:Woven and non-woven fabrics for protective garments face dual EU MDR and Gulf national standards body assessment requirements extending approval cycles.
- Films:Thin-gauge aromatic polyamide substrates serve electrical insulation applications in Saudi grid modernization programs.
- Paper:Cellulose-aramid hybrid structures address filtration media for refinery process streams in the Eastern Province corridor.
Dominant value share: Composites. Fastest volume climb: Textiles under SFDA PPE mandate enforcement.
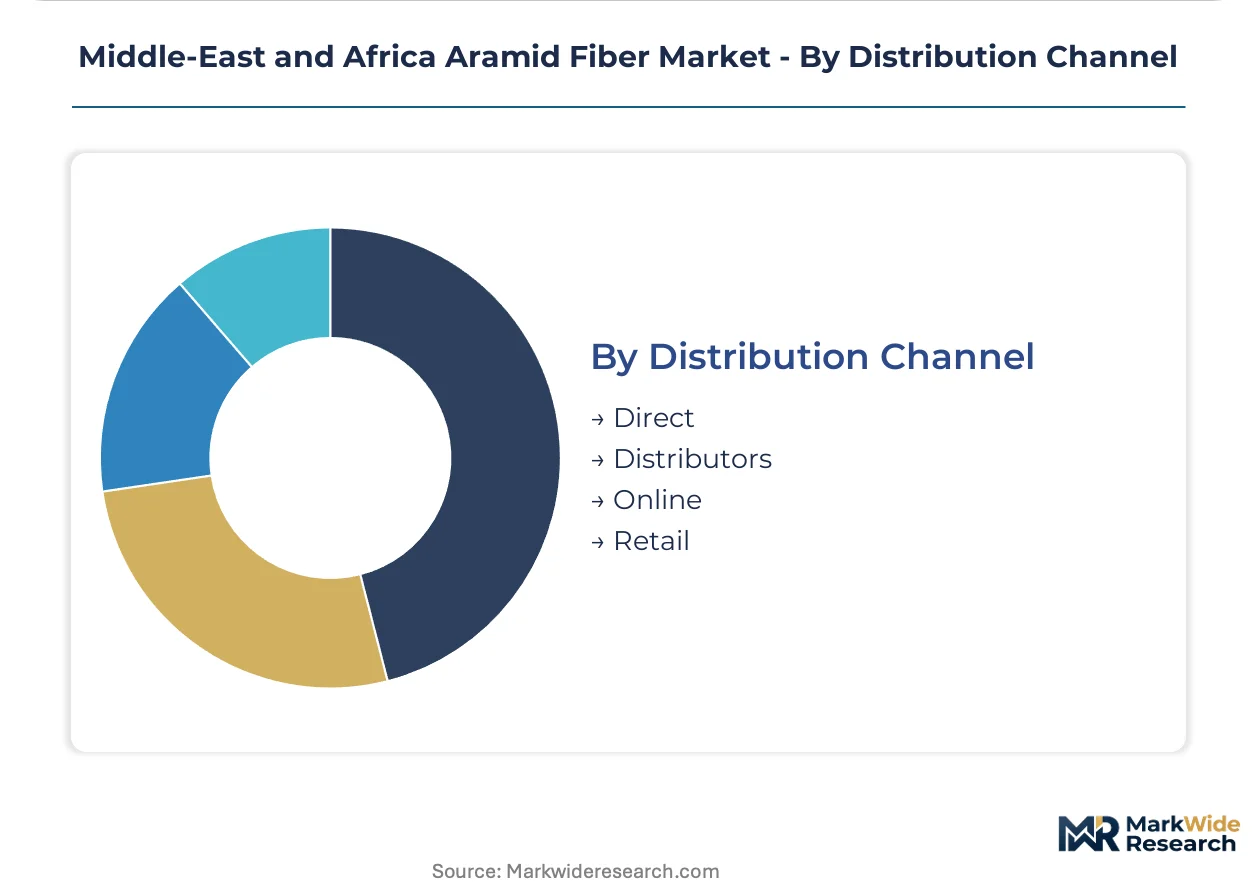
Distribution Channel:
Channel structure reflects buyer consolidation patterns, with tier-one programs bypassing traditional distributors while military textile markets retain intermediary control.
- Direct:Polymerization-integrated manufacturers anchor premium para-aramid supply into Gulf aerospace programs and hydrogen transport tenders. DuPont leverages upstream capabilities; Teijin Aramid fields specialized formulation teams.
- Distributors:Channel partnerships control access across North African military textile markets where Kolon Industries extends position via regional intermediaries.
- Online:Digital procurement platforms serve small-volume industrial maintenance orders with limited technical service requirements.
- Retail:Point-of-sale availability concentrates in urban PPE suppliers serving construction and logistics workforces in Dubai and Riyadh.
Procurement consolidation favors: Direct. Distributor-dependent markets: North African defense textiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City and the Ras Al Khair Industrial City anchor aramid fiber demand concentration through petrochemical cluster proximity and aerospace supply chain incentives. These zones concentrate procurement spend around integrated composite subsystem suppliers rather than commodity distributors.
Saudi Arabia
Eastern Province petrochemical corridor drives bulk para-aramid uptake for refinery protective equipment and filtration systems. SFDA personal protective equipment certification aligned with EU MDR technical benchmarks compels dual conformity assessment protocols for imported garments. Ras Al Khair Industrial City hosts downstream chemical expansion projects that accelerate aramid composite procurement for pressure vessel fabrication.
United Arab Emirates
MOHAP flame-retardant material specifications for hydrocarbon sector workforce safety pull certified meta-aramid textile demand through Abu Dhabi National Oil Company supply chains. Abu Dhabi National Oil Company subsidiaries pre-qualify suppliers against dual UAE-Saudi certification benchmarks to streamline cross-border deployment. Dubai's aerospace tier-one programs consolidate procurement spend around polymerization-integrated converters capable of delivering bonded panel assemblies.
South Africa
National standards body coordination with UAE MOHAP on flame-retardant specifications creates regulatory pull for certified meta-aramid textiles in hydrocarbon processing. Industrial filtration retrofit cycles in Sasol's Secunda coal-to-liquids complex favor established Gulf-certified suppliers. Johannesburg-Pretoria corridor distributors control channel access for protective garment imports serving mining and petrochemical workforces.
Egypt
Underpenetrated North African defense procurement channels present first-mover positioning for certified meta-aramid suppliers establishing local finishing partnerships. Military textile modernization programs prioritize dual-certified product platforms spanning Gulf and European specifications. Cairo-Alexandria industrial zone concentration enables regional distribution hub development for North African military markets.
Middle-East and Africa Aramid Fiber Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across polymer chemistry and composite fabrication tiers. Market structure tilts toward polymerization-integrated manufacturers anchoring premium supply into aerospace and hydrogen infrastructure programs. Three archetypes dominate: upstream polymer producers with direct sales teams, regional distributors controlling military textile channel access, and composite subsystem fabricators capturing integrated contracts. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with technical service capabilities outweighing unit price in supplier selection criteria.
Within the polymerization-integrated tier, DuPont and Teijin Aramid exemplify upstream-controlled supply anchoring into Gulf aerospace tier-one programs and hydrogen transport tenders. Kolon Industries Inc occupies a distributor-dependent position extending channel access across North African military textile markets where intermediary control persists.
| Leading Market Players |
|---|
| Hyosung |
| YF International bv |
| DuPont |
| Taekwang Industrial |
| Kermel |
| Teijin Aramid |
| Kolon Industries Inc |
| Huvis Corp |
| Toray Industries Inc |
| Others |
Supply & Pricing Matrix
Specialized wet-spinning process engineering expertise concentrated in European and East Asian training pipelines drives labor-cost differentials that widen pricing-tier spreads across the Middle-East and Africa aramid fiber market. SFDA and MOHAP dual certification requirements compound these spreads by embedding compliance premiums into Gulf-procured grades.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premiums while spot inventory trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates polymerization-integrated aerospace grades from distributor-channel industrial textiles and uncommitted spot volumes. Price differentiation hinges on EU MDR certification status and volume scale, with bulk para-aramid contracts for Saudi refinery operators commanding stability while spot meta-aramid faces softness from acrylonitrile feedstock volatility. Small-volume industrial maintenance buyers exhibit highest price sensitivity; Gulf aerospace tier-one programs demonstrate lowest.
Supply Chain Analysis
Freight costs from North American and European polymerization centers amplify landed costs for MEA fabricators operating on fixed-price municipal contracts. Geographic supply concentration centers on the United States, the Netherlands, and Japan for para-aramid polymer feedstock. Raw material dependencies rest on acrylonitrile, p-phenylene diamine, and terephthaloyl chloride precursors. Single-source polymer vulnerability from concentrated upstream producers exposes regional converters to currency mismatch risks. Distribution runs through direct sales teams for aerospace and hydrogen infrastructure, while North African military textiles retain distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where SFDA personal protective equipment certification aligned with EU MDR technical benchmarks erects barrier-to-entry moats favoring pre-certified incumbents.
For Market Incumbents: Anticipate UHMWPE substitution pressure in ballistic applications by deepening captive supply of para-aramid polymer and anchoring premium grades into Gulf hydrogen transport infrastructure tenders. SFDA-MOHAP harmonization talks demand proactive certification investment to lock in dual-market positioning before regulatory fragmentation solidifies. For New Entrants and Emerging Players: Enter via Egyptian military textile modernization programs where underpenetrated defense procurement channels reward first-mover local finishing partnerships. North African defense textiles represent the most penetrable geography; go-to-market execution should prioritize distributor alliances controlling channel access across Cairo-Alexandria industrial zone concentration. For Investors and Strategic Acquirers: The window for entry favors polymerization-integrated mid-cap specialists with established Gulf aerospace qualifications and latent capacity for meta-aramid formulation expansion. Long-term viability centers on technical service capabilities rather than commodity volume positioning. Monitor MOHAP-SFDA certification benchmark convergence as the inflection signal for scalable dual-market product platform deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymerization | Captive p-phenylene terephthalamide supply secures margin control for Gulf aerospace tier-one programs. |
| Dual Certification Investment | EU MDR plus SFDA alignment streamlines cross-border deployment across Saudi-UAE procurement corridors. |
| Local Finishing Partnership | Egyptian military textile hub development captures North African defense channel access from regional distributors. |
| Composite Subsystem Contracting | Integrated panel assembly supply displaces commodity yarn purchasing in Abu Dhabi hydrogen infrastructure tenders. |
| Smart Textile R&D Partnership | Conductive fiber weaving convergence enables next-generation industrial monitoring garments for offshore platforms. |
Research Methodology
Independent corroboration across primary interviews with polymerization plant managers, aerospace procurement leads at Gulf tier-one suppliers, protective equipment regulatory affairs directors, and North African military textile distributors underwrites the qualitative findings. Secondary validation draws from customs and trade data, SEC 10-K filings of listed chemical conglomerates, Gulf national standards body regulatory filings, and aerospace supply chain disclosure documents. Bottom-up volume modeling triangulates against top-down macroeconomic absorption rates.
Rate-of-change decomposition across the analysis window segments demand trajectories by polymer chemistry, end-use industry, processing form, and regional regulatory cluster. CAGRs derive from segment-level volume build-ups calibrated to named project pipelines and procurement disclosure patterns. Forecast inputs incorporate SFDA enforcement timeline assumptions and Gulf hydrogen infrastructure capex commitment visibility.
Forecast precision tightens around the base case; tail outcomes carry wider variance under acrylonitrile price volatility extremes and Gulf Cooperation Council regulatory harmonization failure scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Europe Aramid Fiber Market
Synthetic Fibers
Clothing Fibers Market
Synthetic Fibers
Synthetic Fiber Market
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
Polyester Straps Market
Synthetic Fibers
Conductive Fibers Market
Synthetic Fibers
Fiberglass Roving Market
Synthetic Fibers
Rayon Fibers Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Polyimide Fiber Market
Synthetic Fibers
Synthetic Sewing Thread Market
Synthetic Fibers
Designer Fiber Market
Synthetic Fibers
Global Lyocell Fibers Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Polyester Strap for Manual Grade Market