
 Polyester Filament Market | 2026-2036
Polyester Filament Market Size, Share, and Industry Trends Forecast 2026-2036
Polyester Filament Market Outlook
OEKO-TEX Standard 100 certification is rotating competitive access across the polyester filament supply base, filtering out smaller spinners lacking testing infrastructure. Indorama Ventures leverages its integrated PET resin-to-filament chain to sustain cost positions in Southeast Asian markets. Toray Industries anchors premium industrial filament supply through advanced polymerization technology in Japan and Thailand. Reliance Industries dominates South Asian feedstock access with its captive PTA and MEG production at Jamnagar.
Polyester filament comprises continuous extruded synthetic fibers spun from polyethylene terephthalate (PET) polymer, typically ranging from 50 to 300 denier with tenacity values of 4.5–8.0 grams per denier depending on draw ratio and thermal treatment. These filaments serve as structural inputs for woven and knitted fabrics, tire cord, seat belts, and filtration media where dimensional stability and chemical resistance outweigh natural fiber limitations. POY and FDY grades concentrate margin capture in apparel and home textile channels where downstream weaving efficiency depends on uniform dye uptake and low broken-filament rates. DTY volumes are accelerating in automotive upholstery and travel gear as stretch-recovery specifications tighten across OEM supplier manuals. Monofilament and multifilament forms diverge in equipment compatibility, with multistrand constructions commanding technical premiums in industrial belting and composite reinforcement.
REACH compliance in Europe and the EU Green Deal's carbon border adjustment mechanisms are elevating traceability requirements for PET feedstock origins, compelling Asian exporters to document recycled content percentages. China's GB standards for chemical fiber industry emissions and India's BIS quality certification for textile filaments are tightening product specifications in the two largest production geographies. Stakeholders must monitor how diverging national carbon accounting rules reshape cost competitiveness between virgin and chemically recycled filament routes.
Market Dynamics
China's dual carbon goals and tightening MEE emissions protocols are forcing filament spinners to reconfigure feedstock sourcing, redirecting capital toward chemically recycled PET and bio-based alternatives while raising entry barriers for smaller producers.
Growth Catalysts
- Automotive upholstery specifications:OEM supplier manuals in Germany, Japan, and the United States are mandating higher tenacity DTY grades for seat fabrics and interior panels, pulling filament volumes into transportation end-uses.
- REACH traceability mandates:ECHA documentation requirements for recycled content percentages are creating certified supply premiums that reward early movers with integrated resin-to-filament operations.
- India's PLI scheme for textiles:Production-linked incentives for man-made fiber manufacturing are absorbing capacity migration from China's Zhejiang belt, expanding South Asian filament output.
Market Restraints
- PTA and MEG price volatility:Purified terephthalic acid and monoethylene glycol feedstock costs oscillate with crude oil futures, compressing spinner margins when downstream textile buyers resist pass-through.
- Single-region supply concentration:China's Jiangsu and Zhejiang provinces host over sixty percent of global POY and FDY spinning capacity, exposing buyers to concentrated logistics disruption risks.
- Natural fiber substitution in premium apparel:Merino wool and organic cotton are reclaiming share in outerwear and base-layer segments where moisture management and tactile properties outweigh polyester durability.
Strategic Opportunities
- Vietnam's accelerating textile exports:Free trade agreements with the European Union and United Kingdom are positioning Vietnamese weavers as near-shore alternatives, creating filament demand from first-tier suppliers.
- Ocean-bound plastic feedstock certification:Third-party verification of maritime plastic recovery is enabling premium pricing in European home textile channels where sustainability claims require documentary proof.
- Digital textile printing compatibility:Low-warp filament constructions that accept reactive dyes without pretreatment are capturing share from conventional screen-printed fabrics in fast-fashion supply chains.
Industry Challenges
- OEKO-TEX Standard 100 testing infrastructure:Smaller spinners in Bangladesh and Pakistan lack in-house toxicology laboratories, forcing expensive third-party certification that delays market access by four to six months.
- Melt-spinning equipment reconfiguration:Shifting from virgin to chemically recycled PET requires screw and filter modifications that idle production lines for three to four weeks, eroding quarterly output targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyester Filament Market |
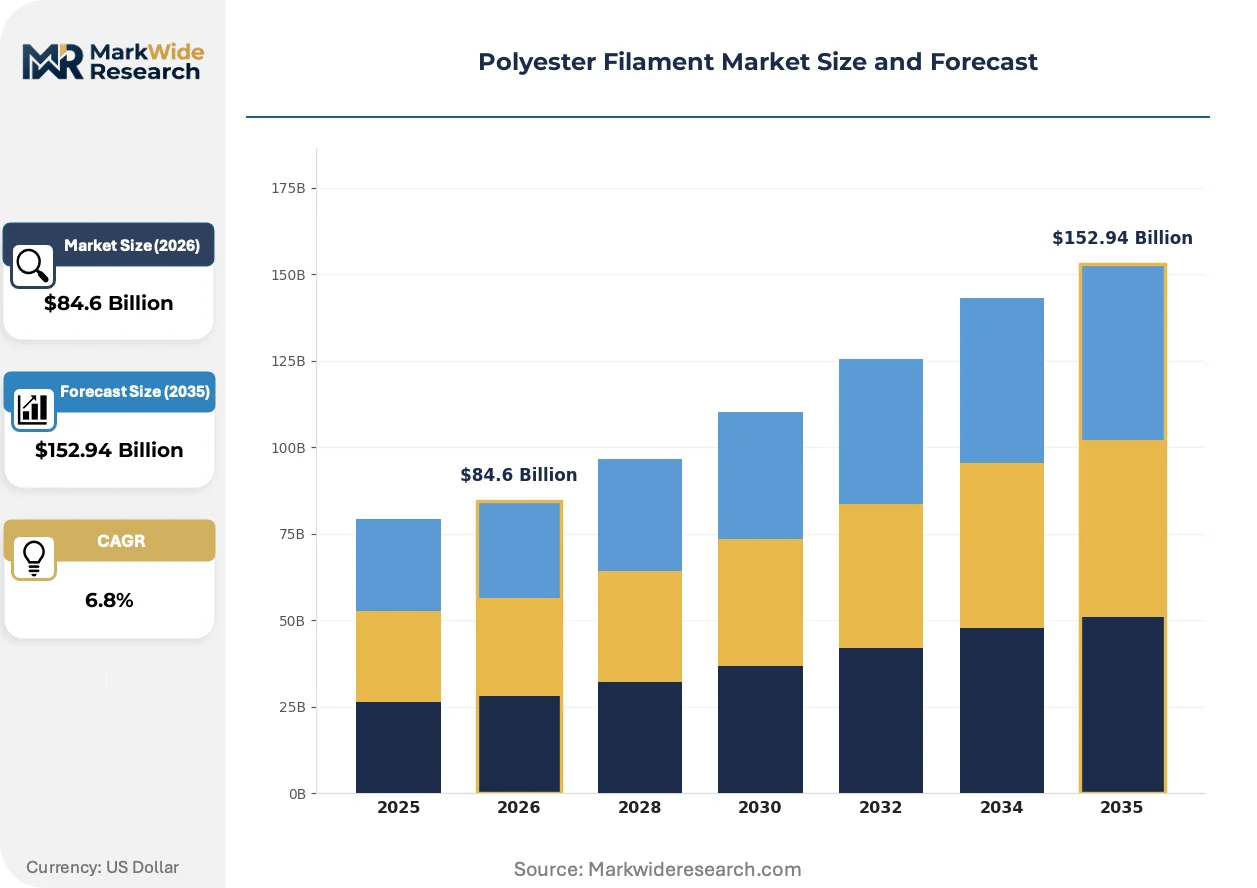
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $152.94 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: POY, FDY, DTY, Other End User: Textiles, Automotive, Industrial, Consumer Goods Application: Clothing, Upholstery, Filtration, Travel Gear Form: Monofilament, Multifilament, Bristle, Other |
| Companies Covered | Zhejiang Hengyi Group Co., Ltd., Indorama Ventures, Xin Feng Ming Group, Toray Industries, Reliance Industries, Hengli Group Co., Ltd., Jiangsu Eastern Shenghong Co., Ltd., Teijin Limited, Tongkun Holding Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyester Filament Market Strategic Shifts
Polymerization and spinning technologies are converging with digital traceability systems, compressing development cycles and enabling mass-customization of filament specifications for niche industrial applications.
Bi-component sheath-core filament architectures are miniaturizing denier ranges while maintaining thermal bonding performance, enabling lighter nonwoven substrates for hygiene and filtration. Medical gown manufacturers in the United States are adopting these constructions to replace spunbond-meltblown-spunbond laminates. The technology is miniaturizing equipment footprints required for high-loft thermal insulation production.
China's evolving GB standards for chemical fiber industry emissions are mandating closed-loop cooling and solvent recovery systems that raise capital intensity for new capacity. Spinners in Sichuan and Fujian provinces are retrofitting existing lines to avoid production suspensions. The industrial filament segment faces the steepest compliance costs due to higher throughput volumes and waste generation rates.
Direct-to-mill procurement platforms are compressing traditional distributor layers, allowing woven fabric manufacturers to specify denier, tenacity, and dye uptake parameters through digital interfaces. Turkish denim weavers are piloting these systems to reduce inventory carrying costs and match filament lots to specific loom configurations. The shift is most visible in mid-volume apparel channels where order fragmentation exceeds distributor stocking capabilities.
Polyester Filament Market Segmentation
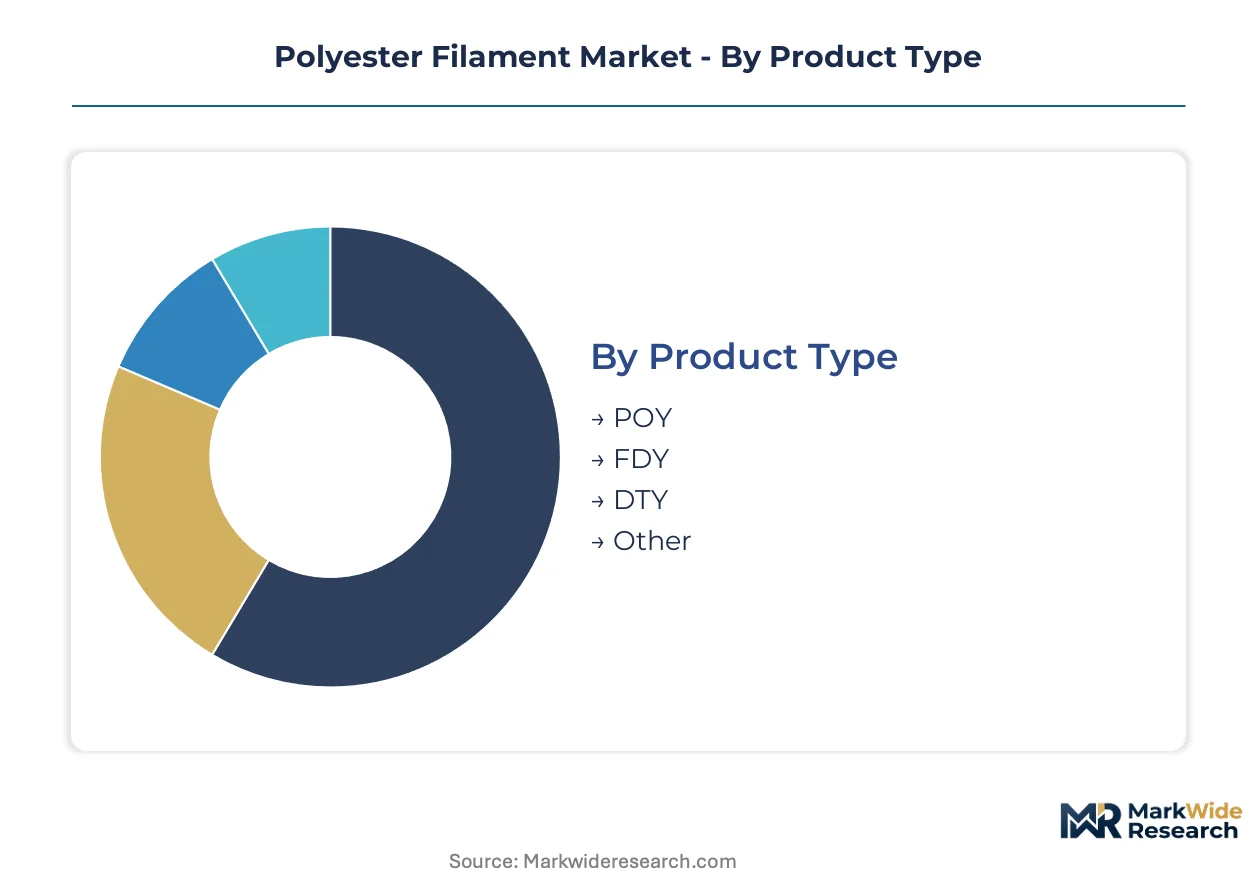
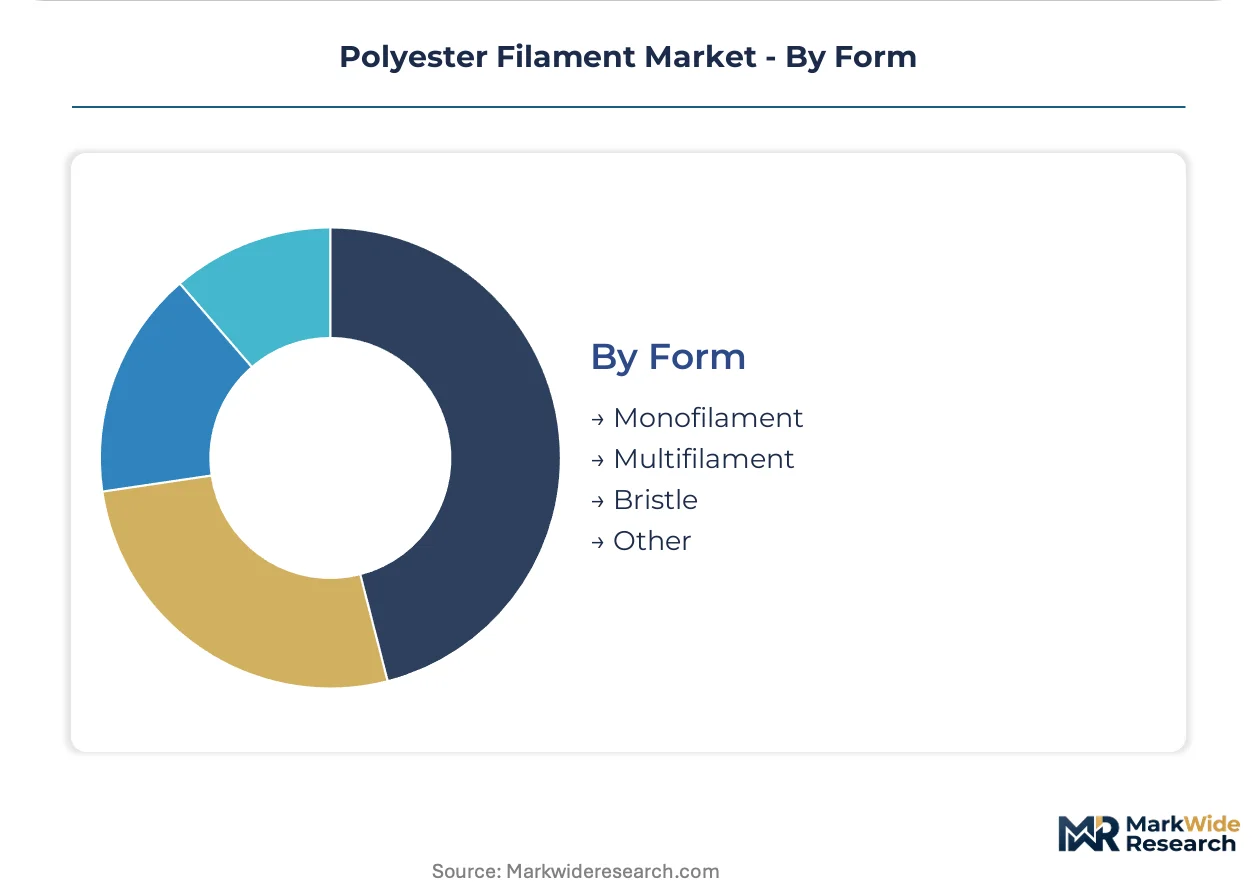
Segmentation in polyester filament markets reveals how margin capture concentrates around processing technology, end-use performance specifications, and form factor compatibility. Spinners align capital allocation with the segments where technical differentiation commands sustainable pricing power.
Product Type:
Margin pools concentrate in draw-textured and fully-drawn grades where downstream weaving efficiency depends on uniform dye uptake and low broken-filament rates.
- POY:Partially oriented yarn serves as a feedstock intermediate for subsequent draw-texturing operations, with demand concentrating in China's Zhejiang and Jiangsu corridors where integrated spin-texture operations minimize handling costs. The grade faces margin pressure from overcapacity in virgin PET spinning.
- FDY:Fully drawn yarn eliminates separate texturing steps for apparel and home textile weavers, capturing premium positioning in Turkey's denim sector where digital procurement platforms specify tenacity and dye uptake parameters. High capital intensity in spin-draw equipment limits new entrant participation.
- DTY:Automotive upholstery programs in Germany, Japan, and the United States mandate higher tenacity DTY grades for seat fabrics and interior panels.
- Other:Specialty partially-oriented and fully-drawn variants serve niche industrial belting and composite reinforcement channels.
The dominant share belongs to FDY, while DTY is closing the gap fastest on automotive specification tightening.
End User:
Application-driven volume splits reveal where specification complexity creates defensive market positions.
- Textiles:Woven and knitted fabric production consumes the majority of POY and FDY volumes, with demand fragmenting across fast-fashion supply chains in Vietnam and Bangladesh where OEKO-TEX certification requirements filter out smaller spinners lacking testing infrastructure.
- Automotive:OEM supplier manuals mandate DTY grades with precise stretch-recovery specifications for seat fabrics and interior panels, creating technical barriers that sustain margin premiums for qualified suppliers.
- Industrial:Tire cord, seat belts, and filtration media require dimensional stability and chemical resistance.
- Consumer Goods:Travel gear and luggage manufacturers specify abrasion-resistant filament constructions.
Textiles maintains volume leadership, though automotive is expanding most quickly on upholstery program growth.
Application:
Performance requirements diverge sharply between aesthetic-driven and functional-driven end-uses.
- Clothing:Apparel channels prioritize uniform dye uptake and low broken-filament rates for downstream weaving efficiency, with digital textile printing compatibility emerging as a selection criterion in fast-fashion supply chains.
- Upholstery:Furniture and automotive seating applications demand higher tenacity DTY grades with precise stretch-recovery specifications, concentrating procurement among first-tier suppliers with certified quality systems.
- Filtration:Industrial and medical filtration media require chemical resistance and dimensional stability.
- Travel Gear:Luggage and backpack manufacturers specify abrasion-resistant constructions.
Clothing retains the largest position, while upholstery is climbing the fastest on automotive program expansion.
Form:
Equipment compatibility and construction geometry determine addressable market scope.
- Monofilament:Single-strand extrusions serve fishing line, surgical suture, and filtration mesh applications where precise diameter control and surface smoothness outweigh multistrand flexibility, commanding technical premiums in medical device manufacturing.
- Multifilament:Bundled fiber constructions dominate woven and knitted fabric production, with denier ranges from 50 to 300 accommodating diverse loom configurations and downstream processing requirements.
- Bristle:Stiff monofilament variants serve brush and broom manufacturing.
- Other:Specialty forms including hollow and profiled cross-sections target thermal insulation and moisture-wicking applications.
Multifilament holds the dominant share, while monofilament is gaining share fastest on medical and industrial specification tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for textiles is absorbing capacity migration from China's Zhejiang belt, while Vietnam's free trade agreements with the European Union and United Kingdom are positioning Vietnamese weavers as near-shore alternatives. Germany's automotive OEM supplier manuals mandate higher tenacity DTY grades for seat fabrics, pulling filament volumes into transportation end-uses. China's dual carbon goals and tightening MEE emissions protocols are redirecting capital toward chemically recycled PET feedstock investments.
China
Automotive upholstery programs and integrated PET resin-to-filament operations drive demand in Zhejiang and Jiangsu provinces. MEE emissions protocols and GB standards for chemical fiber industry emissions mandate closed-loop cooling and solvent recovery systems. Sichuan and Fujian spinners are retrofitting existing lines to avoid production suspensions.
India
Textile brands are diversifying sourcing beyond China's production belts, absorbing capacity in Maharashtra and Gujarat. The PLI scheme for man-made fiber manufacturing incentivizes domestic filament output expansion. Reliance Industries anchors South Asian feedstock access through captive PTA and MEG production at Jamnagar.
Vietnam
Free trade agreements with the European Union and United Kingdom accelerate textile exports, creating filament demand from first-tier suppliers. REACH traceability mandates from ECHA require documentation of recycled content percentages for European market access. Ho Chi Minh City and Hanoi corridors concentrate weaving operations for near-shore supply chains.
Germany
OEM supplier manuals mandate higher tenacity DTY grades for seat fabrics and interior panels, pulling filament volumes into transportation end-uses. EU Green Deal carbon border adjustment mechanisms elevate traceability requirements for PET feedstock origins. Stuttgart and Munich automotive clusters drive specification tightening across supplier networks.
Japan
Premium industrial filament supply anchors through advanced polymerization technology serving tire cord and filtration media applications. METI industrial standards and JIS certification requirements filter supplier participation in technical segments. Toray Industries maintains production concentration in domestic and Thai facilities for automotive and industrial channels.
Polyester Filament Market Competitive Environment
Player mix skews toward integrated petrochemical-to-textile conglomerates with captive resin production, creating tiered competitive access based on feedstock control and certification infrastructure. The structure concentrates margin capture among operators with in-house PTA and MEG supply, while smaller spinners face OEKO-TEX Standard 100 testing barriers. Two strategic archetypes dominate: integrated resin-to-filament chains that sustain cost positions through backward feedstock control, and premium industrial specialists commanding technical premiums through advanced polymerization technology. Dominant competitive moves include capacity expansion in Southeast Asian markets and strategic partnerships for chemically recycled PET feedstock sourcing.
Within the integrated conglomerate tier, Indorama Ventures and Reliance Industries exemplify archetypes built on captive resin production and geographic feedstock dominance. Toray Industries occupies a position among premium industrial specialists leveraging advanced polymerization capabilities. These three anchors represent how backward integration into petrochemical inputs and certification-ready testing infrastructure create defensive market positions against margin compression from feedstock volatility.
| Leading Market Players |
|---|
| Zhejiang Hengyi Group Co., Ltd. |
| Indorama Ventures |
| Xin Feng Ming Group |
| Toray Industries |
| Reliance Industries |
| Hengli Group Co., Ltd. |
| Jiangsu Eastern Shenghong Co., Ltd. |
| Teijin Limited |
| Tongkun Holding Group Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Chemically recycled PET feedstock substitution for virgin resin is redrawing supply geography toward Southeast Asian collection hubs while compressing pricing premiums that previously rewarded European sustainability claims. This input shift simultaneously elevates logistics costs from ocean-bound plastic certification networks and forces spinners to recalibrate contract structures around volatile rPET availability.
Pricing Analysis
Certification level creates the primary spread between OEKO-TEX Standard 100 verified filament and uncertified commodity grades, with REACH documentation requirements from ECHA layering additional premiums for European market access. Contract-based long-term offtake agreements dominate automotive upholstery channels where OEMs lock in tenacity specifications, while spot purchasing persists in apparel weaving where downstream buyers resist pass-through of PTA and MEG volatility. Price differentiation hinges on integrated resin-to-filament operations versus merchant feedstock dependence, with Reliance Industries and Indorama Ventures capturing margin stability that smaller spinners forfeit. Cost compression in standard-grade POY is intensifying because China's Zhejiang overcapacity outpaces demand absorption, making apparel weavers in Bangladesh and Vietnam the most price-sensitive buyers while automotive Tier 1 suppliers show lowest sensitivity due to specification-locked contracts.
Supply Chain Analysis
Port congestion at Shanghai and Ningbo is elevating inbound logistics costs for European and North American buyers dependent on Jiangsu and Zhejiang filament exports, with container availability swings amplifying working capital requirements. Supply concentrates in China, India, and Vietnam, with over sixty percent of global POY and FDY spinning capacity anchored in China's eastern provinces. Raw material dependencies rest on purified terephthalic acid from petrochemical complexes, monoethylene glycol from ethylene crackers, and increasingly post-consumer PET flake from maritime collection programs. Single-region supply concentration presents structural vulnerability to MEE emissions enforcement actions that trigger production suspensions. Distribution runs through integrated textile conglomerates with captive weaving operations, bypassing traditional distributor layers as direct-to-mill procurement platforms gain adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against bio-based polyamide and advanced natural fiber blends reclaiming share in premium outerwear and base-layer segments. Incumbents must navigate material substitution threats while reinforcing technical specification lock-in across automotive and industrial channels.
For Market Incumbents: Secure OEKO-TEX Standard 100 certification infrastructure ahead of evolving EU Green Deal traceability mandates, as smaller competitors in Bangladesh and Pakistan face six-month delays from third-party testing bottlenecks. Anchor backward integration into chemically recycled PET feedstock through partnerships with maritime plastic recovery certification programs, defending margin position against virgin resin volatility. Prioritize capacity retention in Thailand and Vietnam to maintain proximity to diverging textile brand sourcing strategies.
For New Entrants and Emerging Players: Differentiate on ocean-bound plastic feedstock certification for European home textile channels where sustainability claims command documentary premiums unavailable to incumbent virgin resin spinners. Target Vietnam's accelerating textile export corridor as the most penetrable geography, leveraging free trade agreements with the European Union and United Kingdom to bypass China's carbon border adjustment exposure. Pursue digital textile printing compatibility as the go-to-market angle, specifying low-warp filament constructions that reactive dyes accept without pretreatment.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap spinners in India's Maharashtra and Gujarat corridors that absorbed capacity migration under the PLI scheme but lack integrated resin supply. Long-term viability favors operators with captive PTA and MEG production and certification-ready testing infrastructure, positioning them to consolidate fragmented downstream weaving networks. Watch for ECHA documentation requirement enforcement as the inflection signal separating certified premium suppliers from commodity price-takers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Feedstock | Secures supply certainty against China's MEE emissions enforcement and virgin resin volatility. |
| OEKO-TEX Standard 100 Certification Investment | Unlocks European market access before smaller competitors clear testing backlogs. |
| Capacity Expansion in Vietnam | Captures filament demand from EU-UK free trade agreement textile export acceleration. |
| Long-term Supply Agreement with Automotive OEMs | Locks in DTY volume commitments as seat fabric specifications tighten across German and Japanese supplier manuals. |
| Joint Venture for Maritime Plastic Recovery Certification | Enables premium pricing in sustainability-verified European home textile channels. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with filament plant managers, procurement leads at downstream textile OEMs, distribution channel partners, and technical R&D directors; and secondary validation against customs and trade data, chemical industry association reports, SEC filings from listed petrochemical conglomerates, and regulatory submissions to ECHA and China's MEE. Bottom-up and top-down triangulation cross-checked capacity utilization estimates from provincial industry bureaus against demand projections from apparel and automotive end-use channels.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation dimensions spanning product type, end-use industry, application performance requirements, and regional production hub concentration. CAGRs were derived from regression analysis of historical filament consumption against downstream textile output indices and automotive production schedules, with specific inputs including Zhejiang and Jiangsu capacity expansion announcements and India's PLI scheme disbursement timelines.
The analysis sits within stated boundaries; outcomes outside sustained enforcement of China's dual carbon goals and MEE emissions protocols, or abrupt shifts in crude oil futures affecting PTA and MEG feedstock economics, would require recalibration. Forecasts reflect documented assumptions around recycled content adoption rates and trade agreement implementation timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Polyethylene Terephthalate (PET) Fiber Market
Synthetic Fibers
Polyester Straps Market
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
Monofilament Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Synthetic Sewing Thread Market
Synthetic Fibers
Spandex Market
Synthetic Fibers
High-Strength Polyester Thread Market
Synthetic Fibers
IMO Fiber Market
Synthetic Fibers
Blended Fibers Market
Synthetic Fibers
US Textile Market
Synthetic Fibers
Polyester Staple Fiber Market
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
Polypropylene Fiber Market
Synthetic Fibers
High Performance Polyester Market
Synthetic Fibers
South Korea Textile Market