
 Fiberglass Roving Market | 2026-2036
Fiberglass Roving Market Size, Share, and Industry Trends Forecast 2026-2036
Fiberglass Roving Market Analysis
Direct roving and assembled roving process automation is reconfiguring how composite manufacturers integrate glass fiber into resin transfer molding and pultrusion lines. Owens Corning leverages its thermoplastic-compatible roving portfolio to anchor positions in automotive underbody shields. Jushi Group Co., Ltd. sustains cost leadership through integrated glass-melting and fiber-drawing operations at scale in Asia. Chongqing Polycomp International Corporation specializes in high-modulus roving grades for wind blade spar caps.
Fiberglass roving consists of continuous glass fiber strands gathered into bundles without twist, typically sized with silane coupling agents and film-formers to ensure compatibility with polyester, vinyl ester, or epoxy matrices. E-glass and ECR-glass formulations dominate industrial supply, with filament diameters ranging from 13 to 24 microns depending on end-use mechanical requirements. Continuous Roving captures the largest volume share due to wind energy and pultrusion demand, while Chopped Strand is displacing short-fiber thermoplastic compounds in automotive front-end modules. Composite Materials as an application segment leads value generation because aerospace and marine laminates command performance-certified supply tiers.
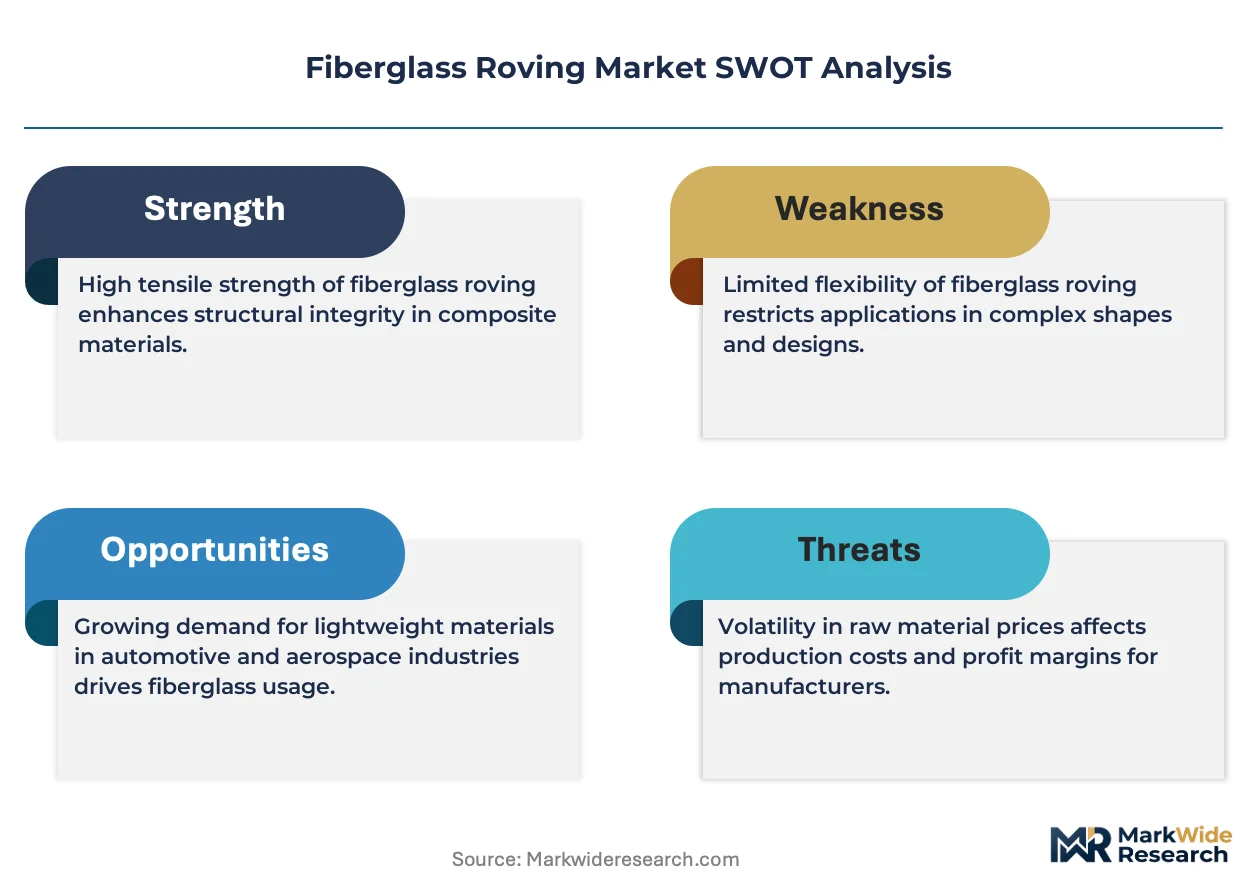
EPA emissions standards for glass melting furnaces and OSHA silica exposure limits constrain US-based roving production economics, while REACH registration requirements in Europe filter non-compliant sizing chemistries from import channels. China's GB standards and MEE air quality enforcement push domestic producers toward electric furnace retrofits and binder reformulation. Stakeholders must monitor how sizing chemistry patents and furnace energy intensity regulations reshape cost structures and regional supply qualifications.
Market Dynamics
Wind blade manufacturers are consolidating specifications around high-modulus continuous roving formats, forcing glass fiber suppliers to retool furnace chemistry and sizing systems for longer fiber lengths and tighter property bands.
Growth Catalysts
- EU Green Deal decarbonization mandates:Offshore wind installation targets in Germany and Denmark are accelerating orders for spar-cap-grade roving with certified low-carbon footprints.
- Thermoplastic resin compatibility advances:Automotive underbody shield programs in Detroit and Stuttgart are specifying silane-sized roving for direct PP-matrix welding, bypassing thermoset curing stages.
- China's dual carbon policy enforcement:MEE air quality inspections are shuttering small electric furnaces, concentrating compliant volume with integrated producers serving domestic wind tower OEMs.
Market Restraints
- Natural gas price volatility:European glass melting operations face input cost swings that compress margin on standard E-glass grades, particularly in Italy and Spain.
- Supply concentration in boron-free ECR chemistry:Three integrated Asian producers control over 70% of high-corrosion-resistant roving capacity, creating single-source risk for chemical storage tank fabricators.
- Carbon fiber substitution in aerospace spars:Boeing and Airbus laminates are specifying T800-grade carbon for next-generation wing boxes, displacing S-glass roving in primary structure applications.
Strategic Opportunities
- Recyclable thermoplastic roving systems:Closed-loop automotive programs in Bavaria are piloting PA6-compatible sizing that enables shredder-friendly end-of-life processing without pyrolysis.
- India PLI scheme for renewable energy components:Domestic content requirements for wind turbine nacelles are creating qualified-supplier status for roving producers establishing local texturizing operations.
- Digital thread integration in pultrusion:Inline dielectric sensors paired with AI-controlled resin injection are enabling real-time property adjustment for construction rebar manufacturers.
Industry Challenges
- Furnace rebuild cadence and capital intensity:Refractory lining replacement cycles every 8-10 years require $40-60 million outlays that strain mid-tier producers without captive mineral sourcing.
- REACH registration timelines for novel sizing chemistries:ECHA data requirements for silane alternatives are extending qualification periods to 18-24 months, delaying commercialization of chrome-free formulations.
- Wind blade OEM specification fragmentation:Each major turbine manufacturer maintains proprietary roving property bands, forcing suppliers to manage 15-20 distinct product codes with minimal volume per SKU.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiberglass Roving Market |
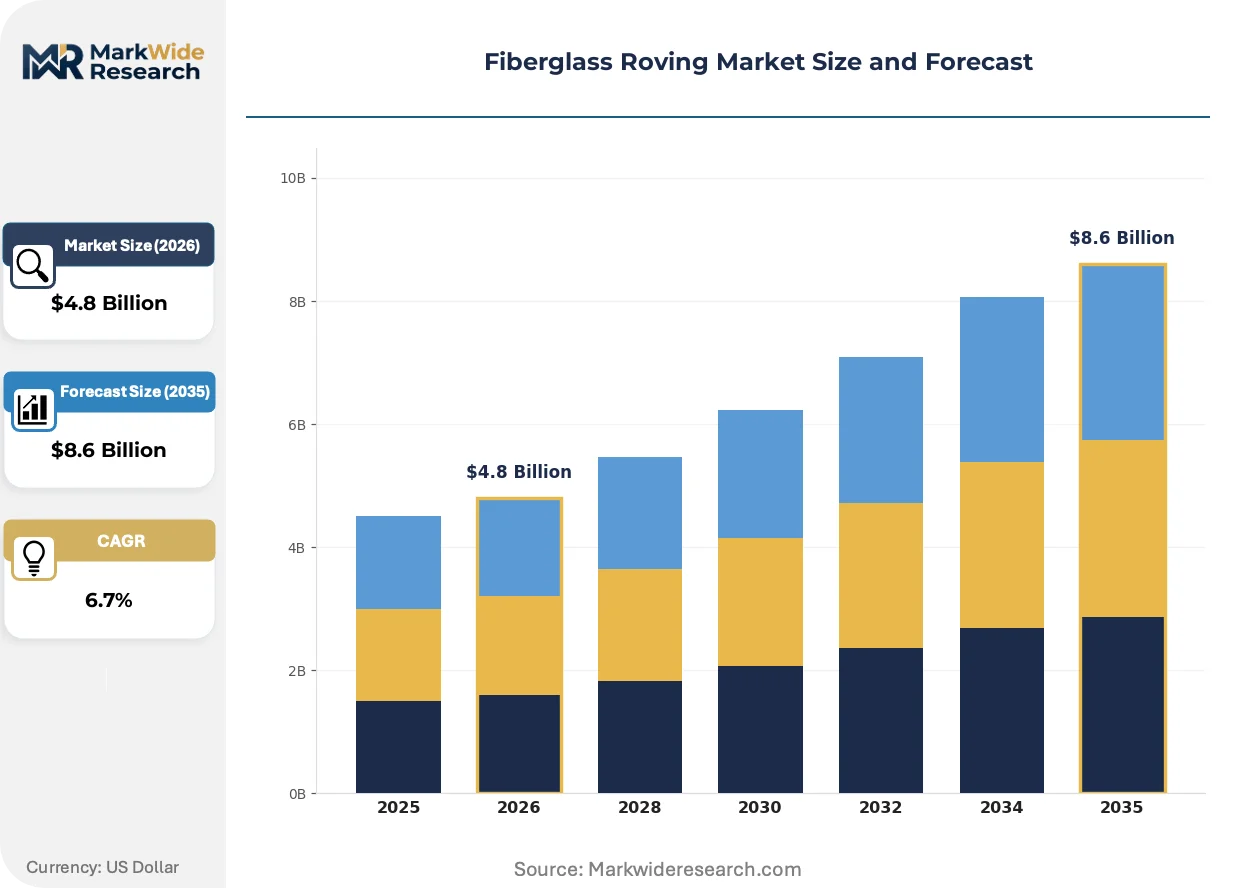
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chopped Strand, Continuous Roving, Woven Roving, Multi-Axial Roving End User: Aerospace, Automotive, Marine, Construction Application: Composite Materials, Electrical Insulation, Reinforcement, Sports Equipment Form: Sheet, Tape, Fabric, Yarn |
| Companies Covered | Owens Corning, Jushi Group Co., Ltd., Chongqing Polycomp International Corporation, Johns Manville, Saint-Gobain Vetrotex, Nippon Electric Glass, Taishan Fiberglass, Inc., China Beihai Fiberglass Co., Ltd., Taiwan Glass Industry Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiberglass Roving Market Emerging Trajectories
Material-formulation convergence and furnace-digitization investments are compressing the traditional 5-year product development cycle for structural roving grades.
Hybrid glass-carbon roving architectures are hybridizing load-path optimization in wind blade root sections. Vestas and Siemens Gamesa laminators are trialing commingled tow formats that place carbon fiber at spar-cap centers with E-glass outer plies, reducing blade mass 12-15% without full carbon cost. This hybridizing approach is compressing the premium-standard grade boundary, as mid-modulus glass formulations capture loads previously requiring aerospace-grade fiber.
REACH Annex XIV authorization requirements for chromium-based sizing agents are forcing reformulation across European supply chains. ECHA sunset dates for hexavalent chrome in film-formers are accelerating silane-alternative development, with German and Dutch compounders piloting zirconium-organic hybrids. Wind energy laminates are most affected, as blade manufacturers face customer sustainability audits that disqualify legacy-sized roving from green-tariff projects.
Specification consolidation among wind OEMs is compressing supplier qualification pipelines. Goldwind, Envision, and MingYang have each published unified roving property matrices that eliminate regional variants, forcing fiber producers to consolidate 30-plus legacy grades into 6-8 platform products. This consolidation is most visible in China's coastal provinces, where tower fabricators now accept identical roving specifications across onshore and offshore blade programs, enabling volume pooling that rewards furnace-scale producers.
Fiberglass Roving Market Segmentation
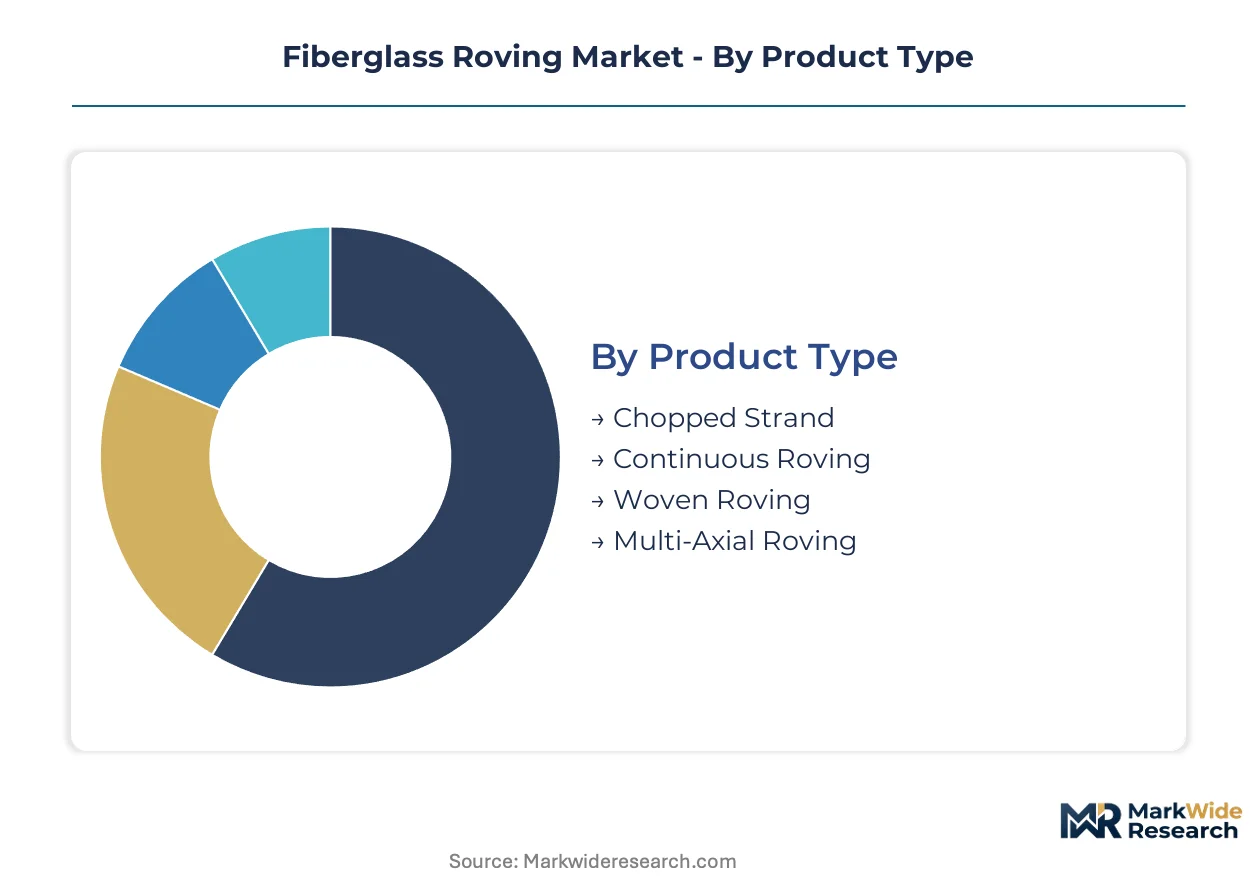
Fiberglass roving segmentation reveals how product format, end-use specification, and application chemistry create distinct supply tiers with divergent qualification cycles. Understanding these divisions exposes where furnace capacity allocates across margin profiles and regulatory exposure.
Product Type:
Cycle times vary dramatically: continuous formats lock in annual contracts with wind OEMs while chopped products turn inventory quarterly through distributor channels.
- Continuous Roving:Untwisted bundles of parallel glass filaments sized for epoxy or vinyl ester infusion. Wind blade spar-cap laminators in Denmark and Germany specify high-modulus ECR-glass grades with 18-month qualification locks, anchoring multi-year furnace allocations.
- Chopped Strand:Short-cut fibers dispersed into thermoplastic or thermoset compounds. Automotive front-end module producers in Stuttgart and Detroit specify 4.5mm lengths for direct PP compounding, cycling purchase orders monthly through resin compounders.
- Woven Roving:Plain or twill weave constructions for hand lay-up marine hulls. Yacht builders in Italy and Florida stock standard E-glass weights for seasonal production ramps.
- Multi-Axial Roving:Unidirectional or biaxial stitched layers for automated tape laying. Aerospace tier-two suppliers in Toulouse and Hamburg qualify these for wing skin preforms.
Continuous Roving anchors the volume base while Chopped Strand gains share at the steepest rate.
End User:
Customer concentration shapes margin structure: single-source aerospace programs command 40% price premiums over fragmented construction distributors.
- Automotive:Underbody shields and structural members specify thermoplastic-compatible sizing for compression molding lines. BMW and Ford programs in Bavaria and Michigan drive silane chemistry standardization.
- Construction:Rebar, grating, and facade panels consume standard E-glass grades through pultrusion. Chinese tower fabricators in Jiangsu and Zhejiang consolidate purchases around GB-certified suppliers.
- Marine:Hull laminates and deck cores demand corrosion-resistant ECR-glass for saltwater exposure. Italian yacht builders and Dutch barge yards maintain legacy vinyl ester specifications.
- Aerospace:Interior panels and cargo liners require FAA-certified flame-smoke-toxicity compliance. Boeing tier-one suppliers in Wichita specify S-glass for secondary structures.
Construction absorbs the highest tonnage while Automotive delivers the steepest margin expansion trajectory.
Application:
Application chemistry determines sizing formulation complexity and regulatory burden across supply tiers.
- Composite Materials:Structural laminates combining glass with epoxy, polyester, or vinyl ester matrices. Wind energy and marine fabricators in Spain and China dominate procurement.
- Reinforcement:Concrete and asphalt modification with alkali-resistant glass. Infrastructure projects in India and Saudi Arabia specify AR-glass for corrosion durability.
- Electrical Insulation:Transformer coils and motor windings requiring high dielectric strength. German and Japanese electrical OEMs source low-alkali E-glass with tight filament diameter control.
- Sports Equipment:Hockey sticks, bicycle frames, and fishing rods using hybrid glass-carbon layups. Taiwanese and Chinese sporting goods assemblers drive short-fiber formats.
Composite Materials commands the largest value pool while Reinforcement climbs fastest on infrastructure stimulus.
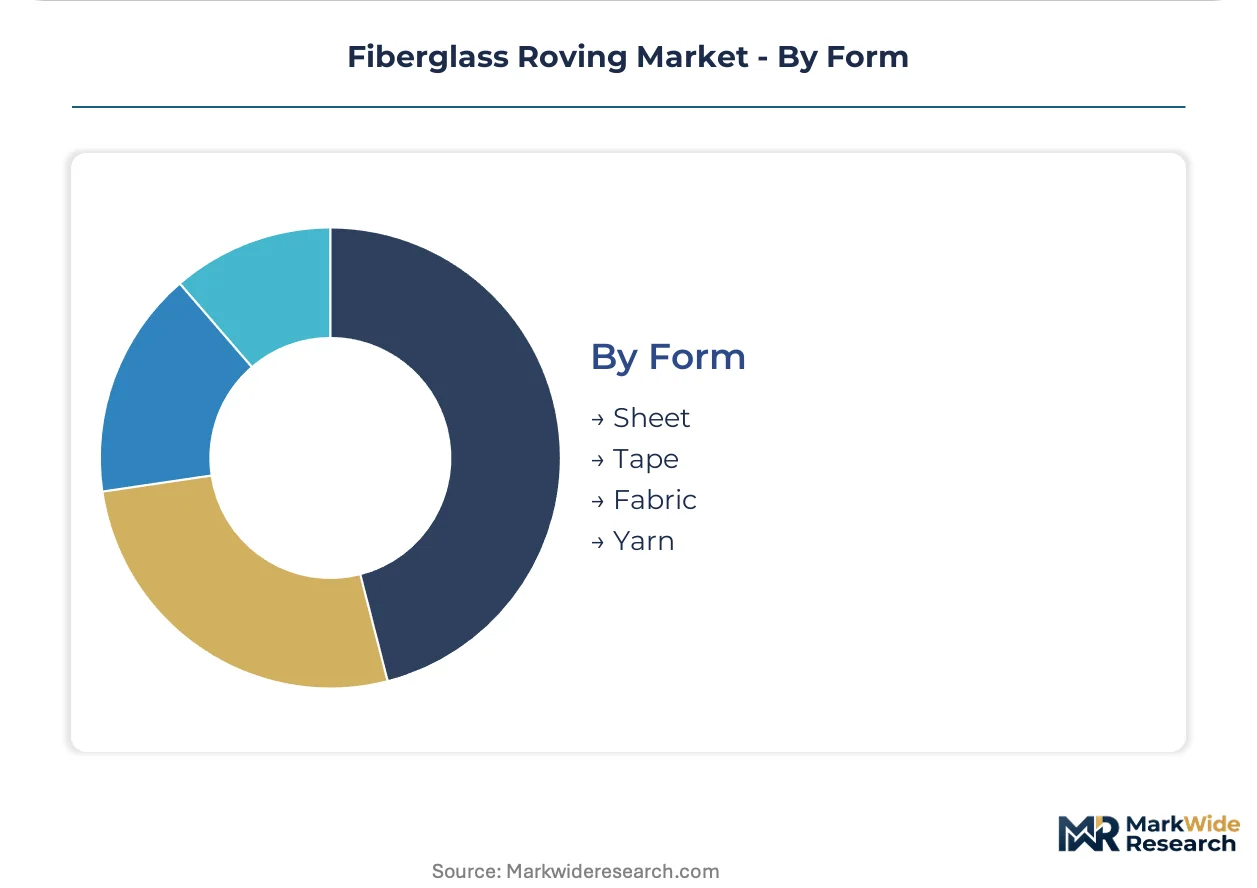
Form:
Physical configuration dictates downstream processing equipment and customer switching costs.
- Fabric:Woven sheets for hand lay-up and vacuum infusion. Boat builders in Florida and France stock standard widths for hull production.
- Tape:Narrow rolls for automated fiber placement and filament winding. Pressure vessel manufacturers in Germany and Korea specify precision-wound formats.
- Sheet:Chopped strand mat for open mold applications. Construction panel producers in Turkey and Brazil purchase bulk rolls for roofing and cladding.
- Yarn:Twisted roving for textile processing and specialty braiding. Hose reinforcement manufacturers in Italy and the US specify S-twist constructions.
Fabric holds the broadest installed base while Tape expands most quickly on automation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fiberglass roving exports dominate supply corridors into European wind blade manufacturers and North American automotive OEMs, while domestic absorption within Asia-Pacific concentrates furnace capacity around coastal industrial zones.
China
Domestic wind tower buildout and automotive lightweighting programs absorb the majority of E-glass and ECR-glass output. MEE air quality enforcement shutters small electric furnaces, concentrating compliant volume with Jiangsu and Zhejiang-based integrated producers serving Goldwind and Envision blade programs.
Germany
Offshore wind installation targets in the North Sea and Baltic Sea accelerate spar-cap-grade roving procurement with certified low-carbon footprints. EU Green Deal decarbonization mandates filter non-compliant sizing chemistries through ECHA REACH registration requirements. Siemens Gamesa laminators in Hamburg and Rostock consolidate specifications around unified property matrices.
United States
Automotive underbody shield programs in Detroit and Michigan drive thermoplastic-compatible silane-sized roving demand for direct PP-matrix welding. EPA emissions standards for glass melting furnaces and OSHA silica exposure limits constrain domestic production economics, compressing margin on standard E-glass grades.
India
Domestic content requirements for wind turbine nacelles under the PLI scheme create qualified-supplier status for roving producers establishing local texturizing operations. CEA grid integration mandates accelerate renewable energy component manufacturing. Tower fabricators in Gujarat and Tamil Nadu consolidate purchases around BIS-certified suppliers.
Japan
Electrical insulation applications for transformer coils and motor windings require low-alkali E-glass with tight filament diameter control. METI energy efficiency standards push furnace operators toward electric retrofits. Osaka and Nagoya-based electrical OEMs source precision-controlled roving formats for high-dielectric applications.
Fiberglass Roving Market Vendor Landscape
Channel-controlling players compete with product-specialist players across furnace-scale and niche-format segments. The market structures around three tiers: integrated Asian producers with captive mineral sourcing, European specialty compounders with REACH-compliant sizing portfolios, and regional distributors managing inventory turns for construction-grade chopped strand. Dominant competitive moves include furnace capacity expansion in coastal China and strategic partnerships between roving suppliers and wind blade OEMs for qualification-locked volume.
Among China-based integrated producers, Jushi Group Co., Ltd. and Chongqing Polycomp International Corporation exemplify the scale-driven archetype with backward integration into glass-melting operations. Owens Corning occupies a position representing North American channel control through thermoplastic-compatible portfolio breadth. These three anchors illustrate how geographic concentration and format specialization stratify competitive positioning across premium wind energy and standard construction tiers.
| Leading Market Players |
|---|
| Owens Corning |
| Jushi Group Co., Ltd. |
| Chongqing Polycomp International Corporation |
| Johns Manville |
| Saint-Gobain Vetrotex |
| Nippon Electric Glass |
| Taishan Fiberglass, Inc. |
| China Beihai Fiberglass Co., Ltd. |
| Taiwan Glass Industry Corporation |
| Others |
Supply Flow & Price Mechanics
Jiangsu and Zhejiang furnace clusters anchor global E-glass capacity, concentrating pricing leverage with integrated producers who feed Goldwind and Envision blade programs while squeezing mid-tier compounders on standard-grade margins.
Pricing Analysis
Prior-generation E-glass roving trades at commodity compression while next-generation ECR-glass and thermoplastic-compatible grades capture widening premiums. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from European natural gas volatility compressing margin on standard grades. Construction rebar distributors exhibit highest price sensitivity, while aerospace tier-two suppliers show lowest sensitivity due to qualification-locked supply tiers.
Supply Chain Analysis
Export-control regimes on advanced furnace technology and sizing chemistry patents limit equipment and know-how flows into emerging production zones. Supply concentrates in China, Germany, and the United States, with raw material dependencies on boron, silica sand, and silane coupling agents. Single-source vulnerability runs through Asian ECR-glass capacity controlled by three integrated producers. Distribution runs through direct mill contracts for wind OEMs and distributor networks for construction-grade chopped strand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fiberglass roving markets increasingly reward sizing chemistry services and technical qualification support, with formulation consulting and blade-design collaboration expanding faster than base fiber tonnage.
For Market Incumbents: Insulate furnace-scale positions by deepening backward integration into boron and silica sourcing, and accelerate REACH-compliant sizing patent filings before ECHA sunset dates. Carbon fiber substitution in aerospace spars threatens S-glass margins, demanding defensive certification investments in hybrid glass-carbon architectures. For New Entrants and Emerging Players: India's PLI-qualified wind nacelle supply chain represents the most penetrable entry point, with domestic content requirements filtering non-local roving from turbine OEM procurement. Texturizing joint ventures with Gujarat and Tamil Nadu tower fabricators offer lowest-qualification-barrier access. Target thermoplastic sizing development for automotive PP-matrix welding programs bypassing thermoset curing. For Investors and Strategic Acquirers: Long-term, this sits as a furnace-scale consolidation play because MEE air quality enforcement shutters small Chinese electric furnaces, concentrating compliant volume with integrated producers. Acquisition targets should show captive mineral sourcing and unified wind OEM qualification status. Watch for Goldwind, Envision, or MingYang specification consolidation announcements as volume-pooling inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Jiangsu and Zhejiang furnace buildouts capture wind OEM volume pooling from specification consolidation. |
| Backward Integration | Captive boron and silica sourcing insulates margin against mineral price volatility from Turkish and US suppliers. |
| Green Manufacturing Transition | Electric furnace retrofits satisfy MEE air quality enforcement and EU Green Deal carbon footprint audits. |
| Long-term Supply Agreement | Multi-year qualification-locked contracts with Vestas and Siemens Gamesa anchor furnace utilization rates. |
| Joint Venture | Local texturizing partnerships in Gujarat and Tamil Nadu unlock PLI scheme qualified-supplier status. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with glass furnace operators, wind blade procurement managers, automotive Tier 1 composite engineers, and sizing chemistry formulators; and secondary validation through customs trade data, SEC 10-K filings of listed fiber producers, GB standards documentation, and ECHA REACH registration databases. Bottom-up volume modeling triangulated against top-down end-use consumption estimates across wind energy, automotive, and construction segments.
Forecast inputs span product format, glass chemistry grade, end-use industry, and regional regulatory cluster across the projection horizon. CAGRs derive from segment-level demand elasticity modeling and furnace capacity utilization trajectories. Specific inputs include wind turbine installation pipelines from Goldwind, Envision, and MingYang, and automotive lightweighting program timelines from BMW and Ford.
Practitioners should monitor ECHA authorization timelines for chromium-based sizing agents and MEE furnace enforcement intensity for early signals of supply restructuring. Forecasts embed assumptions around REACH compliance costs and natural gas price normalization. Material shifts in wind OEM specification consolidation pace or carbon fiber cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Carbon Fiber Strands Market
Synthetic Fibers
Rayon Fibers Market
Synthetic Fibers
Melt Spun Fibers Market
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
IMO Fiber Market
Synthetic Fibers
Latin America Textile Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
High End Synthetic Suede Market
Synthetic Fibers
Europe Nanofiber Market
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
Global Lyocell Fibers Market
Synthetic Fibers
Neoprene Fabric Market
Synthetic Fibers
Monofilament Market
Synthetic Fibers
High Performance Polyester Market
Synthetic Fibers
North America Aramid Fiber Market