
 Carbon Fiber Strands Market | 2026-2036
Carbon Fiber Strands Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Fiber Strands Market Analysis
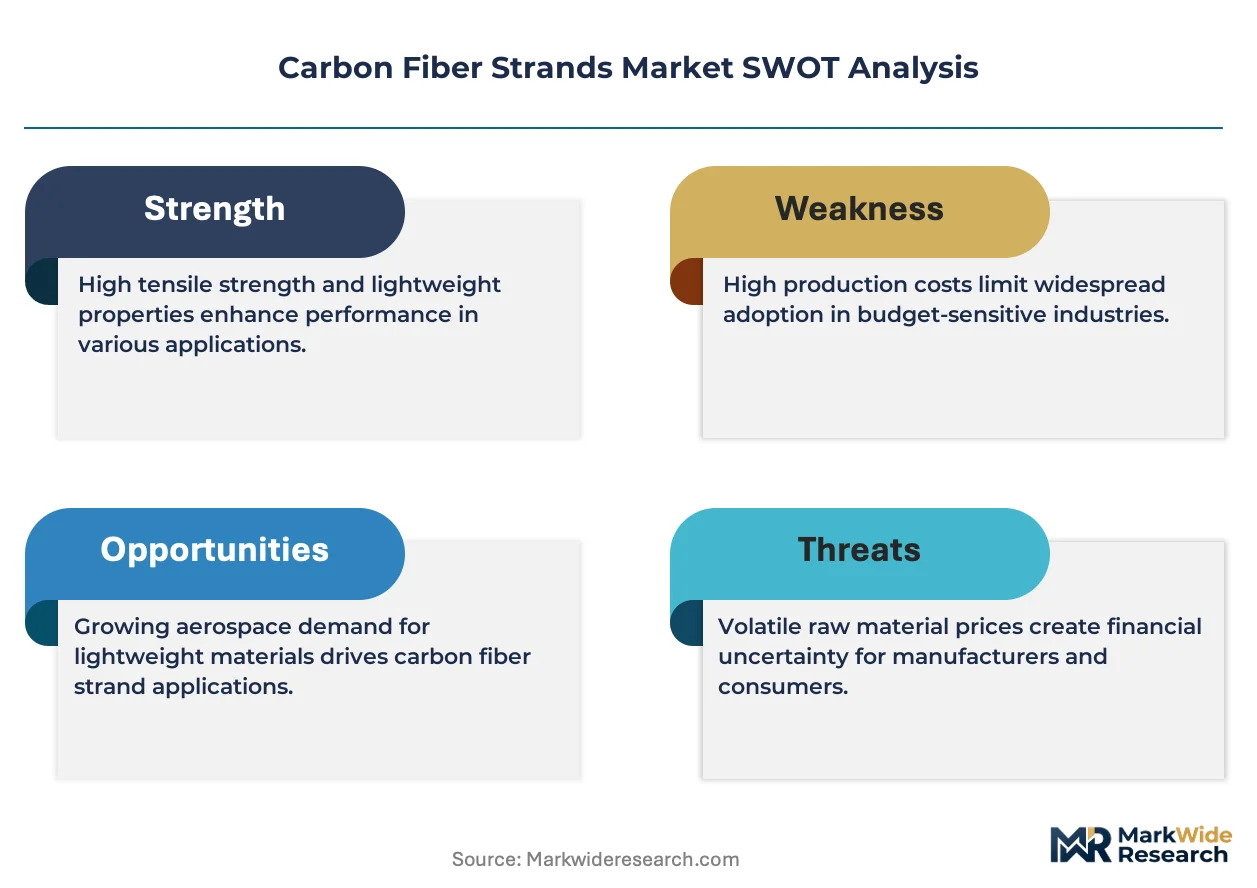
A shift from single-source to multi-source precursor supply is restructuring procurement strategies across the carbon fiber strands value chain. Toray Industries leverages captive acrylonitrile capacity and PAN precursor integration to sustain cost leadership in continuous fiber grades. Hexcel Corporation competes through aerospace-qualified product lines and qualification lock-in with Boeing and Airbus tier suppliers. SGL Carbon specializes in automotive-focused chopped fiber and short-cycle compression molding feedstocks, anchoring its position with German OEM direct contracts.
Carbon fiber strands are filaments of carbon atoms arranged in crystalline formation, typically 5-10 micrometers in diameter, produced through controlled oxidation and carbonization of polyacrylonitrile or pitch precursors at temperatures exceeding 1,000°C, yielding specific tensile strength exceeding 3,500 MPa for industrial grades. These strands serve as the foundational reinforcement element in polymer matrix composites where stiffness-to-weight ratio determines system performance. Continuous fiber commands the dominant value share due to qualification barriers in aerospace primary structures and wind blade spar caps, while chopped fiber segments expand fastest in automotive underbody and battery enclosure applications where throughput and cost-per-part drive purchasing decisions. Prepreg formats concentrate margin pools through autoclave-cure specifications and freezer-chain logistics that limit supplier switching.
The FAA certifies carbon fiber strand composites under Part 25 airworthiness standards, while REACH and the EU F-Gas Regulation constrain solvent-based sizing chemistries and manufacturing emissions in European production facilities. China's GB standards and MIIT industrial policy directives set domestic content thresholds for rail transit and new energy vehicle applications, channeling demand toward local strand producers. Japan's METI funds next-generation low-carbon fiber development through national technology roadmaps. Stakeholders must monitor qualification timeline compression in automotive programs and the divergence between aerospace certification cycles and industrial market volume ramps.
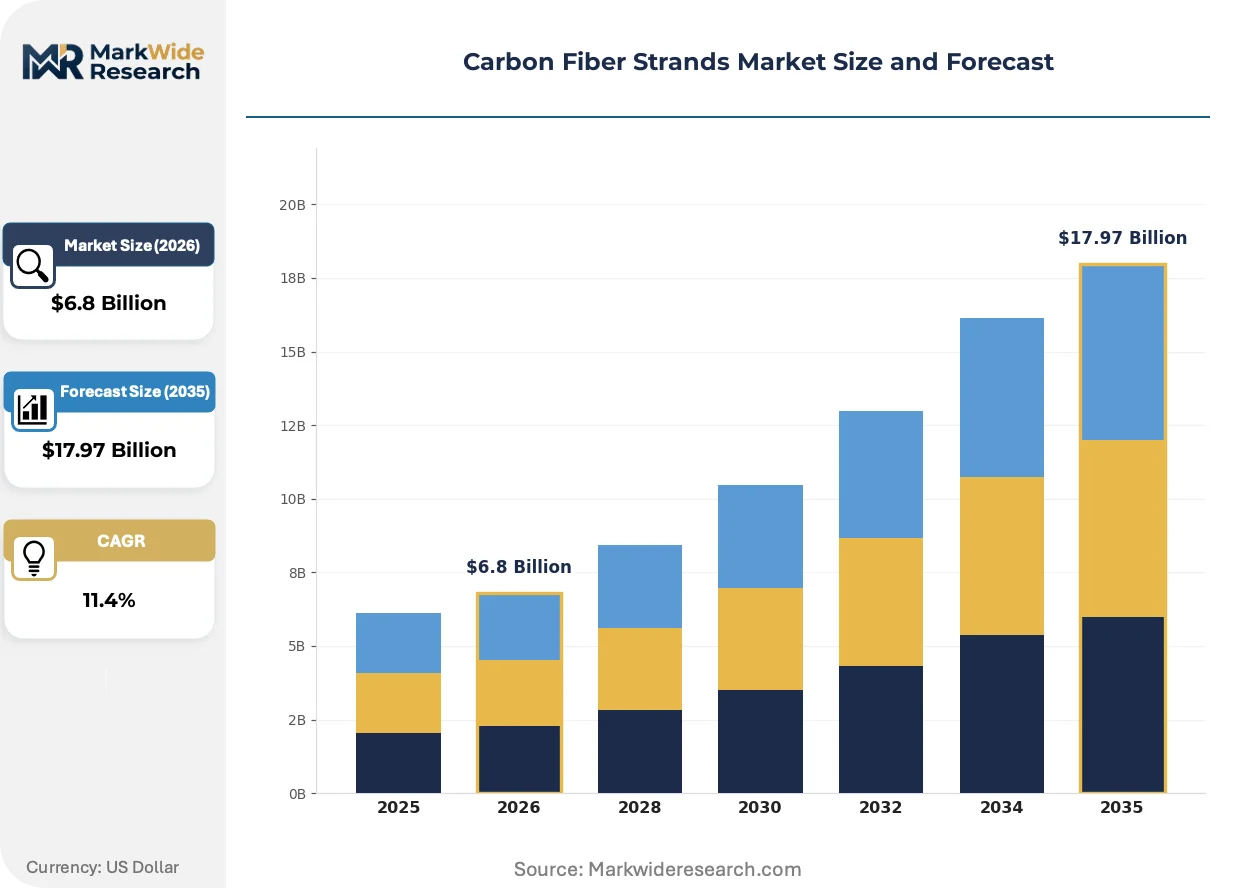
Market Dynamics
Multi-source precursor procurement is restructuring supply relationships as aerospace and automotive OEMs diversify away from concentrated acrylonitrile suppliers. This shift is compressing qualification timelines and forcing strand producers to integrate backward into PAN precursor production or secure long-term offtake agreements with regional chemical suppliers.
Growth Catalysts
- EU Green Deal emissions mandates:Germany and France are accelerating metal substitution in vehicle platforms, driving procurement of chopped fiber for battery enclosures and underbody structures.
- Wind turbine scaling in China:Eastern manufacturing corridor producers are expanding composite component output for domestic turbine OEMs, concentrating demand for industrial-grade continuous fiber.
- FAA Part 25 certification pathways:Next-generation airframe programs are expanding qualified supplier pools for primary structure carbon fiber, opening procurement to tier-2 strand producers.
Market Restraints
- Acrylonitrile price volatility:Propylene-ammonia feedstock cost swings compress margins for non-integrated strand producers lacking captive precursor supply.
- Japanese precursor concentration:Three suppliers control over half of global PAN supply, creating single-source vulnerability for European and North American carbonization facilities.
- REACH solvent constraints:ECHA restrictions on sizing chemistries force reformulation of fiber surface treatments, extending qualification cycles for aerospace grades.
Strategic Opportunities
- India rail transit localization:PLI scheme incentives and BIS domestic content thresholds are channeling demand toward local strand production for metro and high-speed rail composite components.
- Thermoplastic unidirectional tape:Automotive compression molding is converging with automated fiber placement, enabling out-of-autoclave processing for structural battery enclosures.
- Recycled carbon fiber feedstocks:Pyrolysis recovery technologies are creating secondary fiber streams for non-structural automotive applications at 40% cost reduction.
Industry Challenges
- Carbonization furnace operator scarcity:Specialized high-temperature process engineering talent pools are concentrated in Japan and Germany, constraining greenfield facility staffing.
- Aerospace qualification timeline compression:Boeing and Airbus tier suppliers face 18-24 month certification cycles that misalign with automotive program ramp schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Fiber Strands Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Fiber, Chopped Fiber, Fabric, Prepreg End User: Aerospace, Automotive, Construction, Sports Equipment Application: Reinforcement, Lightweight Structures, Aerospace Components, Sporting Goods Manufacturing Technique: Pultrusion, Filament Winding, Resin Transfer Molding, Compression Molding |
| Companies Covered | Toray Industries, Hexcel Corporation, Teijin Limited, Mitsubishi Chemical, SGL Carbon, Hyosung Advanced Materials, Solvay, Formosa Plastics Corporation, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Fiber Strands Market Emerging Trajectories
Digital thread integration across precursor-to-composite workflows is compressing development cycles and enabling real-time quality assurance. These shifts are unifying historically siloed process steps and reshaping how strand producers collaborate with downstream converters.
Low-temperature plasma oxidation is unifying PAN stabilization with surface functionalization in a single continuous process. Toray and SGL Carbon pilot lines are adopting this approach for automotive-grade fiber, reducing energy intensity by 30% while enabling inline sizing chemistry modification. The technology is unifying cost reduction with emissions compliance, positioning plasma oxidation as the dominant pathway for industrial fiber expansion.
REACH F-Gas Regulation amendments are constraining hydrofluorocarbon-based refrigerants in carbonization furnace cooling systems. European producers face retrofit deadlines requiring transition to ammonia or CO2-based alternatives, adding €2-4 million per facility in capital burden. German and French strand operations are responding by consolidating carbonization capacity at larger scale facilities to amortize compliance costs.
Buyer consortiums are aggregating procurement across tier-1 automotive suppliers, displacing bilateral annual contracts with multi-year volume commitments indexed to acrylonitrile futures. This concentration is compressing supplier margins while securing supply priority for German OEM direct contracts. The shift is most visible in Bavaria and Baden-Württemberg, where BMW, Mercedes-Benz, and Porsche suppliers have formed joint sourcing entities.
Carbon Fiber Strands Market Segmentation
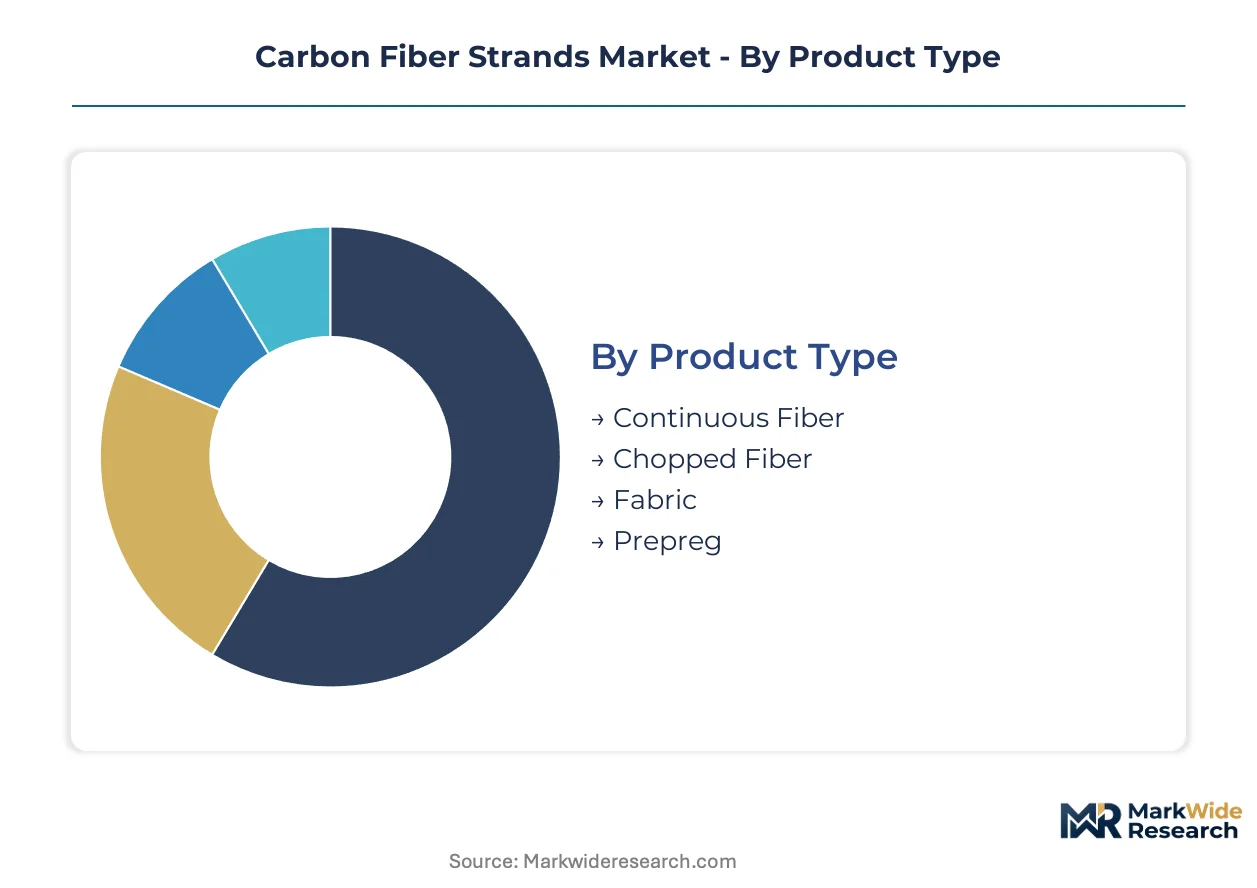
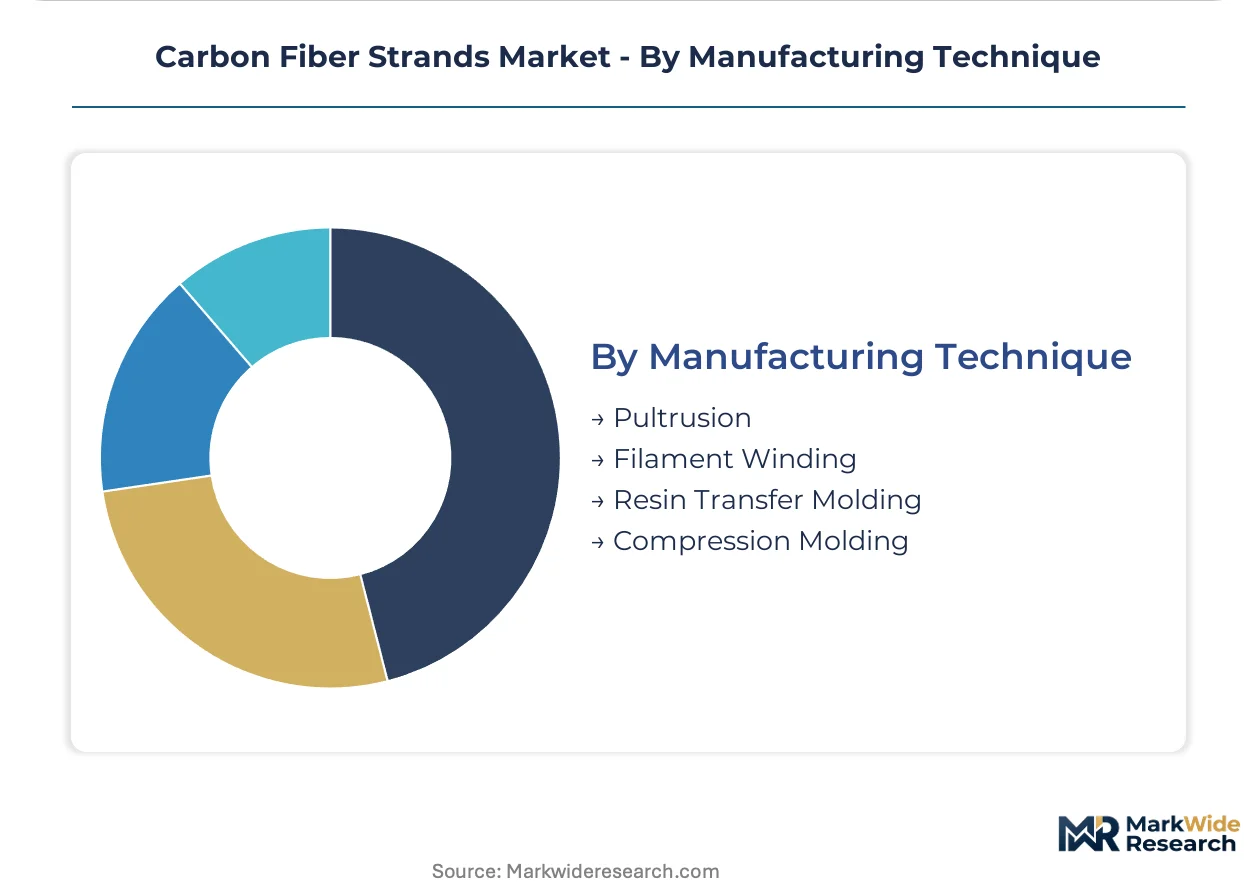
Carbon fiber strand procurement diverges sharply across end-use specifications, with aerospace qualification requirements and automotive cost-per-part targets driving incompatible sourcing strategies. Understanding these segment boundaries enables suppliers to align furnace capacity and precursor inventory with divergent margin and volume profiles.
Product Type:
Technical specifications around fiber length, tow size, and surface chemistry define the product hierarchy and lock in downstream processing compatibility.
- Continuous Fiber:Unbroken filaments arranged in tows of 3K to 50K fibers, delivering specific tensile strength exceeding 3,500 MPa for primary structural loads. Demand concentrates in Boeing and Airbus tier supply chains for wing spars and fuselage barrels, where FAA Part 25 qualification cycles extend 18-24 months and lock out unqualified suppliers. Mature deployment sits with Continuous Fiber. Newer deployment is concentrated in Chopped Fiber.
- Chopped Fiber:Precut filaments 3-50mm in length, optimized for high-throughput compression molding of complex geometries. Procurement is expanding fastest among German OEM direct contracts for battery enclosures and underbody shields, where EU Green Deal emissions mandates accelerate metal substitution and cycle time targets fall below 90 seconds.
- Fabric:Woven or non-woven textile formats assembled from continuous tows, enabling drapability over compound curves. Marine and industrial applications in China's eastern manufacturing corridor absorb volume for mold-ready reinforcement layers.
- Prepreg:Pre-impregnated fiber sheets requiring frozen-chain logistics and autoclave cure cycles, commanding margin premiums through qualified aerospace specifications. Autoclave capacity constraints in North America and Europe limit supplier switching.
Continuous fiber commands the dominant value share due to qualification barriers, while chopped fiber segments expand most quickly in automotive underbody applications where throughput drives purchasing decisions.
End User:
Customer procurement patterns split between long-cycle qualification regimes and short-cycle volume manufacturing.
- Aerospace:Primary and secondary structure manufacturers subject to FAA, EASA, and CAAC certification pathways. Boeing 787 and Airbus A350 programs anchor demand for qualified continuous fiber grades, with tier supplier consolidation favoring incumbent strand producers.
- Automotive:OEM platform engineering teams specifying chopped fiber for structural components and Class A surface alternatives. BMW, Mercedes-Benz, and Porsche supplier consortiums in Bavaria and Baden-Württemberg are aggregating procurement across multi-year volume commitments indexed to acrylonitrile futures.
- Construction:Infrastructure retrofit and seismic reinforcement projects utilizing carbon fiber reinforced polymer strips and tendons. Japan's METI-funded technology roadmaps support next-generation low-carbon fiber development for civil engineering applications.
- Sports Equipment:Bicycle frames, golf shafts, and hockey sticks demanding high stiffness-to-weight ratios with shorter qualification cycles than aerospace. Premium bicycle manufacturers in Italy and Taiwan specify Toray T800-grade continuous fiber for monocoque frame production.
Volume concentration sits with Automotive. Margin concentration sits with Aerospace.
Application:
Functional performance requirements determine fiber format selection and surface treatment chemistry.
- Reinforcement:Load-bearing integration within concrete, timber, and polymer matrices where corrosion resistance extends service life. Wind turbine blade spar caps in China's eastern manufacturing corridor represent the dominant volume application for industrial-grade continuous fiber.
- Lightweight Structures:Stiffness-critical components where mass reduction directly improves energy efficiency or payload capacity. Battery enclosures for electric vehicles are the fastest-expanding application category, with thermoplastic unidirectional tape formats enabling out-of-autoclave processing.
- Aerospace Components:Flight-critical primary structures including wings, empennage, and pressure vessels where damage tolerance and fatigue resistance are non-negotiable. Qualification lock-in with Boeing and Airbus tier suppliers protects incumbent strand producers.
- Sporting Goods:Performance equipment where brand differentiation justifies material cost premiums over metals and glass fiber. Cycling and golf equipment manufacturers in Germany and Japan specify aerospace-grade fiber for flagship product lines.
Structural load-bearing deployment sits with Reinforcement. Emerging deployment is concentrated in Lightweight Structures.
Manufacturing Technique:
Process compatibility constraints filter fiber format availability and sizing chemistry selection.
- Pultrusion:Continuous profile extrusion producing constant-cross-section beams and rods with unidirectional fiber alignment. Bridge strengthening and industrial handrail applications in Germany and France specify pultruded carbon fiber profiles for corrosion-resistant infrastructure.
- Filament Winding:Automated fiber placement onto rotating mandrels for pressure vessels, drive shafts, and rocket motor casings. Compressed natural gas vehicle tank production in India leverages filament-wound carbon fiber to meet BIS domestic content thresholds under PLI scheme incentives.
- Resin Transfer Molding:Closed-mold infusion of liquid resin through stationary fiber preforms, enabling complex net-shape production with controlled void content. Automotive structural components in Baden-Württemberg supplier networks favor RTM for medium-volume battery enclosure programs.
- Compression Molding:High-pressure, high-temperature consolidation of chopped fiber or unidirectional tape preforms into finished parts in sub-90-second cycles. Bavarian OEM supplier parks are converging automated fiber placement with compression molding for thermoplastic structural battery enclosures.
High-volume deployment sits with Compression Molding. Precision-critical deployment sits with Filament Winding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acrylonitrile feedstock availability and carbonization furnace capacity anchor regional production economics. Demand concentrates where aerospace OEMs, automotive platforms, and wind turbine manufacturers cluster.
United States
Boeing 787 and Airbus A350 programs drive qualified continuous fiber procurement through FAA Part 25 certification pathways. The FAA maintains stringent airworthiness standards for primary structure composites. South Carolina and Washington state aerospace corridors host tier supplier consolidation favoring incumbent strand producers.
Germany
EU Green Deal emissions mandates accelerate metal substitution in BMW, Mercedes-Benz, and Porsche vehicle platforms. REACH and the EU F-Gas Regulation constrain solvent-based sizing chemistries and furnace cooling systems. Bavaria and Baden-Württemberg supplier consortiums aggregate procurement across multi-year volume commitments.
China
Domestic wind turbine and electric vehicle producers scale composite component output in the eastern manufacturing corridor. MIIT industrial policy directives and GB standards set domestic content thresholds for rail transit and new energy vehicle applications. Jiangsu and Zhejiang provinces channel demand toward local strand producers.
Japan
Three suppliers control over half of global PAN precursor supply, creating single-source vulnerability for downstream carbonization. METI funds next-generation low-carbon fiber development through national technology roadmaps. Tokyo and Osaka industrial clusters concentrate specialized high-temperature process engineering talent.
India
PLI scheme incentives and BIS domestic content thresholds channel demand toward local strand production for metro and high-speed rail composite components. Compressed natural gas vehicle tank production leverages filament-wound carbon fiber. Gujarat and Maharashtra manufacturing hubs absorb industrial-grade fiber volume.
Carbon Fiber Strands Market Vendor Landscape
Global majors compete with regional champions across precursor integration and qualification depth. The vendor base stratifies between aerospace-certified incumbents with 18-24 month lock-in cycles and automotive-focused challengers optimizing throughput economics. Three archetypes dominate: integrated precursor-to-fiber operators, aerospace-qualified specialists, and automotive cost-per-part optimizers. Capacity expansion and backward integration into PAN precursor production represent the dominant competitive moves.
Within the integrated operator archetype, Toray Industries and Mitsubishi Chemical exemplify captive acrylonitrile capacity and PAN precursor control. Hexcel Corporation occupies a position among aerospace-qualified specialists competing through qualification lock-in with Boeing and Airbus tier suppliers. SGL Carbon sits within the automotive-focused tier, anchoring its market presence with German OEM direct contracts for chopped fiber and compression molding feedstocks.
| Leading Market Players |
|---|
| Toray Industries |
| Hexcel Corporation |
| Teijin Limited |
| Mitsubishi Chemical |
| SGL Carbon |
| Hyosung Advanced Materials |
| Solvay |
| Formosa Plastics Corporation |
| BASF |
| Others |
Supply Flow & Price Mechanics
Captive precursor-to-fiber integration anchors pricing power for Toray Industries and Mitsubishi Chemical, locking in acrylonitrile cost advantages that non-integrated strand producers cannot replicate. This structural control over PAN supply insulates qualified aerospace grades from commodity volatility while compressing margins for European and North American carbonization facilities dependent on Japanese precursor imports.
Pricing Analysis
Warranty and qualification-bundling separate aerospace-grade continuous fiber from automotive chopped fiber tiers, with FAA Part 25 certification cycles extending 18-24 months and embedding technical support into long-term offtake agreements. Pricing stratifies across premium aerospace-qualified continuous fiber, standard industrial grades for wind applications, and economy chopped fiber for automotive compression molding. Cost compression in automotive grades intensifies because buyer consortiums in Bavaria and Baden-Württemberg aggregate procurement across multi-year volume commitments indexed to acrylonitrile futures. Tier-1 automotive suppliers exhibit highest price sensitivity, while Boeing and Airbus tier suppliers accept premium pricing for qualification-locked supply security.
Supply Chain Analysis
Acrylonitrile feedstock rests on Japanese, Chinese, and South Korean petrochemical producers, with three Japanese suppliers controlling over half of global PAN precursor output. Polyacrylonitrile polymerization, carbonization furnace operation, and surface sizing chemistry constitute the critical processing stages. Single-source vulnerability in Japanese precursor concentration creates structural risk for European and North American carbonization facilities lacking backward integration. Distribution runs through qualified tier supplier networks for aerospace grades and direct OEM contracts for automotive feedstocks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low-temperature plasma oxidation is displacing conventional thermal oxidation in carbonization, unifying PAN stabilization with surface functionalization while cutting energy intensity. This technology transition compresses qualification timelines and reshapes competitive positioning between incumbent aerospace specialists and automotive-focused challengers.
For Market Incumbents: Anchor qualification lock-in with Boeing and Airbus tier suppliers through accelerated FAA Part 25 certification support, while deepening backward integration into regional acrylonitrile supply to offset Japanese precursor concentration risk. Defend margin position by consolidating carbonization capacity at larger scale facilities to amortize EU F-Gas Regulation compliance costs for furnace cooling system retrofits.
For New Entrants and Emerging Players: Digital thread integration platforms offer a route to compress development cycles and enable real-time quality assurance partnerships with tier-2 automotive suppliers. Target India's PLI scheme rail transit localization as the most penetrable geography, where BIS domestic content thresholds channel demand toward local strand production for metro composite components. Lead with thermoplastic unidirectional tape formats for out-of-autoclave battery enclosure applications.
For Investors and Strategic Acquirers: Exit pathways concentrate in aerospace-qualified specialists with deep Boeing and Airbus tier relationships, where 18-24 month certification cycles create durable competitive moats. Long-term viability favors integrated precursor-to-fiber operators with captive acrylonitrile capacity and regional production footprints spanning Japan, China, and Germany. Watch plasma oxidation adoption rates as the inflection indicator for automotive-grade cost structure transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor | Captive acrylonitrile supply insulates Toray and Mitsubishi Chemical from feedstock volatility. |
| Plasma Oxidation Technology Deployment | Low-temperature processing cuts energy intensity 30% for automotive-grade fiber expansion. |
| Multi-Year Volume Commitment Structuring | Bavarian buyer consortiums lock supply priority through acrylonitrile futures-indexed contracts. |
| EU F-Gas Regulation Compliance Retrofit | German and French producers consolidate carbonization capacity to amortize €2-4 million facility upgrades. |
| India PLI Scheme Localization Partnership | BIS domestic content thresholds channel rail transit demand toward Gujarat and Maharashtra production hubs. |
Methodological Framework
Document review covered SEC 10-K filings, MIIT industrial policy directives, FAA Part 25 certification databases, and EU ECHA REACH regulatory filings, complemented by interviews with carbonization furnace operators, aerospace tier supplier procurement leads, automotive OEM platform engineers, and PAN precursor technical directors. Secondary validation drew from Japan Chemical Industry Association trade data, German KBA automotive registration statistics, and China customs export records. Bottom-up strand production capacity modeling triangulated against top-down composite component demand forecasts.
Segment-level value outputs across the projection horizon reflect fiber format splits between continuous, chopped, fabric, and prepreg grades, cross-referenced with end-use industry procurement patterns in aerospace, automotive, wind energy, and rail transit. CAGRs were derived from elasticity-adjusted demand modeling against acrylonitrile price scenarios and qualification timeline compression assumptions. Forecast inputs incorporated plasma oxidation adoption curves and EU Green Deal emissions mandate compliance schedules.
The model holds under stable acrylonitrile feedstock availability and sustained FAA certification pathway integrity; deviation in Japanese precursor supply disruption or REACH solvent restriction acceleration would shift volume and value trajectories. A small set of named triggers warrants ongoing watch: plasma oxidation scale-up rates, EU F-Gas Regulation enforcement timing, and India PLI scheme disbursement velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
Asia-Pacific Lyocell Fibers Market
Synthetic Fibers
Anti-Static Fibers Market
Synthetic Fibers
Melt Spun Fibers Market
Synthetic Fibers
Fiberglass Roving Market
Synthetic Fibers
Nanofibers Market
Synthetic Fibers
Europe Nanofiber Market
Synthetic Fibers
Polybenzoxazole Fibers Market
Synthetic Fibers
Conductive Fibers Market
Synthetic Fibers
Americas Spandex Market
Synthetic Fibers
Modacrylic Fiber Market
Synthetic Fibers
Glass Fiber Yarn Market
Synthetic Fibers
Bio-Based Elastic Core-Spun Yarn for Denim Stretch Market
Synthetic Fibers
Aramid Fiber Market
Synthetic Fibers
Polypropylene Fiber Market
Synthetic Fibers
Regenerated Fibers Market