
 Europe Contract Textiles Market | 2026-2036
Europe Contract Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Contract Textiles Market Insights
Buyer concentration among European hospitality chains is broadening procurement leverage, forcing suppliers to diversify account risk. Camira Fabrics Ltd. sustains its position through vertical integration into yarn production. Panaz competes on rapid custom color matching for hotel rollouts. Gabriel A/S anchors its portfolio with durable wool blends engineered for high-traffic commercial seating.
Contract textiles are industrial-grade fabrics manufactured to flame-retardant, abrasion-resistant, and colorfastness specifications for commercial installation rather than consumer purchase. Production typically involves solution-dyed fibers, woven or knitted constructions meeting ISO 12947 martindale abrasion thresholds, and back-coating treatments for dimensional stability in institutional laundering. Upholstery commands the largest value pool due to replacement frequency in seating-intensive environments, while wall coverings represent the fastest-expanding segment as acoustic performance gains priority in open-plan offices. Wool and wool-blend materials retain premium positioning in heritage hospitality settings, whereas polyester dominates volume through cost scalability and inherent flame resistance.
REACH restrictions on chemical finishes and the EU Green Deal's textile circularity mandates are elevating compliance costs for dye houses and finishers across the continent. ECHA substance evaluations now drive reformulation timelines for stain-resistant and antimicrobial treatments previously standard in healthcare and restaurant applications. The EU AI Act's emerging transparency requirements will eventually extend to automated textile sorting and recycling infrastructure. Stakeholders must monitor how the CSRD's scope expansion affects Tier 2 supplier disclosure obligations for fiber traceability.
Market Dynamics
The EU Green Deal's textile circularity mandates are compressing supplier margins while consolidating procurement power among hospitality chains running synchronized renovation cycles across Germany, France, and the UK.
Growth Catalysts
- REACH reformulation timelines:ECHA substance evaluations are accelerating R&D investment in bio-based flame retardants, creating first-mover advantage for compliant suppliers.
- Acoustic performance prioritization:Open-plan office redesigns across Nordic markets are expanding wall covering specifications that integrate sound absorption with fire safety.
- Solution-dyed polyester scalability:Inherent colorfastness and flame resistance properties are capturing specification share from post-dyed natural fibers in high-traffic seating.
Market Restraints
- Wool price volatility:New Zealand and Australian fiber auctions transmit cost instability directly to premium hospitality upholstery lines.
- Dye house concentration in Northern Italy:Geographic clustering of finishing capacity creates single-point vulnerability for EU-wide supply continuity.
- Antimicrobial treatment substitution:Silver-ion and triclosan restrictions under REACH Annex XVII are eliminating established performance differentiators without fully viable replacements.
Strategic Opportunities
- CSRD disclosure mandates:Tier 2 fiber traceability requirements will advantage suppliers with captive yarn production and blockchain-enabled provenance systems.
- Healthcare-acquired infection protocols:Copper-infused and photocatalytic surface treatments are opening specification pathways previously blocked by chemical resistance concerns.
- Automated textile sorting infrastructure:EU AI Act transparency requirements for recycling systems will reward early investment in computer-vision enabled separation technology.
Industry Challenges
- Martindale abrasion certification bottlenecks:ISO 12947 testing capacity constraints are extending product launch timelines for seating-intensive applications.
- Legacy ERP integration with traceability platforms:Fiber origin documentation requirements are exposing data architecture gaps across mid-tier weaving operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Contract Textiles Market |
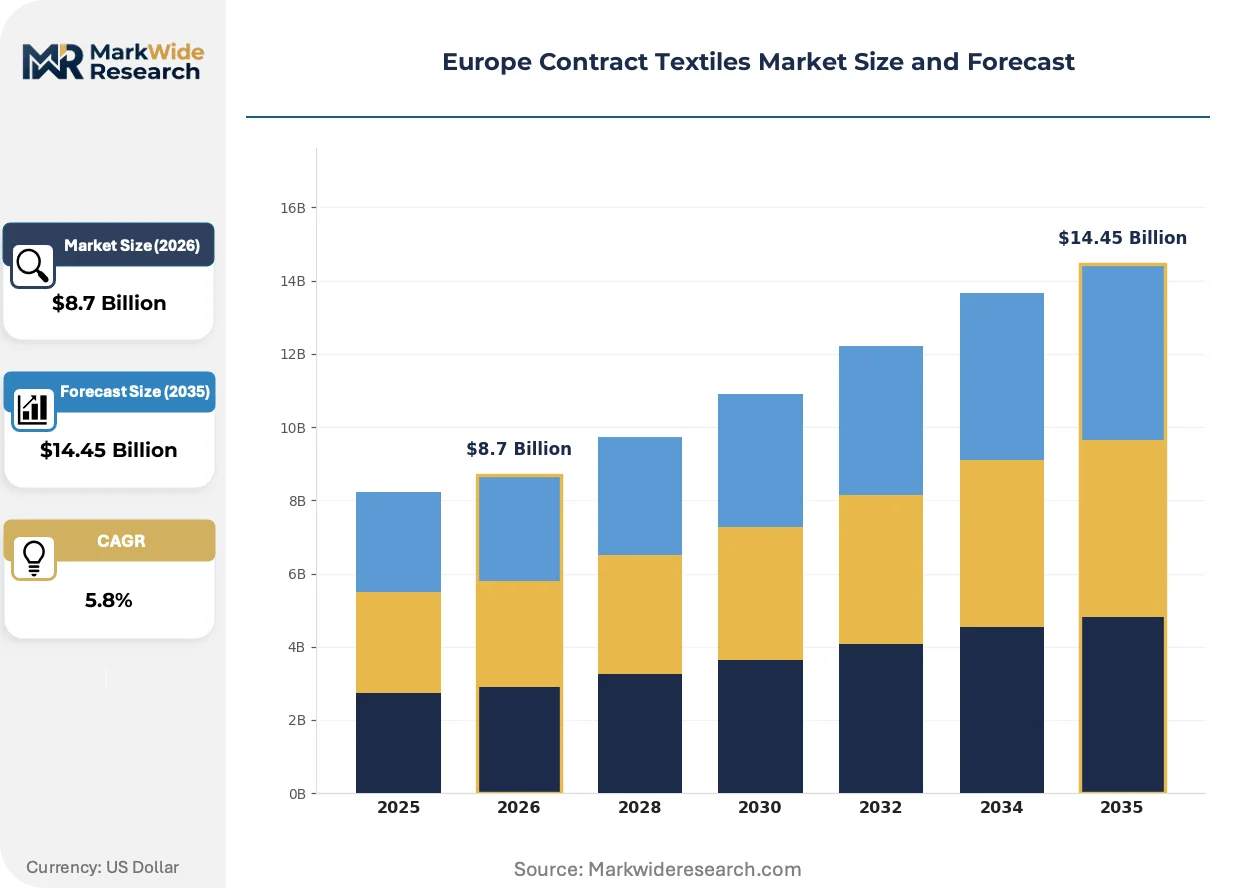
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upholstery, Curtains, Carpets, Wall Coverings Material: Cotton, Polyester, Wool, Acrylic End User: Hotels, Offices, Hospitals, Restaurants Application: Commercial, Residential, Educational, Healthcare |
| Companies Covered | Camira Fabrics Ltd., Panaz, Sunbury Design, Gabriel A/S, Agua Fabrics, DELIUS, Beaulieu International Group, Successori REDA S.p.A., Architex, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Contract Textiles Market Trends and Innovations
Material science convergence with digital manufacturing is collapsing traditional lead times while regulatory chemistry restrictions are forcing fundamental reformulation of performance finishes.
Recycled polyethylene terephthalate (rPET) fiber production is absorbing post-consumer bottle waste streams into contract-grade yarn specifications. Hospitality procurement teams in the Netherlands and Belgium are specifying minimum recycled content thresholds in framework agreements. This material transition is absorbing price volatility in virgin polymer markets while compressing the cost premium historically attached to sustainability credentials.
EU AI Act transparency provisions are extending to automated sorting infrastructure for post-consumer textile collection. Industrial laundries and hospitality fleet operators must now document algorithmic decision-making in recycling handoffs. Wall covering and upholstery segments with shorter replacement cycles face accelerated compliance timelines compared to heavy-duty seating applications.
Consolidated vendor frameworks are displacing project-by-project specification among European hospitality chains. Procurement directors at multi-property groups are negotiating multi-year supply agreements with volume guarantees and exclusive color development rights. This concentration is most visible in German hotel refurbishment programs, where single-source upholstery contracts now span fifty-plus property rollouts.
Europe Contract Textiles Market Segmentation
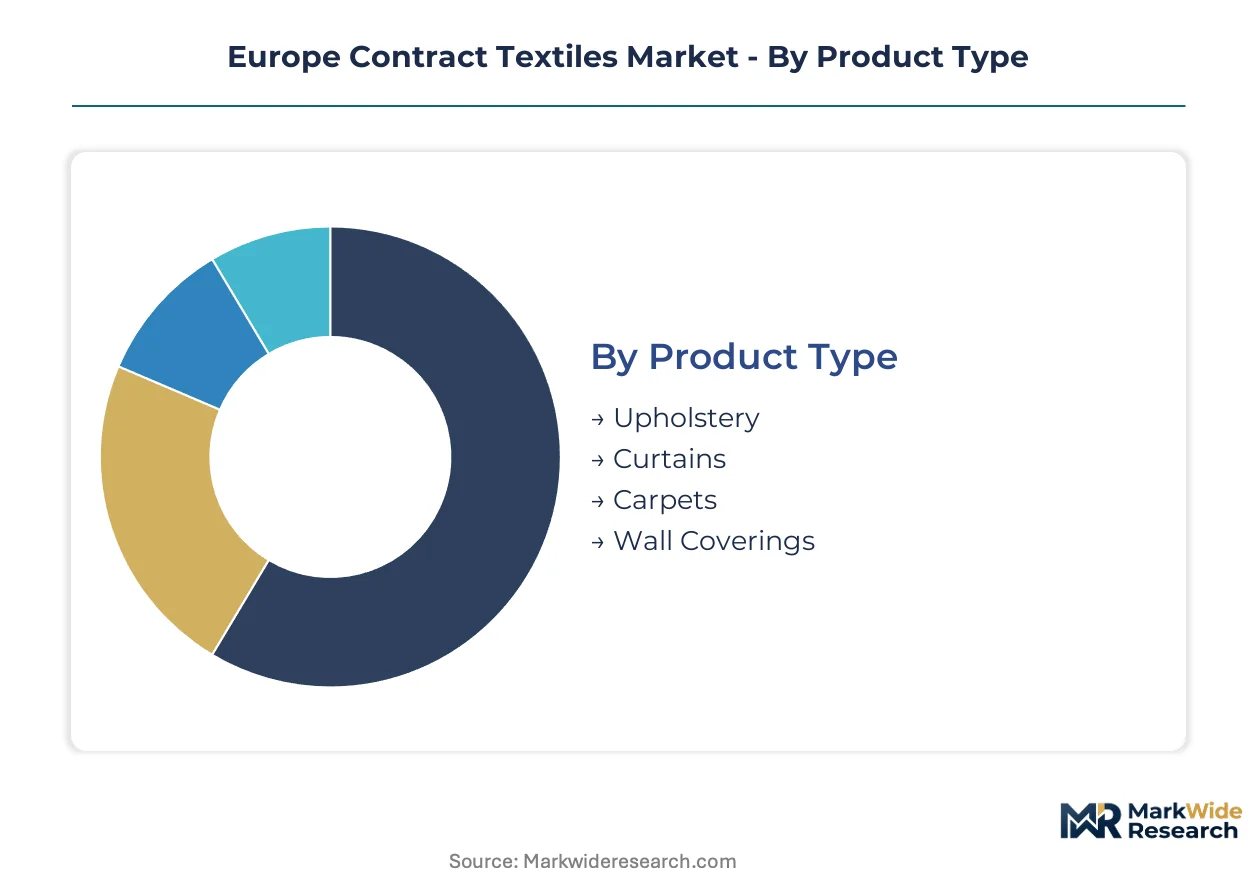
Contract textile procurement in Europe operates through parallel specification tracks: standalone replacement cycles for visible soft furnishings versus integrated systems where fabric performance must synchronize with fixed architectural elements. Understanding these integration patterns clarifies where suppliers capture recurring revenue versus one-time project margins.
Product Type:
Integration depth separates segments that ship as finished goods from those requiring field coordination with installers and fire safety consultants.
- Upholstery:Woven and knitted constructions meeting ISO 12947 martindale abrasion thresholds, typically back-coated for dimensional stability in institutional laundering cycles. German hotel refurbishment programs concentrate procurement volume here, driven by fifty-plus property rollouts demanding synchronized color consistency across seating fleets.
- Wall Coverings:Acoustic-performance textiles integrating sound absorption with REACH-compliant flame retardancy, increasingly specified in Nordic open-plan office redesigns. The EU Green Deal's circularity mandates compress lead times as architects bundle these with modular partition systems.
- Curtains:Flame-retardant drapery for hospitality and healthcare window treatments, requiring coordination with motorized track installers.
- Carpets:Broadloom and tile formats for commercial traffic areas, specified through flooring contractors rather than direct textile procurement.
Volume placements concentrate in Upholstery; the faster expansion belongs to Wall Coverings.
Material:
Cost tier stratification aligns raw material selection with end-use durability requirements and regulatory compliance burdens.
- Polyester:Solution-dyed fibers delivering inherent colorfastness and flame resistance without post-dye chemical finishes, capturing specification share from natural fibers in high-traffic seating. Cost scalability and REACH reformulation resilience position this material for volume hospitality contracts across France and the UK.
- Wool:Premium wool blends engineered for martindale abrasion performance in heritage hospitality settings, with New Zealand and Australian fiber auctions transmitting direct cost instability to upholstery lines. Gabriel A/S anchors portfolio positioning here through durable construction expertise.
- Cotton:Natural fiber specifications declining in commercial applications due to flame-retardant treatment compliance costs under ECHA evaluations.
- Acrylic:Synthetic alternative for outdoor and marine contract applications, limited by indoor air quality certification constraints.
Polyester commands placement volume; wool maintains premium positioning despite price volatility.
End User:
Customer type determines specification authority concentration versus fragmented project-based procurement.
- Hotels:Consolidated vendor frameworks now displace project-by-project purchasing, with multi-property groups negotiating multi-year supply agreements carrying volume guarantees and exclusive color development rights. Procurement leverage is broadening most visibly in German refurbishment cycles.
- Offices:Corporate real estate teams specifying acoustic wall coverings and durable upholstery for flexible workspace configurations, with Nordic markets leading performance prioritization.
- Hospitals:Healthcare-acquired infection protocols driving copper-infused and photocatalytic surface treatments, opening specification pathways previously blocked by antimicrobial chemical restrictions.
- Restaurants:High-frequency replacement demand for seating upholstery, constrained by silver-ion and triclosan treatment bans under REACH Annex XVII.
Hotel chains consolidate procurement power; healthcare facilities present the steepest specification trajectory.
Application:
Maturity gradients separate established commercial specifications from emerging residential and educational adoption curves.
- Commercial:Mature specification track encompassing offices, hospitality, and retail environments with standardized flame-retardant and abrasion testing protocols. ECHA substance evaluations are accelerating R&D investment in bio-based flame retardants here.
- Healthcare:Institutional laundering requirements and infection control protocols creating specialized performance thresholds for upholstery and privacy curtains.
- Educational:University and school procurement increasingly adopting contract-grade durability specifications, though budget constraints limit premium material penetration.
- Residential:Minimal penetration due to consumer preference for fashion-driven aesthetics over industrial performance ratings, with limited regulatory pressure to upgrade specifications.
Commercial applications anchor volume; healthcare specifications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospitality procurement concentration in Germany is reshaping supplier economics across the continent, with synchronized renovation cycles in France and the UK amplifying contract volumes for flame-retardant upholstery and acoustic wall systems.
Germany
Large-scale hotel refurbishment programs and corporate office modernization are driving contract textile procurement volumes. The EU Green Deal's circularity mandates are accelerating supplier qualification timelines for fiber traceability documentation. Frankfurt and Munich host the continent's densest clusters of hospitality specification consultants coordinating multi-property rollouts.
United Kingdom
Consolidated vendor frameworks among London-based hospitality chains are compressing supplier margins while extending contract durations. REACH restrictions on chemical finishes are forcing reformulation of stain-resistant treatments for restaurant upholstery. Yorkshire and Lancashire retain significant weaving capacity serving both domestic and export contract markets.
France
Heritage hospitality properties in Paris and Lyon sustain premium wool-blend specifications despite raw material cost volatility. ECHA substance evaluations under REACH Annex XVII are eliminating silver-ion antimicrobial treatments previously standard in healthcare applications. The Lyon textile cluster specializes in solution-dyed polyester production for high-traffic seating contracts.
Italy
Dye house concentration in Northern Italy—particularly around Como and Biella—creates single-point vulnerability for EU-wide finishing capacity. CSRD disclosure mandates are exposing data architecture gaps among mid-tier weaving operations in the region. Milan serves as the primary specification hub for luxury hospitality projects requiring custom color development.
Netherlands
Procurement teams in Amsterdam and Rotterdam are mandating minimum recycled content thresholds in multi-year framework agreements. The EU AI Act's transparency requirements are extending to automated textile sorting infrastructure for post-consumer collection. Eindhoven's technical textile research institutes are piloting computer-vision enabled fiber separation systems.
Europe Contract Textiles Market Competitive Landscape
British producers anchor the premium upholstery tier; Danish and Italian specialists hold differentiated positions in wool engineering and rapid color matching. The vendor base splits between vertically integrated yarn-to-fabric operators and weaving-focused finishers dependent on third-party dye houses. Three archetypes dominate: captive yarn producers controlling fiber provenance, custom color developers serving hospitality rollouts, and durable construction specialists engineering for martindale abrasion thresholds. Competitive moves concentrate on backward integration into yarn production and blockchain-enabled traceability platform deployment.
Within the integrated production tier, Camira Fabrics Ltd. and Gabriel A/S occupy positions emphasizing upstream control over fiber supply chains. Panaz exemplifies the rapid-response archetype, serving hospitality procurement teams with accelerated color development cycles. These three anchors illustrate how competitive positioning stratifies across manufacturing depth, customization velocity, and performance engineering specialization.
| Leading Market Players |
|---|
| Camira Fabrics Ltd. |
| Panaz |
| Sunbury Design |
| Gabriel A/S |
| Agua Fabrics |
| DELIUS |
| Beaulieu International Group |
| Successori REDA S.p.A. |
| Architex |
| Others |
Pricing and Supply Chain Analysis
Solution-dyed polyester fiber costs transmit directly through three pricing tiers, with virgin polymer volatility compressing margins in standard-grade upholstery while REACH compliance investments elevate premium wool-blend quotations. Northern Italian dye house concentration amplifies price leverage for finishing-dependent weavers serving German hospitality chains.
Pricing Analysis
Volume placements cluster in contract-based long-term offtake agreements, while spot procurement for custom color development captures margin premiums. Price differentiation rests on martindale abrasion certification grade and exclusive color development rights. Pricing pressure stems from consolidated vendor frameworks among multi-property hospitality groups demanding synchronized rollout pricing. Mid-tier weaving operations exhibit highest price sensitivity; vertically integrated yarn producers maintain greatest pricing resilience.
Supply Chain Analysis
Direct-to-hospitality procurement channels handle consolidated buyer demand, bypassing traditional textile distributors. Supply concentrates in Germany, the United Kingdom, and Italy, with raw material dependencies on New Zealand wool auctions, solution-dyed polyester from Lyon, and finishing chemicals from Como. Single-source vulnerability pervades Northern Italian dye house clustering. Distribution runs through specification consultants coordinating multi-property rollouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal compliance costs are forcing a consolidation play, with REACH reformulation timelines eliminating capital-constrained finishers unable to fund bio-based flame retardant R&D.
For Market Incumbents: Anchor market position through backward integration into solution-dyed yarn production, eliminating dye house dependency. Secure captive wool supply through direct New Zealand auction contracts to neutralize fiber price volatility. ECHA substance evaluation acceleration threatens established antimicrobial treatment lines; redirect R&D toward copper-infused surface technologies.
For New Entrants and Emerging Players: Independent healthcare facilities represent the most penetrable buyer archetype, with infection control protocols creating specification entry points blocked to legacy suppliers. Nordic open-plan office acoustic wall covering demand offers white-space expansion with lower incumbent saturation. Pursue rapid martindale certification partnerships with German testing laboratories to compress product launch timelines.
For Investors and Strategic Acquirers: CSRD Tier 2 disclosure mandate expansion is the leading indicator that fiber traceability infrastructure will determine supplier viability. Five-to-ten year positioning favors acquisition of mid-tier weavers with blockchain-enabled provenance systems already deployed. Monitor ECHA substance evaluation announcements for reformulation-driven distress opportunities among finishers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yarn Production | Eliminates dye house concentration risk while capturing REACH compliance cost recovery. |
| Blockchain-Enabled Fiber Traceability Platform | Positions suppliers for CSRD Tier 2 disclosure mandates affecting German hospitality procurement. |
| Acoustic Wall Covering Specification Partnership | Captures Nordic open-plan office redesign demand bundling sound absorption with fire safety. |
| Bio-Based Flame Retardant R&D Investment | Creates first-mover advantage as ECHA evaluations eliminate legacy chemical treatments. |
| Multi-Year Hospitality Framework Agreement | Locks volume guarantees and exclusive color development rights across fifty-plus property rollouts. |
Research Methodology
Multi-period observation of ECHA substance evaluation timelines, REACH reformulation announcements, and hospitality procurement framework consolidations anchored the trend analysis, supplemented by interviews with specification consultants, procurement directors at multi-property hospitality groups, technical directors at dye house operations, and sustainability compliance officers. Secondary validation drew from EU Green Deal implementation bulletins, CSRD disclosure requirement drafts, ISO 12947 certification records, and New Zealand wool auction data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segment-weighting across product type, material composition, end-user category, and application maturity shaped the analytical framework. CAGRs derived from regression analysis of historical procurement volumes against renovation cycle timing and regulatory implementation schedules. Industry-specific forecast inputs incorporated martindale testing capacity constraints and automated textile sorting infrastructure deployment curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance evaluation acceleration, wool auction price spikes, and CSRD scope expansion beyond Tier 1 disclosure. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Technical Textile Market
Technical Textiles
Smart Fabrics for Sports and Fitness Market
Technical Textiles
Aramid Conveyor Belt Market
Technical Textiles
Global Agricultural Textiles Market
Technical Textiles
Smart Sports Textile Market
Technical Textiles
Blackout Fabric Market
Technical Textiles
Webbing Market
Technical Textiles
Waterproof Fabrics Market
Technical Textiles
Wet-Molded Fibre Market
Technical Textiles
Blackout Fabric Laminates Market
Technical Textiles
Global PTFE Fabric Market
Technical Textiles
Waterproof Breathable Textiles (WBT) Market
Technical Textiles
Geotextiles and Geogrids Market
Technical Textiles
Global Conductive Textiles Market
Technical Textiles
Global Geotextile Market
Technical Textiles
Pavement Overlay Fabrics Market