
 Indonesia Home Textile Market | 2026-2036
Indonesia Home Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Home Textile Market Foresight
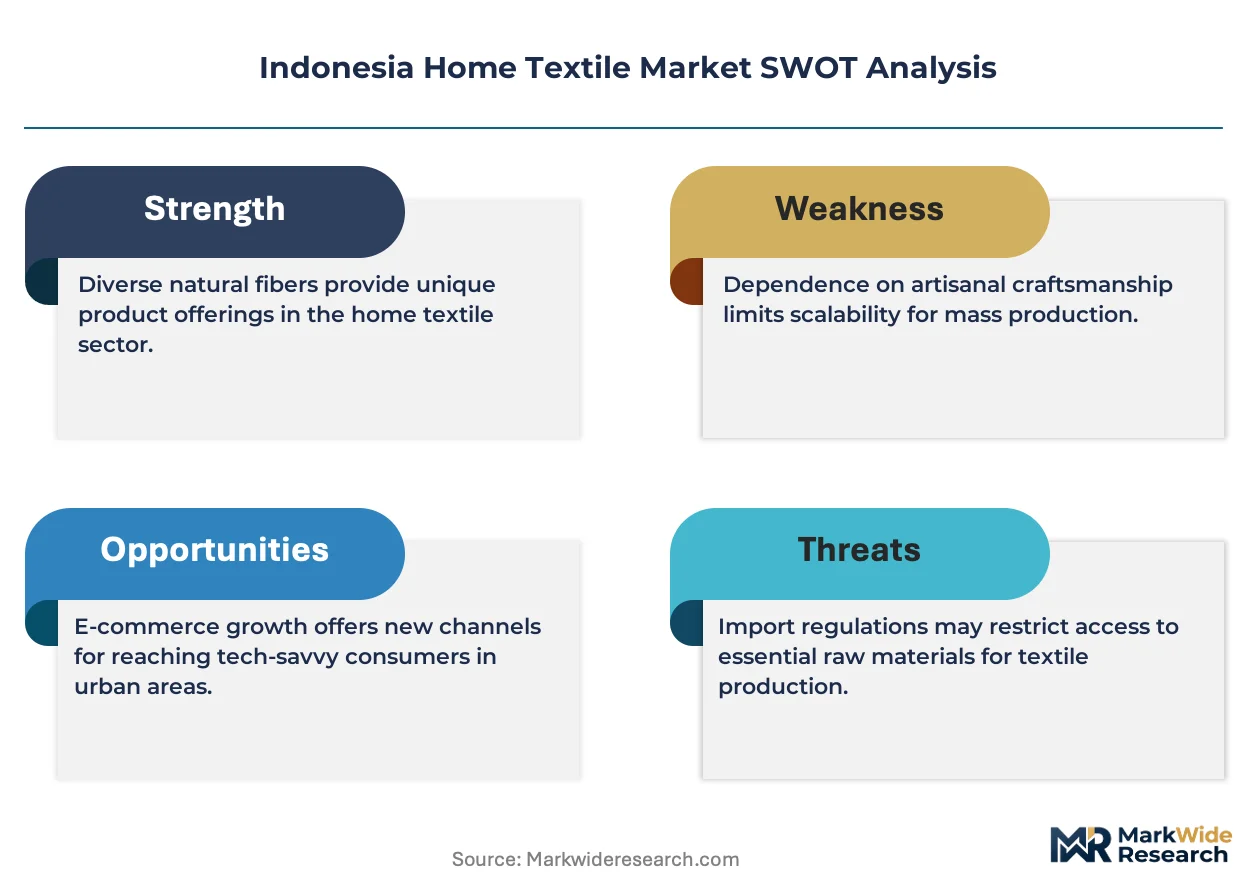
Subscription-based fabric care and refresh services for premium home textiles is rebalancing how Indonesian consumers acquire and maintain bedding and drapery. Ateja leverages its integrated weaving and finishing facilities to control quality from fiber to finished curtain panels. PT Panjimas Textile anchors supply to hospitality developers across Jakarta and Bali with specialized fire-resistant treatments. Sinar Group differentiates through vertical mastery of polyester spinning, sustaining cost advantages in mass-market bed linen.
Indonesia home textiles encompass woven, knitted, and non-woven fabric products designed for interior residential and commercial environments, typically manufactured from natural fibers like cotton and linen or synthetics like polyester through processes including ring spinning, air-jet weaving, and reactive dyeing, with functional specifications covering thread count, abrasion resistance, and colorfastness to serve decorative, protective, and comfort purposes. Bed linen commands the largest revenue pool due to replacement frequency in tropical climates, while curtains capture margin concentration through custom sizing and premium finishing. Cotton sustains volume leadership across residential channels, though polyester is accelerating fastest in hospitality procurement where durability and stain resistance outweigh breathability preferences.
BIS-equivalent SNI certification enforced by Indonesia's National Standardization Agency shapes product compliance costs for domestic mills, while the Ministry of Industry's Making Indonesia 4.0 textile roadmap pushes automation adoption in dyeing and finishing. The Ministry of Environment and Forestry regulates wastewater discharge from textile wet processing, elevating capital requirements for smaller producers in Central Java clusters. Stakeholders must monitor how evolving eco-label requirements and digital traceability mandates reshape supplier qualification criteria across archipelago distribution networks.
Market Dynamics
Indonesia's Ministry of Industry textile modernization incentives are compressing technology adoption timelines across Central Java dyeing clusters, while SNI mandatory certification restructures supplier qualification barriers for domestic mills serving hospitality procurement in Bali and Jakarta.
Growth Catalysts
- Residential Premiumization:Rising middle-class households in Surabaya and Bandung are expanding replacement demand for thread-count-differentiated bed linen and custom-finished curtains in tropical climate conditions.
- Regulatory Quality Upgrades:Indonesia's National Standardization Agency enforces BIS-equivalent SNI certification, accelerating capital investment in reactive dyeing and air-jet weaving automation across domestic manufacturing clusters.
- Hospitality Procurement Concentration:Hotel developments in Bali and Jakarta are concentrating demand for fire-retardant upholstery fabrics with specified abrasion resistance thresholds.
Market Restraints
- Input Cost Volatility:Cotton fiber prices fluctuate with global commodity markets, compressing margin stability for natural-fiber-focused residential bedding producers in Bandung.
- Wastewater Compliance Burden:Indonesia's Ministry of Environment and Forestry discharge regulations elevate capital requirements for wet processing facilities, disproportionately affecting smaller Central Java producers.
- Polyester Substitution Pressure:Synthetic fiber alternatives accelerate in hospitality channels where durability specifications override breathability preferences, displacing cotton volume in institutional procurement.
Strategic Opportunities
- Eco-Label Traceability:Digital fiber-to-finished-goods tracking systems create qualification advantages for mills supplying sustainability-focused hotel developers in Jakarta.
- Subscription Refresh Services:Fabric care and replacement cycles for premium residential textiles enable recurring revenue models among Surabaya middle-class households.
- Automation Incentive Capture:Indonesia's Making Indonesia 4.0 textile roadmap offers pathway for dyeing and finishing facilities to secure modernization grants.
Industry Challenges
- Certification Timeline Compression:SNI mandatory certification requires extensive laboratory testing for colorfastness and thread count verification, extending product launch cycles for new entrants.
- Technical Skill Scarcity:Automated air-jet weaving and reactive dyeing process control demands specialized technician training that outpaces vocational pipeline output in Central Java textile clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Home Textile Market |
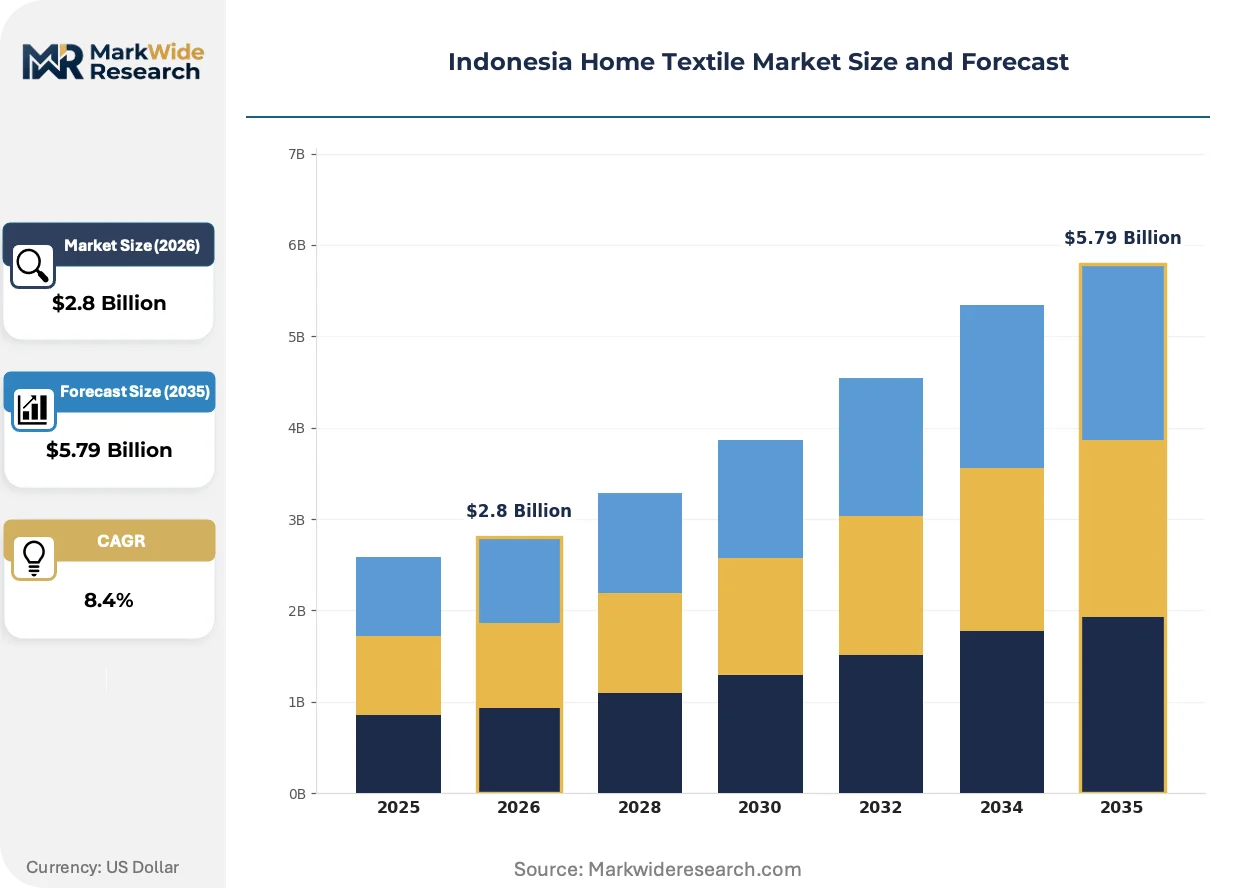
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Curtains, Bed Linen, Table Linen, Cushions Material: Cotton, Polyester, Linen, Silk End User: Residential, Hospitality, Retail, Institutional Distribution Channel: Online, Offline, Supermarkets, Specialty Stores |
| Companies Covered | Ateja, PT Panjimas Textile, Sinar Group, PT Asia Pacific Fibers Tbk, PT Sri Rejeki Isman Tbk, PT Indah Jaya Textile Industry, Dunlopillo, PT Lotus Indah Textile Industries, PT Tyfountex Indonesia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Home Textile Market Shifts & Advancements
Digital traceability platforms and reactive dyeing automation are restructuring how Indonesian mills qualify for hospitality procurement and residential premium channels, compressing traditional supplier hierarchies.
Air-jet weaving technology with computerized pattern control is consolidating quality consistency in curtain panel production. Jakarta hospitality developers specify these systems for fire-retardant upholstery procurement. The technology is consolidating mid-tier mills' access to premium contract segments previously reserved for integrated weaving-finishing facilities.
Indonesia's Ministry of Environment and Forestry wastewater discharge regulations are forcing wet processing consolidation. Central Java dyeing clusters face capital thresholds for effluent treatment installation. Smaller producers without integrated finishing capabilities are exiting hospitality supply chains as compliance costs rise.
Subscription-based fabric refresh services are emerging as an alternative ownership model for Surabaya and Bandung residential buyers. Traditional retail bedding replacement cycles compress as middle-class households adopt managed maintenance programs. This pattern concentrates most visibly in urban condominium developments with limited storage for seasonal textile rotation.
Indonesia Home Textile Market Segmentation
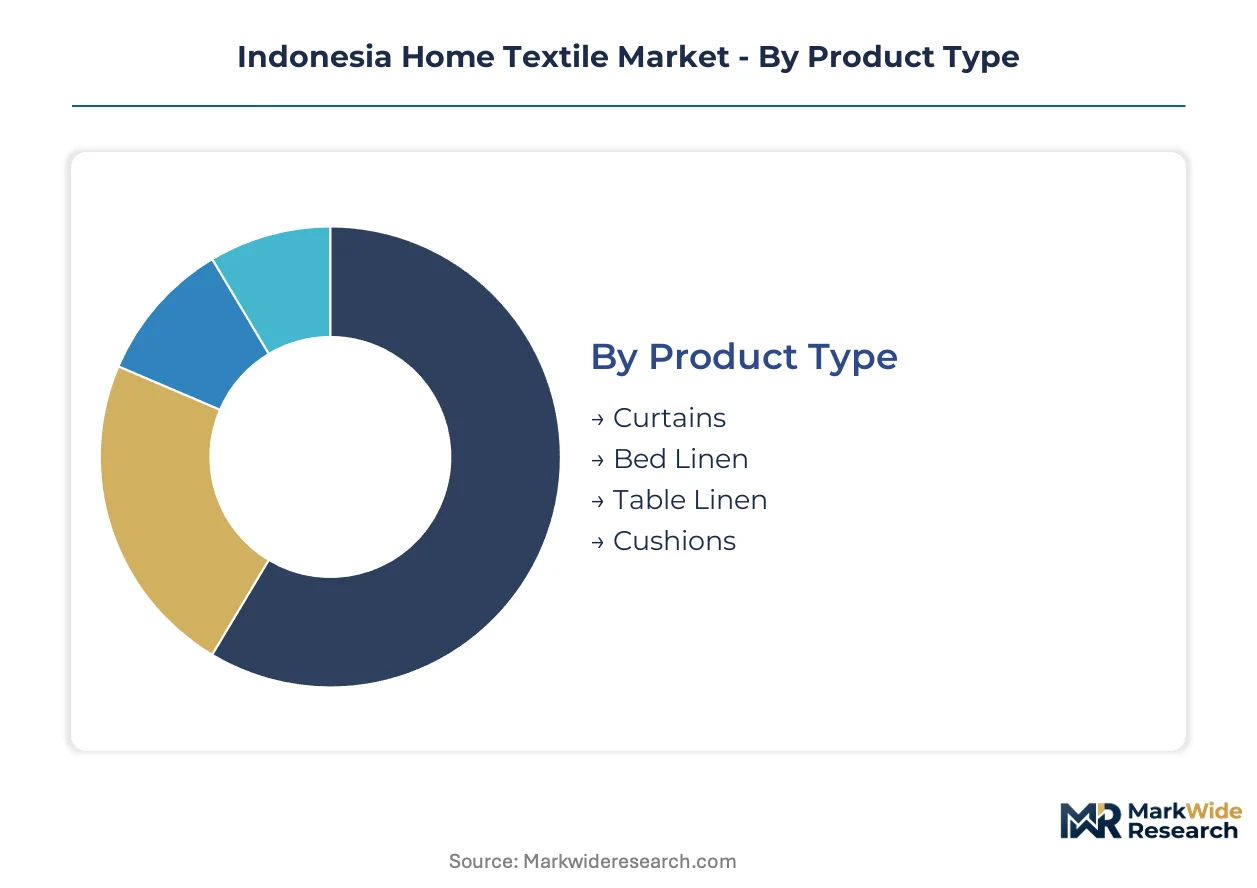
Segmentation in the Indonesia home textile market exposes divergent margin structures across tropical climate residential replacement cycles and hospitality durability specifications. Understanding these splits enables suppliers to align capital deployment between commodity volume plays and premium contract manufacturing.
Product Type:
Volume concentration sits in high-frequency replacement categories, while premium capture clusters in custom-finished applications with sizing complexity.
- Bed Linen:Woven and knitted sheets, pillowcases, and duvet covers manufactured through ring spinning and reactive dyeing processes with thread-count differentiation. Surabaya and Bandung middle-class households drive replacement demand in tropical humidity conditions where laundering frequency accelerates wear cycles.
- Curtains:Air-jet woven drapery panels with computerized pattern control and custom finishing specifications. Bali and Jakarta hotel developers concentrate procurement for fire-retardant treatments with specified abrasion resistance thresholds, capturing margin through bespoke sizing.
- Table Linen:Dining textiles with stain-resistant finishing for hospitality table service applications.
- Cushions:Decorative and functional upholstery inserts with polyester fiberfill or down-alternative construction for residential accent markets.
Today's leader: Bed Linen. Tomorrow's challenger: Curtains.
Material:
Natural fiber dominance in residential channels confronts synthetic acceleration where institutional durability specifications override breathability preferences.
- Cotton:Ring-spun natural fiber with reactive dyeing compatibility and moisture absorption properties suited to tropical climates. Volume leadership persists across Surabaya and Bandung residential channels, though input cost volatility from global commodity markets compresses margin stability.
- Polyester:Synthetic staple and filament fibers manufactured through melt spinning with inherent stain resistance and dimensional stability. Hospitality procurement in Bali and Jakarta accelerates fastest where fire-retardant specifications and abrasion resistance outweigh cotton's breathability advantages.
- Linen:Bast fiber from flax with superior moisture wicking and textural premium positioning for high-end residential curtains.
- Silk:Protein fiber with luxury positioning in decorative cushion and specialty curtain applications.
Cotton commands current volume. Polyester gains share fastest on hospitality contract wins.
End User:
Customer type determines specification intensity, with institutional buyers enforcing certification barriers that residential channels ignore.
- Residential:Individual household procurement through retail and online channels with replacement-driven purchasing patterns. Surabaya and Bandung middle-class expansion concentrates demand for thread-count-differentiated bed linen and custom-finished curtains in condominium developments.
- Hospitality:Hotel and resort developers in Bali and Jakarta specifying fire-retardant upholstery fabrics with SNI certification compliance and documented abrasion resistance. Procurement concentration elevates supplier qualification barriers through mandatory laboratory testing.
- Retail:Branded home goods chains and department store buyers sourcing private-label textile collections.
- Institutional:Healthcare, education, and government facility procurement with standardized durability specifications.
Residential anchors volume throughput. Hospitality restructures supplier hierarchies through certification mandates.
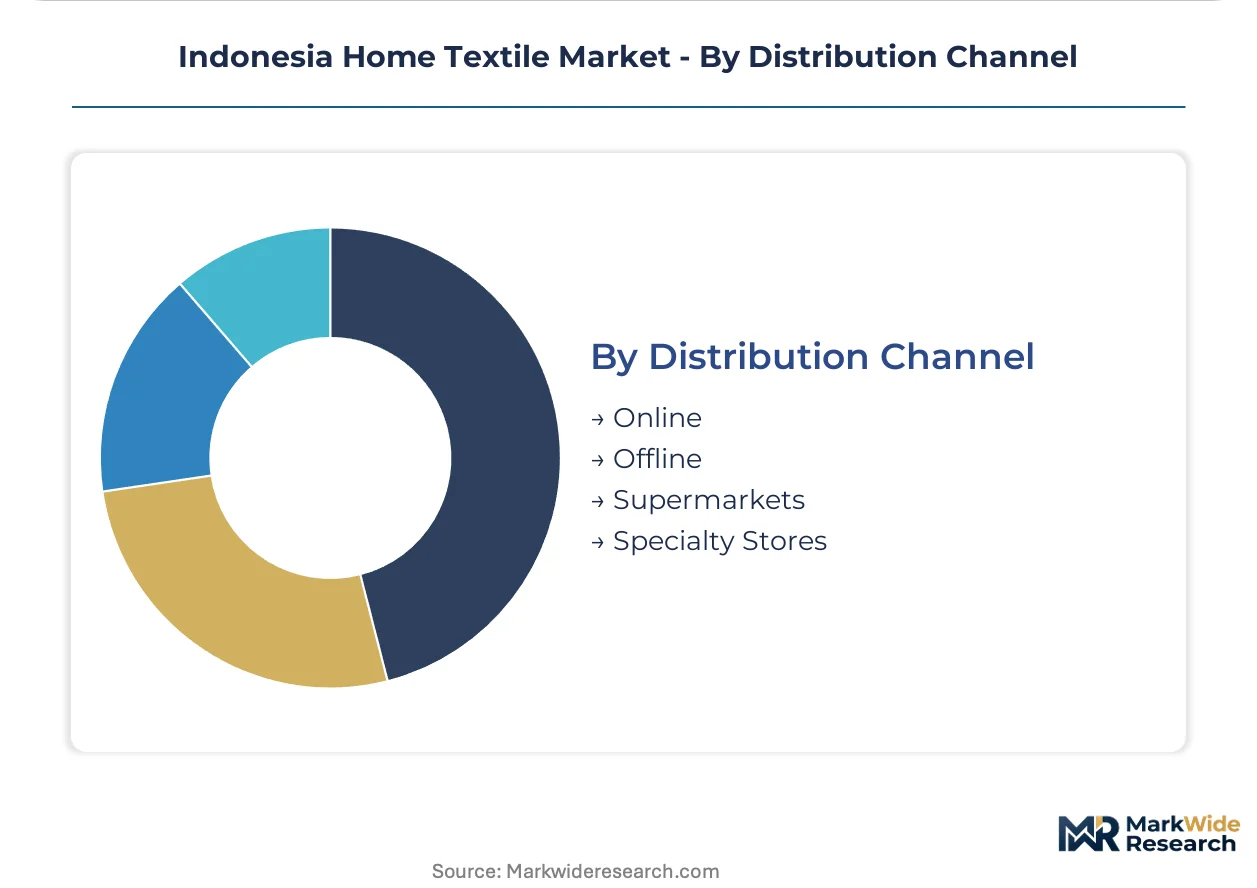
Distribution Channel:
Channel selection correlates with customer sophistication, separating specification-heavy contract sales from convenience-driven replacement purchasing.
- Online:E-commerce platforms and direct-to-consumer digital storefronts enabling subscription-based fabric refresh services. Surabaya urban condominium households adopt managed maintenance programs with limited storage for seasonal textile rotation.
- Offline:Traditional brick-and-mortar retail with tactile evaluation for thread count and finishing quality. Bandung residential buyers maintain preference for physical inspection of premium bed linen.
- Supermarkets:Mass-market volume channels for standardized bed linen with economy positioning.
- Specialty Stores:Curated retail environments for custom curtain sizing and premium material selection.
Offline retains premium textile preference. Online enables recurring revenue model innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest home textile manufacturing base worldwide, while Indonesia accelerates fastest among Southeast Asian producers through government modernization incentives and hospitality sector expansion.
China
Shaoxing and Nantong textile clusters dominate global bed linen and curtain panel output through automated air-jet weaving at scale. China's Ministry of Industry and Information Technology enforces GB standards for textile quality and environmental compliance in wet processing. Zhejiang Province manufacturers supply fire-retardant upholstery fabrics to international hotel chains, leveraging integrated dyeing-finishing capabilities.
India
Surat and Tirupur cotton spinning centers drive residential bedding volume for domestic middle-class households and export markets. India's Bureau of Indian Standards mandates ISI certification for textile quality, while the Production Linked Incentive scheme subsidizes technical textile modernization. Maharashtra-based mills expand polyester hospitality fabric capacity to compete with Indonesian suppliers.
Vietnam
Ho Chi Minh City and Binh Duong provinces attract foreign direct investment in synthetic fiber spinning for export-oriented upholstery manufacturing. Vietnam's Ministry of Industry and Trade implements technical barriers to trade aligned with EU market access requirements. Central region dyeing clusters face wastewater treatment mandates from the Ministry of Natural Resources and Environment.
Bangladesh
Dhaka and Chittagong export processing zones concentrate on cotton bed linen for European retail private-label contracts. The Bangladesh Garment Manufacturers and Exporters Association coordinates compliance with EU GSP+ preferential trade rules. Narayanganj wet processing facilities invest in effluent treatment to meet retailer sustainability audit standards.
Thailand
Bangkok metropolitan area and Pathum Thani province host specialty textile operations for regional hospitality procurement. Thailand's Industrial Standards Institute enforces TISI certification for fire safety in upholstery applications. Eastern Economic Corridor incentives attract Japanese and Korean joint ventures in technical textile finishing.
Indonesia Home Textile Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated weaving-finishing facilities commanding hospitality procurement while retail-focused spinners dominate residential volume. Three archetypes define competitive positioning: vertically integrated mills controlling fiber-to-fabric production, specialized dyeing-finishing subcontractors serving multiple weavers, and brand houses outsourcing manufacturing to certified suppliers. Consolidation pressures concentrate among smaller Central Java wet processors facing wastewater compliance thresholds. Capacity expansion and automation grant capture represent the dominant competitive vectors.
Among Indonesia-based producers, Ateja, PT Panjimas Textile, and Sinar Group occupy distinct positions within this structure. Ateja represents the integrated mill archetype with captive weaving and finishing capabilities. PT Panjimas Textile exemplifies hospitality-focused specialization through fire-resistant treatment expertise. Sinar Group anchors the synthetic fiber vertical, controlling polyester spinning upstream. These three entities illustrate how Indonesian competitors differentiate through supply chain positioning rather than brand recognition alone.
| Leading Market Players |
|---|
| Ateja |
| PT Panjimas Textile |
| Sinar Group |
| PT Asia Pacific Fibers Tbk |
| PT Sri Rejeki Isman Tbk |
| PT Indah Jaya Textile Industry |
| Dunlopillo |
| PT Lotus Indah Textile Industries |
| PT Tyfountex Indonesia |
| Others |
Supply & Pricing Matrix
Air-jet weaving automation across Central Java dyeing clusters compresses unit economics while concentrating production among capitalized mills, simultaneously lowering per-meter fabric costs and restructuring supplier hierarchies toward integrated weaving-finishing facilities. Indonesia's Ministry of Industry modernization incentives accelerate this transition, rewarding automation adoption with grant capture that reshapes competitive cost positioning.
Pricing Analysis
Capacity additions in Central Java are reshaping price floors for standard-grade bed linen as automated mills achieve thread-count consistency at lower labor intensity. Three-tier pricing structure across premium certification-grade, standard SNI-compliant, and economy non-certified levels separates hospitality procurement from residential replacement cycles. Cost compression in mass-market polyester bedding intensifies because Sinar Group's captive spinning advantages transmit downstream. Budget-conscious residential buyers in Surabaya exhibit highest price sensitivity, while Jakarta hotel developers prioritize abrasion resistance thresholds over unit cost.
Supply Chain Analysis
Cotton fiber supply rests on Indonesian agricultural output supplemented by Australian and Indian import flows, with polyester staple drawing from China and domestic PT Asia Pacific Fibers Tbk production. Reactive dyeing chemicals and fire-retardant treatment formulations hinge on Japanese and German specialty chemical imports. Single-source vulnerability concentrates in advanced finishing chemicals where European suppliers dominate hospitality certification requirements. Distribution runs through Jakarta-centered wholesale networks serving Bali hospitality clusters and Surabaya-Bandung residential retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's home textile market compounds steadily through residential middle-class expansion in Surabaya and Bandung, where tropical climate replacement cycles and condominium living patterns sustain predictable demand velocity.
For Market Incumbents: Hedge cotton input volatility through backward integration into polyester spinning or long-term fiber supply agreements with Australian growers. Capture Ministry of Industry automation grants to defend cost position against Vietnamese synthetic fiber competitors. Prioritize SNI certification maintenance as hospitality procurement barriers tighten. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest friction entry path for Surabaya urban households with limited textile storage and managed refresh preferences. Target premium curtain customization for Jakarta condominium developers seeking fire-retardant specifications without integrated mill relationships. Launch with digital fabric sampling and virtual measurement tools to bypass offline retail real estate requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among Central Java wet processors facing wastewater compliance thresholds and consolidation pressure. Five-to-ten year viability favors integrated weaving-finishing facilities with captive dyeing capabilities and hospitality certification track records. Monitor SNI audit backlog timelines as inflection indicator for supplier qualification bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Grant Capture | Ministry of Industry Making Indonesia 4.0 incentives compress payback periods for air-jet weaving investments. |
| SNI Certification Investment | National Standardization Agency compliance opens hospitality procurement channels in Bali and Jakarta developments. |
| Subscription Service Launch | Recurring revenue models align with Surabaya middle-class household storage constraints and replacement preferences. |
| Backward Integration into Fiber | Captive polyester spinning insulates margin from global cotton commodity volatility affecting Bandung bedding producers. |
| Digital Traceability Platform | Fiber-to-finished-goods tracking satisfies Jakarta hotel developer sustainability audit requirements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with textile mill operations directors, hospitality procurement managers at Jakarta and Bali hotel developers, retail category buyers, and Ministry of Industry program administrators with secondary validation against Indonesian Central Bureau of Statistics trade data, Ministry of Environment and Forestry discharge compliance records, and SNI certification registry filings. Bottom-up production capacity estimates and top-down expenditure flow analysis triangulated market sizing.
Segment-weighting applied product type, material composition, end-user category, and distribution channel dimensions across the projection horizon. CAGRs derived from elasticity-adjusted demand modeling incorporating tropical climate replacement frequency, middle-class household formation rates, and hospitality room stock expansion. Forecast inputs included Ministry of Industry automation incentive disbursement trajectories and SNI certification timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for air-jet weaving penetration would alter the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and fiber import tariff stability. A small set of triggers—SNI audit capacity constraints, cotton price spike duration, and wastewater treatment capital access—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
United States Home Textile Market
Home Textiles
Europe Home Textile Market
Home Textiles
Blanket Market
Home Textiles
Bangladesh Home Textile Market
Home Textiles
Plush Blanket Market
Home Textiles
Cotton Towel Market
Home Textiles
India Home Textile Market
Home Textiles
Home Textile Products Market
Home Textiles
Microfiber Cleaning Cloth Market
Home Textiles
South Korea Home Textile Market
Home Textiles
Textile Floorings Market
Home Textiles
Russia Home Textile Market
Home Textiles
China Home Textiles Market
Home Textiles
Linen Bed Sheets Market
Home Textiles
Australia Home Textiles Market
Home Textiles
Fabric Wash and Care Market