
 Latin America Textile Market | 2026-2036
Latin America Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Textile Market Foresight
The capital-intensity divergence between integrated spinners and trading-dependent converters is redrawing competitive boundaries across Latin America. Santana Textiles Group leverages captive yarn-to-fabric operations to sustain margin control in denim and knit basics. Vicunha Textil SA anchors its position through vertical dyeing and finishing capabilities that dominate Brazil's performance apparel supply chain. Kaltex SA differentiates via specialized upholstery and automotive textile production serving OEM assembly plants in Mexico.
Latin America textiles encompass natural and synthetic fiber-based materials engineered through weaving, knitting, or non-woven processes into fabrics with specified tensile strength, abrasion resistance, and dye-fastness properties for apparel, industrial, and consumer applications. Cotton retains structural dominance in regional production due to established ginning infrastructure across Brazil and Argentina, while polyester gains share from recycled PET feedstock integration in Mexican manufacturing. Technical textiles represents the fastest-expanding end-user segment, driven by medical, geotextile, and filtration specifications that command premium positioning over commodity fashion fabrics.
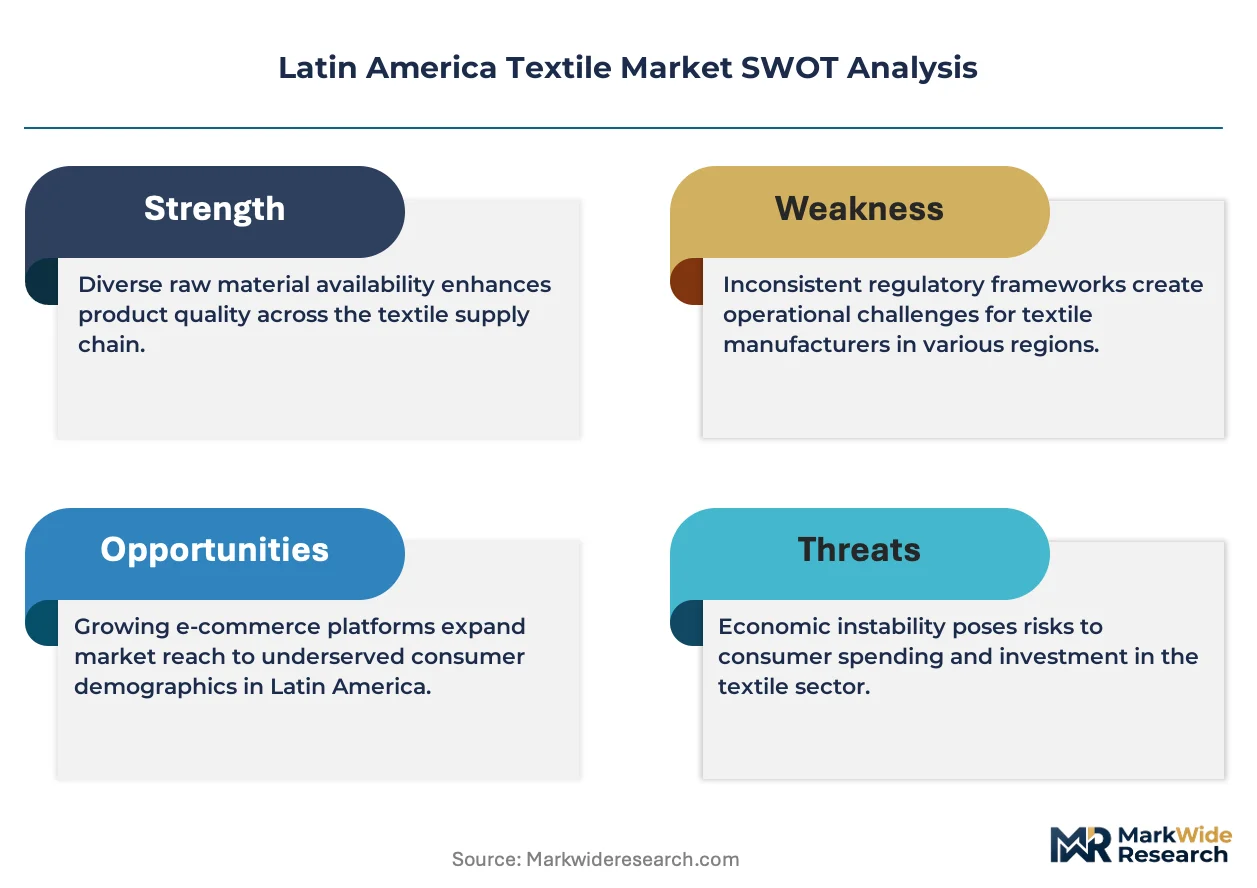
ANVISA regulates medical textile biocompatibility standards in Brazil, while Mexico's NOM certification mandates flammability and chemical safety thresholds for consumer fabrics; both frameworks elevate compliance costs for importers and create protected demand zones for certified domestic producers. Brazil's SEBI-linked sustainability disclosure rules for listed manufacturers and emerging ESG-linked credit facilities from regional development banks are reshaping capital allocation toward water recycling and renewable energy in dyeing operations. Stakeholders must monitor how nearshoring contract flows from US brands interact with evolving traceability requirements under pending EU deforestation regulation extraterritorial effects.
Market Dynamics
Nearshoring contract flows from US apparel brands are restructuring Latin American textile capacity allocation, with dyeing and finishing investments clustering in Mexico's Puebla-Tlaxcala corridor and Brazil's São Paulo industrial belt to compress lead times and bypass Asia-Pacific shipping bottlenecks.
Growth Catalysts
- ANVISA Medical Textile Standards:Brazil's biocompatibility certification requirements for surgical fabrics and wound care materials are creating protected demand zones for domestic producers capable of meeting Class II and III device specifications.
- Recycled PET Feedstock Integration:Mexican manufacturers are expanding polyester yarn production from post-consumer bottle waste, reducing virgin polymer dependency while qualifying for USMCA regional content rules in automotive upholstery applications.
- Performance Apparel Procurement:Fashion retail buyers in São Paulo and Mexico City are accelerating technical textile sourcing for moisture-wicking sportswear and compression garments serving fitness and outdoor recreation end-uses.
Market Restraints
- Cotton Input Volatility:Brazilian ginning infrastructure concentration in Mato Grosso and Goiás exposes spinners to climate-driven yield fluctuations and export parity pricing pressures from Chinese state reserve auctions.
- Dyehouse Energy Costs:Natural gas and electricity tariffs in Argentina and Colombia exceed regional medians, eroding margin recovery for commission finishers lacking captive thermal generation or renewable power purchase agreements.
- Import Substitution Thresholds:Mercosur common external tariff structures on synthetic filament yarn preserve Argentine weaving capacity but inflate raw material costs for Brazilian knitters relative to duty-advantaged Asian competitors.
Strategic Opportunities
- Geotextile Infrastructure Deployment:Colombian and Peruvian mining tailings dam regulations are mandating geosynthetic liner specifications, opening specification capture for regional non-woven producers with ISO 10319 tensile testing capabilities.
- SEBI-Linked Sustainability Finance:Brazil's exchange-mandated ESG disclosure rules for listed manufacturers are unlocking BNDES credit lines tied to water recycling and solar thermal dyeing retrofits, accelerating capital deployment toward low-carbon finishing.
- Automotive Textile Localization:OEM assembly plants in Aguascalientes and Resende are expanding just-in-time upholstery and airbag fabric sourcing from Mexican and Brazilian suppliers to satisfy USMCA automotive rules of origin.
Industry Challenges
- Dye Chemist Talent Scarcity:Formulation expertise for reactive and disperse dye compatibility with recycled polyester blends is concentrating among aging technical workforces in Blumenau and Torreón, constraining new product development velocity.
- Traceability System Integration:EU deforestation regulation extraterritorial enforcement is forcing cotton spinners to retrofit blockchain-based farm-to-fabric documentation onto legacy ERP platforms without standardized data interchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Textile Market |
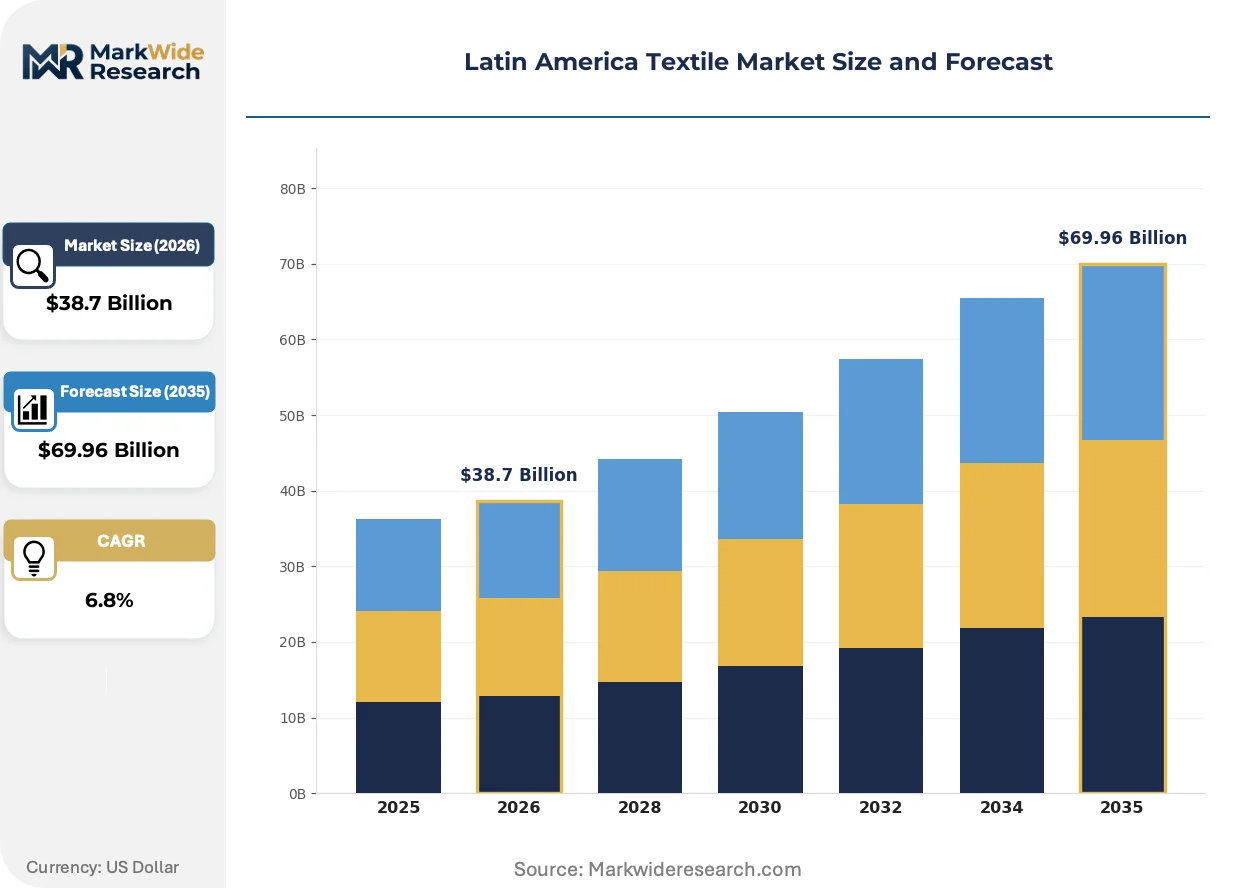
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton, Polyester, Wool, Silk End User: Fashion Retail, Home Furnishing, Industrial Use, Technical Textiles Application: Apparel, Upholstery, Automotive, Non-Woven Fabrics Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | Alpargatas SAIC, Fabricato SA, Evora SA, Santana Textiles Group, Pettenati SA Textile Industry, Kaltex SA, Santista Argentina SA, Coteminas SA, Vicunha Textil SA, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Textile Market Shifts & Advancements
Digital textile printing and closed-loop chemical recycling are compressing batch minimums and raw material circularity timelines across Latin American finishing operations, with sustainability-linked procurement criteria now filtering supplier qualification beyond cost and capacity metrics.
Digital textile printing is miniaturizing production economics for short-run fashion and home décor applications. São Paulo-based converters serving fast-fashion e-commerce clients are adopting single-pass inkjet systems to compress sampling cycles from weeks to days. This technology is miniaturizing the traditional rotary screen printing infrastructure, enabling micro-factories within urban logistics zones and reducing water and dye discharge volumes by eliminating engraving and washout stages.
EU deforestation regulation extraterritorial enforcement is reshaping cotton sourcing documentation requirements for Brazilian and Argentine spinners exporting to European Union member states. The regulation mandates geolocation-tagged farm-level traceability for all cellulosic fibers entering EU supply chains after compliance deadlines, elevating compliance costs for traders lacking integrated farm management software. Brazilian ginning cooperatives in Mato Grosso are responding by deploying satellite-verified planting boundary systems to preserve market access.
Nearshoring procurement models are compressing traditional seasonal buying calendars for US apparel brands sourcing from Latin American suppliers. Buyers are abandoning six-month forward commitment structures in favor of four-week replenishment cycles enabled by air freight and regional distribution center proximity. This behavioral shift is most visible in Mexico's Puebla-Tlaxcala knitwear cluster, where converters are reconfiguring warp knitting schedules to accommodate weekly order volatility rather than quarterly bulk shipments.
Latin America Textile Market Segmentation
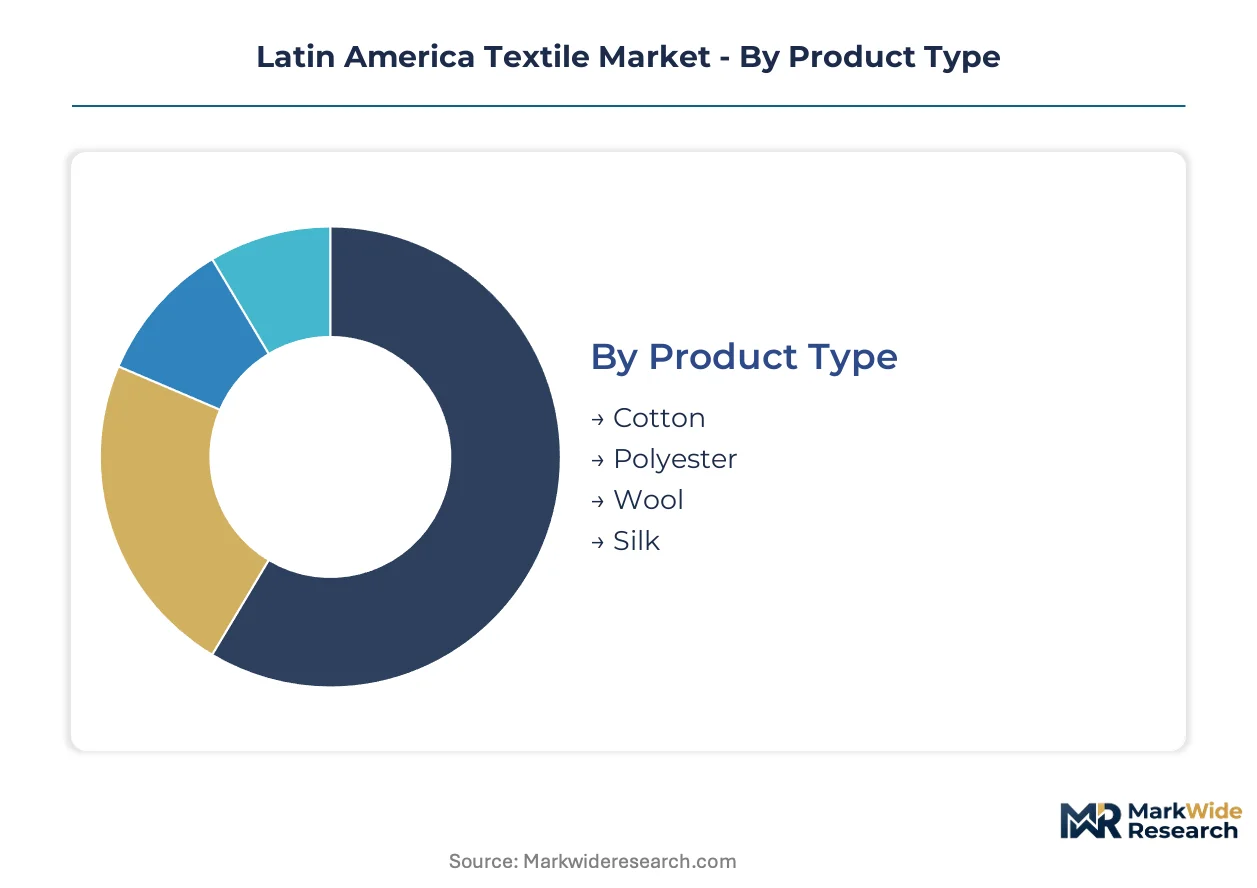
Latin American textile procurement patterns diverge sharply between commodity-driven apparel supply chains and specification-heavy technical applications. Understanding where margin pools concentrate across fiber types, end-uses, and distribution modes reveals which converters can defend pricing power against Asian import competition.
Product Type:
Margin pools concentrate in synthetic fiber production where recycled PET integration and USMCA regional content rules create tariff-advantaged positioning against virgin polymer imports.
- Cotton:Natural fiber retaining structural dominance through established ginning infrastructure across Brazil and Argentina. São Paulo spinners and Mato Grosso cooperatives face EU deforestation regulation traceability mandates that elevate compliance costs for exporters lacking satellite-verified farm documentation.
- Polyester:Synthetic filament and staple fiber produced from post-consumer bottle waste in Mexican manufacturing clusters. Puebla-Tlaxcala converters leverage recycled feedstock to qualify for automotive upholstery regional content thresholds under USMCA while reducing virgin polymer exposure.
- Wool:Natural protein fiber sourced primarily from Argentine Patagonian ranching operations serving premium apparel and home furnishing niches.
- Silk:Specialty fiber with limited regional sericulture infrastructure, concentrated in small-batch artisanal production for luxury accessories.
Cotton holds installed capacity across Brazilian industrial corridors. Polyester is rotating up the share rankings through sustainability-linked procurement criteria and regulatory compliance advantages.
End User:
Application diversity determines contract stability, with long-cycle industrial and medical specifications insulating producers from fast-fashion demand volatility.
- Fashion Retail:Apparel brands in São Paulo and Mexico City driving seasonal procurement of woven and knit fabrics. Buyers are compressing forward commitment structures from quarterly bulk orders to four-week replenishment cycles enabled by regional distribution proximity.
- Technical Textiles:Medical, geotextile, and filtration specifications commanding premium positioning over commodity fashion fabrics. ANVISA Class II and III device certification requirements in Brazil create protected demand zones for domestic producers with biocompatibility testing capabilities.
- Home Furnishing:Upholstery and decorative fabric demand concentrated in Brazil's furniture manufacturing belt around Bento Gonçalves.
- Industrial Use:Conveyor belting, filtration media, and protective equipment textiles serving mining and agricultural machinery OEMs.
Fashion Retail commands volume throughput. Technical Textiles delivers the steepest expansion trajectory through infrastructure and healthcare specification capture.
Application:
Performance requirements stratify pricing tiers, with automotive and technical non-woven applications demanding certification investments that screen out commodity converters.
- Automotive:Upholstery, airbag fabric, and interior trim textiles supplied to OEM assembly plants in Aguascalientes and Resende. Just-in-time sourcing mandates and USMCA rules of origin are localizing procurement from Mexican and Brazilian suppliers previously dependent on Asian imports.
- Apparel:Woven shirting, denim, and knit basics serving mass-market and premium fashion labels. Digital textile printing adoption in São Paulo micro-factories is compressing sampling cycles and enabling short-run production economics.
- Upholstery:Residential and commercial furniture coverings requiring abrasion resistance and flammability compliance under Mexico's NOM certification framework.
- Non-Woven Fabrics:Geosynthetics, medical disposables, and filtration media produced through spunbond and needlepunch processes.
Apparel maintains baseline capacity utilization. Automotive is climbing the fastest through OEM localization mandates and regional content compliance.
Distribution Channel:
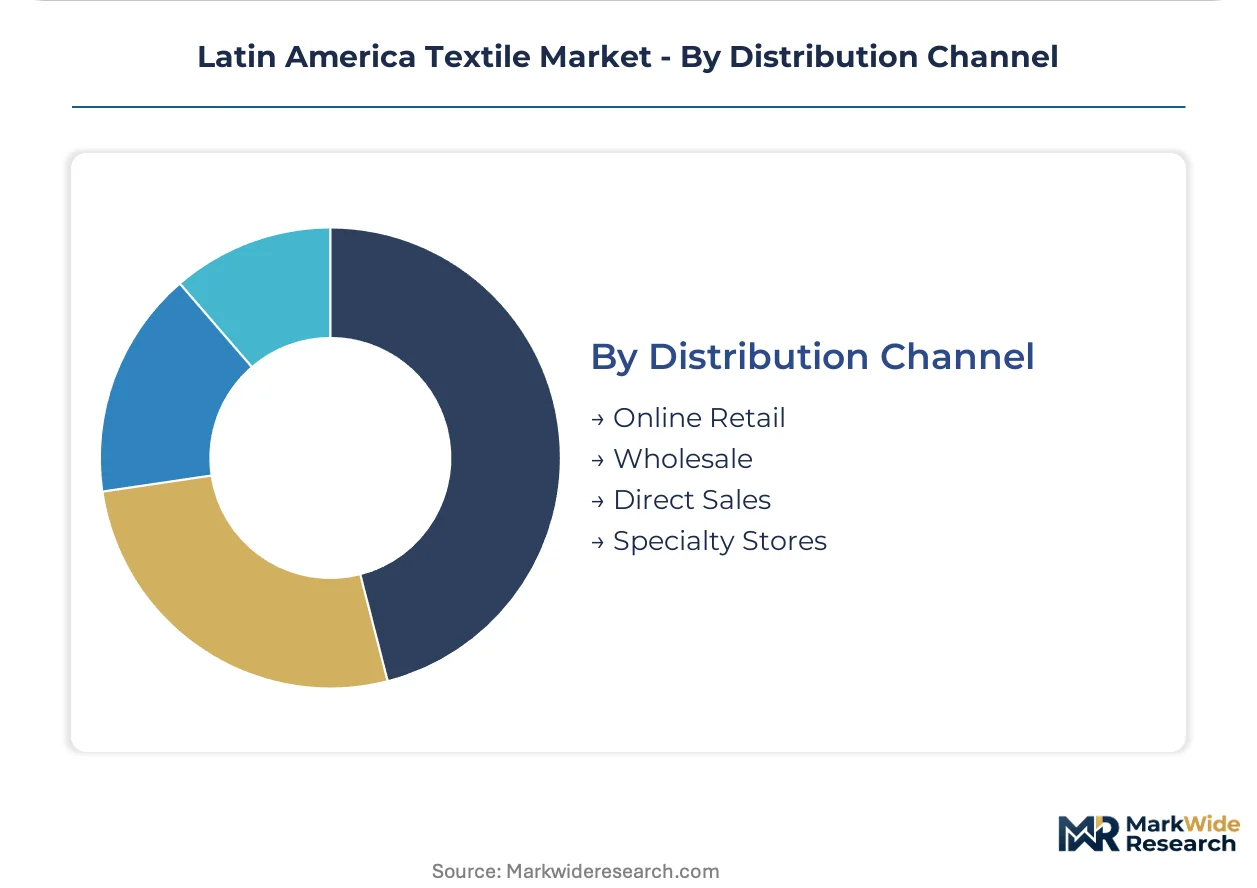
Channel selection reflects buyer scale and specification complexity, with direct relationships dominating technical textile procurement and digital platforms penetrating fashion replenishment.
- Wholesale:Traditional fabric merchants and trading houses aggregating volume for apparel manufacturers across Brazil's Bom Retiro district and Mexico's Lagunera textile zone.
- Direct Sales:Mill-direct relationships for automotive OEMs, medical device manufacturers, and industrial end-users requiring lot traceability and certification documentation.
- Online Retail:E-commerce platforms and digital marketplaces enabling small-batch procurement for independent fashion designers and home décor startups.
- Specialty Stores:Branded fabric retailers serving consumer sewists and interior design professionals with curated natural fiber selections.
Wholesale retains legacy volume flows. Direct Sales is gaining share fastest through technical specification requirements and traceability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Latin America's textile trade balance tilts toward import dependency for synthetic filament yarn, while Brazil and Mexico anchor regional export capacity through denim, knit basics, and technical fabrics. Nearshoring momentum is redrawing cross-border procurement flows as US brands compress lead times.
Brazil
São Paulo state's industrial corridor concentrates spinning, weaving, and dyeing capacity serving domestic apparel brands and medical textile exporters. ANVISA Class II and III device certification requirements create protected demand zones for surgical fabric producers with biocompatibility testing infrastructure. Mato Grosso ginning cooperatives supply cotton feedstock while deploying satellite-verified farm boundary systems to satisfy EU deforestation regulation traceability mandates.
Mexico
Puebla-Tlaxcala textile cluster hosts warp knitting and finishing operations supplying automotive upholstery and performance apparel to US buyers. NOM certification mandates flammability and chemical safety thresholds for consumer fabrics, elevating compliance costs for importers and shielding certified domestic producers. Recycled PET feedstock integration in Torreón and Puebla polyester yarn plants qualifies output for USMCA regional content rules.
Argentina
Patagonian wool ranching operations supply premium protein fiber for export-oriented apparel and home furnishing niches. Natural gas tariffs exceed regional medians, eroding dyehouse margins for commission finishers lacking captive thermal generation. Buenos Aires province weaving mills depend on Mercosur common external tariff protection for synthetic filament yarn, preserving capacity but inflating raw material costs.
Colombia
Medellín and Cali industrial zones manufacture non-woven geosynthetics for mining tailings dam regulations mandating liner specifications. Mining sector procurement commands ISO 10319 tensile testing capabilities, screening out commodity converters. Coffee region textile micro-enterprises serve domestic fashion labels with limited technical textile penetration.
Chile
Santiago metropolitan area concentrates apparel distribution and retail buying offices rather than primary manufacturing. Copper mining sector procurement of filtration media and conveyor belting creates industrial textile demand served by regional imports. Limited domestic spinning capacity leaves Chile dependent on Brazilian and Peruvian fabric supply for local garment assembly.
Latin America Textile Market Competitive Landscape
Concentration sits with integrated spinners controlling captive yarn-to-fabric operations, while trading-dependent converters face margin compression from Asian import competition. Three archetypes dominate: vertically integrated denim and knit basics producers, specialized technical textile fabricators with certification infrastructure, and regional trading houses aggregating volume for commission finishing. Competitive moves cluster around dyeing and finishing capacity expansion in Mexico's automotive corridor and sustainability-linked retrofit finance accessing BNDES credit lines in Brazil.
Among Brazilian integrated producers, Santana Textiles Group and Vicunha Textil SA exemplify the spinner-fabricator archetype through captive operations sustaining margin control. Kaltex SA anchors the specialized tier with Mexico-based production serving OEM assembly plants. These three occupy positions reflecting capital-intensity divergence between integrated and trading-dependent business models.
| Leading Market Players |
|---|
| Alpargatas SAIC |
| Fabricato SA |
| Evora SA |
| Santana Textiles Group |
| Pettenati SA Textile Industry |
| Kaltex SA |
| Santista Argentina SA |
| Coteminas SA |
| Vicunha Textil SA |
| Others |
Supply & Pricing Matrix
Four-week replenishment cycles now dominate buyer-producer relationships across the Puebla-Tlaxcala corridor and São Paulo industrial belt, compressing inventory buffers and amplifying pricing power for dyeing and finishing operators with captive thermal generation. This lead-time compression rewards regional proximity while penalizing converters dependent on Asian filament yarn imports facing maritime bottlenecks.
Pricing Analysis
Configured-to-order pricing for ANVISA-certified medical textiles commands substantial premiums over commodity knit basics, with biocompatibility testing infrastructure acting as the primary price differentiation driver alongside lot-traceability documentation. Three-tier pricing structure across premium certification-grade, standard mill-run, and economy spot-market tiers is intensifying cost compression in the bottom tier as recycled PET integration in Mexican plants softens virgin polyester contract rates. Fashion retail buyers in São Paulo exhibit highest price sensitivity, while automotive OEMs in Aguascalientes prioritize specification compliance over unit cost.
Supply Chain Analysis
Just-in-time sourcing mandates from US apparel brands are displacing strategic cotton stockpiling traditions among Brazilian spinners, forcing Mato Grosso ginning cooperatives to absorb climate-driven yield volatility rather than buffering through forward purchases. Raw material flows draw from Brazilian cotton belts, Mexican recycled PET collection networks, and Argentine Patagonian wool operations, with tariff exposure on synthetic filament yarn imports threatening margin stability for Mercosur-dependent weavers. Distribution runs through mill-direct relationships for technical specifications and wholesale fabric merchants aggregating volume for apparel converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where ANVISA certification and USMCA regional content rules create entrenched switching costs for qualified domestic producers. Network effects concentrate among integrated spinners with backward yarn control.
For Market Incumbents: Shield market position by accelerating captive recycled PET pellet capacity in Torreón and Puebla to offset virgin polymer price volatility, while securing BNDES sustainability-linked credit lines for solar thermal dyeing retrofits ahead of SEBI disclosure tightening. Commission finishers lacking biocompatibility testing infrastructure face displacement from surgical fabric procurement as ANVISA Class III specifications harden. For New Entrants and Emerging Players: Differentiate on geosynthetic specification capture for Colombian and Peruvian mining tailings dam regulations, where ISO 10319 tensile testing capabilities screen out incumbent commodity converters. White-space concentrates in automotive airbag fabric localization serving Resende and Aguascalientes OEM plants, with entry best executed through technical partnership with established dye-chemist workforces in Blumenau rather than greenfield formulation labs. For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned trading houses in Brazil's Bom Retiro district lacking succession planning and certification infrastructure to meet EU deforestation regulation traceability mandates. Long-term viability favors integrated producers with water recycling assets and solar thermal dyeing capabilities. Watch for inflection when blockchain-based farm-to-fabric documentation shifts from competitive advantage to table-stakes procurement requirement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled PET Pellet Production | Torreón and Puebla yarn plants secure USMCA automotive content thresholds while reducing virgin polymer cost exposure. |
| ANVISA Class III Biocompatibility Certification Investment | Surgical fabric producers capture protected demand zones as Brazil's medical device standards harden against imports. |
| Solar Thermal Dyeing Retrofit Finance | BNDES credit lines tied to SEBI-linked ESG disclosure accelerate capital deployment toward low-carbon finishing operations. |
| Blockchain Farm-to-Fabric Traceability Deployment | Mato Grosso ginning cooperatives preserve EU market access under deforestation regulation extraterritorial enforcement. |
| Automotive Airbag Fabric Localization | Mexican and Brazilian suppliers displace Asian imports as USMCA rules of origin tighten OEM procurement criteria. |
Research Methodology
A spread of perspectives from textile plant managers, fashion retail procurement directors, automotive OEM sourcing leads, and medical device regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against customs trade records, ANVISA certification databases, SEC filings from listed manufacturers, and BNDES credit facility disclosures. Bottom-up capacity assessments across São Paulo, Puebla-Tlaxcala, and Medellín industrial zones were triangulated with top-down demand modeling from end-use sector consumption patterns.
Segmentation dimensions modeled span fiber type, end-user application, and distribution channel across the analysis window, with additional granularity on certification tier for technical textiles. CAGRs were derived from trend extrapolation of nearshoring contract flows, recycled PET integration rates, and regulatory compliance cost trajectories. Forecast inputs incorporated dyehouse energy tariff differentials, cotton yield volatility from climate modeling, and EU deforestation regulation implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained USMCA utilization, ANVISA regulatory stability, or nearshoring momentum retention would require recalibration. Forecasts reflect assumptions on regional trade policy continuity and certification infrastructure investment rates. Revision becomes warranted when blockchain traceability deployment costs cross thresholds that commoditize compliance rather than differentiate suppliers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Kevlar Fiber Market
Synthetic Fibers
Middle-East and Africa Aramid Fiber Market
Synthetic Fibers
Staple Fibers Market
Synthetic Fibers
Polybenzoxazole Fibers Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
Blended Fibers Market
Synthetic Fibers
Global Lyocell Fibers Market
Synthetic Fibers
South Korea Textile Market
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
Fiber Blends Market
Synthetic Fibers
Designer Fiber Market
Synthetic Fibers
High Performance Polyester Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Polyethylene Terephthalate (PET) Fiber Market
Synthetic Fibers
Bio-Based Elastic Core-Spun Yarn for Denim Stretch Market
Synthetic Fibers
Long Fiber Thermoplastics Market