
 Microfiber Leather Market | 2026-2036
Microfiber Leather Market Size, Share, and Industry Trends Forecast 2026-2036
Microfiber Leather Market Intelligence
The shift towards water-based polyurethane resin technology is tilting the production landscape away from traditional solvent-based processes, reducing environmental impact. This transition creates new technical challenges and opportunities for material suppliers. Kuraray Co., Ltd. leverages its advanced polymer science to develop high-performance materials for demanding automotive applications. Meanwhile, Huafon Group sustains a significant market presence through its large-scale, integrated production of the core polyurethane inputs required for microfiber leather manufacturing.
Microfiber leather is a high-tech synthetic composite material designed to replicate the structure and feel of natural leather. It consists of a non-woven fabric base made from ultra-fine fibers, typically polyester and polyamide, which is then impregnated with polyurethane. Its primary purpose is to offer a durable, consistent, and cost-effective alternative to genuine leather. Demand from the automotive end-user segment for interior components is a primary growth engine. Within product types, coated microfiber leather commands a significant share, valued for its enhanced durability and resistance to abrasion and stains.
Regulations such as the EU's REACH framework restrict the use of certain volatile organic compounds, steering manufacturers toward water-based production methods. In parallel, China's GB standards for automotive interior air quality influence material specifications for vehicles produced or sold within the country. These regulatory pressures directly impact material formulation and market access. Future competitive advantage will depend on securing a stable supply of bio-based raw materials and achieving cost-parity with traditional synthetics.
Market Dynamics
The microfiber leather market is defined by the core tension between the automotive and footwear industries' demand for sustainable, high-performance materials and the technical and cost hurdles of transitioning away from traditional solvent-based polyurethane production. This dynamic is concentrating innovation on water-based and bio-based resin technologies, driven by regulatory pressures and shifting consumer preferences.
Growth Catalysts
- Automotive Sector Demand:The automotive industry's push for lightweight, durable, and aesthetically pleasing interior components like seating, dashboards, and door panels provides a consistent demand stream. This is amplified by the electric vehicle segment's focus on material innovation and sustainability.
- Bio-Based Polyurethane Development:Advances in polymer science are enabling the creation of polyurethane resins from renewable feedstocks. This technological shift enhances the material's environmental profile, appealing to brands and consumers focused on sustainability.
- Regulatory Restrictions on Solvents:European regulations like REACH restrict the use of volatile organic compounds (VOCs) common in solvent-based manufacturing. This creates a powerful incentive for producers to adopt cleaner, water-based production processes to maintain market access.
Market Restraints
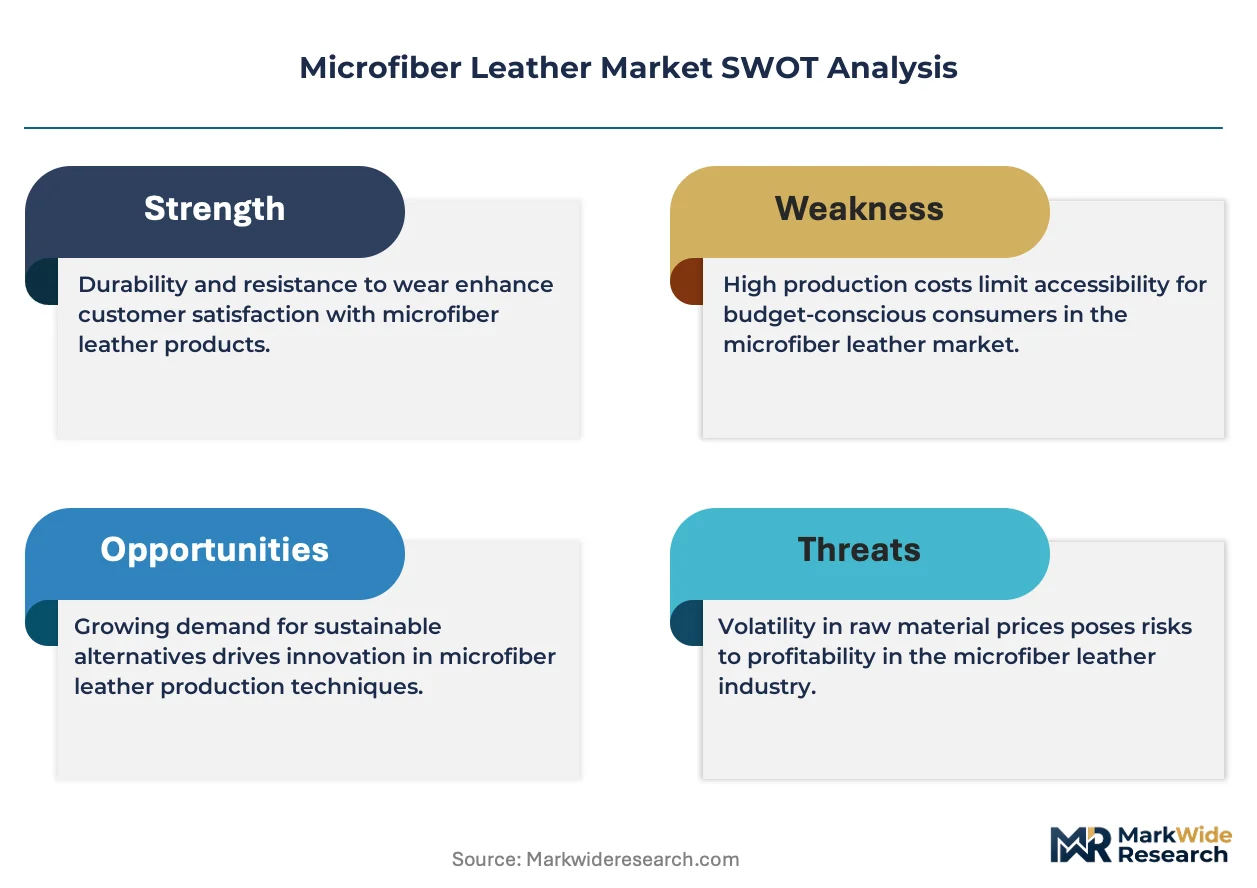
- Petrochemical Feedstock Volatility:The primary raw materials, including polyester, polyamide, and conventional polyurethane, are derived from petrochemicals. Their price volatility directly impacts production costs and creates margin pressure for manufacturers.
- Performance Parity with Natural Leather:While advanced, microfiber leather still faces challenges in perfectly replicating the unique breathability, moisture management, and aging characteristics (patina) of high-grade genuine leather, limiting its use in some luxury applications.
- Concentrated Production Base:The significant concentration of both raw material and finished microfiber leather production within China creates potential supply chain vulnerabilities for global buyers, exposing them to geopolitical and logistical risks.
Strategic Opportunities
- Expansion into Technical Textiles:Opportunities exist in developing specialized microfiber leather variants for high-performance applications such as protective gear, marine upholstery, and aviation interiors, where durability and specific resistances are critical.
- Bio-Feedstock Supply Chain Control:Securing a stable, cost-effective supply of bio-based inputs, such as bio-polyols or bio-succinic acid, offers a significant competitive advantage. This can be achieved through strategic partnerships or backward integration.
- Market Penetration in Southeast Asia:As manufacturing for footwear and furniture expands in countries like Vietnam and Indonesia, there is a clear opportunity to establish local supply chains for microfiber leather to serve these growing industrial hubs.
Industry Challenges
- Scaling Water-Based Production:Transitioning from mature solvent-based processes to water-based systems requires significant capital investment and technical expertise to overcome challenges in drying times, film formation, and overall production efficiency.
- Lack of Global Standardization:The absence of universally accepted standards for terms like "eco-leather" or "bio-based content" allows for inconsistent quality and greenwashing claims, creating confusion for buyers and complicating material specification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microfiber Leather Market |
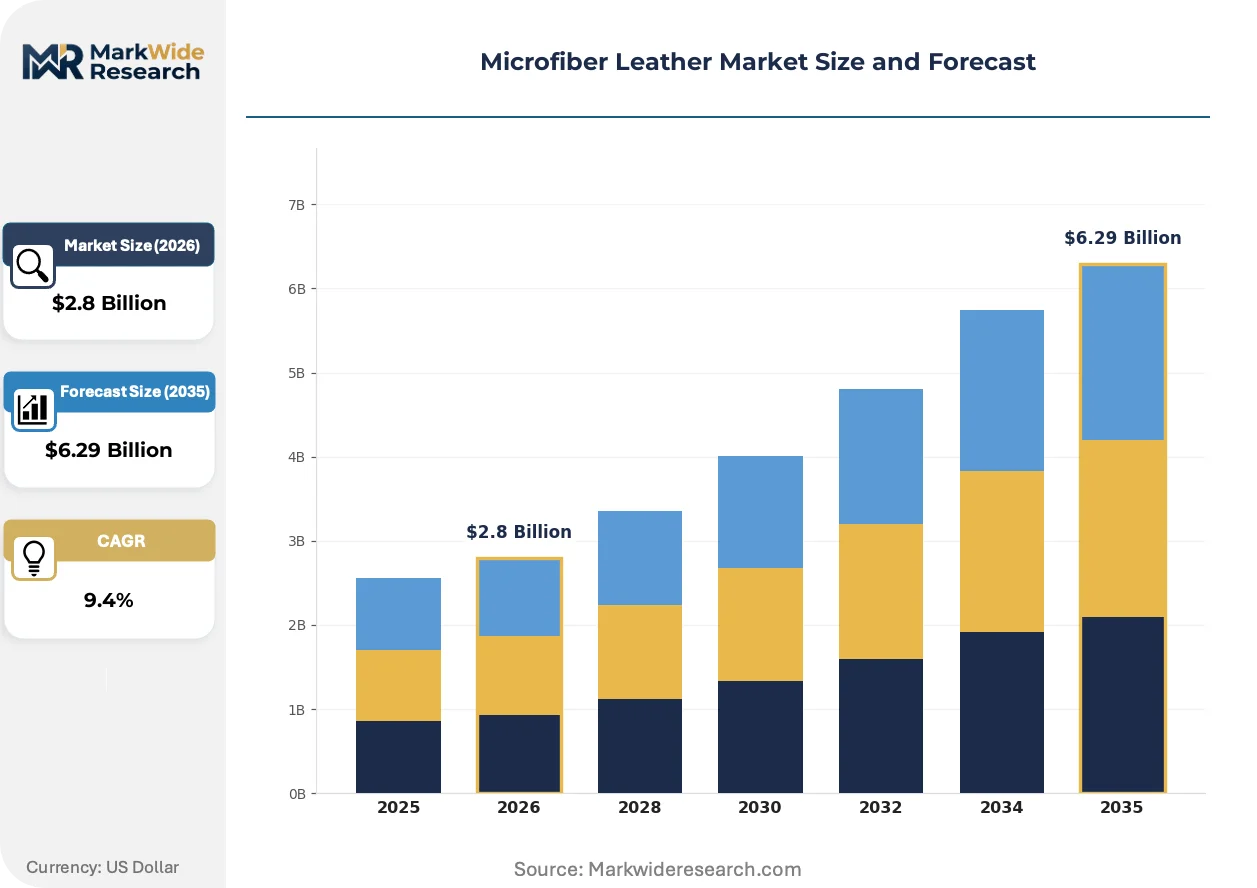
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated, Non-Coated, Synthetic, Natural End User: Footwear, Furniture, Automotive, Fashion Application: Upholstery, Clothing, Accessories, Sports Distribution Channel: Online, Retail, Wholesaler, Direct Sales |
| Companies Covered | San Fang Chemical Industry Co., Ltd., Teijin Limited, Kuraray Co., Ltd., Chongqing Double Elephant Micro Fibre Material Co., Ltd., Huafon Group, Toray Industries, Inc., Filwel Co., Ltd., Seiren Group, Asahi Kasei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microfiber Leather Market Strategic Shifts & Innovations
Material science is advancing to resolve the conflict between performance requirements and environmental impact. The innovation focus is on reformulating the core polyurethane component to reduce its carbon footprint and eliminate hazardous chemicals, while simultaneously enhancing the material's physical properties for demanding applications.
Bio-based polyurethane is a key product evolution. This technology uses renewable resources, such as plant-derived polyols, to create the resin component of the material. Automotive and fashion brands are increasingly adopting these materials to meet their corporate sustainability goals. This development is hybridizing the established performance of synthetic leather with the environmental benefits of renewable feedstocks, creating a distinct, higher-value product category.
China's GB standards for automotive interior air quality exert significant influence on material specifications. These regulations strictly limit the levels of volatile organic compounds (VOCs) inside vehicle cabins, directly impacting material choices for components. Automotive suppliers selling into the world's largest car market are compelled to adopt water-based polyurethane systems or other low-VOC alternatives, accelerating the technology shift away from traditional solvent-based methods.
Corporate procurement practices are changing, with a greater emphasis on supply chain transparency and certified sustainability. Buyers in the furniture and consumer electronics sectors are moving beyond price and performance to demand materials with documented life cycle assessments (LCAs) and third-party environmental certifications. This shift disadvantages suppliers unable to provide verifiable data on their products' environmental footprint, particularly in European and North American markets.
Microfiber Leather Market Segmentation
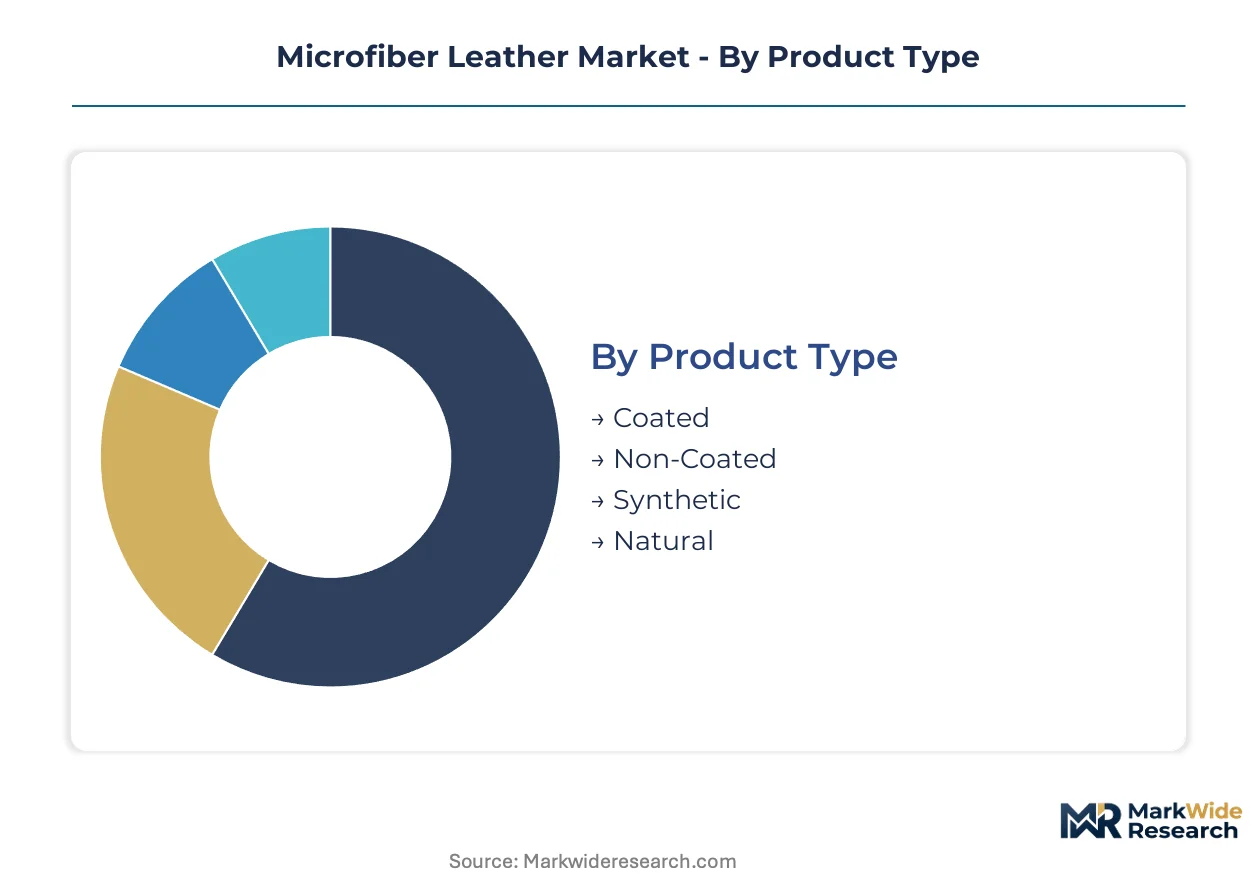
The Microfiber Leather Market exhibits diverse segmentation across product types, end-user industries, and application areas, reflecting the material's versatility and evolving technological landscape. Understanding these segments is crucial for identifying specific demand drivers, competitive dynamics, and strategic opportunities within the broader market.
Product Type:
The material composition of microfiber leather differentiates products based on their surface treatment and foundational components.
- Coated:This product type features an additional surface layer, typically polyurethane, enhancing its durability, abrasion resistance, and aesthetic finish. Coated microfiber leather commands a significant market share, particularly in applications requiring robust performance and stain resistance, such as automotive upholstery and high-traffic furniture.
- Natural:This segment encompasses bio-based microfiber leather variants, often utilizing plant-derived polyols or other renewable feedstocks in their polyurethane impregnation. Demand for natural microfiber leather is concentrating in sectors like automotive and fashion, driven by corporate sustainability goals and consumer preferences for environmentally conscious materials.
- Non-Coated:These microfiber leather products lack an additional surface coating, offering a softer hand-feel and often greater breathability. Non-coated variants find use in applications where a more textile-like texture is desired, such as certain apparel linings or specific footwear components.
- Synthetic:This category broadly refers to conventional microfiber leather produced from petroleum-derived polyurethane and synthetic fiber non-woven bases. Synthetic microfiber leather offers cost-effectiveness and consistent performance, serving as a widely adopted alternative to genuine leather across various industries.
Coated microfiber leather commands the established base. The steepest expansion runs through Natural microfiber leather.
End User:
Demand patterns for microfiber leather vary significantly across different industrial and consumer sectors, each with distinct performance requirements.
- Automotive:The automotive industry utilizes microfiber leather extensively for vehicle upholstery, dashboards, door panels, and headliners, valuing its durability, lightweight properties, and aesthetic appeal. This end-user segment is a primary growth engine, amplified by material innovation in electric vehicles.
- Footwear:Microfiber leather serves as a key material for shoe uppers, linings, and insoles, offering a consistent and durable alternative to natural leather. Demand is concentrating significantly within China's vast manufacturing ecosystem for footwear production, supporting large-scale output.
- Furniture:The furniture sector employs microfiber leather for residential and commercial upholstery, benefiting from its wear resistance, ease of cleaning, and consistent appearance. Manufacturers seek cost-effective, high-performance materials for sofas, chairs, and other furnishings.
- Fashion:Microfiber leather is adopted in various fashion items, including apparel, bags, and accessories, providing a cruelty-free and often more sustainable alternative to animal leather. Brands increasingly leverage this material to align with evolving consumer ethics and design trends.
The automotive sector remains a dominant consumer. Footwear applications are gaining share fastest.
Application:
The functional use cases for microfiber leather span a wide range of consumer and industrial products, leveraging its specific material characteristics.
- Upholstery:This application involves using microfiber leather for covering seating surfaces in vehicles, homes, and commercial spaces, valued for its durability and aesthetic versatility. Upholstery applications directly link to the significant demand from the automotive and furniture end-user segments.
- Clothing:Microfiber leather is integrated into various apparel items, including jackets, skirts, and activewear, providing a lightweight, flexible, and weather-resistant material. Advances in material science enable clothing applications to meet both performance and fashion demands.
- Accessories:This segment includes small leather goods such as handbags, wallets, belts, and luggage, where microfiber leather offers a consistent, durable, and cost-effective material. Its uniform quality and wide range of finishes make it suitable for mass production of accessories.
- Sports:Microfiber leather finds application in sports equipment and apparel, including athletic shoes, gloves, and protective gear, where its abrasion resistance and consistent performance are critical. The material's ability to withstand rigorous use is a key advantage in this segment.
Upholstery consistently accounts for substantial volume. Clothing applications are expanding quickly.
Distribution Channel:
The pathways through which microfiber leather reaches end-users reflect diverse commercial strategies, from large-scale industrial supply to direct consumer engagement.
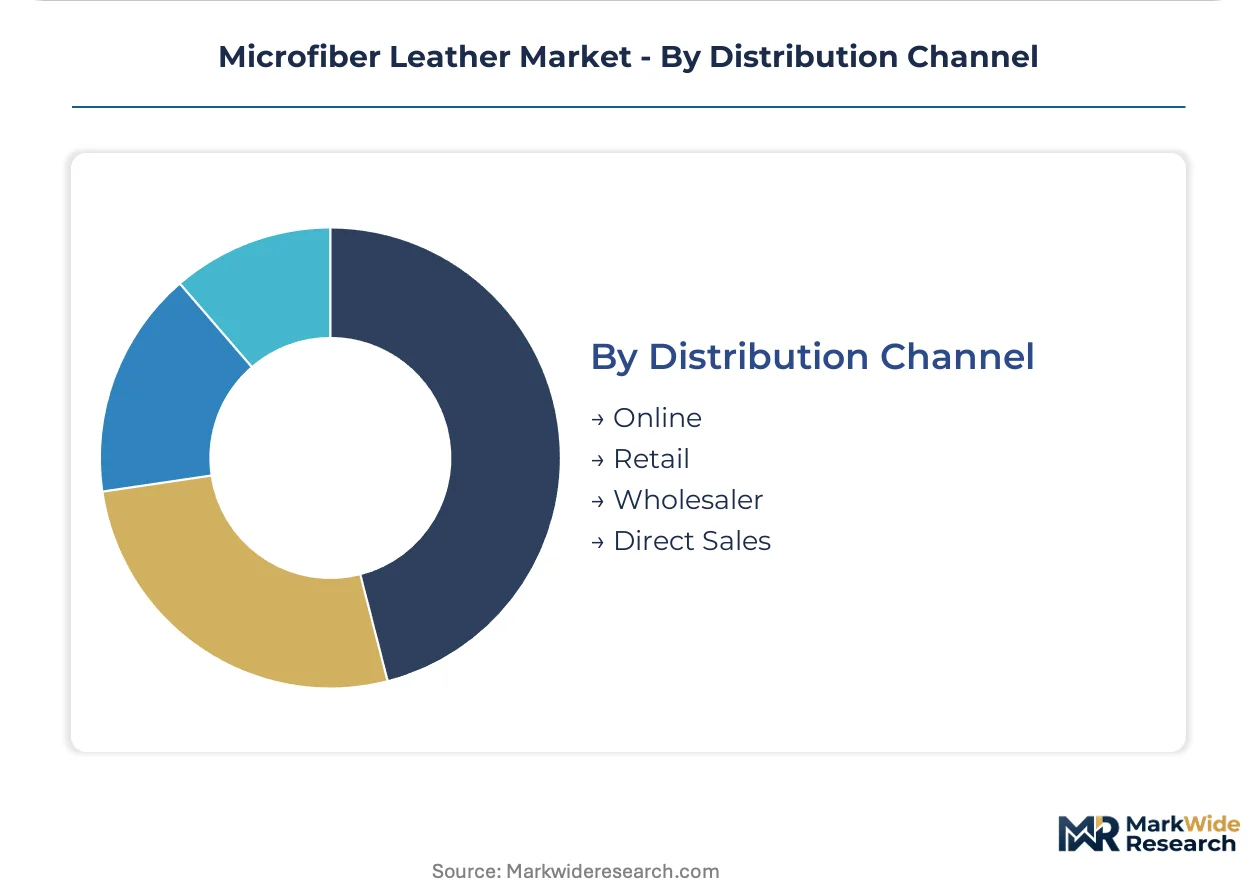
- Wholesaler:Wholesalers serve as intermediaries, supplying large volumes of microfiber leather to manufacturers across various industries such as automotive, footwear, and furniture. This channel facilitates efficient bulk distribution and inventory management for industrial clients.
- Direct Sales:Manufacturers of microfiber leather often engage in direct sales to large original equipment manufacturers (OEMs) or specialized brands, particularly for custom orders or high-volume contracts. This channel allows for closer collaboration on material specifications and technical requirements.
- Online:The online distribution channel includes e-commerce platforms and company websites selling microfiber leather, primarily to smaller businesses, designers, or individual consumers. This channel offers accessibility and a broader reach for specialized or niche products.
- Retail:Retail channels involve physical stores or showrooms where microfiber leather products, or products incorporating the material, are sold directly to end-consumers. This channel often focuses on finished goods like furniture, footwear, or fashion accessories.
Wholesalers manage significant material flow. Direct sales channels are becoming more common for specialized orders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes for microfiber leather include automotive, footwear, furniture, and fashion. These sectors drive significant material procurement across key manufacturing and consumption hubs globally. The material's versatility and performance characteristics cater to diverse industrial requirements.
China
China's vast manufacturing ecosystem drives immense demand for microfiber leather in footwear, furniture, and automotive components. GB standards for automotive interior air quality directly influence material specifications for vehicles sold within the country. Major industrial clusters in the Yangtze River Delta and Pearl River Delta are hubs for microfiber leather production and application.
Germany
Germany's automotive industry requires high-performance microfiber leather for vehicle interiors, focusing on durability and aesthetic appeal. European regulations like REACH restrict volatile organic compounds, pushing manufacturers towards water-based production methods. The automotive manufacturing centers in Bavaria and Baden-Württemberg actively integrate advanced synthetic materials into vehicle designs.
United States
United States demand for microfiber leather stems from its large automotive and furniture sectors, prioritizing material longevity and consistent quality. Federal environmental regulations, including EPA guidelines, encourage the use of low-VOC materials in consumer products. Manufacturing facilities in the Southeast, particularly around states like South Carolina, are adapting to produce sustainable interior materials.
Japan
Japan's advanced automotive and fashion industries seek innovative microfiber leather solutions with superior aesthetic and functional properties. METI initiatives promote the development of sustainable materials and circular economy practices within manufacturing. Industrial centers in the Kanto region, including Tokyo, are home to research and development efforts for next-generation synthetic leathers.
India
India's rapidly expanding automotive and footwear sectors contribute to a rising demand for cost-effective, durable microfiber leather. The PLI scheme supports domestic manufacturing, encouraging local production of advanced materials for various industries. Production hubs in Maharashtra and Tamil Nadu are witnessing increased investment in synthetic material capabilities.
Microfiber Leather Market Key Industry Players
Channel-controlling players compete with product-specialist players across the microfiber leather market. The market exhibits a tiered structure, with large integrated chemical producers supplying core polyurethane inputs and specialized material manufacturers focusing on advanced composites. Strategic archetypes include raw material giants, high-performance material innovators, and regional volume producers. These entities pursue distinct strategies, with capacity expansion and strategic partnerships remaining dominant competitive moves across the industry.
At the scale-driven end, Huafon Group sustains a significant market presence through its large-scale, integrated production of core polyurethane inputs for microfiber leather manufacturing. Meanwhile, San Fang Chemical Industry Co., Ltd., a Taiwan-based entity, represents a key player specializing in chemical industry applications and finished microfiber leather. Kuraray Co., Ltd., a Japanese corporation, exemplifies the high-performance material innovator archetype, leveraging advanced polymer science to develop materials for demanding automotive applications. These companies collectively shape the supply dynamics for diverse end-user segments, from automotive to fashion.
| Leading Market Players |
|---|
| San Fang Chemical Industry Co., Ltd. |
| Teijin Limited |
| Kuraray Co., Ltd. |
| Chongqing Double Elephant Micro Fibre Material Co., Ltd. |
| Huafon Group |
| Toray Industries, Inc. |
| Filwel Co., Ltd. |
| Seiren Group |
| Asahi Kasei |
| Others |
Cost & Logistics Intelligence
China's significant concentration in core polyurethane inputs for microfiber leather manufacturing gives upstream suppliers substantial pricing power, directly influencing downstream material costs for global automotive and footwear manufacturers. This dynamic shapes margin pools across the value chain.
Pricing Analysis
Cost-plus contract patterns with indexation to petrochemical feedstock prices define pricing in this market. Price differentiation stems from quality grade, particularly for automotive-specification materials, and the volume scale for large original equipment manufacturers. Pricing softness reflects volatile petrochemical feedstock costs and intensifying competition in standard synthetic grades. Furniture manufacturers exhibit high price sensitivity, while premium automotive brands prioritize performance and durability over marginal cost differences.
Supply Chain Analysis
Geopolitical and logistical risks due to concentrated production in China create supply chain vulnerabilities for global buyers. Raw material dependencies include polyester non-wovens and various polyurethane resins sourced primarily from China, South Korea, and Japan. Commodity price volatility for petrochemical feedstocks represents a structural risk for manufacturers globally. Downstream distribution runs through wholesalers for bulk industrial supply and direct sales channels for specialized OEM requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microfiber leather market offers fragmentation opportunities as evolving consumer ethics and sustainability goals create niches for bio-based and low-VOC materials. This shift enables specialized product development for discerning buyers.
For Market Incumbents: Entrench market position by investing heavily in advanced water-based polyurethane systems and securing long-term bio-based feedstock agreements. Enhance research and development into next-generation sustainable materials to counter regulatory threats like REACH and emerging bio-based material alternatives. Capacity additions in Southeast Asia can also mitigate supply chain concentration risks.
For New Entrants and Emerging Players: Build out specialized product lines targeting high-performance technical textiles and luxury fashion applications. The bio-based fashion accessories segment represents a penetrable white space. A focused go-to-market angle should emphasize verifiable sustainability certifications and documented life cycle assessments to attract environmentally conscious brands.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized, specialized producers focused on sustainable material innovation. The microfiber leather market shows long-term viability driven by material innovation and increasing sustainability mandates from major end-user industries. Watch for significant shifts in regulatory enforcement of volatile organic compound limits in key automotive markets as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases scale for cost leadership in high-volume segments like footwear. |
| Green Manufacturing Transition | Aligns production with EU REACH and China GB standards for market access. |
| Long-term Supply Agreement | Secures stable access to bio-based raw materials, reducing feedstock volatility. |
| Joint Venture | Accelerates entry into specialized technical textile applications requiring specific expertise. |
| Certification Investment | Validates sustainability claims for automotive and fashion brands, enhancing market appeal. |
Research Approach
Operator-level perspectives from automotive interior designers, footwear procurement managers, chemical research and development directors, and material scientists anchored the qualitative base. Bottom-up and top-down triangulation combined these primary interviews with secondary validation from industry association reports, patent databases, corporate sustainability disclosures, and regulatory body publications. This comprehensive approach ensured robust data collection.
Scenario-bracketing across optimistic, probable, and conservative market trajectories informed the analytical framework over the projection horizon. Segmentation dimensions modeled included product type, end-user industry, application area, distribution channel, and regional regulatory environment. Compound annual growth rates were derived from historical data analysis and projected demand-supply gaps, with bio-based resin adoption rates and automotive production volumes serving as key forecast inputs.
Stress conditions across petrochemical prices and regulatory stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological advancements and trade policies, acknowledging potential disruptions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Regenerated Fibers Market
Synthetic Fibers
US Textile Market
Synthetic Fibers
North America Aramid Fiber Market
Synthetic Fibers
Polyester Strap for Manual Grade Market
Synthetic Fibers
South Korea Textile Market
Synthetic Fibers
Polyester Tire Cord Fabrics Market
Synthetic Fibers
Clothing Fibers Market
Synthetic Fibers
Synthetic Textile Fiber Market
Synthetic Fibers
Bio-Based Elastic Core-Spun Yarn for Denim Stretch Market
Synthetic Fibers
Anti-Static Fibers Market
Synthetic Fibers
Americas Spandex Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
Rayon Fibers Market
Synthetic Fibers
North America High Performance Fibers Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
Polyester Staple Fiber Market