
 Para-Aramid Fibers Market | 2026-2036
Para-Aramid Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Para-Aramid Fibers Market Analysis
Performance-based maintenance contracts for ballistic protection systems is repositioning how military buyers contract for para-aramid materials. Teijin Limited leverages its integrated aramid-to-fabric pipeline to sustain long-term defense supply agreements. DuPont anchors North American demand through its Kevlar production infrastructure and established channel control with domestic armor manufacturers.
Para-aramid fibers are aromatic polyamide filaments spun from liquid crystalline solutions, exhibiting tensile strength five times that of steel on an equal-weight basis and thermal stability exceeding 400°C, making them indispensable for ballistic protection, aerospace composites, and high-temperature filtration media. The Kevlar and Twaron product types dominate volume shipments to defense and industrial channels, while Nomex captures premium margin pools in electrical insulation and firefighter protective gear where thermal performance commands price premiums. Body Armor and Composites applications are expanding fastest as military modernization programs and lightweight vehicle platforms drive specification upgrades across aerospace and automotive end users.
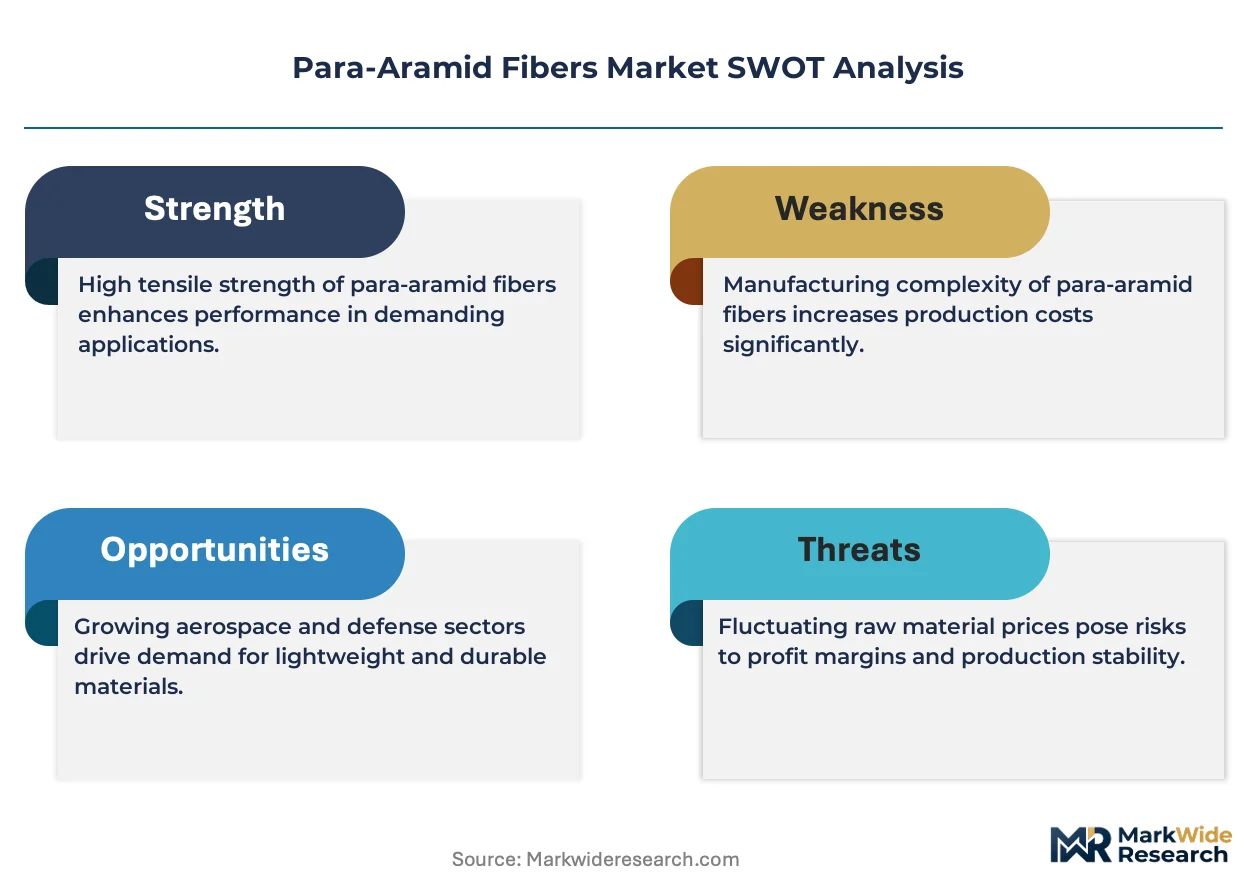
The EU's PPE Regulation (EU) 2016/425 and CE marking requirements are elevating testing protocols for protective gear sold within Europe, directly shaping product development cycles at fiber producers serving law enforcement and military segments. The US National Institute of Justice maintains ballistic resistance standards that govern federal procurement eligibility, creating a dual-compliance burden for suppliers operating across both jurisdictions. Stakeholders must monitor evolving flame-resistance specifications from the EU Green Deal's chemical restriction roadmap and assess backward integration into meta-aramid precursor supply as a hedge against feedstock volatility.
Market Dynamics
Defense procurement of body armor is accelerating across NATO members, tightening specification standards and compressing supplier qualification timelines for para-aramid fiber producers serving military channels.
Growth Catalysts
- EU PPE Regulation (EU) 2016/425:CE marking requirements are elevating testing protocols for protective gear, forcing fiber producers to upgrade certification infrastructure and locking in premium-grade material demand from law enforcement agencies.
- Lightweight vehicle platforms:Aerospace and automotive end users are specifying para-aramid composites for structural weight reduction, expanding volume shipments beyond traditional ballistic protection channels.
- Germany's industrial belt:Demand concentration around Düsseldorf and Cologne is creating cluster economies that reduce logistics costs and accelerate specification feedback loops between fiber producers and fabricators.
Market Restraints
- Petrochemical feedstock volatility:Para-aramid production depends on para-phenylenediamine and terephthaloyl chloride, both exposed to benzene derivative pricing swings that compress margin predictability.
- Supply concentration in Japan and US:Liquid crystal spinning technology and precursor chemical production remain controlled by a handful of integrated producers, creating bottleneck risk for non-captive buyers.
- Meta-aramid substitution in thermal applications:Nomex-type fibers are capturing share in electrical insulation and firefighter gear where extreme thermal stability outweighs tensile strength requirements.
Strategic Opportunities
- EU Green Deal chemical restrictions:The roadmap's flame-resistance specifications are opening specification windows for halogen-free para-aramid formulations in public procurement tenders.
- High-temperature filtration media:Cement and steel producers are adopting para-aramid filter bags for exhaust gas treatment, creating industrial volume channels with lower certification barriers than defense.
- Performance-based maintenance contracts:Military buyers are contracting for ballistic protection system lifecycle service rather than material-only supply, enabling fiber producers to capture recurring revenue streams.
Industry Challenges
- Liquid crystal spinning technician shortage:The specialized polymer physics expertise required for dope preparation and fiber formation is concentrated among retiring cohorts at legacy production facilities.
- Dual compliance burden:Suppliers operating across NATO defense channels must simultaneously satisfy US National Institute of Justice ballistic standards and EU CE marking protocols, extending product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Para-Aramid Fibers Market |
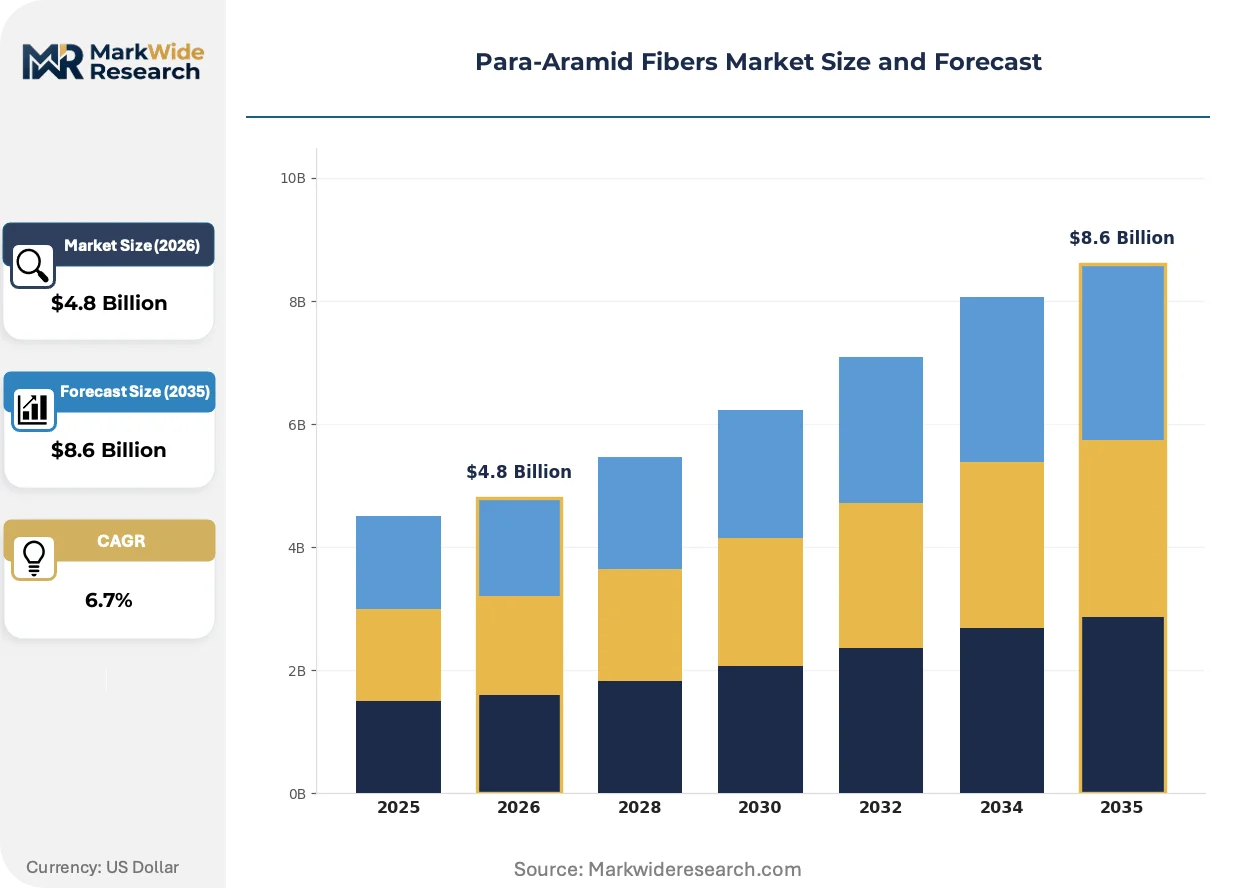
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kevlar, Twaron, Nomex, Technora End User: Aerospace, Automotive, Defense, Manufacturing Application: Body Armor, Ropes, Composites, Electrical Insulation Market Segment: Industrial, Consumer, Military, Protective Gear |
| Companies Covered | Teijin Limited, DuPont, Kolon Industries, Yantai Tayho Advanced Materials, Hyosung Advanced Materials, Taekwang Industrial, X-FIPER New Material, AFChina, HUVIS Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Para-Aramid Fibers Market Emerging Trajectories
Multi-axial fabric architectures and recycled fiber reclamation are reshaping how para-aramid producers compete on sustainability credentials and processing efficiency. Specification engineers are prioritizing lifecycle carbon metrics alongside ballistic performance.
Hybrid yarn constructions combining para-aramid with ultra-high molecular weight polyethylene are integrating into next-generation soft armor systems. Armor manufacturers in North America are adopting these blends to reduce backface deformation while maintaining areal density targets. The technology is integrating ballistic and comfort performance into single-layer solutions that displace traditional multi-ply Kevlar stacks.
REACH authorization requirements for aromatic amines are tightening precursor chemical sourcing protocols for European fiber producers. The regulation is forcing backward integration into captive para-phenylenediamine production or exclusive supplier partnerships. German and Dutch chemical regulators are coordinating enforcement timelines, compressing compliance windows for non-integrated market participants.
Long-term defense supply agreements are displacing spot purchasing for para-aramid raw material. Prime contractors in the US and UK are locking in five-to-seven year fiber supply commitments with penalty clauses for specification drift. Military procurement offices are driving this shift to secure supply chain resilience against geopolitical disruption.
Para-Aramid Fibers Market Segmentation
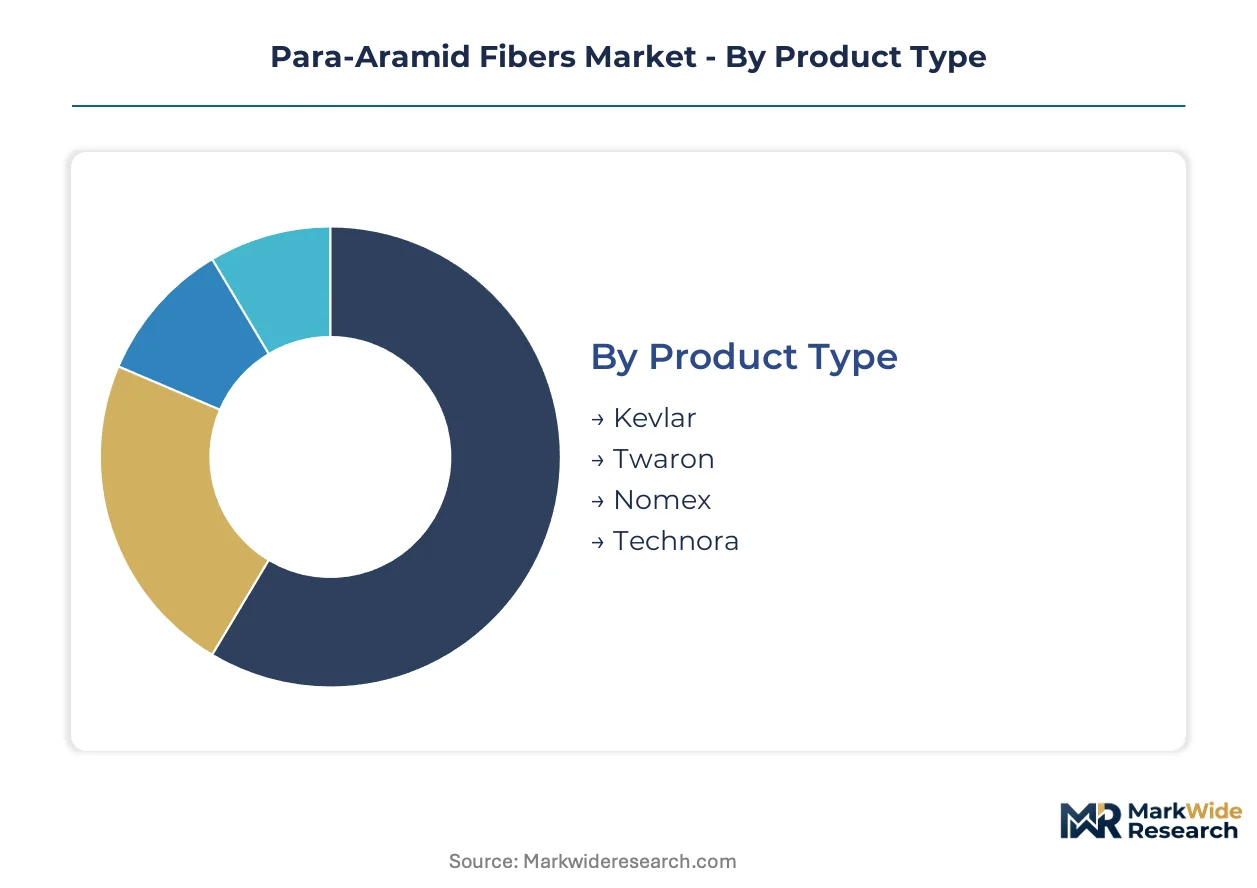
Para-aramid fiber buyers segment procurement by performance tier and certification burden, with defense contractors prioritizing ballistic consistency over unit cost while industrial purchasers optimize for thermal durability in high-cycle applications. Specification engineers weight tensile strength, areal density, and flame resistance differently across end-use channels, fragmenting supplier strategies.
Product Type:
Buyers select fiber chemistry based on the trade-off between tensile strength and thermal stability, with cost sensitivity varying sharply by end-use certification requirements.
- Kevlar:The para-aramid filament spun from poly-paraphenylene terephthalamide delivers the highest tensile strength-to-weight ratio among commercial grades, making it the default specification for US military soft armor systems governed by NIJ ballistic standards. Demand concentrates in domestic armor manufacturing clusters where long-term supply agreements with DuPont lock in specification continuity.
- Twaron:Teijin's equivalent para-aramid offers comparable ballistic performance with slightly lower modulus, capturing share in European defense procurement where EU PPE Regulation (EU) 2016/425 CE marking requirements favor established certification pathways. German and Dutch fabricators around the Düsseldorf-Cologne industrial belt specify Twaron for its integrated aramid-to-fabric pipeline and faster lot-to-lot consistency testing.
- Nomex:The meta-aramid variant sacrifices tensile strength for thermal stability exceeding 370°C, commanding premium pricing in electrical insulation and firefighter protective gear where flame resistance outweighs ballistic requirements.
- Technora:A copolymer para-aramid with enhanced fatigue resistance and chemical stability, specified in dynamic rope applications and marine cables where flex cycling and salt exposure degrade standard grades.
Volume sits with Kevlar and Twaron in defense channels; growth tilts toward Nomex as EU Green Deal flame-resistance specifications expand public procurement windows for halogen-free thermal protection.
End User:
Application-specific performance requirements fragment procurement patterns, with certification burden and volume scale determining supplier relationship structures.
- Aerospace:Structural composite specifications for airframes and engine nacelles demand para-aramid prepregs with void content below 1% and autoclave compatibility, concentrating demand with Tier 1 aerostructures manufacturers in France and Germany.
- Automotive:Lightweight vehicle platforms specify para-aramid composites for crash structures and battery enclosures, with German OEMs driving adoption through weight reduction targets in electric vehicle architectures.
- Defense:NATO body armor modernization programs and vehicle armor upgrades specify multi-axial para-aramid fabrics, with procurement accelerating across member states following revised threat assessments.
- Manufacturing:Industrial filtration, conveyor belting, and gaskets consume technical-grade para-aramid with lower certification barriers, creating volume channels with price-sensitive spot purchasing patterns.
Defense captures the steepest expansion trajectory; manufacturing holds the deepest volume base.
Application:
Functional performance hierarchy determines material selection, with life-safety applications tolerating minimal specification drift and industrial uses accepting broader performance bands.
- Body Armor:Soft and hard armor systems specify para-aramid for backface deformation control and multi-hit capability, with US and UK prime contractors locking in five-to-seven year fiber supply commitments to secure supply chain resilience.
- Ropes:Dynamic climbing ropes, marine mooring lines, and industrial hoisting cables exploit para-aramid fatigue resistance and UV stability, with European alpine equipment manufacturers driving specification innovation.
- Composites:Aerospace and automotive structural components integrate para-aramid with epoxy and thermoplastic matrices, with German automotive suppliers specifying recycled fiber content to meet EU sustainability procurement criteria.
- Electrical Insulation:Transformer wraps, motor slot liners, and cable insulation specify meta-aramid variants for thermal class F and H ratings, with demand concentrating in electrical equipment manufacturing clusters.
Composites gain share fastest; body armor retains the tightest supplier qualification timelines.
Market Segment:
Customer type determines pricing architecture and contract structure, with institutional buyers extracting performance guarantees unavailable to commercial purchasers.
- Industrial:Cement, steel, and chemical producers specify para-aramid filter bags for exhaust gas treatment, creating recurring volume with lower certification barriers than defense but higher price sensitivity.
- Consumer:Sporting goods, motorcycle apparel, and cut-resistant gloves reach end-users through retail channels, with brand positioning emphasizing safety certification marks over technical specifications.
- Military:National procurement offices contract for ballistic protection system lifecycle service rather than material-only supply, enabling fiber producers to capture recurring revenue through performance-based maintenance contracts.
- Protective Gear:Law enforcement, firefighting, and industrial safety equipment integrates para-aramid for multi-threat protection, with EU PPE Regulation tightening testing protocols and elevating premium-grade material demand.
Military contracts concentrate margin; industrial segments scale volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Japan and the United States while consumption concentrates in European defense procurement and Chinese industrial filtration. This geographic split creates trade flows of precursor chemicals and finished fiber. Logistics costs favor regional hub strategies near Düsseldorf, Seoul, and Shanghai.
United States
Defense procurement through the National Institute of Justice sustains demand for ballistic-grade fiber, with prime contractors locking multi-year supply commitments. The IRA's domestic manufacturing incentives support precursor chemical capacity expansion. Armor manufacturing concentrates in South Carolina and Virginia near military logistics corridors.
Germany
The Düsseldorf-Cologne industrial belt hosts fabricators serving EU defense and automotive OEMs with integrated aramid-to-fabric pipelines. REACH authorization requirements for aromatic amines tighten precursor sourcing protocols. Teijin's European operations anchor specification feedback loops with local Tier 1 suppliers.
China
Industrial filtration and conveyor belting consume technical-grade para-aramid at scale, with cement and steel producers driving volume procurement. MIIT standards govern domestic quality certification for protective textiles. Yangtze River Delta chemical parks host para-phenylenediamine production for captive fiber spinning.
Japan
Liquid crystal spinning expertise concentrates at legacy production facilities in Osaka and Nagoya, with technician cohorts nearing retirement. METI coordinates supply chain resilience initiatives for critical material security. Domestic producers maintain technology licensing revenue from global fiber operations.
South Korea
Hyosung and Kolon anchor para-aramid capacity serving domestic automotive lightweighting and export defense channels. The Busan-Ulsan industrial corridor integrates fiber production with composite fabrication for aerospace Tier 2 suppliers. Government R&D programs target meta-aramid substitution in thermal applications.
Para-Aramid Fibers Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the para-aramid value chain. Integrated chemical-to-fiber operations dominate premium ballistic grades, while specialized fabricators capture margin in technical textiles. Three archetypes define positioning: captive precursor producers, licensed technology spinners, and downstream composite integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure feedstock access and lock in defense procurement channels.
Among Japanese and Korean integrated producers, Teijin Limited, Kolon Industries, and Hyosung Advanced Materials exemplify the captive-precursor archetype with in-house control over para-phenylenediamine supply. These firms occupy positions that insulate margin from benzene derivative volatility. DuPont anchors the North American vector through established channel relationships with domestic armor manufacturers. Chinese specialists including Yantai Tayho Advanced Materials and X-FIPER New Material represent the technology-licensing tier, building regional scale through MIIT-compliant production platforms.
| Leading Market Players |
|---|
| Teijin Limited |
| DuPont |
| Kolon Industries |
| Yantai Tayho Advanced Materials |
| Hyosung Advanced Materials |
| Taekwang Industrial |
| X-FIPER New Material |
| AFChina |
| HUVIS Corporation |
| Others |
Supply Flow & Price Mechanics
Liquid crystal spinning technology concentration simultaneously elevates fixed-cost absorption for qualified producers and restricts supply elasticity, locking in premium pricing for ballistic-grade para-aramid while compressing margins for non-integrated competitors exposed to benzene derivative volatility.
Pricing Analysis
Margin tightening in technical-grade fiber reflects benzene derivative cost pass-through limitations and spot purchasing patterns among industrial buyers. Three-tier pricing structure across premium, standard, and economy levels separates NIJ-certified ballistic fiber from CE-marked industrial grades and uncertified technical textile feedstock. Cost-down pressure on standard-tier material accelerates because Chinese cement and steel producers negotiate volume procurement with minimal specification tolerance. Defense contractors exhibit lowest price sensitivity due to five-to-seven year supply commitments with penalty clauses, while manufacturing segments drive hardest bargain on per-kilogram contracts.
Supply Chain Analysis
Regional distribution centers near Düsseldorf, Seoul, and Shanghai compress logistics costs for precursor chemical delivery and finished fiber shipment. Supply concentrates in Japan, the United States, and South Korea, where Teijin, DuPont, and Hyosung control liquid crystal spinning capacity. Raw material sourcing draws from para-phenylenediamine and terephthaloyl chloride producers clustered in Yangtze River Delta and Gulf Coast chemical parks. Single-source vulnerability pervades precursor supply for European fabricators lacking captive para-phenylenediamine production. Distribution runs through defense prime contractor warehouses and Tier 1 aerostructures manufacturers with just-in-time composite prepreg requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid crystal spinning technician scarcity constrains capacity expansion across legacy production facilities, propping pricing power for qualified suppliers with retained polymer physics expertise.
For Market Incumbents: Hedge against feedstock volatility through backward integration into para-phenylenediamine production or exclusive supplier partnerships with Yangtze River Delta chemical parks. Lock in five-to-seven year defense supply commitments before REACH authorization timelines compress compliance windows for aromatic amine sourcing. For New Entrants and Emerging Players: Begin with high-temperature filtration media for cement and steel producers, where certification barriers fall below defense procurement thresholds and spot purchasing patterns enable market penetration. Target industrial belt fabricators around Düsseldorf-Cologne with recycled fiber content offerings aligned to EU sustainability procurement criteria. For Investors and Strategic Acquirers: Exit pathways concentrate in technology licensing to Chinese regional producers building MIIT-compliant capacity, with acquisition premiums attaching to captive precursor operations. Monitor EU Green Deal flame-resistance specification enforcement as inflection indicator for halogen-free para-aramid demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive para-phenylenediamine production insulates Teijin and DuPont from benzene derivative price swings. |
| Long-term Supply Agreement | Five-to-seven year fiber commitments with US and UK prime contractors secure volume visibility against geopolitical disruption. |
| Capacity Expansion | Additional liquid crystal spinning lines in South Korea serve Hyundai-Kia lightweighting programs and export defense channels. |
| Green Manufacturing Transition | Recycled fiber reclamation capabilities satisfy EU sustainability procurement criteria for German automotive Tier 1 suppliers. |
| Joint Venture | Technology licensing partnerships with Yantai Tayho accelerate regional scale in Chinese industrial filtration segments. |
Methodological Framework
Independent corroboration across fiber producer technical directors, defense procurement officers, and composite fabricator procurement leads underwrites the qualitative findings. Primary fieldwork encompassed plant managers at Düsseldorf-Cologne industrial belt facilities, R&D directors at Japanese liquid crystal spinning operations, and channel partners serving NATO defense logistics corridors. Secondary validation drew from customs trade data for para-aramid filament and fabric shipments, SEC 10-K disclosures from integrated chemical producers, and ECHA REACH authorization documentation for aromatic amine precursors. Bottom-up fiber demand modeling triangulated against top-down defense procurement budget allocations.
Rate-of-change decomposition across the projection horizon separates volume growth from price-mix effects and regional demand shifts. Segmentation dimensions encompass product chemistry tier, end-use certification burden, and geographic production hub clustering. CAGRs were derived from fitted trend extrapolation with elasticity adjustments for petrochemical feedstock price scenarios. Industry-specific forecast inputs include NIJ ballistic standard revision timelines and EU PPE Regulation enforcement intensity indices.
Underlying measurement precision varies by segment; defense procurement volumes carry tighter precision than industrial spot purchasing patterns. Forecasts reflect documented assumptions regarding REACH authorization phase-in schedules and NATO threat assessment revision cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Nanofibers Market
Synthetic Fibers
Polypropylene Fiber Market
Synthetic Fibers
Kevlar Fiber Market
Synthetic Fibers
Microfiber Leather Market
Synthetic Fibers
Designer Fiber Market
Synthetic Fibers
Global Synthetic Spider Silk Market
Synthetic Fibers
North America Aramid Fiber Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Staple Fibers Market
Synthetic Fibers
Carbon Fiber Strands Market
Synthetic Fibers
Clothing Fibers Market
Synthetic Fibers
Polyester Filament Market
Synthetic Fibers
High Temperature Fiber Market
Synthetic Fibers
Polyimide Fiber Market
Synthetic Fibers
High End Synthetic Suede Market
Synthetic Fibers
Europe Nanofiber Market