

Bio-Based Elastic Core-Spun Yarn for Denim Stretch Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Elastic Core-Spun Yarn for Denim Stretch Market Insights
Modular yarn sourcing is realigning how denim mills configure their elastic supply contracts. Hyosung TNC leverages its integrated spandex-to-yarn pipeline to secure long-term core supply agreements with European fabricators. Candiani Denim anchors its sustainability positioning through vertically controlled bio-based feedstock partnerships in Italy. Kaihara Denim specializes in fine-count core-spun constructions for Japanese premium selvedge lines.
Bio-based elastic core-spun yarn for denim stretch combines a renewable elastomer core with natural fiber sheathing through ring-spinning or Sirospun systems, typically achieving 15-40% elongation recovery for garment fit retention. The primary commercial purpose is replacing petroleum-derived spandex in stretch denim with lower-carbon alternatives that maintain wash performance and seam stability. Spandex-dominant fiber configurations still lead volume but Tencel-sheathed variants represent the fastest-growing margin pool as brands pursue biodegradability claims. Fashion apparel commands the largest end-use share while activewear applications show the steepest trajectory due to cross-category athleisure demand.
EU REACH and the EU Green Deal textile strategy are tightening disclosure requirements for synthetic polymer content, directly shaping bio-based yarn certification standards and mill-level compliance investments. The US EPA industrial fiber guidelines and California's SB 707 textile extended producer responsibility framework add parallel compliance layers for brands selling across both markets. Stakeholders must monitor whether bio-based elastomer feedstock capacity can scale ahead of tightening regulatory thresholds for fossil-derived fiber content.
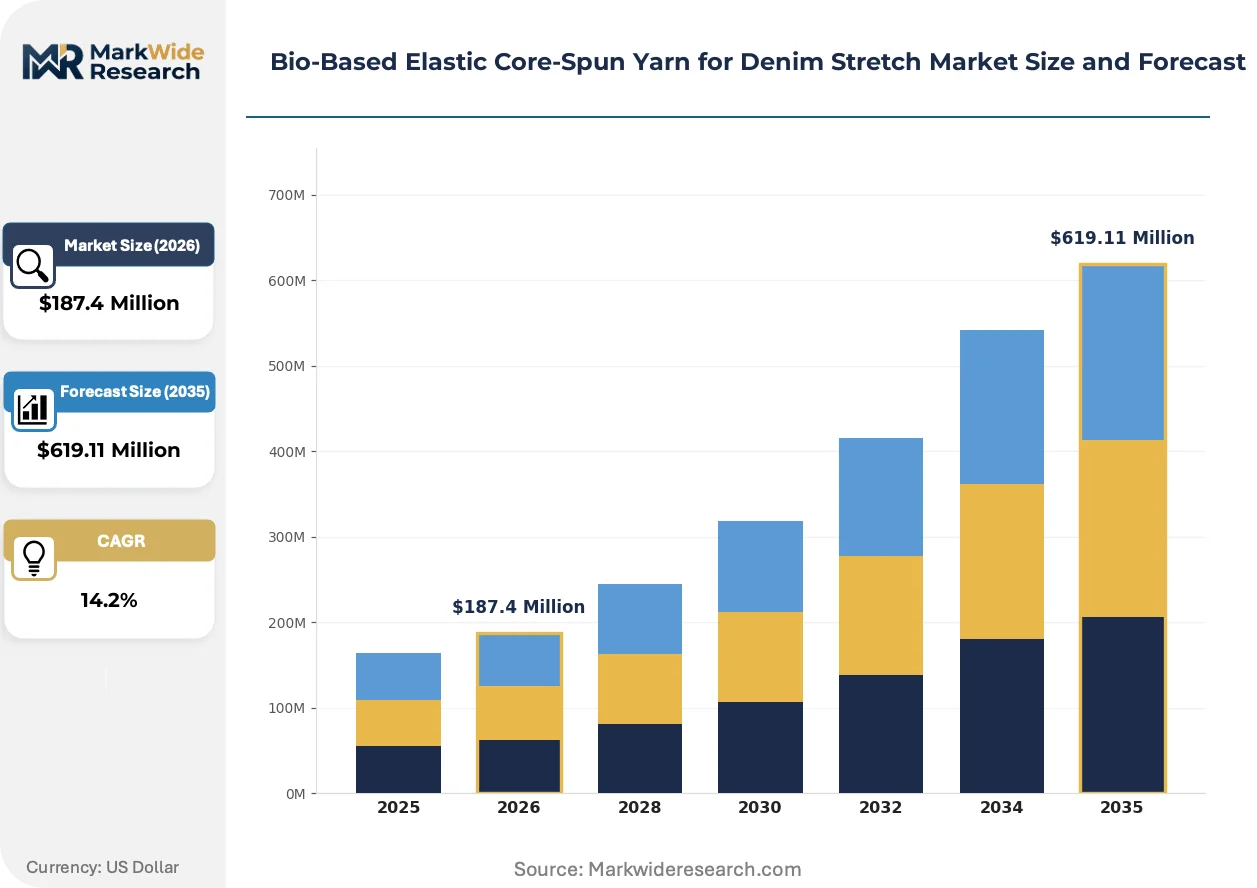
Market Dynamics
EU REACH disclosure mandates and the EU Green Deal textile strategy are compressing synthetic fiber tolerance thresholds, forcing denim mills to reconfigure elastic yarn sourcing around certified bio-based feedstocks before 2030 compliance deadlines.
Growth Catalysts
- EU Green Deal synthetic caps:Tightening fossil-derived fiber limits under the EU textile strategy are mandating bio-based elastomer adoption in European denim production.
- Fashion apparel wash performance requirements:Premium selvedge and stretch denim programs require 15-40% elongation recovery that bio-based core-spun constructions now achieve.
- Italy-Japan procurement corridors:Specialized mill clusters in Lombardy and Okayama Prefecture are consolidating long-term offtake agreements for certified sustainable elastic cores.
Market Restraints
- Bio-based feedstock cost premiums:Renewable elastomer raw materials trade at 30-50% above petroleum-derived spandex benchmarks, compressing mill margins.
- Core supplier concentration:Commercial-scale bio-based elastomer polymerization capacity clusters in South Korea and limited European sites, creating single-source vulnerability.
- California SB 707 EPR layering:Extended producer responsibility frameworks add parallel compliance costs for brands selling across US-EU markets without harmonized standards.
Strategic Opportunities
- Activewear athleisure crossover:Cross-category demand from performance apparel brands creates new volume channels beyond traditional denim.
- Tencel-sheathed biodegradability positioning:Cellulosic fiber wrapping enables end-of-life claims that petroleum-spandex cannot match.
- US EPA industrial fiber guideline alignment:Early compliance with emerging federal disclosure standards opens preferential supplier status for domestic mills.
Industry Challenges
- Ring-spinning technician scarcity:Fine-count core-spun construction requires specialized Sirospun system operators that regional training programs have not scaled.
- Multi-certification timeline compression:Simultaneous pursuit of OEKO-TEX, GOTS, and bio-based content verification creates 12-18 month approval bottlenecks.
- Legacy spandex inventory stranding:Mills face write-down pressure on petroleum-elastic stockpiles as brand RFPs harden bio-based minimums.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Elastic Core-Spun Yarn for Denim Stretch Market Trends and Innovations
Denim stretch yarn technology is fragmenting into modular, certifiable subsystems that let mills swap core elastomer chemistries and sheath fibers independently to meet shifting brand sustainability specifications.
Polyol-based thermoplastic polyurethane elastomer cores derived from castor oil or corn starch feedstocks are modularizing how mills configure stretch performance tiers. Italian and Japanese premium fabricators are adopting these cores fastest, locking in 5-7 year supply contracts that bypass volatile petroleum-spandex spot markets. This modularization is compressing the traditional spandex-to-yarn value chain into integrated bio-feedstock partnerships.
REACH registration requirements for polymer intermediates are tightening substance-level traceability mandates that bio-based elastomer suppliers must document. The industrial consequence is a new certification infrastructure where polymerization batch records travel with yarn lots through weaving and finishing. High-end fashion denim programs in France and Germany are absorbing these compliance costs fastest, while mid-tier Asian mills face 18-24 month system upgrade timelines.
Brand sourcing teams are consolidating approved supplier lists around vertically controlled bio-based feedstock partnerships that guarantee lot-level carbon intensity data. Direct mill-yarn maker relationships are displacing traditional fiber distributor intermediaries in premium denim procurement. This concentration is most visible in Japanese selvedge lines where Kaihara-style fabricators now specify exact castor oil-derived polyol percentages in purchase orders.
Bio-Based Elastic Core-Spun Yarn for Denim Stretch Market Segmentation
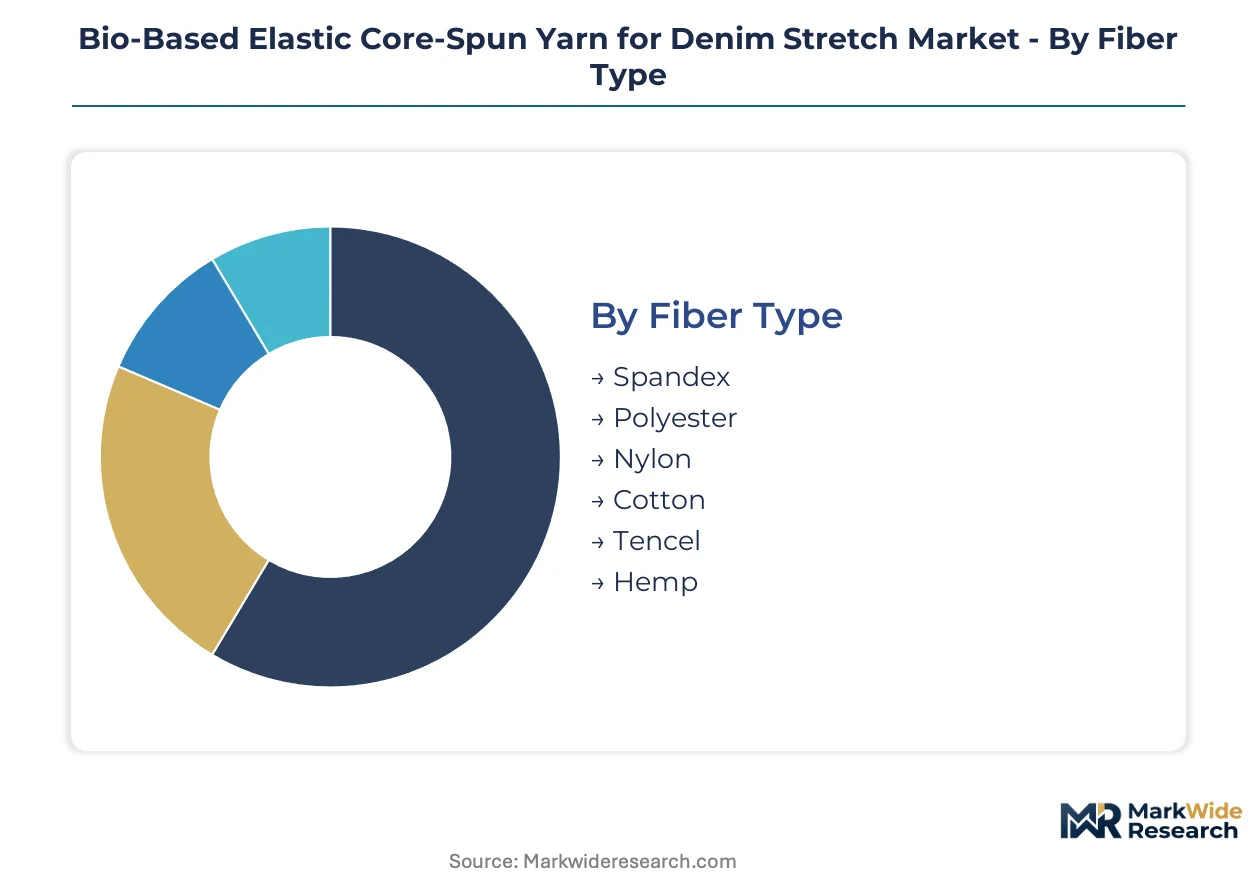
Segmentation in bio-based elastic core-spun yarn reveals how denim mills configure supply contracts around fiber chemistry, yarn construction, and end-use performance tiers. Each dimension carries distinct margin profiles and certification requirements that shape procurement decisions.
Fiber Type:
Integration depth varies sharply across fiber chemistries, with standalone bio-based elastomers commanding premium positioning versus embedded petroleum-legacy alternatives.
- Spandex:Petroleum-derived polyurethane elastomer cores dominate current volume through established polymerization infrastructure and 15-40% elongation recovery specifications. Italian denim mills in Lombardy and Okayama Prefecture fabricators source these cores under long-term contracts, though EU Green Deal synthetic caps are forcing feedstock transitions.
- Tencel:Cellulosic lyocell sheathing enables modular biodegradability claims that petroleum-spandex cannot match. Premium selvedge programs specify exact Tencel percentages for end-of-life positioning, with fashion apparel brands absorbing 30-50% cost premiums for certified sustainable elastic cores.
- Polyester:Recycled PET variants serve mid-tier stretch denim where wash performance requirements are less stringent than premium lines.
- Nylon:Bio-based polyamide alternatives from castor oil feedstocks occupy niche performance tiers in activewear crossover applications.
- Cotton:Natural fiber sheathing provides conventional hand-feel for heritage denim programs avoiding synthetic disclosure complexity.
- Hemp:Bast fiber reinforcement targets durability positioning in workwear segments with lower stretch recovery demands.
Spandex leads volumes today; Tencel is gaining share fastest.
Yarn Count:
Cost tier stratification separates premium fine-count constructions from standard and economy bulk offerings.
- 30s:Mid-count ring-spun construction balances selvedge aesthetic with stretch functionality for Japanese premium denim lines. Kaihara-style fabricators specify 30s for core-spun programs requiring Sirospun system precision and 15-20% elongation recovery.
- 40s:Fine-count Sirospun systems enable lightweight stretch denim for fashion apparel where garment drape and seam stability compete as priorities. Italian mills deploy 40s counts for high-end women's stretch programs with certified bio-based elastomer cores.
- 10s:Heavy-count construction serves rigid workwear applications with minimal stretch requirements.
- 20s:Standard bulk count dominates commodity stretch denim production.
- 50s:Ultra-fine count occupies experimental positioning for next-generation lightweight activewear.
30s commands the largest production commitment; 40s shows the steepest expansion trajectory.
End Use/Application:
Application maturity separates established fashion denim from emerging athleisure crossovers with divergent performance specifications.
- Fashion Apparel:Premium selvedge and stretch denim programs require certified sustainable elastic cores with documented castor oil-derived polyol percentages. EU REACH disclosure mandates and California SB 707 EPR frameworks concentrate compliance investment in this segment.
- Activewear:Cross-category athleisure demand from performance apparel brands creates new volume channels beyond traditional denim, with 20-35% elongation recovery specifications and moisture-wicking sheath requirements.
- Workwear:Durability-focused applications prioritize abrasion resistance over stretch recovery.
- Casual Wear:Mid-tier stretch jeans serve price-sensitive consumers with standard petroleum-elastic configurations.
- Denim Jackets:Outerwear applications require lower elongation recovery than pant constructions.
- Home Textiles:Upholstery and decorative applications represent experimental offshoot demand.
Fashion apparel anchors current procurement volumes; activewear is climbing the fastest.
Distribution Channel:
Supply concentration patterns separate vertically controlled direct relationships from fragmented intermediary channels.
- Direct Sales:Mill-yarn maker partnerships displace traditional fiber distributors in premium denim procurement, with 5-7 year supply contracts guaranteeing lot-level carbon intensity data. Hyosung TNC leverages integrated spandex-to-yarn pipelines for European fabricator agreements.
- Fabricators:Denim mill clusters in Lombardy and Okayama Prefecture consolidate approved supplier lists around bio-based feedstock partnerships with exact elastomer chemistry specifications.
- Wholesale:Traditional fiber distributors serve mid-tier Asian mills facing 18-24 month certification system upgrade timelines.
- Online Platforms:Digital procurement channels facilitate spot purchasing for smaller denim operations.
- Textile Exhibitions:Première Vision and similar events enable supplier qualification for emerging bio-based elastomer entrants.
Direct sales channels capture the highest value contracts; fabricator relationships are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denim stretch yarn manufacturing traces its commercial lineage to mid-20th century Italian and Japanese textile engineering, where ring-spinning innovations first enabled elastic core integration. The current bio-based transition builds upon these established technical foundations while dispersing production across specialized regional clusters.
Italy
Candiani Denim anchors European bio-based elastic yarn procurement through vertically controlled feedstock partnerships in Lombardy. EU REACH disclosure mandates and the EU Green Deal textile strategy compress synthetic fiber tolerance thresholds, forcing mills to reconfigure sourcing before 2030 deadlines. The Busto Arsizio cluster concentrates certified sustainable elastic core production for premium selvedge programs.
Japan
Kaihara Denim specializes in fine-count Sirospun constructions for Okayama Prefecture's premium selvedge lines, specifying exact castor oil-derived polyol percentages in purchase orders. METI industrial fiber guidelines reinforce traceability requirements that bio-based elastomer suppliers must document through polymerization batch records. The Kojima district maintains dense concentrations of ring-spinning technicians capable of 40s count precision.
South Korea
Hyosung TNC leverages integrated spandex-to-yarn pipelines to secure long-term core supply agreements with European fabricators. The country's commercial-scale bio-based elastomer polymerization capacity creates single-source vulnerability for mills dependent on renewable polyurethane feedstocks. Gyeonggi Province hosts the primary polymerization facilities serving global denim stretch yarn demand.
United States
California's SB 707 textile extended producer responsibility framework adds compliance layers for brands selling across US-EU markets without harmonized standards. The Los Angeles denim manufacturing corridor faces write-down pressure on petroleum-elastic stockpiles as brand RFPs harden bio-based minimums. EPA industrial fiber guidelines shape emerging federal disclosure standards that domestic mills must navigate.
China
Advance Denim and mid-tier fabricators in Guangdong Province face 18-24 month certification system upgrade timelines to meet OEKO-TEX and bio-based content verification requirements. MIIT industrial standards and dual carbon goals accelerate feedstock transition pressures across the Yangtze River Delta denim belt. The country's synthetic fiber dominance creates legacy inventory stranding risks as regulatory thresholds tighten.
Bio-Based Elastic Core-Spun Yarn for Denim Stretch Market Competitive Landscape
The competitive structure tilts toward vertically integrated chemical-to-yarn specialists and premium denim fabricators with captive feedstock partnerships. Market concentration clusters around South Korean polymerization capacity and Italian-Japanese mill clusters with long-term offtake agreements. Three archetypes dominate: integrated elastomer producers controlling upstream polymerization, premium denim mills with backward-linked bio-feedstock partnerships, and specialty spinners focused on fine-count Sirospun constructions. Capacity expansion and strategic partnerships represent the dominant competitive moves, with mills locking in 5-7 year supply contracts to bypass volatile spot markets.
Among South Korea-based integrated producers, Hyosung TNC exemplifies the chemical-to-yarn archetype through its spandex-to-core-spun pipeline. Italian fabricator Candiani Denim and Japanese specialist Kaihara Denim occupy positions within the premium mill tier, anchoring procurement consolidation around certified sustainable elastic cores with documented carbon intensity data. These three represent distinct competitive vectors—integrated supply security, vertical feedstock control, and fine-count construction specialization—that structure rivalry across the bio-based transition.
| Leading Market Players |
|---|
| The LYCRA Company |
| Hyosung TNC |
| Candiani Denim |
| Asahi Kasei |
| Advance Denim |
| Kaihara Denim |
| Toray Industries |
| Teijin Frontier |
| Indorama Ventures |
| Others |
Pricing and Supply Chain Analysis
Ring-spinning technician scarcity in Okayama Prefecture and Lombardy widens labor-cost spreads between premium fine-count and standard bulk yarn tiers. EU REACH compliance investments and bio-based feedstock premiums compound these differentials, pushing procurement decisions toward long-term contract structures that lock in margin visibility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified bio-based elastomer cores with full carbon traceability from transitional petroleum-bio blends and legacy petroleum-spandex configurations. Price differentiation rests on certification grade and volume scale, with fashion apparel brands absorbing premiums for OEKO-TEX and GOTS verification. Cost compression in mid-tier Asian mills intensifies because of 18-24 month certification bottlenecks. Economy buyers exhibit highest price sensitivity; premium selvedge fabricators show lowest.
Supply Chain Analysis
Regional distribution centers in Gyeonggi Province, Busto Arsizio, and Kojima district anchor hub-and-spoke patterns for bio-based elastomer cores and finished yarn. Supply draws from South Korean polymerization facilities, Italian compounding sites, and Japanese Sirospun spinning houses. Single-source vulnerability concentrates in renewable polyurethane feedstock capacity. Distribution runs through direct mill-yarn maker partnerships displacing traditional fiber intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds as a regulatory compounder. EU Green Deal synthetic fiber caps mandate bio-based elastomer adoption ahead of 2030 compliance deadlines, hardening demand for certified sustainable elastic cores.
For Market Incumbents: Deploy long-term offtake agreements as the primary lever. Secure 5-7 year supply contracts with South Korean polymerization facilities to bypass volatile petroleum-spandex spot markets and defend against emerging bio-based elastomer entrants. Invest in backward integration into castor oil-derived polyol feedstocks to protect margin compression from 30-50% renewable raw material premiums. For New Entrants and Emerging Players: Launch via direct sales to mid-tier Asian denim mills facing certification system upgrade timelines. Target Guangdong Province fabricators underserved by premium Italian-Japanese supplier networks. Position around rapid OEKO-TEX and bio-based content verification services that compress 12-18 month approval bottlenecks for mills without legacy compliance infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among specialty Sirospun spinners with fine-count construction capabilities but limited bio-based feedstock partnerships. Long-term viability over the next decade hinges on vertical control over certified sustainable elastic core supply. Watch ring-spinning technician training program scale as the inflection signal—scarcity here determines which regional clusters capture premium denim procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Candiani-style vertical partnerships guarantee lot-level carbon intensity data for EU Green Deal compliance. |
| Long-term Supply Agreement | Hyosung TNC leverages integrated pipelines to secure European fabricator contracts bypassing spot volatility. |
| Certification Investment | Simultaneous OEKO-TEX, GOTS, and bio-based verification opens premium selvedge procurement channels. |
| Capacity Expansion in Fine-Count Sirospun | Kaihara Denim specializes 40s count precision for Japanese premium lines requiring exact polyol specifications. |
| Joint Venture with Polymerization Specialist | Italian-Japanese mill clusters consolidate around shared castor oil-derived polyurethane capacity to reduce single-source risk. |
Research Methodology
Coverage spans Italy, Japan, South Korea, and the United States, with primary inputs from each regional cluster. Primary interviews with denim mill procurement directors, ring-spinning technicians, bio-based elastomer polymerization engineers, and sustainability certification auditors combined with secondary validation from EU REACH registration databases, METI industrial fiber guidelines, MIIT dual carbon policy filings, and California SB 707 regulatory texts. Bottom-up yarn production estimates and top-down denim stretch fabric demand triangulate market sizing.
Rate-of-change decomposition separates volume growth from value expansion across fiber type, yarn count, end-use application, and distribution channel dimensions. CAGRs derive from segment-level elasticity modeling against regulatory compliance deadlines and brand RFP bio-based minimum thresholds. Forecast inputs incorporate polymerization batch record traceability requirements and ring-spinning technician training pipeline capacity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Green Deal enforcement or South Korean feedstock capacity constraints. Forecasts reflect assumptions about certification timeline compression and legacy petroleum-elastic inventory write-downs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.