
 IMO Fiber Market | 2026-2036
IMO Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
IMO Fiber Market Foresight
The capital-intensity divergence between integrated fiber producers and specialty compounders is rotating competitive advantage toward upstream players with captive polymer supply. Tate & Lyle PLC leverages its corn wet-milling infrastructure to secure consistent isomaltooligosaccharide feedstock for fiber derivatives. Roquette Frères anchors its position through pea-protein adjacent fermentation capacity that sustains dual-product economics. Cargill competes via its global agricultural origination network, which controls raw material cost volatility across multiple hemispheres.
IMO Fiber refers to isomaltooligosaccharide-derived functional fibers engineered for marine-grade fire resistance, thermal stability, and low smoke toxicity, typically processed through controlled enzymatic polymerization to achieve degree-of-polymerization ranges between three and ten units. These fibers serve primarily as reinforcement matrices in composite bulkhead panels, insulation wraps, and structural laminates where International Maritime Organization safety protocols mandate limited flame spread and reduced toxic gas emission. Glass Fiber formulations dominate current specification sheets for hull and deck applications due to cost-efficiency and established supply chains, while Carbon Fiber prepregs command premium positioning in superyacht and naval segments where weight reduction justifies material substitution. Natural Fiber variants from flax and hemp sources are gaining traction in European ferry retrofits as shipyards respond to EU Green Deal procurement guidelines favoring bio-based content thresholds.
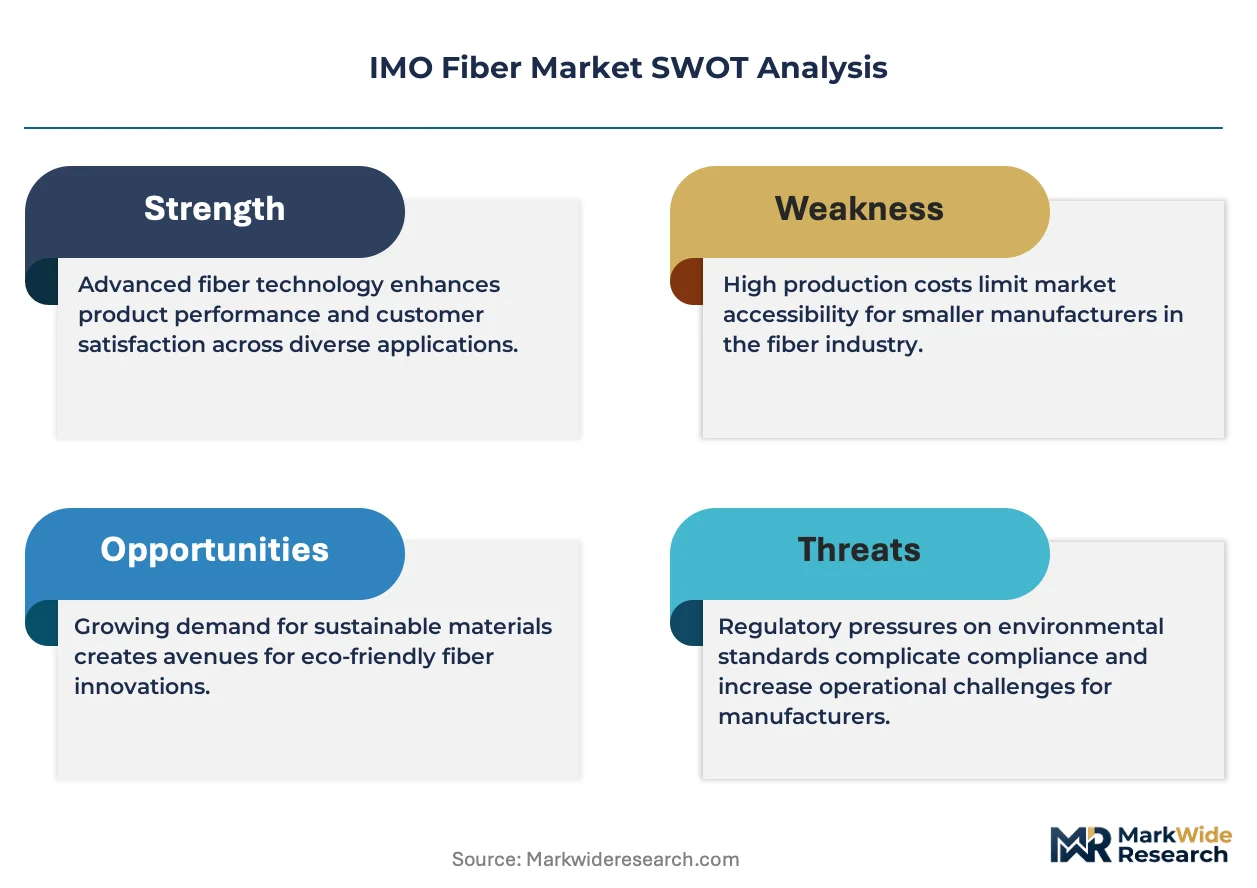
The European Maritime Safety Agency enforces MED certification for all fiber-reinforced composites installed on EU-flagged vessels, creating a compliance barrier that filters out uncertified Asian suppliers. The International Maritime Organization's ongoing review of the FTP Code is expected to tighten smoke-density index requirements, which would accelerate reformulation cycles among compounders serving the cruise and passenger vessel segments. Stakeholders must monitor how classification societies harmonize testing protocols across Lloyd's Register, DNV, and ClassNK, as divergent approval timelines could fragment procurement strategies for multi-registry fleets.
Market Dynamics
The revised SOLAS fire-safety protocols are compressing reformulation cycles across marine fiber supply chains, forcing compounders to recertify bulkhead laminates against stricter smoke-toxicity thresholds before newbuild contracts finalize.
Growth Catalysts
- LNG Carrier Newbuild Surge:South Korean shipyards in Busan and Ulsan are specifying IMO-compliant fiber matrices for cryogenic insulation systems, creating dedicated demand for low-thermal-conductivity prepregs.
- EU Green Deal Procurement Mandates:Ferry operators retrofitting Baltic and North Sea routes must meet bio-based content thresholds, accelerating flax and hemp fiber adoption in composite deck structures.
- Enzymatic Polymerization Advances:Controlled fermentation processes now yield isomaltooligosaccharide chains with precise degree-of-polymerization targeting, improving batch consistency for fire-resistant formulations.
Market Restraints
- Raw Material Cost Volatility:Corn wet-milling feedstock prices fluctuate with agricultural commodity cycles, squeezing margin predictability for integrated producers dependent on North American grain origination.
- Supply Concentration Risk:East Asian fermentation capacity clusters around Nagasaki and Busan, creating single-source vulnerability for European compounders seeking MED-certified fiber supplies.
- Technical Limitation:Natural fiber variants from flax and hemp sources exhibit inconsistent moisture absorption profiles, complicating qualification for high-humidity engine-room applications.
Strategic Opportunities
- Underpenetrated Naval Segment:NATO surface combatant programs in Italy and Spain remain specification-locked on legacy aramid systems, presenting conversion potential for carbon-IMO fiber hybrid laminates.
- Technology Convergence:Integration of enzymatic fiber production with adjacent pea-protein fermentation streams enables dual-product economics and capital efficiency for compounders.
- Regulatory Tailwind:The International Maritime Organization's pending FTP Code revision will tighten smoke-density index requirements, forcing cruise operators into accelerated material upgrade cycles.
Industry Challenges
- Certification Timeline Compression:MED approval pathways through Lloyd's Register and DNV now require 18-24 month validation cycles, misaligning with shipyard production schedules.
- Skill Gap in Fire Chemistry:Compounders lack sufficient formulation chemists trained in halogen-free flame-retardant synergies specific to isomaltooligosaccharide-derived matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IMO Fiber Market |
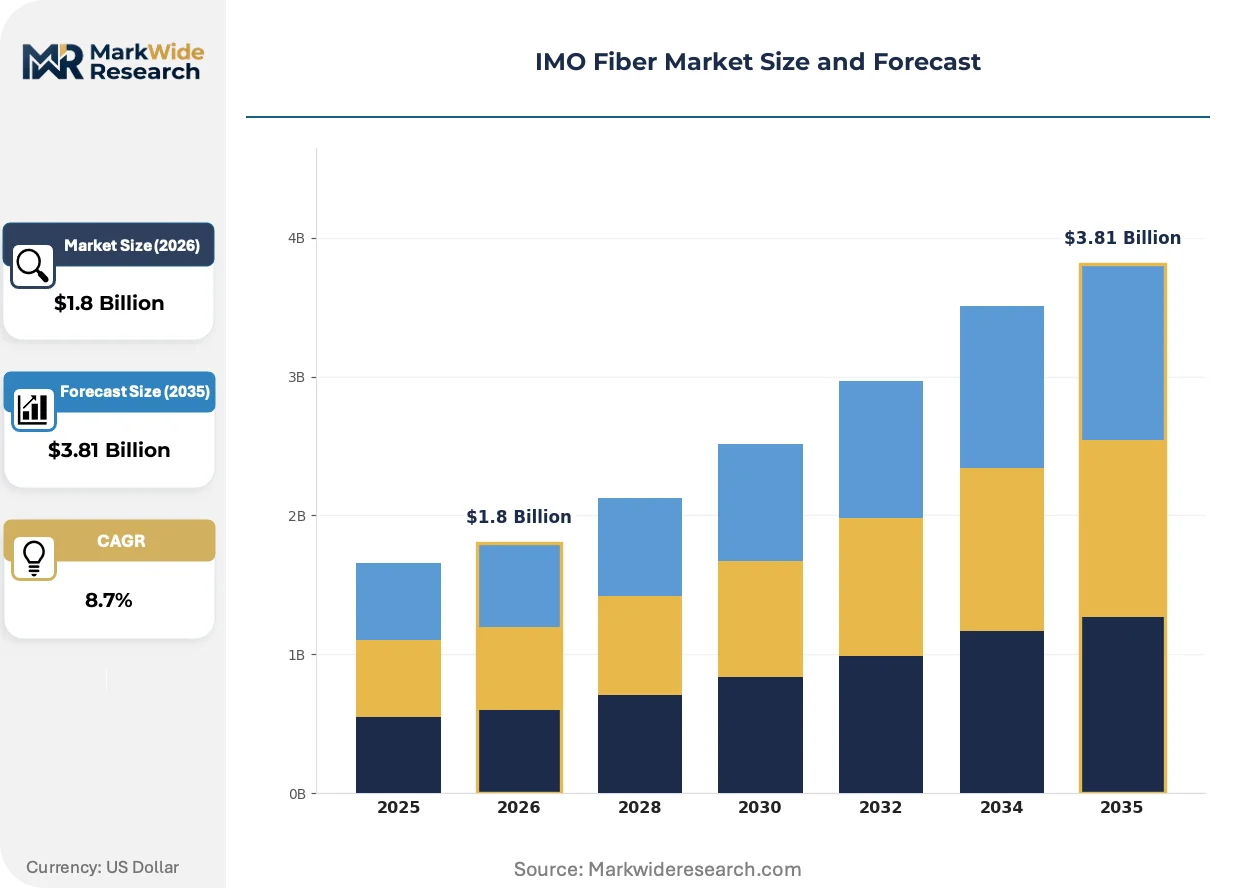
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Fiber, Carbon Fiber, Aramid Fiber, Natural Fiber Application: Aerospace, Automotive, Construction, Sports Equipment End User: Manufacturers, Retailers, Distributors, Importers Form: Chopped Strands, Rovings, Fabrics, Prepregs |
| Companies Covered | Tate & Lyle PLC, Ingredion Incorporated, Roquette Frères, Cargill, ADM, Shandong Bailong Group Co., Ltd., BioNeutra Global Corporation, Baolingbao Biology Co., Ltd., Fonterra Co-operative Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IMO Fiber Market Shifts & Advancements
Marine fiber markets are experiencing active displacement of incumbent chemistries by bio-engineered alternatives, while regulatory harmonization efforts and procurement centralization reshape competitive access.
Hybrid natural-synthetic fiber prepregs are displacing conventional glass-reinforced systems in Baltic ferry retrofits. German and Danish shipyards specify flax-IMO fiber laminates for passenger deck panels to satisfy EU Green Deal bio-content mandates. This substitution is compressing price premiums for established E-glass supply chains while fragmenting specification authority between sustainability officers and naval architects.
REACH restrictions on halogenated flame retardants are forcing reformulation of smoke-toxicity profiles in EU-flagged vessels. Compounders serving cruise and passenger segments must eliminate brominated additives from bulkhead laminates ahead of 2026 compliance deadlines. Mediterranean operators are accelerating qualification timelines with alternative intumescent systems to avoid dry-dock scheduling conflicts.
Shipyard procurement departments are consolidating fiber specifications across multi-vessel programs, reducing qualified supplier lists from twelve to four vendors per contract. Japanese and South Korean builders now mandate multi-registry certification (Lloyd's Register plus ClassNK) upfront, eliminating post-qualification flexibility. This concentration is visible most acutely in LNG carrier construction at Hyundai Heavy Industries and Mitsubishi Shipbuilding yards.
IMO Fiber Market Segmentation
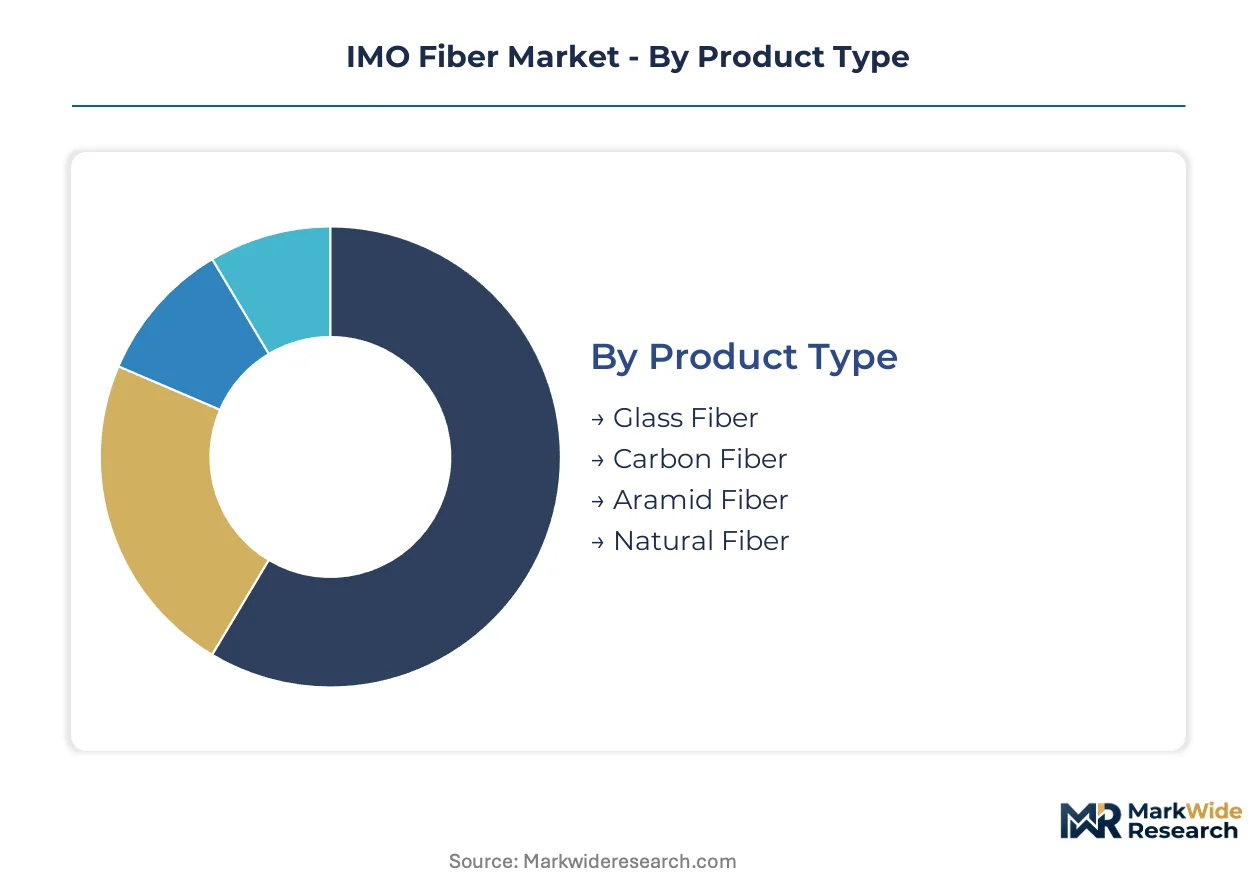
IMO Fiber procurement decisions split across material chemistry, processing form, and end-use certification requirements. Shipyards and compounders navigate trade-offs between fire-performance ratings, bio-content mandates, and supply security when selecting fiber specifications for marine construction.
Product Type:
Glass Fiber faces intensifying substitution pressure from bio-based alternatives as EU Green Deal procurement rules tighten bio-content thresholds for ferry retrofits.
- Glass Fiber:E-glass and S-glass formulations dominate hull reinforcement and bulkhead laminates due to established MED certification pathways and cost-efficient supply from South Korean and Japanese producers. Hyundai Heavy Industries and Mitsubishi Shipbuilding specify glass-reinforced prepregs for LNG carrier cryogenic insulation systems where thermal conductivity requirements override weight considerations.
- Carbon Fiber:High-modulus prepregs command premium positioning in superyacht and naval segments where specific strength ratios justify material substitution. Italian and Spanish NATO surface combatant programs remain specification-locked on legacy aramid systems, presenting conversion potential for carbon-IMO fiber hybrid laminates with enhanced blast resistance.
- Aramid Fiber:Legacy systems in ballistic and thermal protection applications face displacement by IMO-compliant alternatives with lower smoke toxicity profiles.
- Natural Fiber:Flax and hemp variants gain traction in Baltic ferry retrofits as German and Danish shipyards respond to EU Green Deal mandates.
Glass Fiber anchors the volume base while Natural Fiber gains share at the steepest rate.
Application:
Cost tier stratification separates aerospace-grade specifications from construction commodity demand, with automotive and sports equipment occupying intermediate positions.
- Aerospace:Cabin interior panels and cargo bay liners require FAA-compliant fire-resistant fibers with stringent smoke-density index ratings. Boeing and Airbus tier-1 suppliers source IMO fiber derivatives for maritime-adjacent applications where dual certification reduces qualification overhead.
- Automotive:Underbody shields and battery enclosure composites utilize chopped strand mats for thermal runaway protection. European EV manufacturers specify halogen-free formulations ahead of REACH compliance deadlines, compressing reformulation cycles for compounders.
- Construction:Fire-rated facade panels and structural reinforcement represent volume-driven demand with price-sensitive procurement.
- Sports Equipment:Niche applications in racing yacht hulls and high-performance marine craft favor prepregs with optimized strength-to-weight ratios.
Construction absorbs the highest absolute volume while Aerospace commands the steepest price premiums.
End User:
Customer type determines specification authority, with direct manufacturers holding formulation control versus intermediaries managing inventory risk.
- Manufacturers:Tier-1 compounders and laminate producers dominate procurement for newbuild contracts, consolidating qualified supplier lists from twelve to four vendors per multi-vessel program. Japanese and South Korean builders now mandate multi-registry certification upfront.
- Retailers:Distribution channels for maintenance, repair, and overhaul supplies serve retrofit markets with shorter lead time requirements.
- Distributors:Regional stockholding intermediaries buffer supply concentration risk around Nagasaki and Busan fermentation clusters.
- Importers:European compounders dependent on Asian fiber supplies navigate MED certification barriers that filter out uncertified suppliers.
Manufacturers control specification authority while Importers face the steepest compliance burden expansion.
Form:
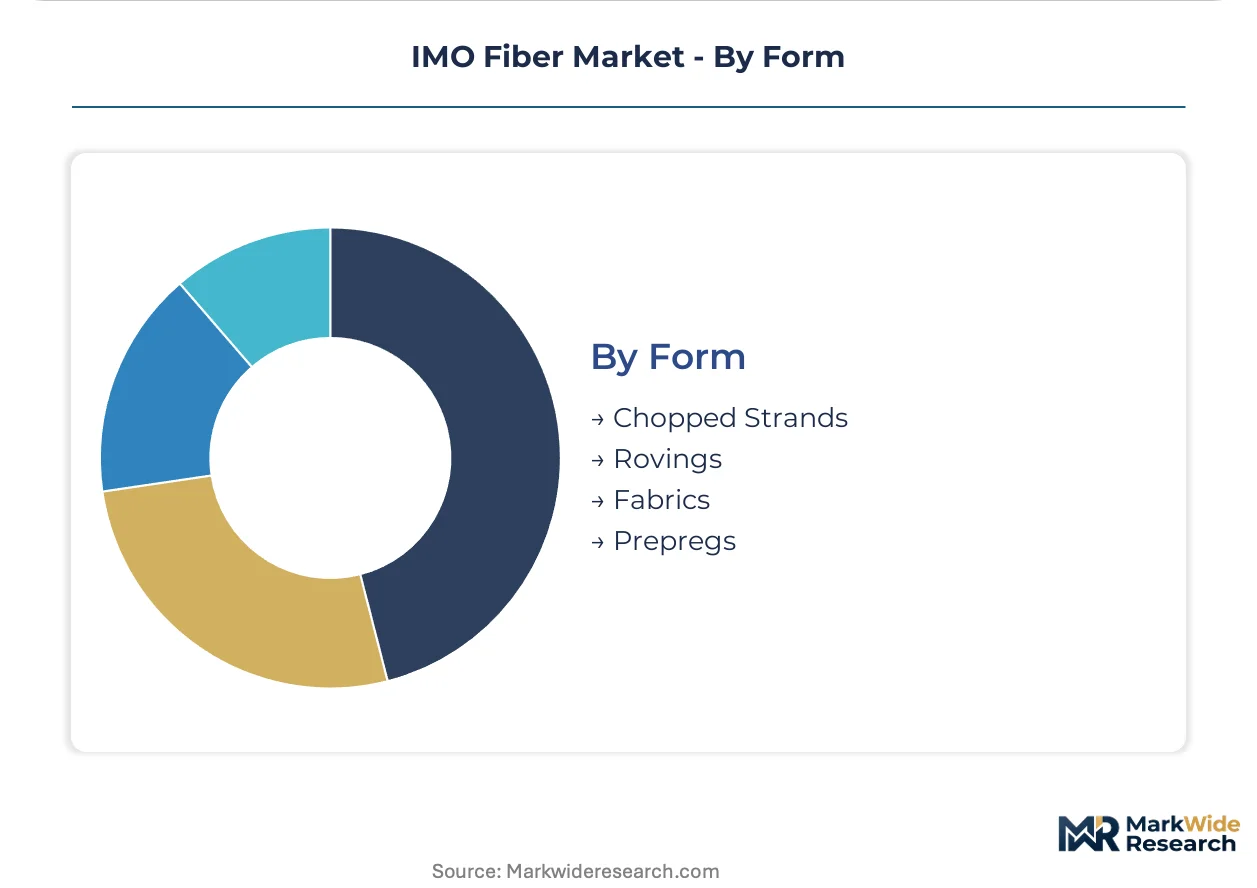
Processing maturity separates established roving and fabric formats from advanced prepreg systems with integrated resin matrices.
- Prepregs:Resin-impregnated fiber sheets with controlled tack and drape properties enable automated layup for complex bulkhead geometries. Cruise ship builders at Fincantieri and Meyer Werft specify prepregs to minimize volatile organic compound emissions during fabrication.
- Rovings:Continuous glass fiber bundles serve pultrusion and filament winding processes for structural profiles and piping systems.
- Fabrics:Woven and non-woven mats provide hand-layup flexibility for repair applications and prototype development.
- Chopped Strands:Short-fiber reinforcements for bulk molding compounds and thermoplastic matrix integration.
Rovings and Fabrics together anchor the volume base while Prepregs expand most quickly in premium marine segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean shipyards consume IMO Fiber primarily for cryogenic LNG insulation, whereas European yards prioritize bio-content compliance for ferry retrofits, and Japanese builders balance both thermal performance and multi-registry certification demands.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries drive demand for low-thermal-conductivity prepregs in LNG carrier construction at Busan and Ulsan yards. MFDS oversees marine material safety approvals alongside ClassNK certification requirements. The Busan-Ulsan corridor concentrates domestic fermentation capacity for isomaltooligosaccharide feedstock supply.
Japan
Mitsubishi Shipbuilding and Imabari Shipyard specify IMO Fiber matrices for cruise ship bulkheads and naval auxiliary vessels. METI coordinates with Lloyd's Register Asia to harmonize smoke-toxicity testing protocols. Nagasaki hosts specialized compounders serving both domestic builders and export markets for MED-certified laminates.
Germany
Meyer Werft and Fincantieri German operations retrofit Baltic ferries with flax-IMO fiber hybrid panels to satisfy EU Green Deal bio-based thresholds. ECHA enforces REACH restrictions on halogenated flame retardants in vessel interiors. Hamburg and Rostock shipyards coordinate procurement through consolidated supplier lists reduced to four qualified vendors per program.
United States
Boeing and Airbus tier-1 suppliers source IMO Fiber derivatives for maritime-adjacent applications requiring dual FAA-IMO certification. FAA and USCG maintain parallel approval pathways for cabin interior panels and structural fire protection. Gulf Coast shipyards in Louisiana and Texas face extended lead times due to dependence on Asian fermentation clusters.
China
State-owned shipbuilders at Dalian and Shanghai accelerate IMO Fiber qualification for domestic LNG carrier programs and Belt-and-Road export vessels. NMPA and CCS classification society coordinate revised FTP Code implementation timelines. Yangtze River Delta compounders develop captive fermentation capacity to reduce import dependence from South Korean suppliers.
IMO Fiber Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with agricultural conglomerates leveraging origination networks against focused fermentation houses. The upstream tier controls corn and pea-protein feedstock streams, while downstream compounders battle for MED certification slots. Two strategic archetypes dominate: integrated agribusinesses with captive polymer supply and specialist biotech firms with precision enzymatic platforms. Competitive moves center on backward integration into fermentation capacity and geographic expansion of certification holdings across Lloyd's Register, DNV, and ClassNK registries.
Among the integrated leaders, Tate & Lyle PLC and Cargill exemplify the agribusiness archetype through their control of North American grain origination and wet-milling infrastructure. Roquette Frères anchors the European specialist tier with pea-protein adjacent fermentation operations. These three occupy positions that reflect divergent capital intensity strategies: captive agricultural supply versus targeted bioprocessing scale.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Ingredion Incorporated |
| Roquette Frères |
| Cargill |
| ADM |
| Shandong Bailong Group Co., Ltd. |
| BioNeutra Global Corporation |
| Baolingbao Biology Co., Ltd. |
| Fonterra Co-operative Group Limited |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between South Korean shipyards and Nagasaki-based compounders lock in multi-year fiber supply while anchoring price visibility against corn wet-milling feedstock volatility. These arrangements bundle MED certification maintenance with volume commitments, insulating procurement teams from spot-market swings in isomaltooligosaccharide derivatives.
Pricing Analysis
Contract-based long-term offtake dominates procurement for LNG carrier newbuilds, with price differentiation driven by certification tier and volume scale. Lloyd's Register and ClassNK dual-certified prepregs command premium positioning over single-registry alternatives. Cost compression in natural fiber variants is intensifying because flax and hemp suppliers compete for limited EU Green Deal retrofit slots. Tier-1 compounders exhibit lowest price sensitivity due to pass-through mechanisms in shipyard contracts, while maintenance distributors face acute margin pressure from inventory carrying costs.
Supply Chain Analysis
Inventory lead times for MED-certified prepregs now stretch eighteen to twenty-four months, forcing European compounders to pre-position stock ahead of contract finalization. Supply concentrates in South Korea, Japan, and coastal China, with fermentation capacity clustering around Busan, Nagasaki, and the Yangtze River Delta. Raw material flows draw from North American corn wet-milling, European pea-protein adjacent fermentation, and Asian cassava starch streams. Single-source vulnerability around the Busan-Ulsan corridor presents acute structural risk for NATO naval programs seeking qualified alternative suppliers. Distribution runs through tier-1 compounders holding multi-registry certification, with regional distributors serving retrofit and MRO segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IMO Fiber market sits at a platform-economics inflection where MED certification registries function as interoperability gatekeepers, determining which compounders can serve multi-registry fleets without redundant qualification cycles.
For Market Incumbents: Consolidate backward integration into captive fermentation capacity to defend margin position against agricultural commodity swings. Lock in multi-registry certification holdings across Lloyd's Register, DNV, and ClassNK before the pending FTP Code revision accelerates competitor qualification timelines. Prioritize channel control through direct long-term offtake relationships with Hyundai Heavy Industries and Mitsubishi Shipbuilding procurement desks. For New Entrants and Emerging Players: Differentiate on enzymatic polymerization precision targeting degree-of-polymerization ranges between three and ten units, where batch consistency gaps persist among established suppliers. Target the underpenetrated NATO naval segment in Italy and Spain, where legacy aramid specifications remain vulnerable to carbon-IMO fiber hybrid conversion. Pursue a qualification-first go-to-market angle, front-loading MED certification investment to bypass the eighteen-to-twenty-four-month validation barrier that filters out Asian competitors. For Investors and Strategic Acquirers: Specialist biotech firms with precision enzymatic platforms and existing Lloyd's Register certification represent the most defensible acquisition archetype, offering technology differentiation without the capital intensity of integrated agribusinesses. Long-term viability hinges on regulatory tailwinds from IMO FTP Code revisions tightening smoke-density thresholds. Watch for harmonization announcements between classification societies as the inflection signal indicating accelerated material upgrade cycles across cruise and passenger vessel segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive isomaltooligosaccharide supply insulates Tate & Lyle and Roquette from corn price volatility. |
| Multi-Registry Certification Investment | Dual Lloyd's Register and ClassNK approval unlocks Hyundai Heavy Industries and Mitsubishi Shipbuilding contracts. |
| Enzymatic Polymerization Scale-Up | Precision degree-of-polymerization targeting improves batch consistency for fire-resistant formulations. |
| Natural Fiber Hybrid Development | Flax-IMO fiber laminates satisfy EU Green Deal bio-content mandates for Baltic ferry retrofits. |
| Naval Segment Qualification Push | Carbon-IMO fiber hybrid conversion targets NATO surface combatant programs in Italy and Spain. |
Research Methodology
A standing panel of shipyard procurement directors, compounder formulation chemists, classification society surveyors, and marine regulatory affairs specialists provided ongoing calibration across the study period. Primary interviews with these stakeholders were cross-validated against secondary sources including Lloyd's Register certification databases, DNV type approval registries, EU Green Deal procurement guideline releases, and customs trade data tracking isomaltooligosaccharide derivative flows. Bottom-up volume modeling from individual shipyard contract specifications was triangulated against top-down market sizing derived from fermentation capacity announcements.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including fiber chemistry, processing form, end-use certification requirements, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to newbuild order backlogs and retrofit cycle timing. Industry-specific forecast inputs incorporated LNG carrier construction rates at South Korean yards and EU Green Deal compliance deadlines for Baltic ferry operators.
The analysis sits within stated boundaries; outcomes outside sustained shipyard order intake or delayed FTP Code implementation would require recalibration. Forecasts reflect documented assumptions regarding certification timeline compression and raw material feedstock availability. Specific risk factors including agricultural commodity price spikes, single-source fermentation capacity disruption, or divergent classification society testing protocols could materially revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Middle-East and Africa Aramid Fiber Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
Polybenzoxazole Fibers Market
Synthetic Fibers
Synthetic Textile Fiber Market
Synthetic Fibers
Nylon Tire Cord Fabrics Market
Synthetic Fibers
Microfiber Leather Market
Synthetic Fibers
Glass Fiber Yarn Market
Synthetic Fibers
Polyester Fibers Market
Synthetic Fibers
Polymer Nanofiber Market
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
Global Synthetic Spider Silk Market
Synthetic Fibers
Latin America Textile Market
Synthetic Fibers
Parachute Fabric Market
Synthetic Fibers
Modacrylic Fiber Market
Synthetic Fibers
Polyester Tire Cord Fabrics Market